
 Japan Microprocessor (MPU) Market | 2026-2036
Japan Microprocessor (MPU) Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Microprocessor (MPU) Market Insights
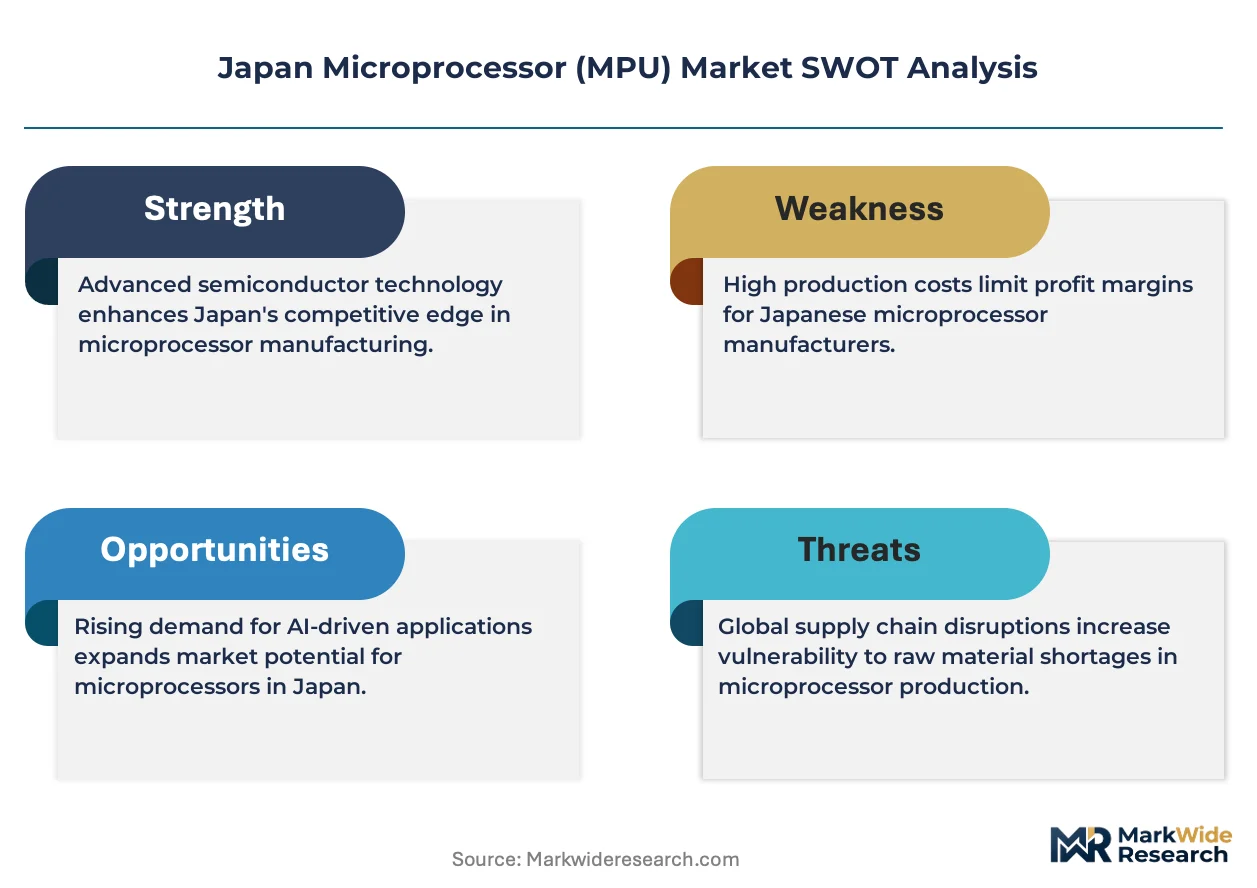
Japan's pool of veteran analog chip designers is collapsing faster than universities replenish semiconductor engineering graduates. Renesas Electronics Corp. sustains its automotive MPU dominance through captive fabs in Naka and Kofu. Toshiba Corporation anchors industrial automation demand with legacy 32-bit architectures still embedded across Nagoya's machine-tool sector. Intel Corporation competes primarily through advanced packaging partnerships rather than greenfield fabrication investment.
A microprocessor unit executes digital instructions via integrated arithmetic logic and control circuitry, typically fabricated on silicon wafers using sub-7nm or mature-node processes depending on thermal and power constraints. Its core purpose spans real-time control in embedded systems to general-purpose computation in consumer devices. Embedded MPUs command the deepest margin pools as automotive OEMs qualify suppliers across decade-long product lifecycles. RISC architectures gain traction in IoT edge devices where Renesas and Rohm Co., Ltd. specialize in ultra-low-power implementations. 64-bit general-purpose processors remain concentrated in gaming console and smartphone applications, though domestic demand for these categories has plateaued relative to embedded alternatives.
METI administers semiconductor subsidies tied to Economic Security Promotion Act benchmarks, while JIS standards govern electromagnetic compatibility and reliability testing for industrial MPUs. PMDA oversight intersects where medical device processors require fail-safe certification, adding compliance layers beyond standard consumer electronics. Stakeholders must weigh reshoring incentives against the capital intensity of domestic leading-edge fabrication, as subsidy duration and local content thresholds remain unresolved variables in long-term capacity planning.
Market Dynamics
Semiconductor fabrication engineers are migrating toward AI accelerator design roles, redirecting scarce talent from legacy MPU development and compressing domestic capacity for mature-node embedded processors.
Growth Catalysts
- Economic Security Promotion Act subsidies:METI's reshoring incentives are reshaping domestic wafer capacity planning and attracting capital into Naka and Kofu fab clusters.
- Automotive ECU demand:Embedded processors for vehicle control units in the Kansai industrial corridor now absorb the bulk of foundry allocation discussions.
- RISC architecture proliferation:Ultra-low-power implementations are gaining traction in IoT edge devices where thermal constraints dominate design specifications.
Market Restraints
- Analog designer attrition:Japan's pool of veteran analog chip designers is collapsing faster than universities replenish semiconductor engineering graduates.
- Leading-edge capex burden:The capital intensity of domestic sub-7nm fabrication strains balance sheets against unresolved subsidy duration timelines.
- Smartphone demand plateau:64-bit general-purpose processor consumption has flattened relative to embedded alternatives in automotive and industrial segments.
Strategic Opportunities
- Medical device certification:PMDA oversight for fail-safe processors adds compliance layers that create margin pools beyond standard consumer electronics.
- Industrial automation retrofit:Legacy 32-bit architectures across Nagoya's machine-tool sector present upgrade cycles for qualified domestic suppliers.
- Advanced packaging partnerships:Foreign competitors are entering through packaging collaborations rather than greenfield fabrication, opening technology transfer channels.
Industry Challenges
- Qualification timeline compression:Automotive OEMs demand decade-long product lifecycle commitments that strain R&D resource allocation.
- Cross-functional talent scarcity:AI accelerator design roles are poaching embedded systems engineers with hybrid digital-analog skill sets.
- JIS compliance integration:Electromagnetic compatibility and reliability testing standards create friction between industrial and medical certification pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Microprocessor (MPU) Market |
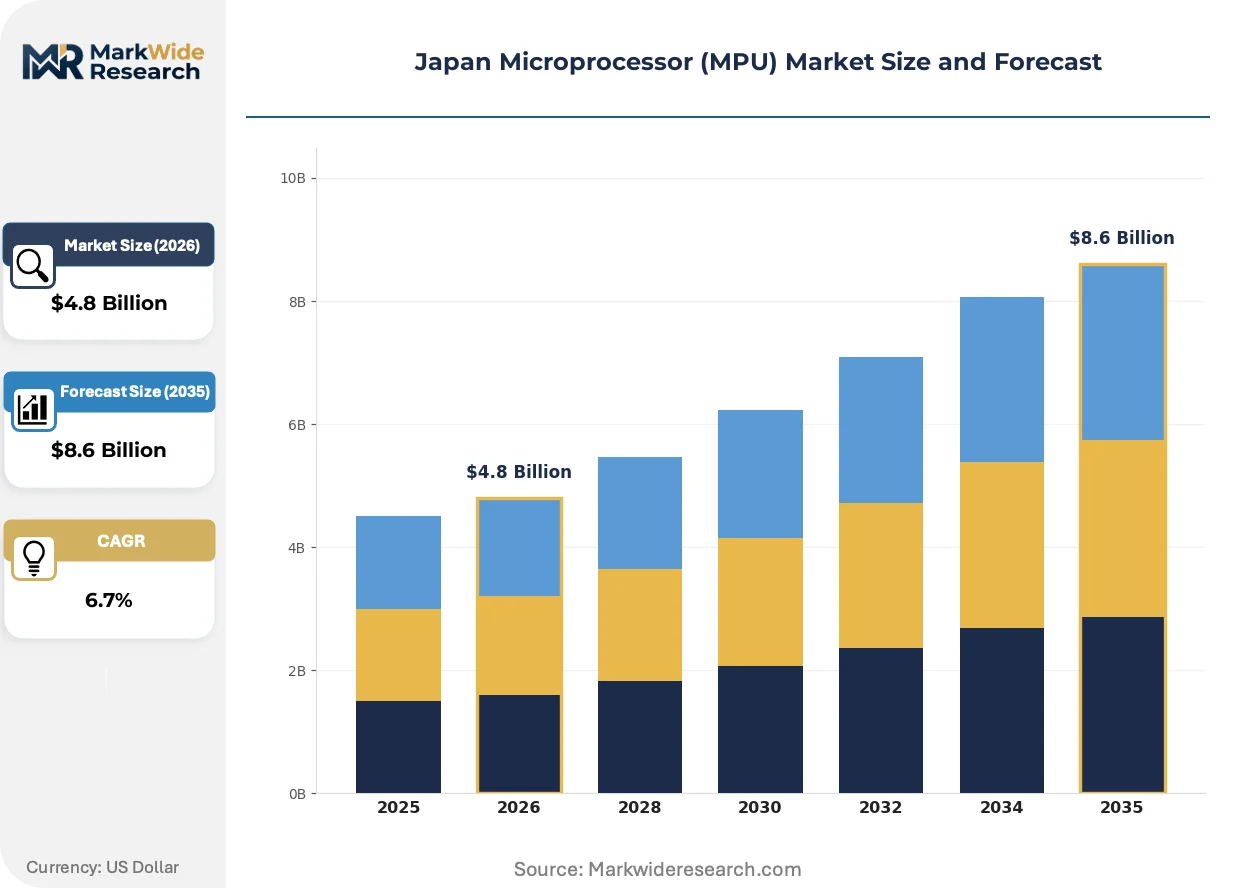
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
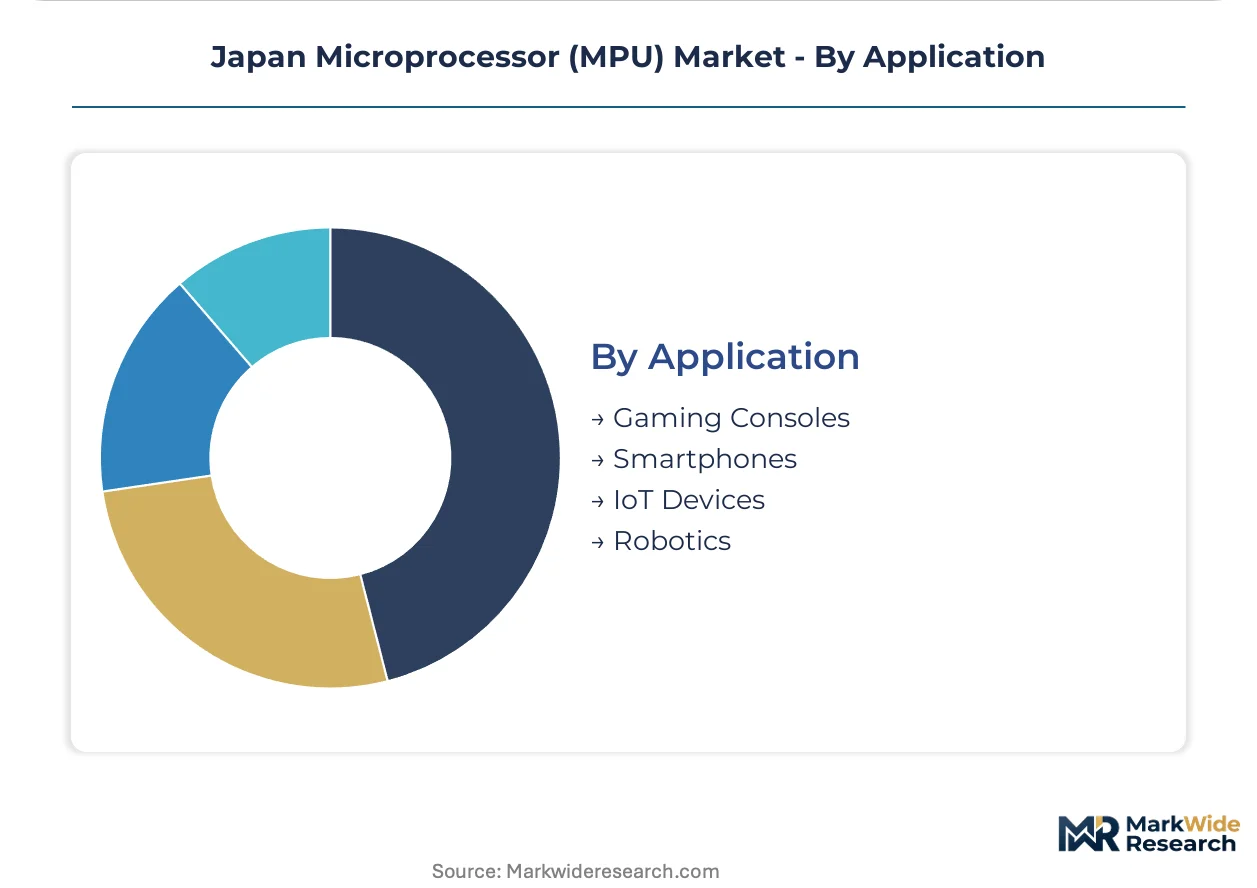
| Segmentation | Product Type: General Purpose, Embedded, Digital Signal, Microcontroller Technology: 32-Bit, 64-Bit, RISC, CISC End User: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Application: Gaming Consoles, Smartphones, IoT Devices, Robotics |
| Companies Covered | Intel Corporation, Renesas Electronics Corp., TSMC, Qualcomm Technologies, Samsung Electronics Co. Ltd., Nuvoton Technology Corporation, Sony Semiconductor Solutions Corp., Toshiba Corporation, Rohm Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Microprocessor (MPU) Market Trends and Innovations
Design methodologies and procurement patterns are diverging across the automotive, industrial, and medical verticals, creating distinct technology roadmaps rather than consolidated platform strategies.
Chiplets are fragmenting the traditional monolithic MPU architecture. These modular silicon tiles enable heterogeneous integration of logic, memory, and analog functions on interposer substrates. Automotive Tier 1 suppliers in the Kansai corridor are adopting chiplet-based designs for advanced driver-assistance systems. This approach is fragmenting the supplier base as packaging houses gain leverage over pure-play foundries in system-level integration.
METI's semiconductor subsidies under the Economic Security Promotion Act are tightening local content thresholds for subsidy eligibility. Domestic wafer capacity planning now prioritizes mature-node processes over leading-edge migration. Industrial MPU suppliers in the Nagoya machine-tool cluster are restructuring supply contracts to meet emerging domestic sourcing benchmarks.
Automotive OEMs are unbundling processor procurement from legacy tiered supplier hierarchies. Direct engagement with MPU designers is replacing module-level purchasing through consolidated electronics suppliers. This pattern is most visible among Kansai-based vehicle manufacturers qualifying embedded processors across extended product lifecycles.
Japan Microprocessor (MPU) Market Segmentation
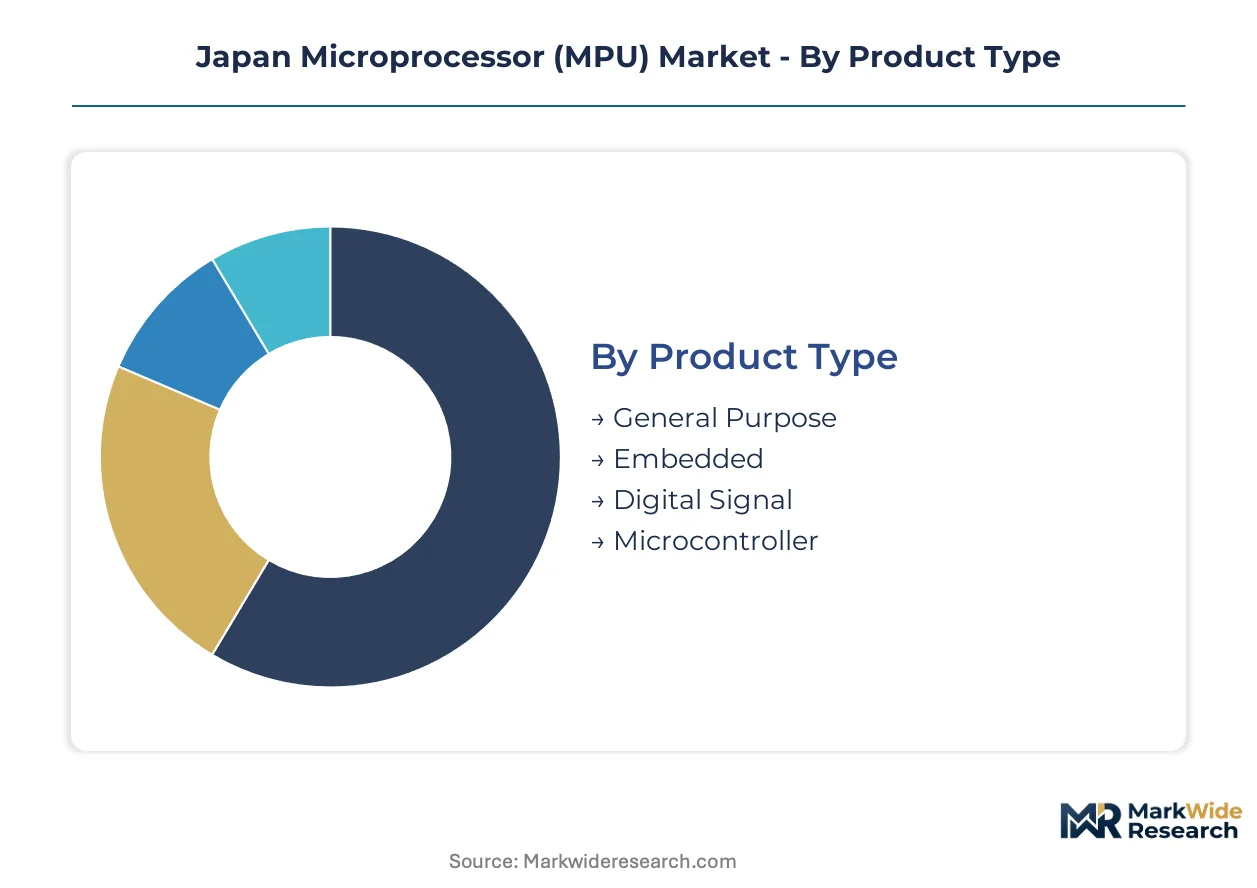
Japan's MPU market fragments across four distinct axes that determine procurement channels and margin structures. Product type and end-user segmentation drive the deepest channel bifurcation, with automotive and industrial buyers qualifying suppliers across decade-long cycles while consumer electronics channels favor rapid product turnover.
Product Type:
Channel distribution varies sharply across product categories, with embedded processors flowing through consolidated Tier 1 automotive suppliers while general-purpose units reach OEMs via broad-line distributors.
- Embedded:These application-specific processors integrate memory and peripherals onto single die for deterministic real-time control. Kansai-based automotive ECU manufacturers now absorb the bulk of foundry allocation discussions for this category, driven by ADAS proliferation and powertrain electrification mandates.
- General Purpose:Flexible instruction-set architectures execute diverse software workloads across operating systems. Demand concentrates in Tokyo-Osaka corridor gaming console assembly, though smartphone consumption has plateaued relative to embedded alternatives.
- Digital Signal:Dedicated multiply-accumulate units accelerate audio and sensor data processing with deterministic latency. Renesas and Rohm dominate medical imaging and telecommunications infrastructure deployments.
- Microcontroller:Self-contained systems-on-chip with minimal external component requirements. Nagoya's machine-tool sector sustains legacy 8-bit and 16-bit architectures through retrofit cycles.
Embedded dominates installed base. General Purpose is where expansion concentrates.
Technology:
Cost tiers stratify sharply by bit-width and instruction-set complexity, with 64-bit RISC commanding premium pricing in data-intensive applications while mature-node 32-bit solutions anchor industrial automation.
- RISC:Reduced instruction-set architectures optimize power efficiency through simplified decode logic and aggressive clock gating. Ultra-low-power implementations from Renesas and Rohm are gaining traction in Kansai IoT edge deployments where thermal constraints dominate design specifications.
- 64-Bit:Extended address spaces and vector registers enable high-throughput multimedia and AI inference workloads. Gaming console and smartphone applications in the Tokyo metropolitan area remain the primary demand centers, though growth has flattened.
- 32-Bit:Balanced performance-per-watt profiles suit real-time control with moderate computational demands. Toshiba's legacy architectures still permeate Nagoya's machine-tool sector through decade-long qualification cycles.
- CISC:Complex instruction-set architectures minimize code size through variable-length opcodes and specialized addressing modes. Industrial automation retrofits sustain demand despite RISC encroachment.
32-Bit anchors volume production. RISC is climbing the fastest.
End User:
Customer type determines procurement modality, with automotive and industrial buyers demanding direct MPU designer engagement while consumer electronics flows through module-level purchasing.
- Automotive:Fail-safe processor requirements span powertrain control, chassis management, and infotainment systems. Kansai-based vehicle manufacturers are unbundling procurement from legacy tiered supplier hierarchies, creating direct qualification pathways for embedded MPU designers.
- Industrial Automation:Ruggedized processors withstand extended temperature ranges and electromagnetic interference in factory-floor deployments. Nagoya's machine-tool cluster sustains demand for legacy 32-bit architectures through structured upgrade cycles.
- Consumer Electronics:Cost-optimized processors prioritize die yield and packaging efficiency over extended temperature specifications. Gaming console assembly in the Tokyo-Osaka corridor represents the residual demand center for 64-bit general-purpose units.
- Telecommunications:High-throughput baseband processing requires deterministic latency and hardware-accelerated cryptography. 5G infrastructure buildouts sustain niche demand for digital signal variants.
Industrial Automation dominates domestic wafer allocation. Automotive is where margin expansion concentrates.
Application:
Volume concentration and supply maturity diverge across application segments, with established gaming and smartphone categories yielding to robotics and IoT as expansion vectors.
- Robotics:Multi-axis motor control and sensor fusion demand real-time deterministic processing with functional safety certification. Kansai automotive suppliers are repurposing chiplet-based ADAS architectures for industrial robot controllers.
- IoT Devices:Battery-constrained endpoints require sub-milliwatt standby power and rapid wake-from-sleep transitions. Renesas and Rohm ultra-low-power RISC implementations are gaining design wins in smart factory sensor networks.
- Gaming Consoles:High-throughput graphics and physics simulation drive 64-bit general-purpose processor specifications. Tokyo-based system integrators sustain demand despite plateauing domestic consumption.
- Smartphones:Integrated application processors with cellular baseband and AI acceleration dominate BOM cost. Domestic demand has flattened relative to embedded alternatives in automotive and industrial segments.
Gaming Consoles dominates legacy revenue. Robotics is where technology transfer concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's microprocessor consumption diverges sharply from global patterns, with embedded automotive processors commanding far greater share relative to general-purpose computing than in North American or European markets.
Kanto/Tokyo
Tokyo-based gaming console assemblers and telecommunications equipment manufacturers sustain demand for 64-bit general-purpose processors. METI's Economic Security Promotion Act subsidies flow disproportionately to Kanto-based packaging and testing facilities. The Tokyo metropolitan corridor anchors domestic R&D concentration for advanced chiplet integration methodologies.
Kansai/Osaka
Automotive ECU manufacturers in Osaka, Kyoto, and Kobe absorb the majority of domestic foundry allocations for embedded processors. PMDA oversight for medical device processors creates compliance-driven margin pools for fail-safe MPU suppliers. Kansai-based vehicle manufacturers are unbundling procurement from legacy tiered supplier hierarchies to engage directly with embedded processor designers.
Chubu/Nagoya
Industrial automation retrofits across Nagoya's machine-tool sector sustain demand for legacy 32-bit architectures through decade-long qualification cycles. JIS electromagnetic compatibility standards govern procurement specifications for factory-floor deployments. The Chubu industrial corridor concentrates captive fab operations serving automotive and industrial control applications.
Kyushu
Semiconductor packaging houses in Kumamoto and Fukuoka are gaining leverage over pure-play foundries through chiplet-based system integration. Reshoring incentives under METI's subsidy framework are attracting backend capacity investments. Kyushu's packaging clusters are repurposing automotive ADAS architectures for industrial robot controller applications.
Japan Microprocessor (MPU) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive fab operators commanding premium positioning in automotive qualification channels. The market structure concentrates around three strategic archetypes: diversified electronics conglomerates with in-house fabrication, fabless designers partnering with foundries for advanced nodes, and analog specialists dominating ultra-low-power edge implementations. Competitive moves center on advanced packaging collaborations and multi-year automotive qualification commitments that lock in decade-long supply relationships.
Among Japan-based integrated suppliers, Renesas Electronics Corp. and Toshiba Corporation exemplify the captive-fab archetype with domestic manufacturing footprints in Naka and Kofu. Rohm Co., Ltd. occupies a position within the analog-digital hybrid specialist tier. Foreign competitors including Intel Corporation are entering through packaging partnerships rather than greenfield fabrication, creating technology transfer channels without direct foundry competition.
| Leading Market Players |
|---|
| Intel Corporation |
| Renesas Electronics Corp. |
| TSMC |
| Qualcomm Technologies |
| Samsung Electronics Co. Ltd. |
| Nuvoton Technology Corporation |
| Sony Semiconductor Solutions Corp. |
| Toshiba Corporation |
| Rohm Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Naka and Kofu fab clusters operate at scale economies that compress unit costs for automotive-qualified embedded processors while simultaneously elevating price floors for non-captive buyers. METI's Economic Security Promotion Act subsidies are reshaping domestic wafer capacity planning, tightening local content thresholds that fragment procurement strategies across qualified and non-qualified supply tiers.
Pricing Analysis
Long-term offtake contracts dominate automotive MPU procurement, with Kansai-based vehicle manufacturers locking in decade-long supply commitments that insulate embedded processor suppliers from spot-market volatility. Price differentiation separates ASIL-D safety-certified automotive tiers from industrial JIS-compliant alternatives, with certification grade commanding substantial premiums. Pricing pressure stems from analog designer attrition compressing domestic capacity for mature-node production. Consumer electronics channels exhibit highest price sensitivity, while medical device OEMs under PMDA oversight demonstrate lowest sensitivity due to fail-safe certification requirements.
Supply Chain Analysis
Strait of Malacca transit underwrites raw silicon wafer flows from Taiwanese and South Korean foundries into Japanese packaging houses. Advanced photoresists and extreme-ultraviolet lithography equipment draw from Dutch and American suppliers, creating single-source vulnerability for sub-7nm process nodes. Tariff exposure on Chinese-sourced substrate materials amplifies cost volatility for interposer-based chiplet assemblies. Distribution runs through consolidated Tier 1 automotive suppliers for embedded processors, while general-purpose units reach OEMs via broad-line distributors serving the Tokyo-Osaka gaming corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's collapsing pipeline of veteran analog chip designers has outpaced university replenishment, creating structural scarcity in hybrid digital-analog skill sets essential for automotive and medical MPU development. Foundry allocation discussions now center on embedded processors for Kansai automotive ECUs, leaving limited domestic capacity for new entrant qualification.
For Market Incumbents: Secure captive fab utilization through multi-year automotive qualification commitments that lock in Naka and Kofu capacity. Deepen backward integration into substrate materials to mitigate tariff exposure on Chinese-sourced interposers. The threat of AI accelerator design roles poaching embedded systems engineers demands accelerated R&D automation investment. For New Entrants and Emerging Players: Differentiate on PMDA fail-safe certification for medical device processors, where compliance layers create margin pools beyond standard consumer electronics. Target Nagoya's machine-tool sector for legacy 32-bit architecture retrofits, exploiting Toshiba's decade-long product lifecycle transitions. A direct engagement model with industrial automation OEMs bypasses consolidated Tier 1 supplier hierarchies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors analog-digital hybrid specialists with captive mature-node fabrication and established automotive qualification channels. Long-term viability rests on backward integration into substrate and packaging materials rather than leading-edge node migration. The signal to watch is METI subsidy duration resolution, which will determine domestic wafer capacity expansion economics.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Lock-in | Multi-year supply contracts with Kansai OEMs secure Naka fab utilization through decade-long product lifecycles. |
| Medical Device Certification Pathway | PMDA fail-safe processor approval opens margin pools beyond standard JIS-compliant industrial alternatives. |
| Chiplet Packaging Partnership | Kyushu-based advanced packaging collaborations enable heterogeneous integration without greenfield fabrication investment. |
| Analog Designer Talent Acquisition | University pipeline partnerships address collapsing veteran designer pools faster than competitor replenishment efforts. |
| Backward Integration into Substrates | In-house interposer production mitigates tariff exposure on Chinese-sourced materials for automotive ADAS architectures. |
Research Methodology
Desk research of METI subsidy filings, JIS electromagnetic compatibility standards, and PMDA medical device processor certifications preceded structured interviews with automotive Tier 1 supplier procurement leads, semiconductor fabrication engineers, industrial automation plant managers, and medical device regulatory affairs specialists. Secondary validation drew from foundry capacity announcements, captive fab utilization disclosures, and automotive OEM platform engineering roadmaps. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Variance decomposition across product type, technology node, end-user vertical, and application segmented volume and value outputs throughout the forecast period. CAGRs derived from regression analysis of historical foundry allocation trends, automotive ECU content per vehicle trajectories, and industrial automation retrofit cycle timing. Industry-specific inputs included analog designer attrition rates, METI subsidy eligibility thresholds, and PMDA certification timeline distributions.
Forecasts assume regulatory continuity in METI's Economic Security Promotion Act subsidy regimes and JIS electromagnetic compatibility standards; material policy shifts would require re-modeling domestic wafer capacity planning assumptions. Practitioners should keep alternative scenarios live as analog designer replenishment rates and automotive OEM unbundling procurement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Audio Processor Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
DNA Sequencing Chip Market
Chipset and Processors
NB-IoT Chipset Market
Chipset and Processors
Battery Monitoring IC Market
Chipset and Processors
South Korea Data Center Processor Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Global Wireless Chipsets Market
Chipset and Processors
Advanced Audio Processor Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
Processor for Smartphones Market
Chipset and Processors
8-Bit MCU Market