
 Digital Audio Processor Market | 2026-2036
Digital Audio Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Audio Processor Market Analytics
Market Dynamics
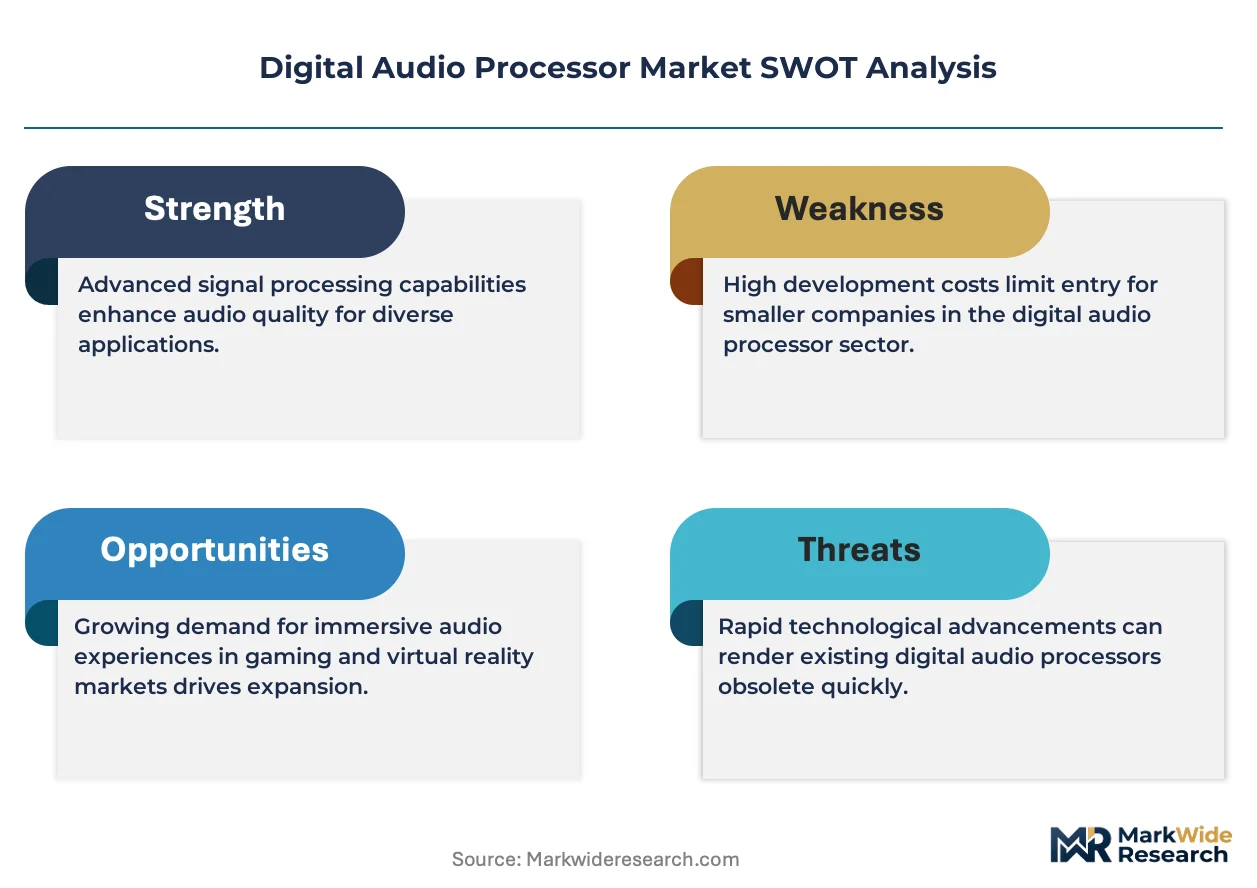
Software-defined audio feature licensing is hardening as the primary revenue layer beyond hardware shipment, with manufacturers now bundling DSP algorithm subscriptions and cloud-based preset libraries into annual contracts. Qualcomm Technologies leverages its Snapdragon audio platform to anchor premium mobile and automotive processor sockets. Texas Instruments sustains dominance in professional studio converters through high-channel-count Burr-Brown architectures. Analog Devices specializes in precision sigma-delta modulators that command margin pools in broadcast and measurement segments.
Technical Definition and Segment Structure
A digital audio processor is a semiconductor or embedded system that performs real-time mathematical operations on digitized sound waveforms, typically handling sample rates from 44.1 kHz to 192 kHz with 24-bit or 32-bit floating-point resolution, to enable filtering, mixing, effects generation, and format conversion across professional and consumer applications. Multi-channel processors lead volume shipment due to immersive audio proliferation in cinema and gaming, while DSP-based architectures capture the fastest expansion as adaptive noise cancellation and spatial audio rendering migrate from flagship to mid-tier devices. Equalizers and effects processors occupy mature margin pools in live sound reinforcement, where analog-hybrid designs persist despite digital encroachment.
Regulatory Environment and Outlook
FCC Part 15 equipment authorization governs electromagnetic emissions for processors embedded in wireless audio products, while EU REACH and RoHS constraints restrict hazardous substances in semiconductor packaging and solder alloys. Japan's METI enforces energy efficiency standards that shape thermal design requirements for rack-mounted broadcast processors. Stakeholders must monitor whether emerging AI-generated audio disclosure mandates in the European Union and United States alter firmware certification burdens for real-time voice-processing chipsets.
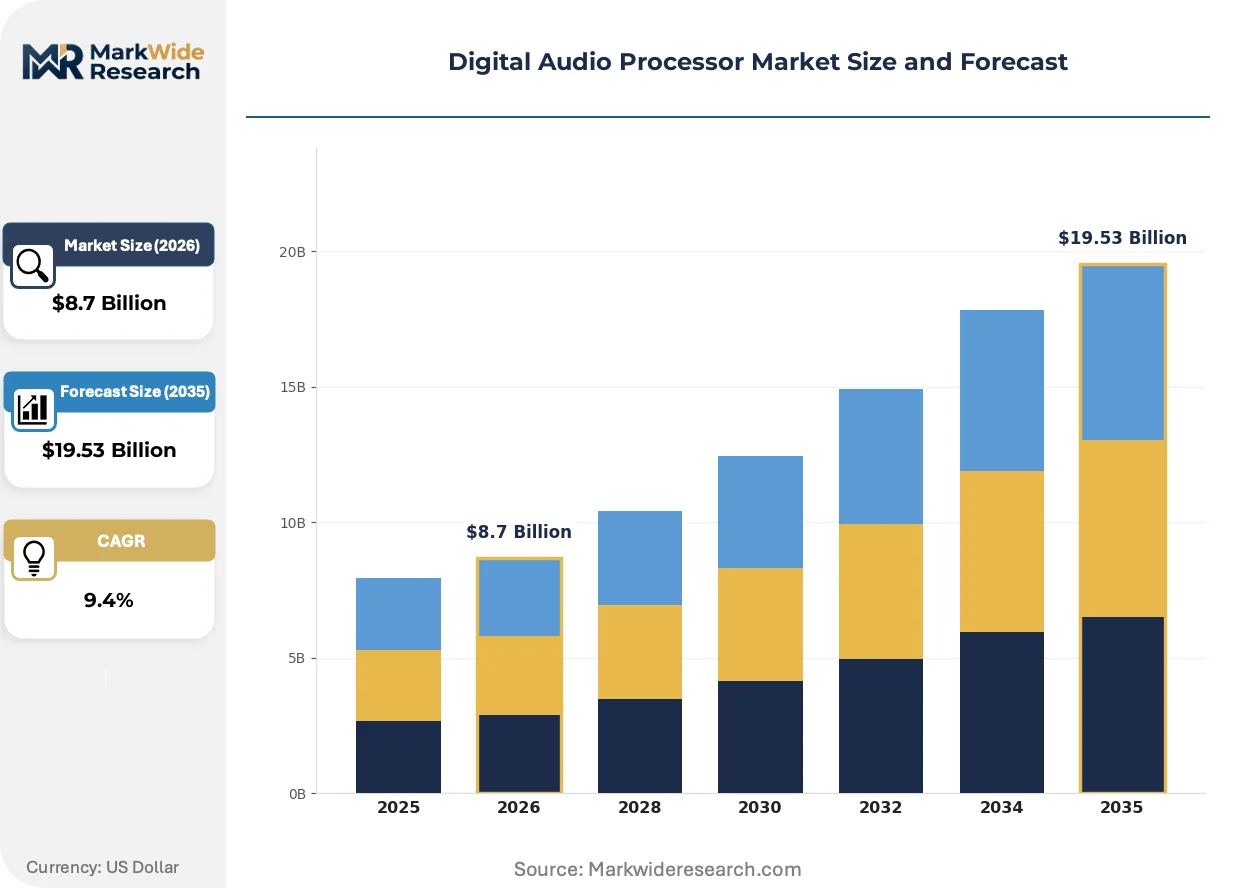
Market Dynamics
Software-defined audio architectures are compressing hardware margins while elevating algorithm licensing to the primary profit layer, forcing manufacturers to restructure revenue models around recurring DSP subscriptions rather than one-time chipset sales.
Growth Catalysts
- Immersive Audio Mandates:Cinema and gaming studios in the United States, Germany, and Japan are retrofitting control rooms with multi-channel processors to meet object-based audio standards for theatrical release and AAA title certification.
- EU AI Act Compliance:Voice-processing chipsets embedded in consumer electronics now require algorithmic transparency documentation, creating certified product tiers that command premium positioning in European distribution channels.
- Automotive Cabin Acoustics:Road noise cancellation and spatial audio rendering are migrating from luxury to mass-market vehicle segments, pulling DSP-based systems into head unit and amplifier integration programs.
Market Restraints
- Silicon Supply Concentration:Advanced node fabrication for high-channel-count studio converters remains concentrated among Taiwanese foundries, exposing professional audio OEMs to geopolitical disruption risk and allocation constraints.
- Legacy Interface Persistence:Analog XLR and AES/EBU connectivity standards dominate live sound reinforcement, slowing digital-native processor penetration in touring and installed venue applications where retrofit costs outweigh performance gains.
- FCC Equipment Authorization Burden:Wireless-enabled processors face extended electromagnetic compliance timelines, delaying product launches by six to nine months and compressing effective sales windows for seasonal consumer electronics cycles.
Strategic Opportunities
- India Professional Infrastructure:Post-production studios in Mumbai and Chennai are expanding dubbing and mixing capacity for streaming content localization, creating demand for mid-tier DSP systems with regional language preset libraries.
- Cloud-Native Preset Distribution:Subscription-based algorithm marketplaces allow manufacturers to monetize impulse response libraries and spatial audio templates outside hardware refresh cycles, capturing recurring revenue from installed base expansion.
- Broadcast Measurement Convergence:Precision sigma-delta architectures are penetrating non-destructive testing and medical imaging adjacent markets where audio-grade signal integrity translates to instrumentation accuracy requirements.
Industry Challenges
- Firmware Certification Complexity:Real-time voice biometrics and AI-generated audio detection features require multi-jurisdictional algorithmic audit trails, extending engineering validation cycles and inflating compliance headcount.
- Legacy System Integration:Broadcast facilities in Japan and Germany maintain decades-old MADI and Dante network infrastructures, forcing processor vendors to support redundant protocol stacks that fragment R&D resources across incompatible standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Audio Processor Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Channel Processors, Equalizers, Mixers, Effects Processors End User: Studios, Live Sound, Broadcasting, Gaming Technology: Analog, Digital, Hybrid, DSP Application: Music Production, Film Scoring, Podcasting, Sound Design |
| Companies Covered | Qualcomm Technologies, Texas Instruments, Analog Devices, NXP Semiconductors, Cirrus Logic, Microchip Technology, STMicroelectronics, Infineon Technologies, Marvell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Audio Processor Market Evolving Landscape
Edge-computing audio architectures are redistributing processing load from centralized servers to endpoint devices, enabling sub-10 millisecond latency for real-time applications while complicating thermal management in compact form factors.
Neural network inference engines are consolidating adaptive noise cancellation, voice activity detection, and spatial audio rendering onto single-chip DSP platforms. Automotive tier-one suppliers are adopting these integrated solutions for cabin comfort systems, collapsing what previously required discrete signal chain components into unified silicon footprints that reduce bill-of-materials complexity and assembly labor.
Japan's METI energy efficiency standards are tightening standby power limits for rack-mounted broadcast equipment, compelling processor designers to implement aggressive power gating and variable clock domains. Manufacturers serving NHK and commercial broadcasters are responding with firmware-managed sleep states that sacrifice instant-on responsiveness for compliance certification, creating product segmentation between broadcast-grade and studio-grade thermal envelopes.
Buyer procurement patterns in professional audio are compressing evaluation cycles from twelve months to ninety days as streaming production schedules accelerate equipment refresh decisions. Rental and staging companies in the United States are displacing capital purchase models with operational lease structures that bundle firmware updates and hardware replacement, shifting margin capture from upfront sale to service attachment rates and residual value management.
Digital Audio Processor Market Segmentation
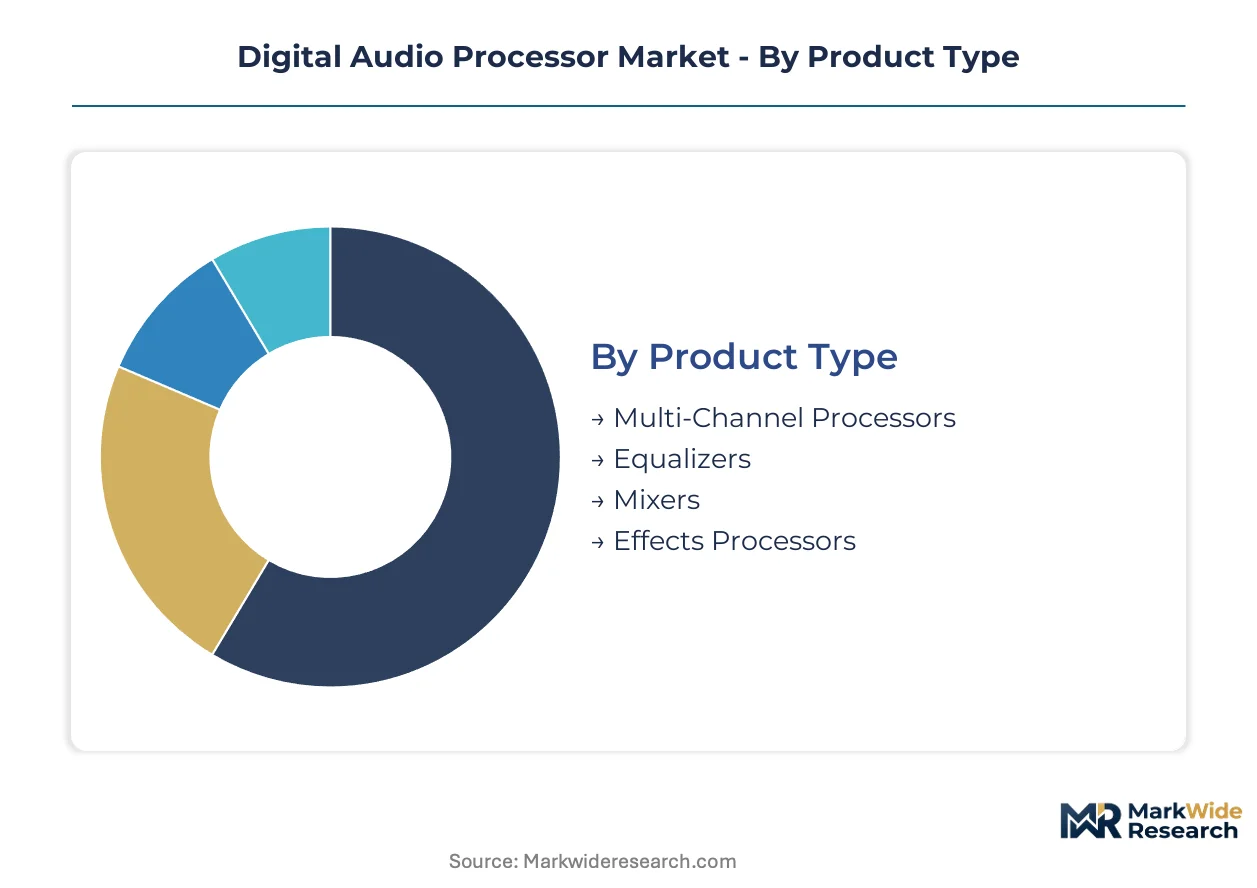
Architectural differentiation in digital audio processors determines which certification pathways manufacturers must navigate, from FCC Part 15 for wireless-enabled units to EU AI Act documentation for voice-processing chipsets. Segmentation clarity helps procurement teams match technical specifications against regulatory burdens and end-use performance requirements.
Product Type:
FCC Part 15 electromagnetic authorization applies universally across wireless-enabled processors, while EU REACH substance restrictions target solder alloys and semiconductor packaging most heavily in rack-mounted multi-channel units destined for European theatrical installations.
- Multi-Channel Processors:These units handle 16 to 64 simultaneous audio channels with 24-bit resolution at 96 kHz sample rates, enabling object-based immersive audio rendering. Demand concentrates in United States cinema retrofit projects and German post-production facilities where theatrical release certification mandates Dolby Atmos compliance.
- Equalizers:Parametric and graphic variants provide precision frequency manipulation across 20 Hz to 20 kHz ranges with 0.1 dB resolution. Live sound venues in Japan favor analog-hybrid designs for touring reliability, slowing full-digital adoption despite superior recall capabilities.
- Mixers:Digital mixing surfaces integrate DSP engines for routing, effects, and automation in broadcast and studio environments.
- Effects Processors:Reverb, delay, and modulation units serve live sound reinforcement and studio production with algorithmic or convolution-based architectures.
Multi-Channel Processors sits at the top of the volume ranking, with DSP-based architectures climbing the fastest across premium mobile and automotive integration programs.
End User:
Customer procurement patterns diverge sharply across these segments, with studios demanding extended evaluation cycles for converter fidelity verification while live sound operators prioritize rental fleet standardization and rapid technical support response.
- Studios:Recording and mixing facilities require transparent signal paths with sub-0.001% total harmonic distortion for critical listening environments. United States music production hubs in Los Angeles and Nashville drive high-channel-count converter demand for orchestral tracking sessions.
- Live Sound:Touring companies and installed venues prioritize ruggedized chassis designs and redundant power supplies for mission-critical performance reliability. German festival infrastructure and Japanese concert hall installations sustain demand for weather-resistant stagebox processors.
- Broadcasting:Radio and television facilities demand 24/7 operational stability with remote monitoring capabilities for transmitter site equipment.
- Gaming:AAA development studios and esports venues require spatial audio rendering with head-related transfer function personalization for competitive advantage.
Studios capture the highest average selling prices per channel, though Gaming installations are expanding most quickly as immersive audio becomes standard for competitive title certification.
Technology:
Silicon architecture choices determine thermal envelopes, power consumption profiles, and algorithmic flexibility boundaries that shape integration possibilities across mobile, automotive, and rack-mounted deployment scenarios.
- Analog:Discrete transistor and integrated circuit designs persist in boutique recording preamplifiers and high-end equalizers where harmonic saturation characteristics define sonic identity. Japanese boutique manufacturers in Tokyo and Osaka maintain specialized production for discriminating studio clients.
- Digital:FPGA and ASIC implementations provide deterministic latency for broadcast synchronization and live sound matrix routing. German broadcast infrastructure projects specify these architectures for ST 2110 compliance in IP-based facility upgrades.
- Hybrid:Analog front-end stages with digital control and recall merge sonic character with operational convenience for touring applications.
- DSP:Programmable digital signal processors enable firmware-upgradable algorithms for noise cancellation, spatial audio, and voice processing across consumer and professional tiers.
DSP commands the steepest expansion trajectory as adaptive algorithms migrate from flagship to mid-tier device segments, while Analog retains defensible niche positions in saturation-critical recording chains.
Application:
Content format requirements and delivery platform specifications create divergent technical demands across these use cases, from theatrical dynamic range standards to podcast loudness normalization mandates.
- Music Production:Recording, mixing, and mastering workflows demand transparent monitoring chains with extended frequency response to 40 kHz for high-resolution release formats. United States independent producers in Austin and Atlanta increasingly adopt mid-tier DSP systems for remote collaboration workflows.
- Film Scoring:Orchestral recording and dubbing stage mixing require 64+ channel counts with sample-accurate synchronization to picture. Mumbai and Chennai post-production expansion for streaming localization drives regional language preset development.
- Podcasting:Voice-optimized processing chains with real-time noise suppression and automatic level control serve creator economy production needs.
- Sound Design:Foley, effects editing, and interactive audio implementation for games and immersive media require spectral manipulation tools and granular synthesis capabilities.
Music Production maintains installed base dominance, with Film Scoring gaining share fastest as theatrical and streaming content budgets converge on immersive audio requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate assembly to jurisdictions with streamlined FCC equipment authorization or lighter AI disclosure burdens, compressing time-to-market for wireless-enabled processors by four to six months versus European compliance pathways.
United States
Los Angeles and Nashville studio clusters drive high-channel-count converter demand for orchestral tracking and immersive mixing workflows. FCC Part 15 electromagnetic authorization governs wireless-enabled processors embedded in mobile and automotive platforms. Austin and Atlanta independent producers increasingly adopt mid-tier DSP systems for remote collaboration, pulling algorithm licensing revenue from hardware-centric models.
Germany
Berlin and Munich post-production facilities retrofit control rooms for Dolby Atmos theatrical certification, sustaining demand for 64-channel processors. EU REACH substance restrictions constrain solder alloy selection in rack-mounted broadcast equipment destined for European theatrical installations. Hamburg broadcast infrastructure projects specify FPGA architectures for ST 2110 IP-based facility compliance.
Japan
Tokyo and Osaka boutique manufacturers maintain specialized analog-hybrid production for discriminating studio clients seeking harmonic saturation characteristics. METI energy efficiency standards tighten standby power limits for rack-mounted broadcast processors, compelling firmware-managed sleep states. Nagoya automotive tier-one suppliers integrate unified DSP platforms for cabin noise cancellation and spatial audio rendering.
India
Mumbai and Chennai post-production studios expand dubbing capacity for streaming content localization, creating demand for mid-tier DSP systems with regional language preset libraries. BIS certification requirements shape import pathways for professional audio equipment. Bangalore and Hyderabad emerging as testbeds for cloud-native algorithm marketplaces serving creator economy producers.
South Korea
Seoul Capital Area semiconductor foundries anchor advanced node fabrication for high-channel-count studio converters, exposing supply chains to geopolitical allocation risk. MFDS regulatory frameworks influence medical imaging adjacent markets where audio-grade sigma-delta architectures penetrate non-destructive testing. Busan-Ulsan industrial zones concentrate contract manufacturing for automotive DSP integration programs.
Digital Audio Processor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with semiconductor incumbents dominating premium mobile sockets while mid-tier professional audio relies on fabless design houses and Taiwanese foundry partnerships. The vendor base concentrates around three strategic archetypes: integrated platform licensors anchoring automotive and mobile supply chains, precision converter specialists serving broadcast and measurement segments, and programmable DSP vendors enabling firmware-upgradable consumer tiers. Competitive moves center on algorithm licensing restructuring and backward integration into captive sigma-delta modulator design.
Among U.S.-based platform licensors, Qualcomm Technologies and Texas Instruments occupy positions exemplifying divergent specialization vectors—one anchoring premium mobile and automotive processor sockets, the other sustaining dominance in professional studio converter architectures through high-channel-count Burr-Brown heritage. Analog Devices represents the precision measurement archetype, with sigma-delta modulator expertise commanding margin pools in broadcast and adjacent instrumentation markets.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| Texas Instruments |
| Analog Devices |
| NXP Semiconductors |
| Cirrus Logic |
| Microchip Technology |
| STMicroelectronics |
| Infineon Technologies |
| Marvell |
| Others |
Value Network & Pricing Analysis
Software-defined audio architectures are collapsing hardware margins while elevating algorithm licensing to the primary profit layer, simultaneously compressing per-unit economics and concentrating margin capture among semiconductor platform licensors with captive DSP IP portfolios. This structural shift forces mid-tier manufacturers to choose between accepting commoditized chipset pricing or investing in proprietary firmware ecosystems that extend engineering cycles and certification burdens.
Pricing Analysis
Distributor margins for professional audio processors range from 15% to 25% for rack-mounted multi-channel units, while direct-to-OEM automotive contracts command steeper volume discounts that sacrifice upfront margin for platform socket security. Three-tier pricing structure across premium, standard, and economy levels separates broadcast-grade sigma-delta architectures from mid-tier DSP systems and consumer-grade CODEC integrations. Cost compression in standard-tier DSP systems is intensifying because algorithm licensing fees now exceed silicon costs in bill-of-materials breakdowns. Live sound rental companies exhibit the highest price sensitivity due to operational lease structures that prioritize total cost of ownership over acquisition price, while cinema post-production facilities remain least sensitive given theatrical certification requirements.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese foundries for advanced node fabrication of high-channel-count studio converters, exposing professional audio OEMs to geopolitical allocation constraints and extended lead time volatility. Supply concentration centers on Taiwan, South Korea, and Japan for precision analog-to-digital components, with Germany anchoring specialized broadcast equipment assembly. Raw material dependencies include high-purity silicon substrates, rare-earth elements for magnetic components in analog stages, and specialized epoxy resins for semiconductor packaging. Tariff exposure runs through cross-border shipments of rack-mounted processors between Asian manufacturing hubs and European theatrical installation sites. Distribution runs through authorized professional audio dealers for studio and broadcast segments, while automotive DSP integration programs bypass intermediaries through direct Tier 1 supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as immersive audio mandates in theatrical release and AAA gaming certification pull procurement toward premium multi-channel processors with transparent converter specifications. Buyers increasingly prioritize algorithm transparency documentation and firmware upgrade pathways over raw channel count metrics.
For Market Incumbents: Hedge against margin erosion in hardware sales by deepening algorithm licensing revenue through cloud-native preset marketplaces that monetize installed base expansion outside refresh cycles. Defensive consolidation should emphasize backward integration into captive sigma-delta modulator design to protect precision converter margin pools from fabless competitors. Priority investment belongs to EU AI Act compliance documentation that creates certified product tiers commanding premium positioning in European distribution channels.
For New Entrants and Emerging Players: Independent podcast producers and creator economy studios represent the most penetrable buyer archetype, as compressed evaluation cycles and remote collaboration workflows displace traditional studio infrastructure requirements. White-space targets include regional language preset libraries for Indian post-production expansion and firmware-upgradable mid-tier DSP systems for Austin and Atlanta independent producers. Go-to-market execution should leverage subscription-based algorithm bundling that mimics incumbent service attachment models without requiring captive silicon fabrication.
For Investors and Strategic Acquirers: Valuations sit cheapest among programmable DSP vendors with automotive cabin acoustics exposure but limited broadcast infrastructure heritage, as market participants misprice the convergence potential between consumer noise cancellation and professional spatial audio rendering. Long-term viability favors precision converter specialists with sigma-delta expertise transferable to adjacent medical imaging and non-destructive testing instrumentation markets. The signal to watch is automotive Tier 1 supplier consolidation around unified DSP platforms that collapse discrete signal chains into single-chip footprints, indicating which algorithm licensors will capture platform socket permanence.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Marketplace Development | Cloud-native preset distribution captures recurring revenue from installed base expansion beyond hardware refresh cycles. |
| EU AI Act Compliance Certification | Algorithmic transparency documentation creates premium product tiers commanding superior positioning in European channels. |
| Automotive Platform Integration | Unified DSP consolidation for cabin acoustics reduces bill-of-materials complexity for Nagoya Tier 1 suppliers. |
| Regional Language Preset Expansion | Mumbai and Chennai dubbing capacity growth drives demand for mid-tier systems with localized template libraries. |
| Sigma-Delta Architecture Adjacency | Precision modulator expertise penetrates medical imaging markets where audio-grade signal integrity meets instrumentation accuracy. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and South Korea, with primary inputs from each market informing regional demand calibration. Primary interviews engaged audio DSP engineering directors, professional audio procurement managers at post-production facilities, automotive Tier 1 supplier platform engineers, broadcast infrastructure project consultants, and semiconductor foundry account managers. Secondary validation drew from FCC equipment authorization databases, EU REACH substance restriction filings, METI energy efficiency compliance records, BIS certification registries, and SEC 10-K disclosures from listed semiconductor vendors. Bottom-up channel checks triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Granularity-level modeling deployed separate forecast frameworks for multi-channel processors, equalizers, mixers, and effects processors, with further disaggregation by DSP, digital, hybrid, and analog technology architectures. Expansion trajectories across the analysis window derived from immersive audio mandate penetration curves, automotive cabin acoustics integration rates, and streaming content production capacity expansion in regional dubbing markets. Industry-specific inputs included theatrical release certification timelines, EU AI Act implementation phases, and METI standby power standard revision schedules.
Underlying measurement precision varies by segment; multi-channel processors and DSP-based architectures carry tighter precision than analog-hybrid equalizers where boutique production obscures volume transparency. Forecasts reflect assumptions regarding regulatory implementation timelines, foundry allocation stability, and automotive platform standardization velocity that could materially shift if geopolitical disruption intensifies or immersive audio mandates accelerate. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Robotic Flat Cable Market
Electronic Components
Audio Transistors Market
Electronic Components
Silicon Capacitors Market
Electronic Components
Ceiling Microphone Market
Electronic Components
High-Voltage Capacitor Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
Ceramic Disc Capacitor Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
RAID Controller Card Market
Electronic Components
Class D Audio Amplifier Market
Electronic Components
AC Adapter Market
Electronic Components
Multi-Layer Ceramic Capacitor (MLCC) Market
Electronic Components
Global Ethernet Controller Market
Electronic Components
China Crystal Oscillator Market
Electronic Components
Bonding Wires and Ribbons Market