
 Biodegradable Bone Graft Polymers Market | 2026-2036
Biodegradable Bone Graft Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Bone Graft Polymers Market Analysis
The pricing gap between premium synthetic scaffolds and commodity natural polymer grafts is recalibrating procurement strategies across hospital systems. Stryker Corporation leverages its orthopedic implant installed base to bundle graft products with hardware platforms. Evonik Industries AG anchors the high-performance synthetic segment through its Resomer portfolio of bioresorbable polymers. Corbion N.V. competes on sustainable sourcing credentials for its polylactic acid-based offerings.
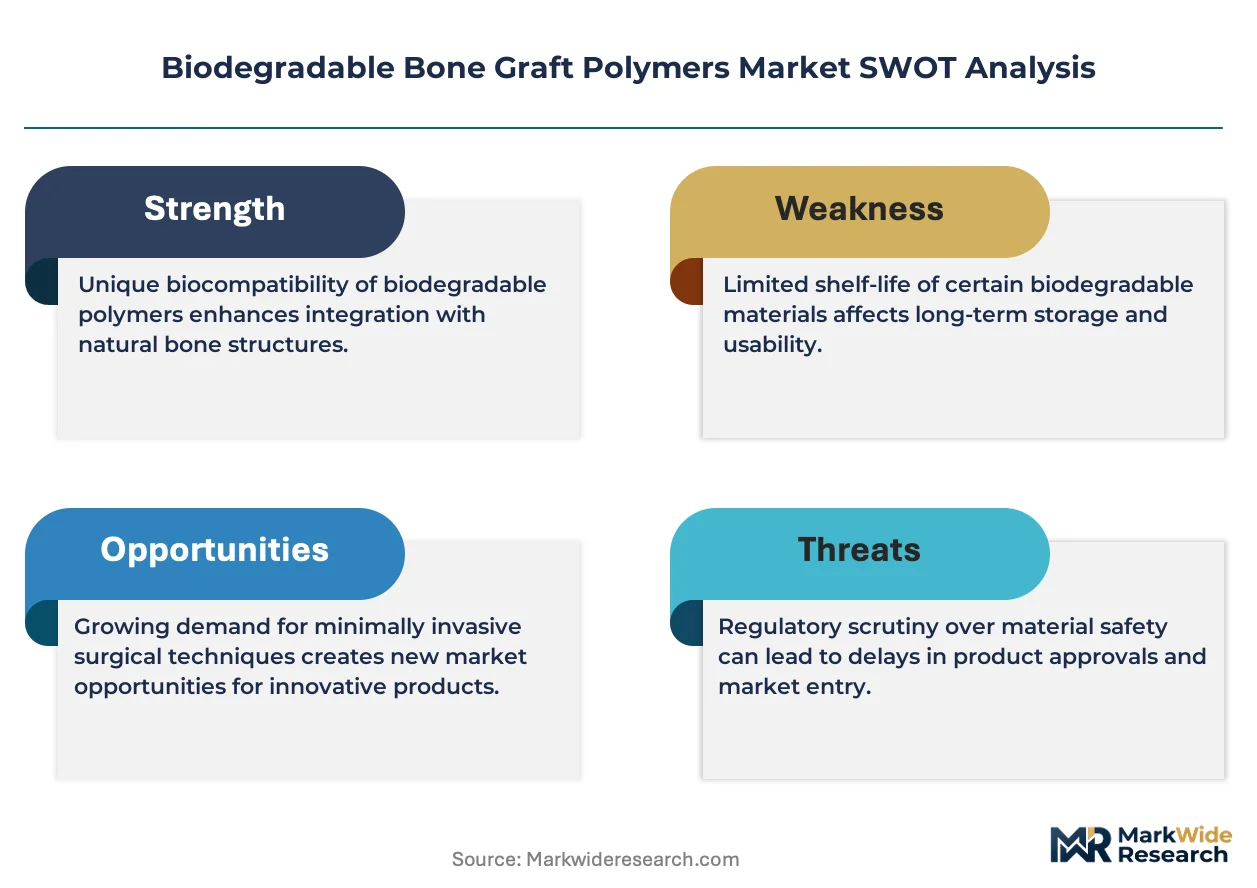
Biodegradable bone graft polymers are absorbable macromolecules—typically polylactic acid, polyglycolic acid, or polycaprolactone—that degrade through hydrolysis into biocompatible byproducts while providing osteoconductive scaffolding for new bone formation. These materials are engineered with controlled degradation rates matching bone remodeling timelines, typically spanning several months to two years depending on molecular weight and copolymer ratios. Synthetic polymers command the highest margins due to batch-to-batch consistency and tunable mechanical properties, while composite materials represent the fastest-expanding category as manufacturers blend ceramics with polymers to improve osteoinductivity. Injectable pastes are gaining share in minimally invasive spinal procedures where open surgery graft placement proves impractical.
The FDA regulates these products as combination devices or biologics depending on structural claims, creating dual pathway complexity for market entry. The EU Medical Device Regulation imposes stricter clinical evidence requirements through notified body oversight, while ISO 10993 biocompatibility testing standards govern cytotoxicity and degradation byproduct safety globally. Stakeholders must monitor how evolving FDA guidance on 3D-printed personalized grafts reshapes regulatory boundaries between standard and custom device classifications.
Market Dynamics
The convergence of 3D printing capabilities with patient-specific anatomical modeling is compressing development cycles and forcing manufacturers to choose between standardized platform economics and personalized graft production at scale.
Growth Catalysts
- FDA combination product pathway clarification:The agency's evolving guidance on scaffolds incorporating biologics accelerates regulatory certainty for hybrid synthetic-natural formulations entering spinal fusion applications.
- Polycaprolactone-ceramic composites:These materials match cortical bone modulus more closely than pure polymers, driving adoption in load-bearing orthopedic trauma repairs where mechanical mismatch causes implant failure.
- Academic medical center concentration:United States teaching hospitals generate clinical evidence that supports premium reimbursement codes, creating pull-through demand into community hospital settings.
Market Restraints
- L-lactide monomer supply concentration:Corbion and NatureWorks control fermentation-derived feedstock capacity, exposing polymer converters to agricultural commodity volatility in corn starch pricing.
- EU MDR clinical evidence requirements:The regulation's expanded notified body oversight for Class III implantable devices extends certification timelines and elevates documentation costs for synthetic scaffold manufacturers.
- Autograft persistence:Harvested iliac crest bone remains the clinical gold standard for spinal fusion, limiting addressable market expansion despite synthetic graft technical improvements.
Strategic Opportunities
- Injectable paste formulations:Minimally invasive kyphoplasty and vertebroplasty procedures create demand for flowable polymers that set in situ, opening ambulatory surgery center channels beyond traditional hospital operating rooms.
- Japan's regenerative medicine framework:PMDA's conditional approval pathways for combination products reduce time-to-market for osteoinductive polymer-ceramic grafts targeting aging demographic spine disorders.
- Bioprinting convergence:Integration of melt electrowriting with live cell deposition enables manufacturing of vascularized grafts that exceed passive osteoconduction, creating premium tier separation from commodity scaffolds.
Industry Challenges
- Polymer degradation characterization:ISO 10993 Part 6 biocompatibility testing requires extended animal study timelines to validate hydrolysis byproduct clearance, compressing R&D productivity metrics.
- Cleanroom capacity constraints:GMP manufacturing of resorbable polymers demands ISO 7-8 environments with controlled humidity to prevent premature hydrolysis, limiting contract manufacturer availability and elevating capital requirements for in-house expansion.
- Surgeon training fragmentation:Technique-specific graft handling protocols vary by polymer chemistry, forcing manufacturers to maintain parallel educational programs without standardized credentialing pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Bone Graft Polymers Market |
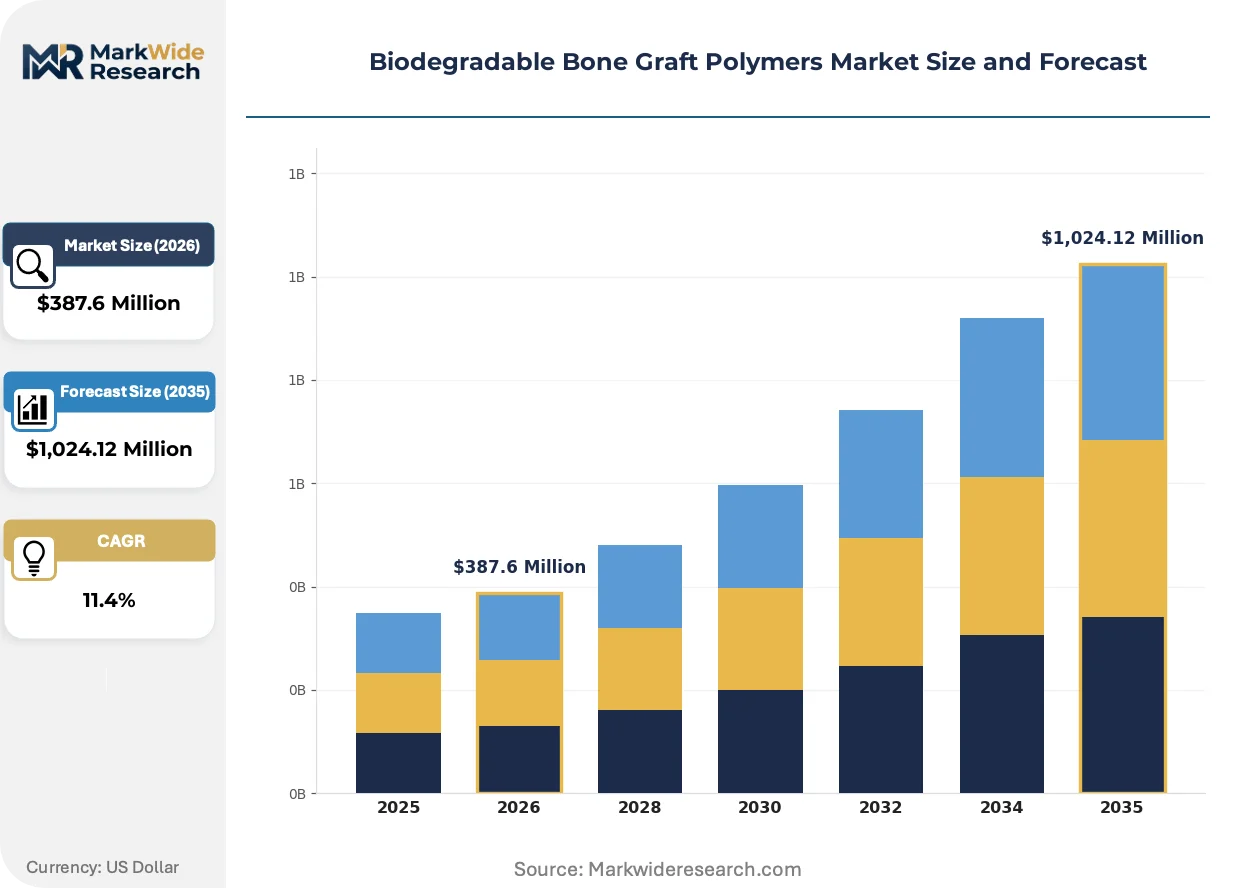
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Polymers, Synthetic Polymers, Composite Materials, Hybrid Solutions Application: Orthopedics, Dental Surgery, Tissue Engineering, Regenerative Medicine End User: Hospitals, Clinics, Research Institutions, Dental Practices Delivery Mode: Injectable Grafts, Pre-formed Scaffolds, Granules, Injectable Pastes |
| Companies Covered | Zimmer Biomet Holdings, Stryker Corporation, Medtronic plc, DePuy Synthes, Smith+Nephew plc, Evonik Industries AG, Corbion N.V., Arthrex, Foster Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Bone Graft Polymers Market Emerging Trajectories
Manufacturing automation and computational modeling are converging to reshape how biodegradable scaffolds transition from batch production to continuous processing at clinical scale.
Electrospun nanofiber architectures are consolidating manufacturing complexity by integrating porosity gradients and mechanical anisotropy into single-process outputs. Orthopedic device divisions within hospital purchasing systems are specifying these structures for anterior cervical discectomy fusion cages. The technology is consolidating what previously required lamination of separate polymer sheets into unified monolithic constructs, compressing unit economics for mid-tier suppliers.
REACH authorization requirements for residual catalysts in medical-grade polymers are tightening supply qualification protocols for European manufacturers. The regulation's Substances of Very High Concern list now captures certain tin-based ring-opening polymerization catalysts used in polylactide production. German notified bodies are demanding migration studies that extend certification timelines by eight to fourteen months for reformulated catalyst systems.
Surgeon preference for pre-shaped anatomical grafts is displacing intraoperative carving of block polymers. Spinal implant distributors report that sterile-packed patient-matched devices reduce operating room time by eliminating contouring steps. This pattern concentrates demand in United States metropolitan markets where integrated delivery networks negotiate bundled procedural payments that reward efficiency gains.
Biodegradable Bone Graft Polymers Market Segmentation
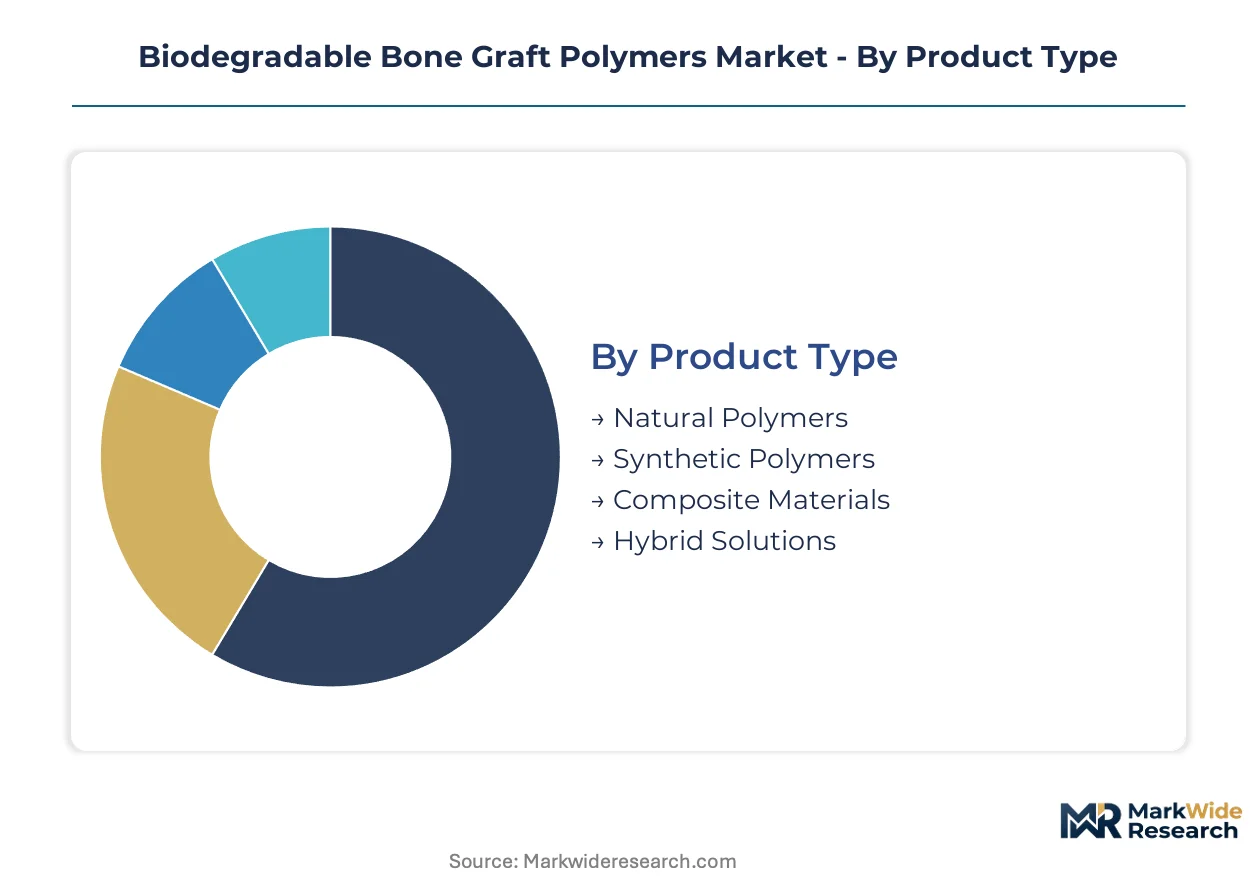
Segmentation in biodegradable bone graft polymers reveals how polymer chemistry, delivery format, and care setting interact to determine pricing power and regulatory pathway. Manufacturers configure product portfolios across these dimensions to match surgeon technique preferences and hospital procurement systems.
Product Type:
Standardization dominates at the commodity end with fermentation-derived feedstocks, while synthetic formulations offer tunable degradation curves for premium positioning.
- Natural Polymers:Collagen and chitosan matrices derived from bovine or marine sources provide immediate biocompatibility without foreign body reaction. Demand clusters in dental practices across Germany and France where CE marking requirements favor established biologic safety profiles over novel synthetic submissions.
- Synthetic Polymers:Polylactic acid, polyglycolic acid, and polycaprolactone deliver batch-to-batch consistency with degradation timelines engineered from months to two years. Academic medical centers in the United States specify these for spinal fusion studies generating reimbursement evidence.
- Composite Materials:Polymer-ceramic blends match cortical bone modulus for load-bearing trauma repairs.
- Hybrid Solutions:Synthetic scaffolds seeded with demineralized bone matrix combine osteoconduction with osteoinduction.
Growing fastest: Composite Materials. Leading the category by volume: Synthetic Polymers.
Application:
Procedure invasiveness and reimbursement codes segment demand across surgical specialties with divergent evidence requirements.
- Orthopedics:Spinal fusion and long-bone trauma procedures consume the majority of polymer graft volume. Hospital systems in Texas and California negotiate bundled payments that reward synthetic graft adoption when operating room time drops below autograft harvesting protocols.
- Dental Surgery:Ridge augmentation and sinus lift procedures favor particulate formats with rapid resorption. Private dental clinics in South Korea and Japan specify injectable pastes for outpatient implant site preparation under national health insurance reimbursement schedules.
- Tissue Engineering:Research-phase applications drive small-batch demand for customized degradation profiles.
- Regenerative Medicine:Cell-therapy combinations require GMP polymer grades with validated endotoxin limits.
Expanding most quickly: Regenerative Medicine. Dominating current volume: Orthopedics.
End User:
Purchasing authority and clinical evidence requirements separate institutional buyers from independent practitioners.
- Hospitals:Integrated delivery networks consolidate procurement through orthopedic implant distributors. Value analysis committees in Michigan and Pennsylvania evaluate graft products alongside fusion hardware in bundled vendor contracts.
- Clinics:Ambulatory surgery centers prioritize pre-sterilized single-use formats minimizing reprocessing overhead. California and Florida certificate-of-need regulations channel spine procedures toward these settings.
- Research Institutions:Academic medical centers generate clinical validation data supporting premium reimbursement codes.
- Dental Practices:Solo practitioners purchase through dental supply cooperatives with limited technical support.
Highest procurement sophistication: Hospitals. Fastest channel expansion: Clinics.
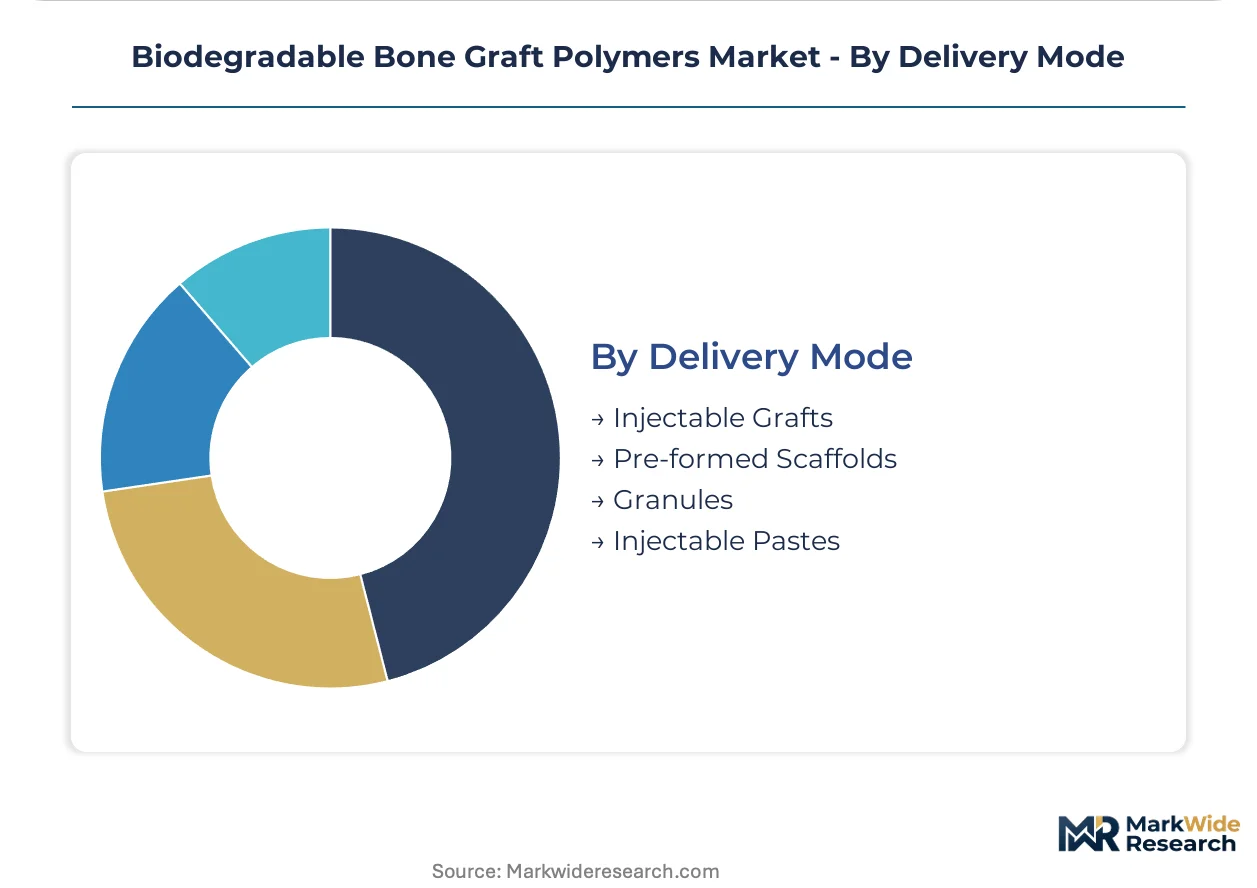
Delivery Mode:
Handling characteristics and surgical access route determine format selection across open versus minimally invasive procedures.
- Injectable Grafts:Flowable polymer-ceramic composites set in situ through thermal or chemical crosslinking. Kyphoplasty procedures in United States ambulatory centers specify these for vertebral compression fractures where open surgical access is contraindicated.
- Pre-formed Scaffolds:Anatomically shaped blocks and wedges eliminate intraoperative contouring time. Sterile-packed patient-matched devices reduce operating room minutes in metropolitan United States markets with bundled procedural payments.
- Granules:Particulate formats pack into irregular defect geometries with surgeon-controlled density.
- Injectable Pastes:Low-viscosity formulations navigate narrow-gauge needles for percutaneous delivery.
Steepest expansion trajectory: Injectable Pastes. Current volume leader: Pre-formed Scaffolds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American demand for biodegradable bone graft polymers through its concentration of orthopedic device headquarters and academic medical center purchasing power. The metropolitan corridor channels procurement decisions that cascade into community hospital systems nationwide.
United States
Academic medical centers in Boston and Houston generate clinical validation data that supports premium reimbursement codes for spinal fusion applications. FDA combination product pathway clarifications accelerate regulatory submissions for hybrid synthetic-natural formulations. The Research Triangle Park corridor in North Carolina concentrates polymer R&D facilities serving orthopedic OEMs.
Germany
Notified bodies in Tübingen and Berlin impose extended certification timelines under EU MDR requirements for Class III implantable devices. REACH authorization protocols for residual catalysts tighten supply qualification for medical-grade polylactide production. The Baden-Württemberg industrial cluster around Stuttgart hosts precision polymer converters supplying spinal implant manufacturers.
Japan
Aging demographic spine disorders drive demand for osteoinductive polymer-ceramic grafts in Tokyo and Osaka metropolitan markets. PMDA conditional approval pathways for combination products compress time-to-market for novel formulations. The Kobe biomedical innovation cluster accelerates regenerative medicine commercialization through integrated industry-academia partnerships.
China
Domestic orthopedic trauma procedure volumes expand demand for load-bearing composite grafts in Shanghai and Beijing hospital systems. NMPA regulatory reforms for innovative medical devices streamline priority review pathways for synthetic scaffolds. The Suzhou Industrial Park concentrates foreign-invested polymer manufacturing serving Asia-Pacific distribution networks.
Biodegradable Bone Graft Polymers Market Vendor Landscape
Capital-heavy polymer producers compete with asset-light graft designers across a market structure bifurcated between fermentation-derived feedstock suppliers and precision formulation specialists. The competitive terrain separates into three strategic archetypes: integrated orthopedic conglomerates bundling hardware with biologics, specialized polymer chemists commanding material science margins, and regional converters filling formulation gaps. Dominant competitive moves include backward integration into monomer supply and strategic partnerships with academic medical centers for clinical evidence generation.
Among diversified orthopedic conglomerates, Stryker Corporation and Zimmer Biomet Holdings exemplify the hardware-bundling archetype that leverages implant installed bases to capture graft procurement decisions. Evonik Industries AG anchors the high-performance synthetic segment through its specialty chemicals positioning. Corbion N.V. occupies a distinct tier competing on sustainable fermentation credentials for polylactic acid feedstocks.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings |
| Stryker Corporation |
| Medtronic plc |
| DePuy Synthes |
| Smith+Nephew plc |
| Evonik Industries AG |
| Corbion N.V. |
| Arthrex |
| Foster Corporation |
| Others |
Supply Flow & Price Mechanics
Hospital value analysis committees in Michigan and Pennsylvania are consolidating graft procurement alongside fusion hardware, forcing polymer converters to bundle sterile packaging with just-in-time delivery guarantees that compress margins on commodity formulations. This procurement consolidation elevates pricing power for manufacturers offering validated degradation profiles that reduce operating room time.
Pricing Analysis
Outcome-based pricing anchors premium tiers to operating room efficiency gains and spinal fusion success rates documented in academic medical centers. Three-tier pricing structure across premium, standard, and economy levels separates validated synthetic scaffolds with tunable degradation curves from fermentation-derived natural polymers and unbranded commodity particulates. Cost compression in the economy tier is intensifying because hospital systems are standardizing on dual-source contracts for natural polymer grafts. Ambulatory surgery centers exhibit highest price sensitivity due to fixed procedural reimbursements, while academic medical centers prioritize clinical evidence over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle demand from Stryker and Zimmer Biomet, while specialty distributors serve mid-tier orthopedic implant manufacturers. Raw material supply concentrates in the United States, the Netherlands, and Germany where Corbion, NatureWorks, and Evonik control fermentation-derived lactide and specialty resin capacity. Manufacturing draws from corn starch feedstocks, tin-based ring-opening polymerization catalysts, and medical-grade ceramic fillers. Single-source vulnerability in L-lactide monomer supply exposes converters to agricultural commodity volatility. Distribution runs through orthopedic implant distributors with GMP warehousing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Injectable paste formulations are displacing pre-shaped block polymers in minimally invasive spinal procedures, compressing demand for intraoperative contouring skills and rewarding manufacturers with flowable platform expertise.
For Market Incumbents: Anticipate margin erosion in natural polymer grafts as hospital systems consolidate procurement through bundled hardware-biologics contracts. Defensive moves center on backward integration into lactide monomer production and captive cleanroom capacity expansion in North Carolina's Research Triangle Park corridor. The priority lever rests on securing long-term supply agreements with academic medical centers generating reimbursement evidence. For New Entrants and Emerging Players: Launch via ambulatory surgery center distribution partnerships targeting injectable paste formulations for kyphoplasty and vertebroplasty procedures. White-space targets include Japan's PMDA conditional approval pathway for osteoinductive polymer-ceramic grafts and South Korean dental clinics specifying rapid-resorption particulates. The most penetrable entry point flows through sterile-packed single-use formats minimizing reprocessing overhead. For Investors and Strategic Acquirers: The window for entry favors precision polymer converters with validated ISO 10993 testing capabilities and established notified body relationships in Germany. Long-term viability hinges on differentiation through bioprinting convergence and vascularized graft architectures exceeding passive osteoconduction. The signal to watch is FDA guidance evolution on 3D-printed personalized graft classifications.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Combination Product Pathway Navigation | Regulatory clarity accelerates hybrid synthetic-natural formulation submissions for spinal fusion. |
| Academic Medical Center Partnership | Clinical validation at Boston and Houston institutions supports premium reimbursement code generation. |
| Injectable Paste Platform Development | Flowable polymers capture ambulatory surgery center volume beyond traditional hospital operating rooms. |
| EU MDR Certification Investment | Notified body readiness in Tübingen and Berlin defends market access under stricter evidence requirements. |
| Bioprinting Capability Acquisition | Melt electrowriting integration enables vascularized graft architectures commanding premium positioning. |
Methodological Framework
Multi-period observation of hospital procurement consolidation patterns, regulatory submission timelines, and polymer degradation study completion rates anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital value analysis committee members, biomedical engineers, GPO contracts managers, and polymer R&D directors. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, hospital procurement records, and SEC filings of publicly traded orthopedic device manufacturers. Bottom-up demand modeling triangulated against top-down market sizing.
Segment-weighting across product type, application, end user, and delivery mode dimensions structured the analytical framework across the projection horizon. CAGRs derived from fitted growth curves applied to procedure volume projections and average selling price trajectories. Industry-specific forecast inputs incorporated spinal fusion reimbursement code valuations and cleanroom capacity expansion announcements.
Regulatory pathway delays, raw material feedstock volatility, and surgeon training adoption curves are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding FDA guidance stability and EU MDR implementation consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Polysaccharide Hemostatic System Market
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
Scaffold Materials Market
Biomaterials
Global Hydroxyapatite Market
Biomaterials
Flowable Hemostats Market
Biomaterials
Bone Substitutes Market
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
US Heparin Market
Biomaterials
Calcium Phosphate Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Heparin Market
Biomaterials
Global Medical Engineered Materials Market
Biomaterials
Bioceramics and Hydroxyapatite Market
Biomaterials
Chitosan Market
Biomaterials
North America Chitosan Market