
 Silver Cyanide Market | 2026-2036
Silver Cyanide Market Size, Share, and Industry Trends Forecast 2026-2036
Silver Cyanide Market Outlook
Buyer concentration among electronics electroplaters is realigning how silver cyanide suppliers structure volume contracts. TANAKA Holdings Co., Ltd. leverages its integrated precious metals refining to secure captive feedstock for plating salts. Merck KGaA anchors European supply through its high-purity chemical portfolio, while American Elements competes on specialty grades for research and niche industrial applications.
Silver cyanide (AgCN) is an inorganic compound formed by reacting silver salts with cyanide sources, typically appearing as white to grayish crystalline or powder material with purity grades exceeding 99% for electroplating applications. Its primary function serves as a controlled silver ion source in alkaline cyanide plating baths, delivering uniform, adherent metal deposits for connectors, contacts, and decorative finishes. Crystalline and powder forms dominate current volumes, with aqueous solution formats gaining traction among automated plating lines seeking reduced handling hazards. Electroplating applications lead absolute consumption, though pharmaceutical and chemical synthesis segments present higher margin pools due to stringent certification requirements.
EPA regulations under the Clean Water Act constrain cyanide discharge limits from plating operations, directly shaping demand for closed-loop bath management and waste treatment systems. REACH registration and the EU's CLP classification impose documentation burdens on importers, while China's MEE enforces tighter wastewater standards around electroplating clusters in Guangdong and Jiangsu provinces. Stakeholders must monitor how dual carbon mandates and evolving cyanide substitution research reshape long-term application viability across key manufacturing geographies.
Market Dynamics
Electronics electroplaters in China, Japan, and Germany are consolidating purchase volumes, forcing silver cyanide suppliers to restructure contract terms around dedicated capacity allocations and technical service bundling rather than spot pricing.
Growth Catalysts
- Semiconductor packaging expansion:Advanced flip-chip and wafer-level packaging in Taiwan and South Korea requires high-purity silver cyanide for interconnect metallization, pulling volumes from decorative plating into electronics.
- REACH registration completion:Full ECHA dossier acceptance for silver cyanide salts has clarified import pathways into EU electroplating clusters, reducing regulatory uncertainty for continental buyers.
- Closed-loop bath chemistry:Automated dosing systems using real-time silver ion monitoring are extending effective bath life, reducing per-unit cyanide consumption while maintaining output quality.
Market Restraints
- Precious metal price volatility:Silver spot fluctuations directly transmit to AgCN production costs, compressing margins for formulators lacking backward integration into bullion sourcing.
- Single-source cyanide dependency:Hydrogen cyanide feedstock concentrates among petrochemical producers in the US Gulf Coast and Chinese coal-chemical corridors, creating supply chokepoints.
- Cyanide substitution research:Non-cyanide silver plating chemistries using thiosulfate or sulfite complexes are achieving commercial viability in decorative applications, threatening volume in lower-specification segments.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme subsidies for semiconductor and component fabrication are attracting electroplating capacity to Gujarat and Tamil Nadu, creating fresh demand for plating salts.
- Pharmaceutical API synthesis:Silver cyanide serves as a reagent in antiviral and oncology intermediate production, commanding price premiums five to eight times above plating grades due to GMP certification requirements.
- Green hydrogen infrastructure:Electrolyzer stack manufacturing in Germany and Denmark requires precision-plated bipolar plates, opening a novel industrial end-use with stringent purity specifications.
Industry Challenges
- Cyanide handling certification:EPA and MEE mandates for specialized transport and storage credentials are lengthening onboarding timelines for new logistics providers and warehouse operators.
- Legacy bath conversion costs:Electroplaters running decades-old open-tank lines face capital barriers to retrofitting closed-loop filtration and automated dosing, delaying efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver Cyanide Market |
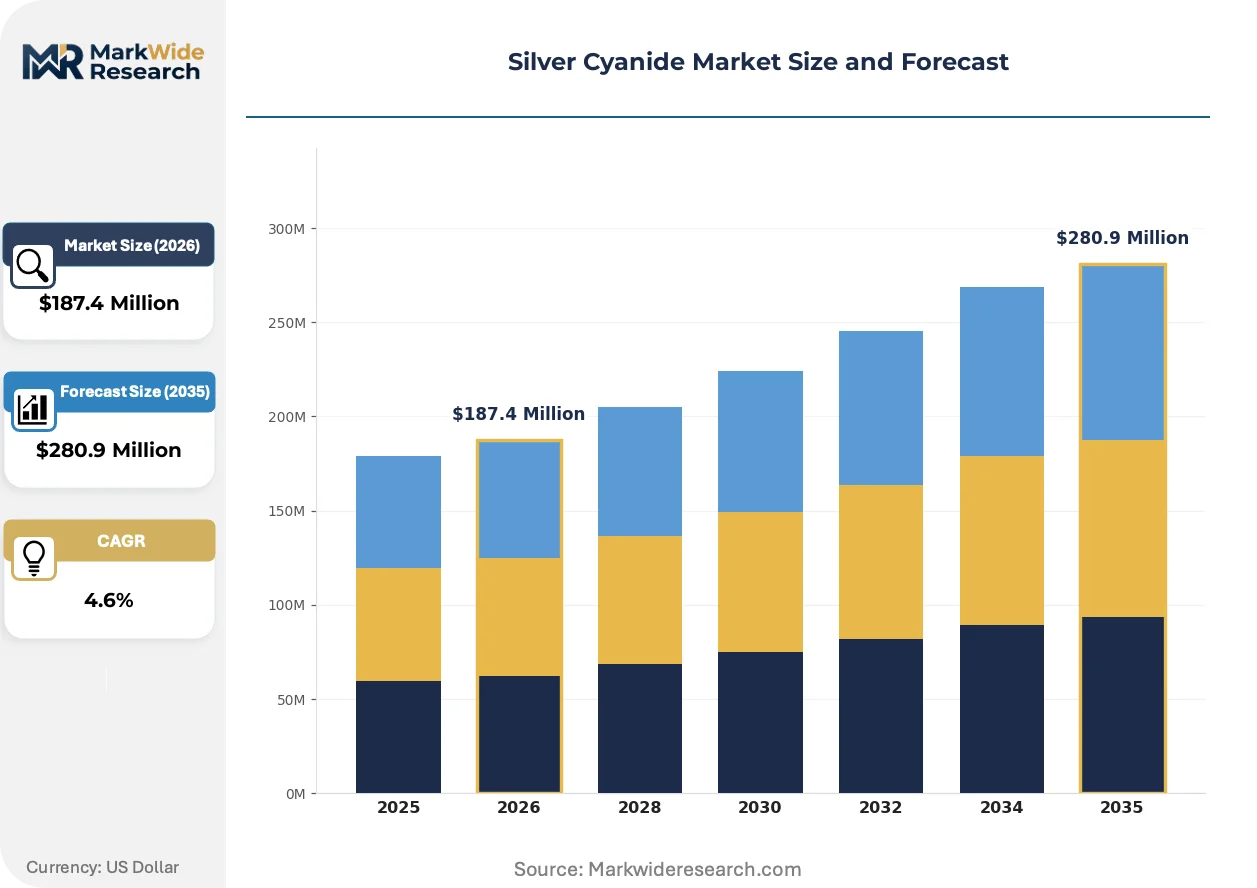
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline, Powder, Granules, Aqueous Solution Application: Electroplating, Chemical Synthesis, Pharmaceuticals, Mining End User: Jewelry Manufacturers, Electronics, Healthcare, Mining Companies Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | TANAKA Holdings Co., Ltd., SAXONIA Edelmetalle GmbH, Thermo Fisher Scientific, SUVCHEM, Merck KGaA, Umicore, American Elements, Metalor Technologies SA, Alfa Aesar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver Cyanide Market Strategic Shifts
Silver cyanide formulation and delivery methods are fragmenting across performance tiers, with automated systems and alternative geometries displacing manual handling in high-throughput operations while research-grade specifications proliferate.
Pre-mixed aqueous silver cyanide solutions are decentralizing supply relationships by eliminating on-site dissolution hazards and enabling just-in-time delivery contracts. Connector manufacturers in Shenzhen and Suzhou are adopting bulk tanker shipments with in-line filtration. This format is decentralizing procurement authority from central chemical stores to individual plating line supervisors.
China's MEE is tightening wastewater discharge standards for electroplating clusters in Guangdong province, mandating zero liquid discharge systems for new facilities. Plating shops are consolidating into industrial parks with shared treatment infrastructure. Small independent operators without relocation capital are exiting, concentrating demand among larger integrated electroplaters.
Electronics OEMs are compressing supplier qualification cycles from twenty-four months to twelve, driven by accelerated product roadmaps in 5G infrastructure and electric vehicle charging. Silver cyanide vendors must front-load technical documentation and audit readiness. This acceleration is most pronounced among Taiwanese and South Korean contract manufacturers serving North American automotive customers.
Silver Cyanide Market Segmentation
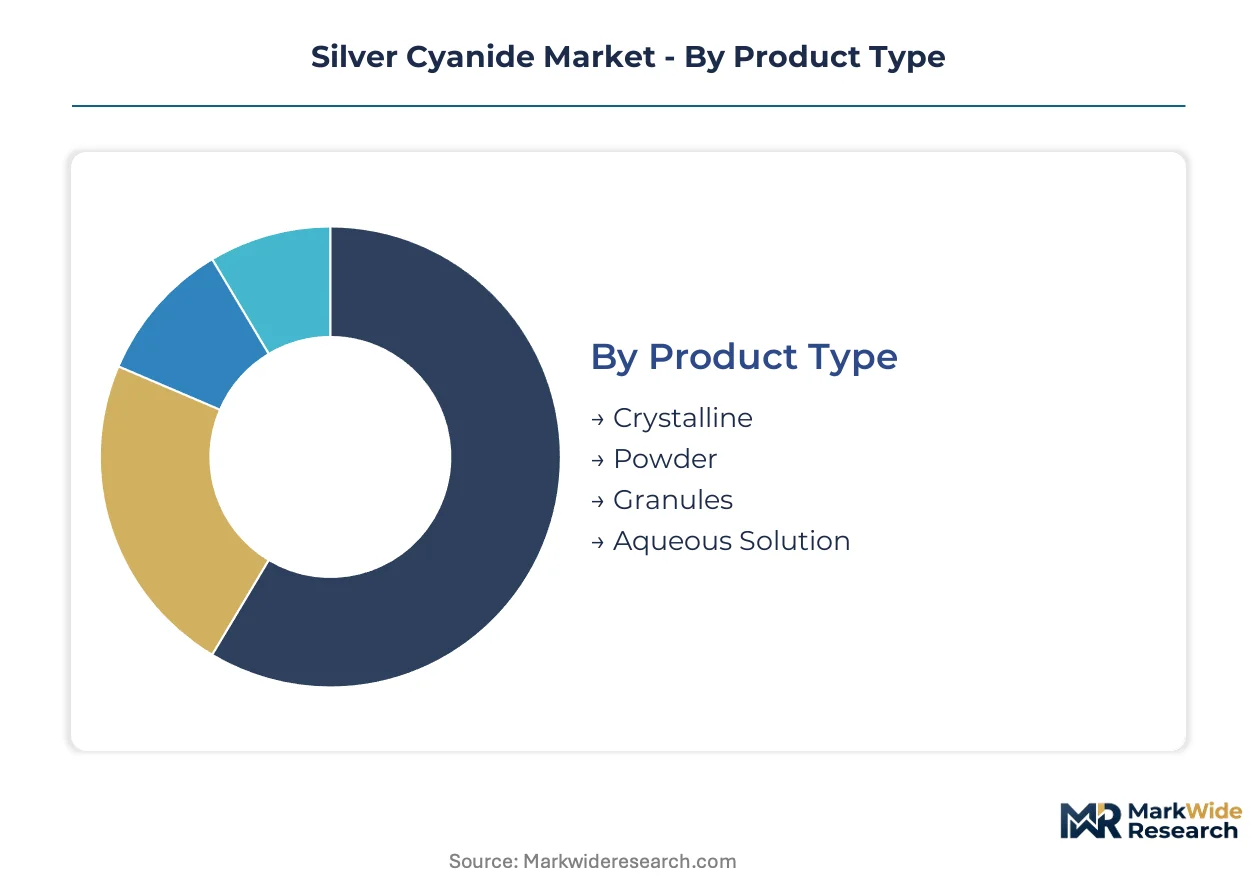
Silver cyanide procurement patterns diverge sharply across product formats and end-use specifications. Capital allocation decisions by electroplaters and pharmaceutical manufacturers determine which segments command premium pricing and technical service investment.
Product Type:
Capital intensity varies dramatically across physical formats, with solution-based delivery requiring specialized transport infrastructure while crystalline production demands precious metals refining integration.
- Crystalline:High-purity monoclinic crystals exceeding 99% AgCN content serve precision electroplating baths for semiconductor interconnects. Taiwan and South Korean packaging facilities specify crystalline grades for batch consistency in flip-chip metallization, though silver spot volatility compresses margins for non-integrated suppliers.
- Powder:Finely divided particulate dominates decorative plating volumes across Guangdong and Zhejiang province clusters. Powder handling automation reduces occupational exposure risks, yet legacy open-tank operations in India and Southeast Asia still rely on manual dissolution protocols.
- Granules:Compressed agglomerates dissolve more slowly than powder, suiting continuous-feed systems in German and Danish electrolyzer manufacturing.
- Aqueous Solution:Pre-dissolved formats eliminate on-site cyanide handling permits, attracting just-in-time contracts from Shenzhen connector manufacturers.
Most installed capacity flows through Powder. Expansion is steepest in Aqueous Solution.
Application:
Margin structure separates commodity plating from certified pharmaceutical synthesis, with regulatory burden intensity determining supplier qualification timelines.
- Electroplating:Alkaline cyanide baths deposit adherent silver layers for electrical contacts, RF connectors, and decorative finishes. China's MEE wastewater mandates are consolidating demand among electroplaters with zero-liquid-disclosure capital, squeezing independent operators in Jiangsu province.
- Chemical Synthesis:Reagent-grade AgCN facilitates nitrile formation and silver-mediated coupling reactions. Specialty chemical producers in Basel and Ludwigshafen specify ultra-low halide content for catalyst applications.
- Pharmaceuticals:GMP-certified batches for antiviral and oncology intermediate production command five-to-eight-fold pricing premiums over plating grades. FDA and EMA audit trails extend supplier onboarding to eighteen months.
- Mining:Historical use in precious metals extraction persists in limited jurisdictions with permissive cyanide codes, though environmental litigation has collapsed volumes outside regulated industrial park settings.
Electroplating absorbs the greatest volume. Pharmaceuticals generates the highest margin per kilogram.
End User:
Customer technical sophistication dictates service bundling requirements, with electronics OEMs demanding real-time bath monitoring integration.
- Jewelry Manufacturers:Decorative plating for luxury goods concentrates in Vicenza, Shenzhen, and Bangkok, where thiosulfate substitution research threatens lower-specification cyanide demand.
- Electronics:Semiconductor packaging and connector fabrication in Taiwan, South Korea, and Germany specify ionic purity below 10 ppm trace metals. Automated dosing system compatibility is now a standard procurement criterion.
- Healthcare:Medical device plating for surgical instruments and implantable components requires biocompatibility certification under EU MDR and FDA 510(k) pathways.
- Mining Companies:Remaining offtake concentrates in state-controlled operators with integrated cyanide production and closed-loop tailings infrastructure.
Electronics commands the deepest technical service relationships. Healthcare shows the steepest certification barrier escalation.
Distribution Channel:
Channel selection reflects hazard classification and customer scale, with direct relationships dominating bulk pharmaceutical procurement.
- Direct Sales:Producer-to-electroplater contracts lock in volume allocations and technical support for multi-ton annual offtake. TANAKA Holdings and Merck KGaA anchor continental supply through dedicated account management.
- Distributors:Regional chemical handlers stock crystalline and powder grades for mid-tier plating shops lacking bulk storage permits. REACH and EPA transport credentials limit viable distributor networks.
- Online Retail:Research-grade quantities below 1 kg reach university and specialty synthesis laboratories through compliant e-commerce platforms with hazardous materials shipping certification.
- Others:Industrial gas suppliers bundle silver cyanide with hydrogen cyanide feedstock for captive electroplating operations.
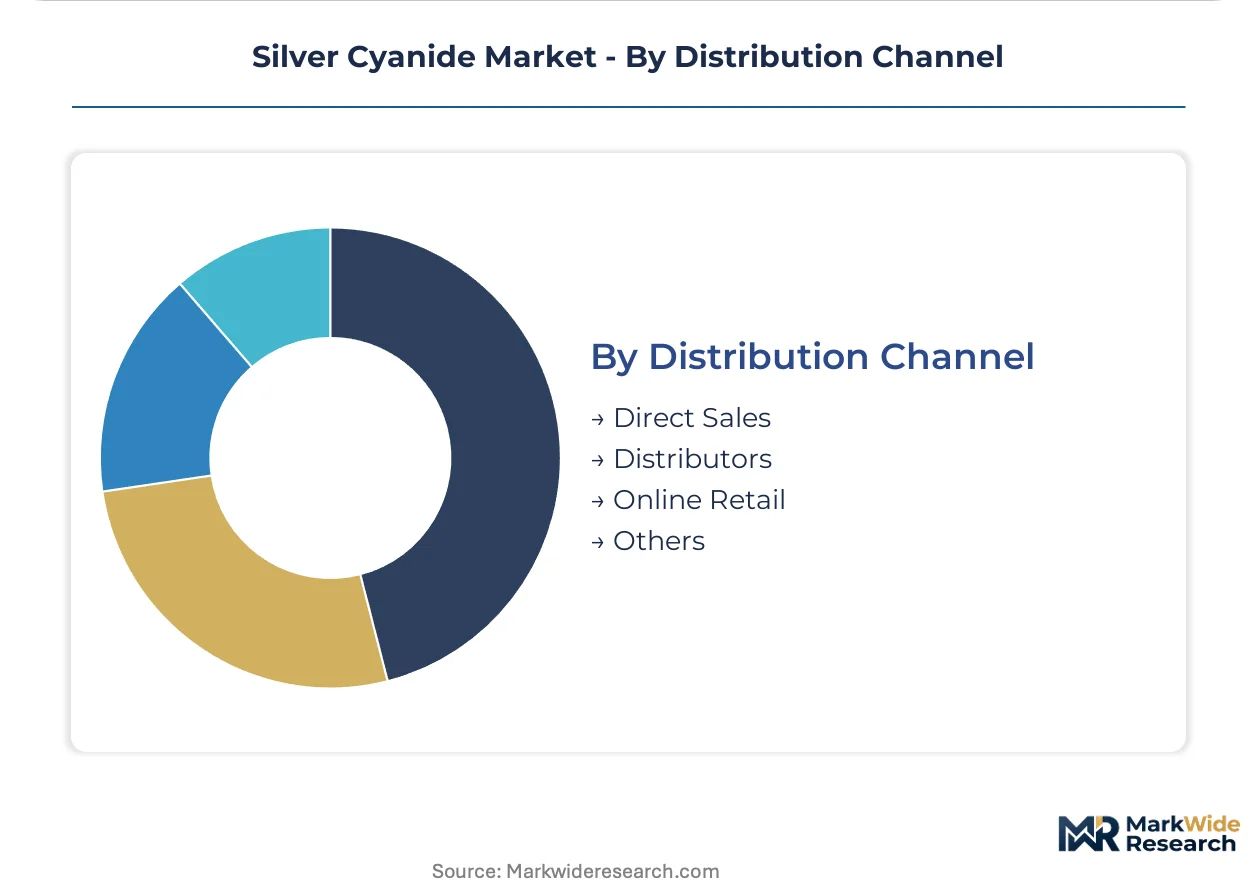
Direct Sales captures the greatest value. Online Retail is expanding most quickly among research segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled electroplating technicians and chemical process engineers concentrate in East Asian manufacturing corridors, German industrial clusters, and North American automotive belts. These workforce pools anchor silver cyanide consumption patterns across three continents. Regional regulatory divergence now shapes where new plating capacity deploys.
China
Connector manufacturers in Shenzhen and Suzhou drive crystalline silver cyanide demand for 5G infrastructure and electric vehicle charging components. MEE wastewater mandates in Guangdong province force electroplaters into zero-liquid-discharge industrial parks. Independent plating shops lacking relocation capital exit, consolidating volume among larger integrated operators with captive treatment infrastructure.
Germany
Electrolyzer stack fabricators in Bavaria and Lower Saxony require precision-plated bipolar plates for green hydrogen infrastructure. REACH registration completion through ECHA clarifies import pathways for high-purity plating salts. The Ludwigshafen-Basel chemical corridor hosts specialty formulators serving pharmaceutical synthesis applications with GMP-certified batches.
United States
Defense contractors and medical device manufacturers in Texas and the Midwest specify ultra-low trace metal content for implantable components and avionics connectors. EPA Clean Water Act discharge limits constrain open-tank plating operations. Gulf Coast petrochemical corridors supply hydrogen cyanide feedstock, creating geographic chokepoints for domestic AgCN production.
South Korea
Semiconductor packaging facilities in Suwon and Gwangju pull silver cyanide volumes from decorative plating into flip-chip metallization. MFDS pharmaceutical oversight extends to reagent-grade material used in antiviral intermediate synthesis. Automated dosing system compatibility now dominates procurement criteria for electronics OEMs.
India
PLI scheme subsidies attract electroplating capacity to Gujarat and Tamil Nadu for semiconductor component fabrication. CDSCO pharmaceutical regulations govern silver cyanide use in API synthesis for oncology and antiviral production. Mid-tier plating shops in Delhi-NCR and Maharashtra still rely on manual powder dissolution, creating occupational exposure compliance gaps.
Silver Cyanide Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct value chain positions. The market structures around three tiers: precious metals refiners with captive feedstock, high-purity chemical houses serving regulated industries, and specialty distributors handling research-grade quantities. Consolidation pressure intensifies as electronics OEMs compress supplier qualification cycles. Backward integration into bullion sourcing and technical service bundling represent the dominant competitive moves.
Among integrated precious metals groups, TANAKA Holdings Co., Ltd. and Umicore occupy positions anchored by refining infrastructure. Merck KGaA exemplifies the high-purity chemical archetype with its European supply footprint. American Elements represents specialty-grade suppliers competing on research and niche industrial specifications. These three archetypes—refiner-integrated, chemical-major, and specialty-distributed—capture distinct margin pools based on certification burden and volume scale.
| Leading Market Players |
|---|
| TANAKA Holdings Co., Ltd. |
| SAXONIA Edelmetalle GmbH |
| Thermo Fisher Scientific |
| SUVCHEM |
| Merck KGaA |
| Umicore |
| American Elements |
| Metalor Technologies SA |
| Alfa Aesar |
| Others |
Value Chain & Pricing Dynamics
China's MEE zero-liquid-discharge mandates for electroplating clusters gate both qualified supply and premium-tier pricing access, as only integrated operators with captive wastewater infrastructure can meet pharmaceutical-grade certification requirements while smaller independents face forced exit.
Pricing Analysis
Bundled technical service contracts versus unbundled commodity spot purchases split the pricing landscape for silver cyanide. Three-tier pricing structure across GMP-certified pharmaceutical, high-purity electroplating, and standard decorative grades reflects certification burden and trace metal specifications. Cost compression in decorative plating tiers is intensifying because thiosulfate substitution research achieves commercial viability for lower-specification applications. Jewelry manufacturers in Bangkok and Vicenza exhibit highest price sensitivity, while semiconductor packaging facilities in Taiwan and South Korea prioritize ionic purity over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with hydrogen cyanide feedstock concentration among US Gulf Coast petrochemical producers and Chinese coal-chemical corridors in Shanxi and Inner Mongolia. Silver cyanide production draws from silver bullion refiners in Japan, Germany, and the United States alongside cyanide sources from these concentrated chemical manufacturing zones. Tariff exposure on precious metals imports creates structural risk for European formulators lacking backward integration into bullion sourcing. Distribution runs through direct producer-to-electroplater contracts for multi-ton offtake, with regional chemical distributors serving mid-tier plating shops lacking bulk storage permits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silver cyanide market functions as a stable compounder, with semiconductor packaging expansion and green hydrogen electrolyzer manufacturing providing durable demand anchors across electronics and energy transition end-uses.
For Market Incumbents: Deepen captive bullion sourcing through precious metals refining integration to defend margin position against silver spot volatility. Prioritize GMP certification investment for pharmaceutical-grade batches, as FDA and EMA audit trails extend supplier onboarding timelines and lock out non-compliant competitors. Add dedicated aqueous solution capacity in Guangdong province to capture MEE-mandated consolidation among electroplating clusters. For New Entrants and Emerging Players: Begin with research-grade and specialty synthesis segments where American Elements and Alfa Aesar compete on specification rather than scale, as these niches lack integrated refiner dominance. Target Indian electronics manufacturing clusters in Gujarat and Tamil Nadu where PLI scheme subsidies attract electroplating capacity without established supplier relationships. Lead with just-in-time aqueous solution delivery to bypass on-site cyanide handling permit barriers that constrain crystalline and powder competitors. For Investors and Strategic Acquirers: Roll-up economics work for regional electroplating chemical distributors because REACH and EPA transport credentials limit viable networks, creating scarcity value for compliant handlers. Five-to-ten-year viability rests on cyanide substitution research failing to achieve semiconductor-grade performance thresholds. Watch thiosulfate and sulfite complex plating chemistry adoption rates in decorative applications as the inflection signal for volume erosion in lower-specification segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bullion Refining | TANAKA Holdings and Umicore secure captive silver feedstock against London Bullion Market Association price swings. |
| GMP Certification Investment | Merck KGaA extends pharmaceutical reagent onboarding timelines to eighteen months through FDA and EMA audit compliance. |
| Aqueous Solution Capacity Expansion | Shenzhen connector manufacturers adopt bulk tanker shipments with in-line filtration to eliminate on-site dissolution hazards. |
| Zero-Liquid-Discharge Infrastructure Partnership | Guangdong electroplating parks consolidate shared treatment systems under MEE wastewater mandates. |
| Automated Dosing System Integration | Taiwanese packaging facilities specify real-time silver ion monitoring compatibility as standard procurement criterion. |
Study Parameters
Direct dialogue with electroplating plant managers, precious metals procurement leads at electronics OEMs, pharmaceutical synthesis R&D directors, and regional chemical distribution channel partners grounded the qualitative assessment. Secondary validation drew from customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings from diversified chemical conglomerates, and EPA enforcement action databases. Bottom-up capacity and consumption estimates triangulated against top-down macroeconomic drivers across the analysis window.
Segment-level projections across crystalline, powder, granule, and aqueous solution formats incorporated electroplating bath chemistry evolution, pharmaceutical API synthesis demand, and mining sector contraction. End-use modeling spanned electronics interconnect metallization, decorative plating, chemical synthesis reagent applications, and GMP-certified pharmaceutical intermediate production. CAGRs were derived from regression analysis of historical precious metals price elasticity, regulatory enforcement intensity indices, and semiconductor packaging capacity expansion announcements.
Several conditions sit outside the modeled scope, including breakthrough non-cyanide plating chemistry achieving semiconductor-grade performance, abrupt silver bullion supply disruptions from geopolitical conflict, and accelerated electroplating capacity relocation outside China due to dual carbon mandate enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Steel Salvage Drums Market
Metals
Silver-Platinum Paste Market
Metals
India Metal Fabrication Market
Metals
Shipbuilding Steel Plate Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Nickel Market
Metals
Aluminum Flat Products Market
Metals
Global Galvanized Steel Wire Market
Metals
Precious Metals Wire Market
Metals
Europe Aluminium Cans Market
Metals
Beryllium Copper Billet Market
Metals
Transition Metals Market
Metals
High Purity Pig Iron Market
Metals
Chrome Metal Powder Market
Metals
Global Welding Powder Market
Metals
Beryllium Copper Plate Market