
 Platinum Market | 2026-2036
Platinum Market Size, Share, and Industry Trends Forecast 2026-2036
Platinum Market Intelligence
Multi-source concentrate procurement is recalibrating how refiners secure platinum feedstock amid South African supply volatility. Anglo American plc leverages its integrated Bushveld operations to sustain upstream control over concentrate flows. Sibanye Stillwater Limited anchors its position through North American recycling assets that offset primary mine disruptions. Impala Platinum Holdings Limited competes by dominating smelting capacity in the Western Limb.
Platinum is a dense, corrosion-resistant transition metal with a melting point of 1,768.3°C, primarily valued for catalytic activity in emission control and chemical processing. Automotive catalyst applications command the largest volume share, though margin pools are thinning as thrifting and palladium substitution advance. Electronics and chemical processing segments are expanding fastest, driven by hydrogen economy catalyst demand and silicone refining needs in Asia.
EPA tailpipe standards, EU F-Gas Regulation, and South Africa's Department of Mineral Resources and Energy licensing frameworks collectively shape product specifications and market access conditions. The EPA mandates force automakers to maintain minimum platinum loadings in gasoline particulate filters. Stakeholders must monitor hydrogen infrastructure subsidy programs and fuel-cell vehicle deployment targets to anticipate platinum offtake trajectories.
Market Dynamics
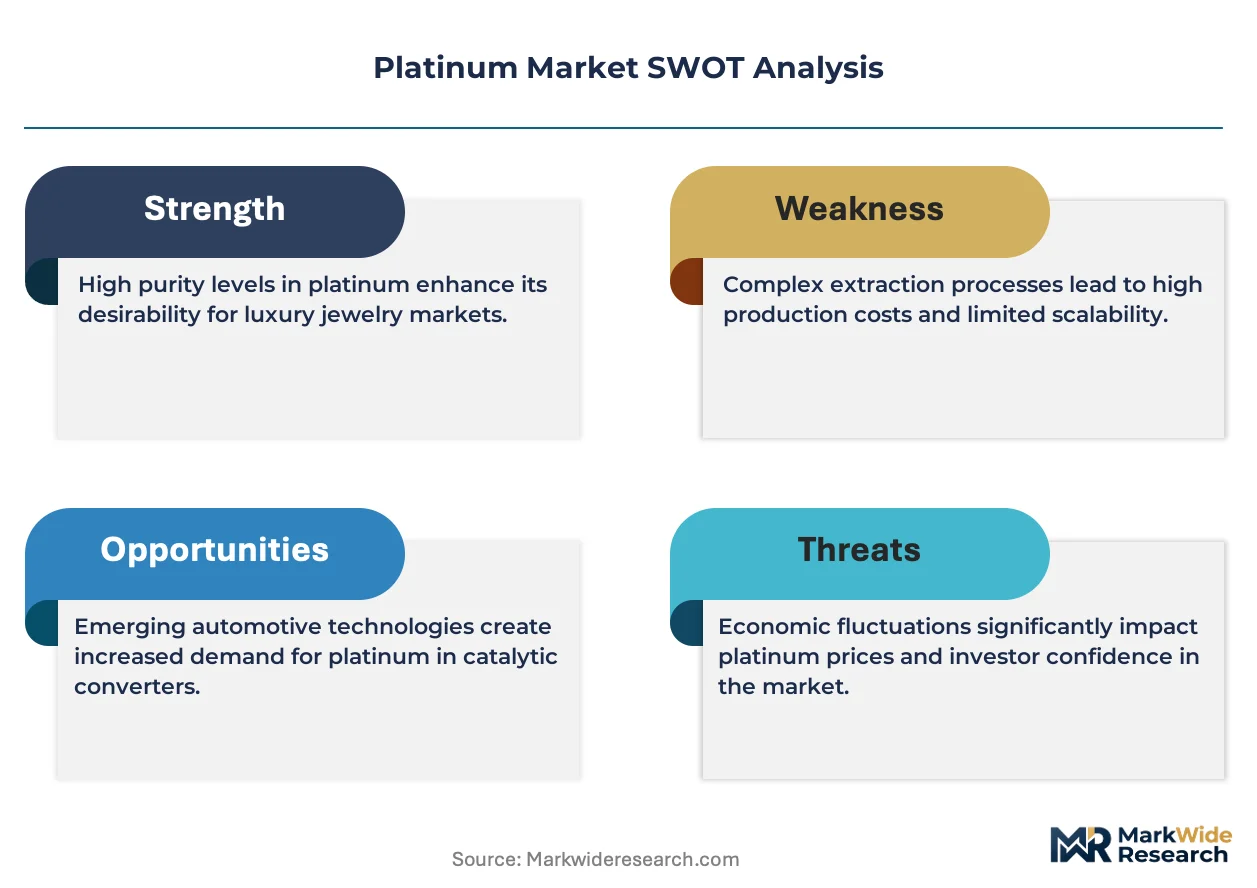
Automotive emissions compliance is forcing platinum loadings upward as gasoline particulate filters absorb metal volumes that palladium thrifting once displaced. This regulatory pull collides with South African supply volatility to create persistent feedstock tension.
Growth Catalysts
- EPA Tier 3 tailpipe mandates:Gasoline particulate filter specifications in the US force automakers to maintain minimum platinum loadings, sustaining offtake volumes despite thrifting pressure elsewhere.
- China's petrochemical expansion:Naphtha reforming catalyst demand concentrates in coastal refineries where platinum serves as the critical active metal for aromatic production.
- Hydrogen economy infrastructure:Proton exchange membrane electrolyzer deployment creates new catalyst demand channels distinct from traditional automotive and chemical processing applications.
Market Restraints
- Bushveld Complex concentration:Over 70% of primary platinum supply originates from South African underground operations exposed to labor stoppages and Eskom grid instability.
- Palladium substitution in gasoline catalysts:Three-way catalyst formulations continue displacing platinum in light-duty gasoline applications where thermal durability requirements permit.
- Capital intensity of new mine development:Deep-level mechanization requirements and ventilation infrastructure demands deter greenfield investment outside existing orebody extensions.
Strategic Opportunities
- EU Green Deal hydrogen subsidies:Renewable hydrogen production targets in Germany and the Netherlands accelerate electrolyzer manufacturing capacity that consumes platinum-group catalysts.
- Platinum recycling arbitrage:North American automotive catalyst collection networks capture spent substrate value that primary concentrate shortages make economically viable.
- Silicone monomer refining in Asia:Platinum-catalyzed hydrosilylation for high-purity silicone production expands with electronics and medical grade material demand in Japan and South Korea.
Industry Challenges
- Smelting furnace rebuild cycles:Anglo American Platinum and Impala Platinum face concentrated maintenance windows that disrupt concentrate throughput timing.
- PGM assay verification complexity:Recycling feedstock valuation requires precise fire assay and instrumental analysis that skilled technician shortages delay.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platinum Market |
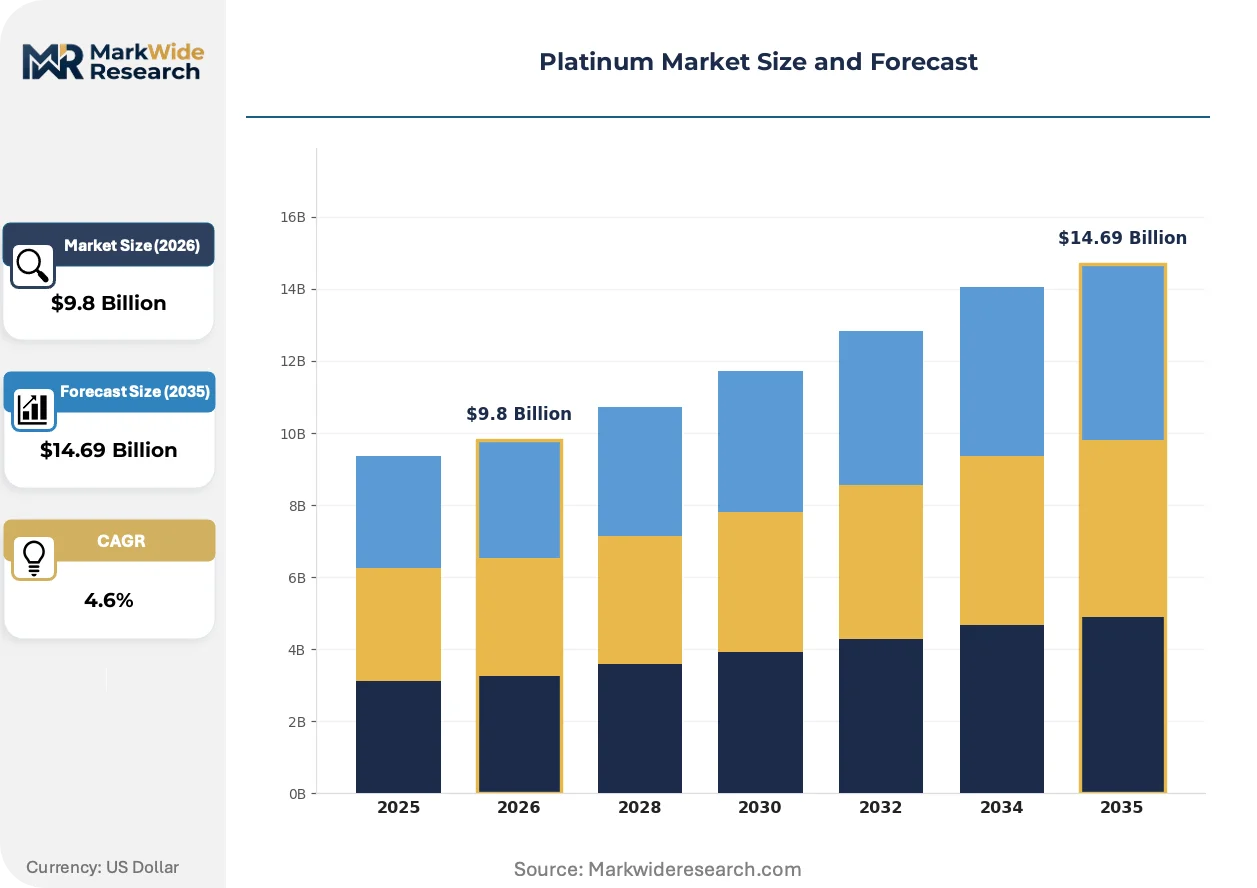
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platinum Ingots, Platinum Bullion, Platinum Coins, Platinum Jewelry End User: Jewelry Manufacturers, Industrial Applications, Investment Firms, Investors Form: Unalloyed, Alloyed, Powder, Sheet Application: Automotive Catalysts, Electronics, Dentistry, Chemical Processing |
| Companies Covered | Valterra Platinum Ltd., Eastern Platinum Ltd., Anglo American plc, Panther Metals, Zimplats Holdings Ltd., Sibanye Stillwater Limited, Platinum Group Metals Ltd., Coeur Mining, Impala Platinum Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platinum Market Strategic Shifts & Innovations
Platinum applications are fragmenting across hydrogen energy systems while automotive demand plateaus, forcing metal flows into unfamiliar industrial channels. Technology substitution and regulatory redesign are rewriting competitive access rules.
Platinum-ruthenium alloy catalysts for proton exchange membrane electrolyzers are rewriting the metal's demand geography. Electrolyzer OEMs in Germany and Japan specify these formulations for alkaline-resistant coatings. The shift pulls metal volumes away from automotive contract structures toward energy infrastructure procurement timelines.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbons indirectly strengthen platinum demand in fluorochemical production where the metal catalyzes alternative refrigerant precursors. Chemical processors in Belgium and France expand reforming capacity to capture this regulatory displacement. The policy creates a secondary demand channel insulated from automotive cycle volatility.
Long-term offtake contracts with hydrogen project developers are displacing spot market sales for major refiners. Japanese trading houses and German utility consortia now secure five-year platinum supply commitments for electrolyzer manufacturing. This contracting pattern concentrates pricing power with integrated miners who can guarantee concentrate purity and delivery schedules.
Platinum Market Segmentation
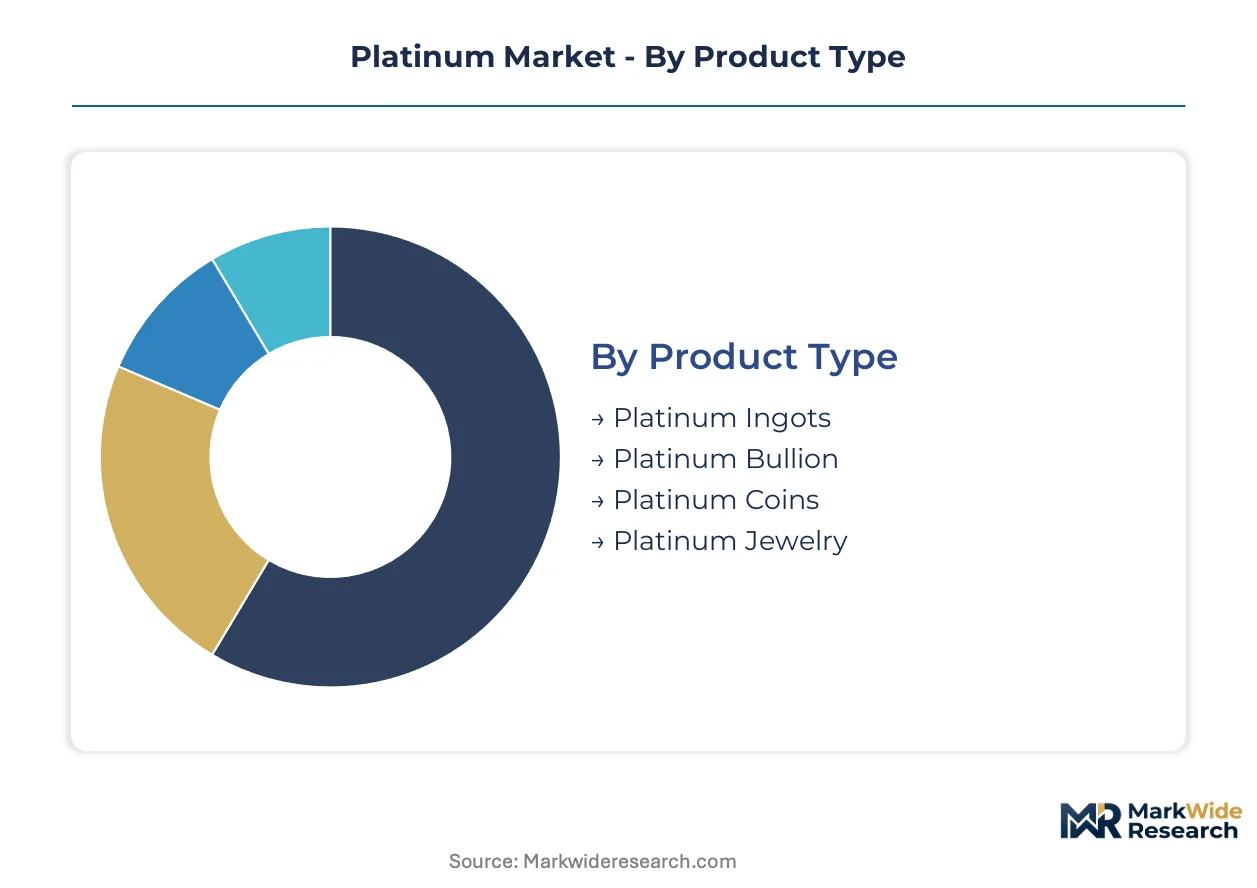
Platinum market segmentation reveals divergent value capture mechanisms across physical forms and buyer profiles. Industrial procurement cycles, investment holding periods, and fabrication specifications create distinct margin pools that suppliers must navigate separately.
Product Type:
Purity thresholds and liquidity premiums drive buyer selection more than physical dimensions alone.
- Platinum Ingots:Cast bars of 99.95% minimum purity serve as the standard settlement unit for industrial contracts and central bank reserves. Chemical processors in Germany and Japan specify ingot delivery for catalyst manufacturing feedstock.
- Platinum Bullion:Investment-grade bars and rounds trade on spot markets with lower fabrication premiums than numismatic products. Retail accumulation in North American and European markets concentrates in bullion formats during price dips.
- Platinum Coins:Government-minted legal tender products carry numismatic premiums that fluctuate with collector demand. The American Platinum Eagle and Canadian Maple Leaf dominate retail investment channels.
- Platinum Jewelry:Fabricated into rings, necklaces, and watch components where whiteness and hypoallergenic properties command design premiums. Japanese and Chinese consumers drive fabrication demand for high-purity settings.
Platinum Ingots leads on scale; Platinum Bullion leads on momentum.
End User:
Contract structures and holding horizons separate industrial consumers from financial buyers.
- Jewelry Manufacturers:Fabricators in Italy and India purchase sponge and grain for alloying and casting operations. Their procurement tracks bridal seasonality and fashion cycle timing.
- Industrial Applications:Automotive catalyst producers, chemical processors, and electronics manufacturers dominate volume offtake through long-term supply agreements. Their contracts specify minimum 99.9% purity with assay certificates.
- Investment Firms:Pension funds and asset managers accumulate physical platinum through allocated and unallocated storage programs. Their flows respond to real interest rate movements and dollar weakness signals.
- Investors:Individual buyers acquire coins, small bars, and exchange-traded products for portfolio diversification. Retail demand spikes during macroeconomic uncertainty periods.
Industrial Applications leads on scale; Investment Firms leads on momentum.
Form:
Processing requirements and downstream compatibility determine form selection for specific applications.
- Unalloyed:Pure platinum in ingot, sponge, or grain form serves chemical and electronics applications requiring maximum catalytic surface area. Hydrogen electrolyzer manufacturers specify unalloyed sponge for catalyst coating operations.
- Alloyed:Ruthenium, iridium, or cobalt additions enhance hardness and wear resistance for jewelry and electrical contacts. Dental laboratories specify platinum-iridium alloys for crown frameworks.
- Powder:Atomized or chemically precipitated particulate enables additive manufacturing and thick-film electronics. Powder metallurgy applications in Japan consume fine platinum powder for sensor electrodes.
- Sheet:Rolled and annealed foil serves laboratory equipment, catalytic gauze, and precision instrument components. Chemical processors in Belgium specify platinum-rhodium alloy sheet for nitric acid production.
Unalloyed leads on scale; Powder leads on momentum.
Application:
Technical specifications and regulatory loadings create divergent demand intensity across end-uses.
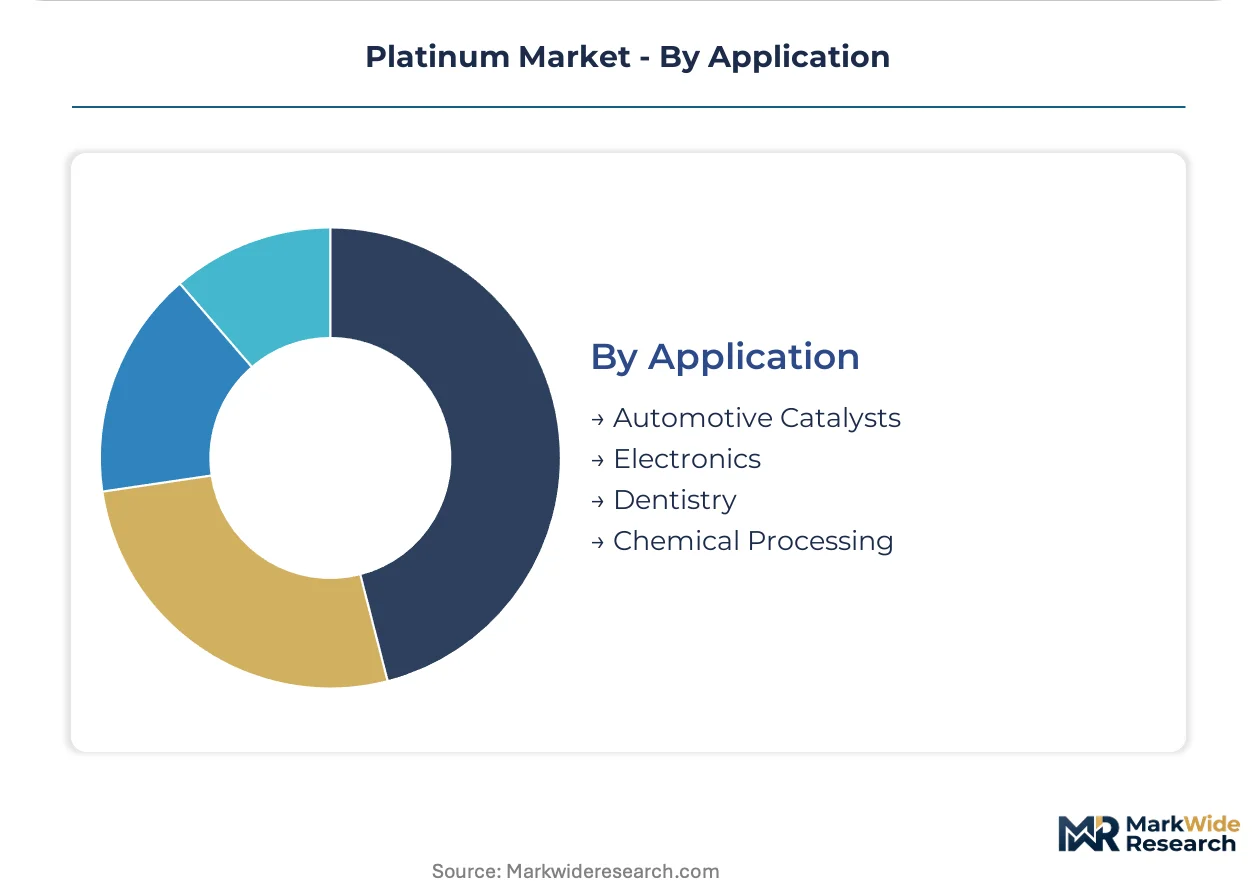
- Automotive Catalysts:Gasoline particulate filters and diesel oxidation catalysts consume platinum in washcoat formulations. EPA Tier 3 mandates in the United States force minimum loadings that sustain offtake despite thrifting pressure.
- Electronics:Hard disk drive coatings, sensor electrodes, and fuel cell membranes demand high-purity platinum in thin-film and powder forms. Japanese electronics manufacturers drive specifications for sputtering targets.
- Dentistry:Alloys for crowns, bridges, and implants leverage biocompatibility and corrosion resistance. German and Swiss dental laboratories specify platinum-based frameworks for precision fit.
- Chemical Processing:Naphtha reforming, silicone production, and nitric acid manufacturing rely on platinum catalysts. China's coastal petrochemical complexes dominate reforming catalyst demand.
Automotive Catalysts leads on scale; Electronics leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bushveld Complex in South Africa concentrates primary platinum mining, yet downstream fabrication and hydrogen catalyst demand are dispersing across industrial clusters in Germany, China, Japan, and the United States.
South Africa
Underground mining in the Western and Eastern Limbs supplies over 70% of global concentrate, though Eskom grid instability and labor stoppages disrupt throughput. The Department of Mineral Resources and Energy licensing frameworks shape export timing. Smelting complexes around Rustenburg and Polokwane process ore into refined metal for automotive catalyst manufacturers.
China
Petrochemical reforming catalyst demand concentrates in coastal refineries at Ningbo, Dalian, and Shanghai where naphtha processing for aromatics consumes platinum sponge. MIIT industrial policy directs hydrogen electrolyzer manufacturing subsidies toward proton exchange membrane technology. The Yangtze River Delta cluster hosts catalyst coating operations serving domestic fuel cell vehicle deployment targets.
Germany
Electrolyzer OEMs in the Ruhr region and Bavaria specify platinum-ruthenium catalyst formulations for alkaline-resistant coatings. EU Green Deal hydrogen subsidies accelerate renewable hydrogen production capacity builds. Industrial gas suppliers in Cologne and Frankfurt am Main negotiate five-year offtake contracts with integrated miners for electrolyzer manufacturing feedstock.
United States
EPA Tier 3 tailpipe mandates force gasoline particulate filter loadings that sustain platinum demand despite thrifting pressure elsewhere. Automotive catalyst fabricators in Michigan and Ohio maintain minimum metal specifications for light-duty vehicle compliance. Recycling networks across the Midwest capture spent substrate value from end-of-life vehicles.
Japan
Electronics manufacturers in Tokyo and Osaka drive specifications for high-purity platinum sputtering targets in hard disk drive and sensor applications. METI hydrogen infrastructure roadmaps align electrolyzer procurement with domestic fuel cell vehicle deployment. Trading houses in Tokyo secure long-term supply commitments for energy infrastructure projects.
Platinum Market Key Industry Players
Global majors compete with regional champions across concentrate supply and recycling arbitrage, producing a tiered structure where integrated miners, mid-tier developers, and recycling specialists occupy distinct margin pools. Anglo American plc and Sibanye Stillwater Limited anchor the integrated tier through Bushveld mining assets and North American recycling networks respectively. Impala Platinum Holdings Limited exemplifies smelting-dominant positioning. Strategic moves concentrate on multi-source concentrate procurement and long-term offtake contracting with hydrogen project developers.
Within the integrated mining tier, Anglo American plc, Sibanye Stillwater Limited, and Impala Platinum Holdings Limited represent the primary archetypes of upstream control. Anglo American plc occupies a position defined by captive Bushveld orebody access. Sibanye Stillwater Limited exemplifies geographic diversification through primary and recycled feedstock combination. Impala Platinum Holdings Limited anchors smelting capacity concentration in the Western Limb. These three structures illustrate how concentrate purity guarantees and delivery schedule reliability concentrate pricing power with miners who command integrated operations.
| Leading Market Players |
|---|
| Valterra Platinum Ltd. |
| Eastern Platinum Ltd. |
| Anglo American plc |
| Panther Metals |
| Zimplats Holdings Ltd. |
| Sibanye Stillwater Limited |
| Platinum Group Metals Ltd. |
| Coeur Mining |
| Impala Platinum Holdings Limited |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers in South Africa anchor upstream concentrate supply, translating Bushveld orebody control into pricing discipline that downstream refiners absorb through long-term offtake premiums. This ownership pattern concentrates margin capture with integrated miners who dictate assay terms and delivery schedules to automotive catalyst fabricators in Germany, Japan, and the United States.
Pricing Analysis
Input-cost pass-through from concentrate to refined metal operates through contract-based long-term offtake structures rather than spot markets. Price differentiation hinges on concentrate purity guarantees and delivery schedule reliability, with integrated miners commanding premiums over recycling feedstock suppliers. Cost compression in chemical-grade sponge is intensifying because thrifting pressures in automotive applications are displacing volume into industrial channels. Automotive catalyst producers exhibit the highest price sensitivity due to thrifting mandates, while hydrogen electrolyzer developers accept premium pricing for guaranteed supply security.
Supply Chain Analysis
Direct-to-automaker channels handle hyperscale catalyst demand from Tier 1 suppliers in Michigan, Ohio, and Bavaria. Geographic supply concentrates in South Africa, Russia, and Zimbabwe for primary concentrate, with North American and European recycling networks providing secondary feedstock. Raw material dependencies center on Bushveld orebody access, sulfuric acid for leaching circuits, and metallurgical coke for smelting reduction. Single-source vulnerability from Eskom grid instability in South Africa disrupts concentrate throughput timing. Distribution runs through integrated miner-smelter-refiner complexes that ship ingot and sponge to catalyst coaters in Germany, China, and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The platinum market functions as a stable compounder where emissions regulation tightening provides recurrent demand floor support regardless of automotive cycle volatility.
For Market Incumbents: Anticipate palladium substitution reversals in gasoline particulate filters by maintaining flexible smelting capacity that can absorb platinum-rich reforming catalyst returns from China's petrochemical sector. Defensive consolidation through captive recycling network expansion in North America offsets Bushveld supply disruption risk. Backward integration into spent automotive catalyst collection secures feedstock arbitrage margins that primary concentrate shortages amplify.
For New Entrants and Emerging Players: Launch via hydrogen electrolyzer catalyst coating partnerships with German and Japanese OEMs seeking non-integrated supply alternatives to Anglo American and Impala Platinum. White-space targets concentrate in proton exchange membrane electrolyzer manufacturing where five-year offtake contract structures favor new suppliers with purity guarantees. The most penetrable segment is European renewable hydrogen project developers facing procurement bottlenecks from incumbent allocation constraints.
For Investors and Strategic Acquirers: Industrial gas suppliers and German utility consortia are the most active acquirers in this space, securing captive catalyst supply for electrolyzer manufacturing scale-up. Long-term viability rests on hydrogen economy infrastructure buildout sustaining demand growth independent of automotive cycle peaks. Acquisition target archetypes include North American automotive catalyst recyclers with established collection networks and assay verification capabilities. The signal to watch is EU Green Deal hydrogen subsidy disbursement timing as inflection indicator for electrolyzer manufacturing capacity commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Japanese trading houses secure five-year platinum commitments from Bushveld miners for electrolyzer feedstock. |
| Backward Integration | Recycling specialists acquire spent catalyst collection networks to capture primary concentrate shortage arbitrage. |
| Capacity Expansion | Smelter furnace rebuilds at Rustenburg and Polokwane concentrate maintenance windows that disrupt throughput. |
| Joint Venture | German electrolyzer OEMs partner with catalyst coaters to localize platinum-ruthenium formulation production. |
| Green Certification Program | EU F-Gas Regulation phase-down schedules redirect fluorochemical production toward platinum-catalyzed alternative precursors. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mining operations executives, automotive catalyst procurement managers, hydrogen project developers, and precious metals trading specialists with secondary validation. Secondary sources included SEC 10-K filings from integrated miners, South African Department of Mineral Resources and Energy licensing records, EPA Tier 3 compliance documentation, EU Green Deal hydrogen subsidy disbursement reports, and customs trade data for platinum concentrate flows. Bottom-up segmentation modeling and top-down macroeconomic anchoring provided cross-verification for volume and value estimates.
Historical reference periods spanning the pre-pandemic baseline through recent supply disruption episodes anchored the forecast window calibration. The analytical framework modeled segmentation across physical form, purity grade, end-use application, and regional demand cluster throughout the projection horizon. CAGRs were derived from regression analysis against automotive production trajectories, hydrogen infrastructure deployment schedules, and petrochemical capacity expansion timelines. Industry-specific forecast inputs included Eskom grid reliability indices and EPA emissions standard phase-in schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended South African labor stoppage scenarios or accelerated palladium substitution reversals. Forecasts reflect assumptions regarding Bushveld mining cost structures, Chinese petrochemical reforming catalyst replacement cycles, and European electrolyzer manufacturing capacity ramps. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Chromium Market
Metals
Electrolytic Manganese Metal Market
Metals
Zinc Ingots Market
Metals
Crude Steel Market
Metals
Copper Chromium Black Market
Metals
Ultrafine Tungsten Wire for Medical Applications Market
Metals
Medical Metal Tubing Market
Metals
Stainless Steel 400 Series Market
Metals
US Copper Scrap Market
Metals
Wear Steel Plate Market
Metals
Global Ultra-Low Alpha Metal Market
Metals
Copper Wire Market
Metals
North America Grain Oriented Electrical Steel Market
Metals
Zinc Dust Market
Metals
Titanium Market
Metals
Aluminum Welding Wires Market