
 Welding Consumables Market | 2026-2036
Welding Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Consumables Market Intelligence
The EU Green Deal's industrial decarbonization mandates is broadening the addressable market for low-carbon welding consumables across European energy and transport infrastructure. Lincoln Electric Holdings, Inc. leverages its vertically integrated electrode production to secure long-term supply agreements with North American heavy fabricators. ESAB Corporation anchors its competitive position through deep R&D investment in automation-compatible wire formulations. Kobe Steel, Ltd. dominates premium solid wire segments serving Japanese automotive and precision machinery OEMs.
Welding consumables encompass electrodes, filler wires, fluxes, and shielding gases engineered to metallurgically bond base metals under thermal stress, with compositions typically specifying tensile strength ratings, alloy percentages, and moisture-resistant coatings for storage stability. Their primary purpose centers on enabling structural integrity in load-bearing assemblies across heavy industry. Solid wire leads volume share in automated MIG applications where repeatability and deposition efficiency command premium positioning, while flux cored wire captures the fastest expansion in field construction and shipyard environments demanding all-position versatility. Brazing alloys and soldering materials occupy specialized margin pools in electronics miniaturization and HVAC joint fabrication.
OSHA's permissible exposure limits for hexavalent chromium and manganese fumes directly shape product formulation requirements and respiratory protection bundling in US fabrication shops. The EU's CE marking under the Machinery Directive and REACH substance restrictions constrain material compositions imported into European supply chains. China's GB standards and MEE enforcement on industrial emissions further differentiate compliant domestic producers from import competitors. Stakeholders must monitor how tightening particulate thresholds across these jurisdictions reshape R&D budgets and regional manufacturing footprints.
Market Dynamics
Offshore wind farm construction is accelerating procurement of specialized flux cored wire and submerged arc consumables, while tightening emissions frameworks across Germany, South Korea, and the EU are compressing allowable fume thresholds and reshaping formulation R&D priorities.
Growth Catalysts
- EU F-Gas Regulation:Tightening specifications for low-fume welding materials are expanding addressable markets for compliant consumables across European energy infrastructure.
- Flux cored wire:All-position versatility is capturing the fastest expansion in field construction and shipyard environments demanding operational flexibility.
- China's coastal provinces:Shipbuilding concentration in Jiangsu, Zhejiang, and Shandong is driving bulk procurement of automated MIG wire and submerged arc fluxes.
Market Restraints
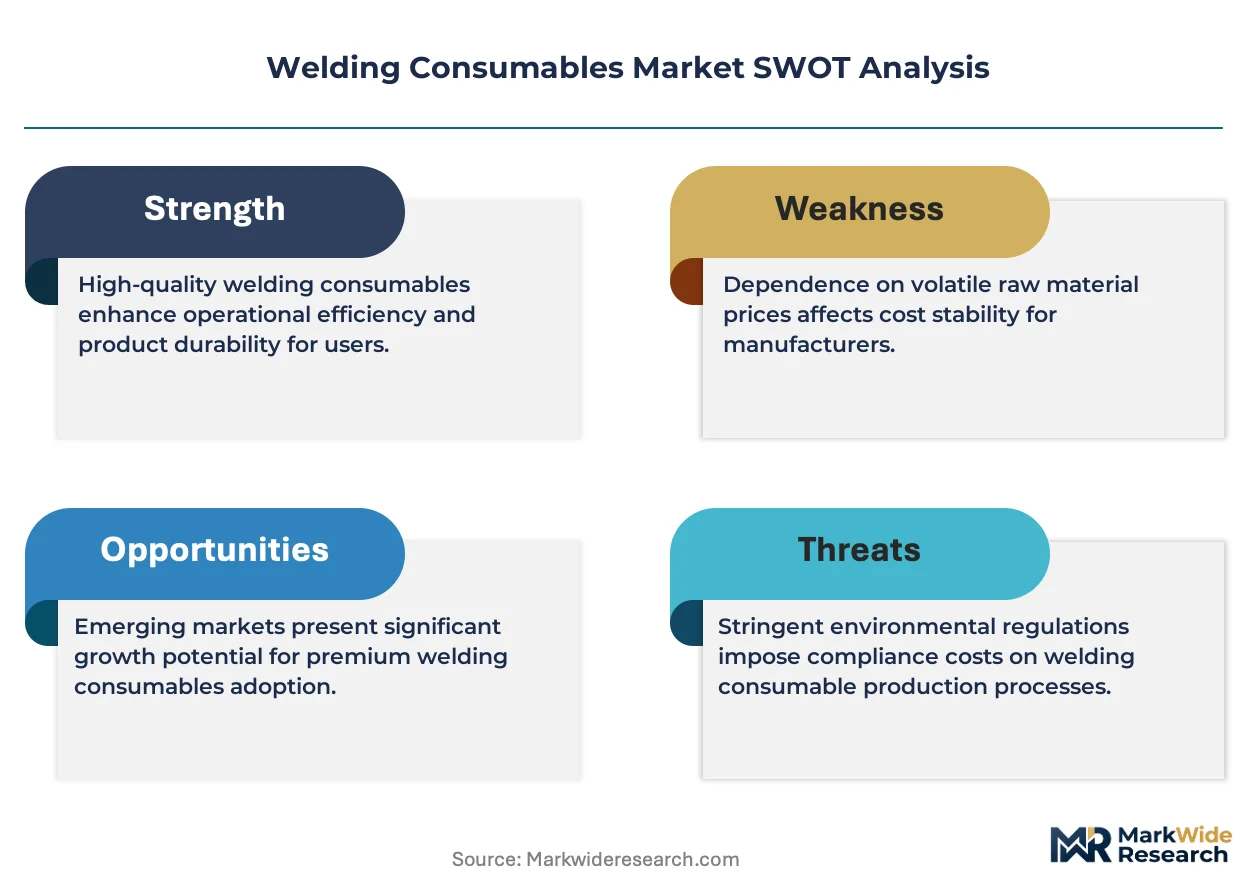
- Alloy input volatility:Nickel and molybdenum price swings destabilize cost structures for premium solid wire formulations serving precision machinery OEMs.
- Supply concentration:Premium electrode coating materials cluster among a limited set of Japanese and European specialty chemical suppliers.
- REACH substance restrictions:Compliance complexity for imported consumables creates friction in European supply chains, favoring domestic producers with established certification pathways.
Strategic Opportunities
- India's western industrial corridor:Underpenetrated fabrication capacity in Gujarat and Maharashtra offers white space for automated wire feeding systems and bundled consumable-service packages.
- EU Green Deal industrial decarbonization mandates:Low-carbon welding consumables are gaining preferential procurement status across European transport and energy infrastructure tenders.
- Robotics-wire convergence:Collaborative robot welding cells are creating demand for precision-engineered wire formulations optimized for adaptive torch positioning and real-time parameter adjustment.
Industry Challenges
- Certified welder scarcity:Pipeline construction and nuclear fabrication face acute shortages of operators qualified to ASME Section IX and API 1104 standards.
- Legacy equipment integration:Retrofitting digital wire monitoring systems onto existing submerged arc setups demands capital outlays that mid-sized fabricators struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Consumables Market |
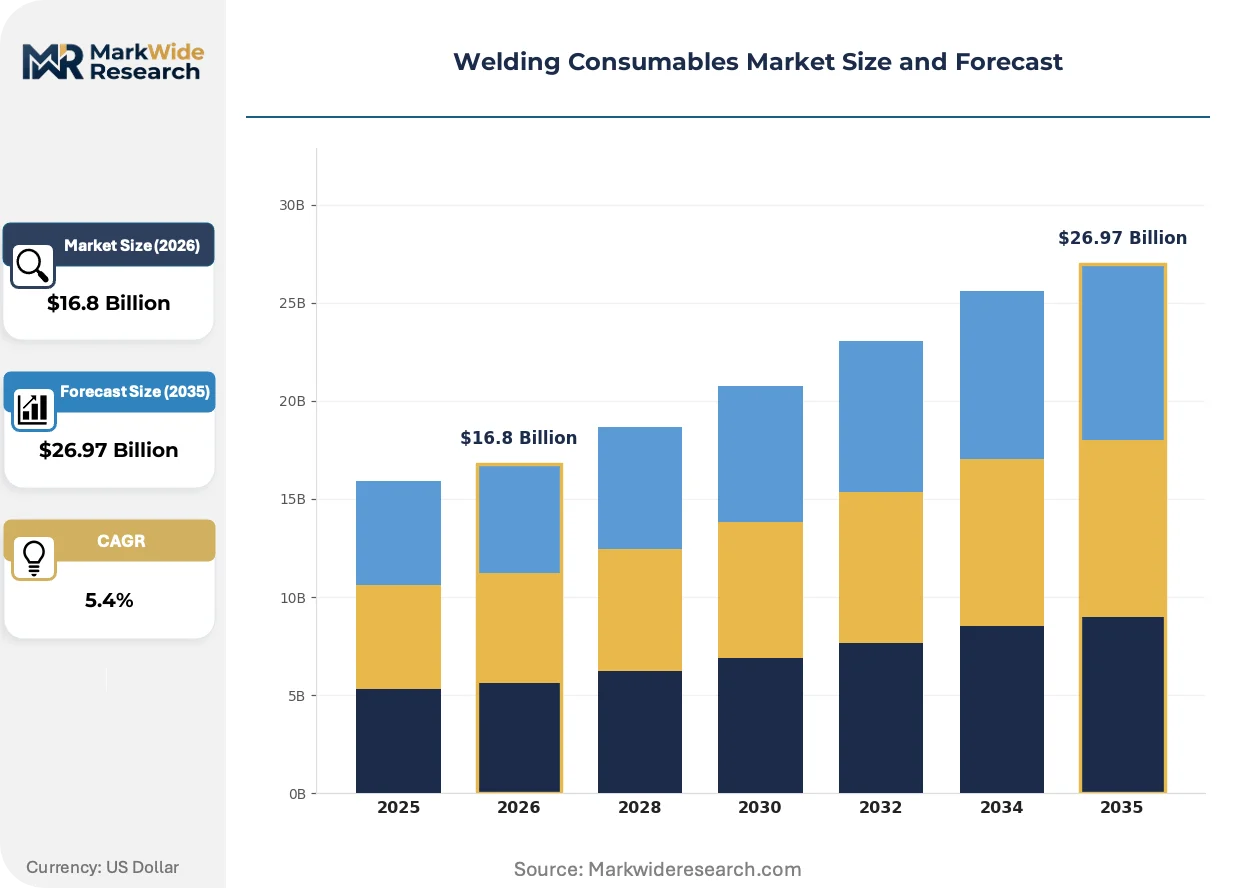
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $26.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrodes, Flux Cored Wire, Solid Wire, Brazing Alloys, Soldering Materials Welding Process: MIG, TIG, Stick, Submerged Arc, Plasma Arc, Resistance End Use Industry: Shipbuilding, Aerospace Manufacturing, Energy Production, Construction Firms, Equipment Fabrication Packaging Type: Spool, Coil, Drum, Box, Carton |
| Companies Covered | Lincoln Electric Holdings, Inc., ESAB Corporation, Kobe Steel, Ltd., Illinois Tool Works Inc., Panasonic Corporation, Fronius International GmbH, voestalpine AG, Hyundai Welding Co., Ltd., Air Liquide S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Consumables Market Strategic Shifts & Innovations
Formulation chemistry, regulatory compliance architectures, and procurement modalities are undergoing simultaneous recalibration as end-users prioritize fume reduction, deposition efficiency, and total cost-per-joint optimization over standalone consumable pricing.
Metal-cored wire formulations are decentralizing deposition control from centralized welding stations to portable field units. Shipyards in South Korea and offshore contractors in the North Sea are adopting these wires for out-of-position work previously requiring stick electrodes. The shift is compressing demand for traditional covered electrodes in heavy fabrication while expanding the addressable market for semi-automated processes in confined spaces.
The EU F-Gas Regulation and Germany's TA Luft technical instructions on air quality are mandating hexavalent chromium exposure reductions below 0.5 micrograms per cubic meter. Fabrication shops across Bavaria and Baden-Württemberg are retrofitting ventilation systems and specifying low-chromium wire grades. Consumable suppliers with pre-certified low-fume portfolios are securing sole-source agreements with automotive tier-one suppliers facing OEM audit pressure.
Consolidated procurement through integrated service contracts is displacing spot purchasing of individual consumable SKUs. Heavy fabricators in Texas and Alberta are contracting welding management providers for guaranteed deposition rates and joint quality outcomes rather than buying wire and flux separately. The model concentrates volume with suppliers capable of predictive logistics and on-site technical support, marginalizing distributors without engineering capabilities.
Welding Consumables Market Segmentation
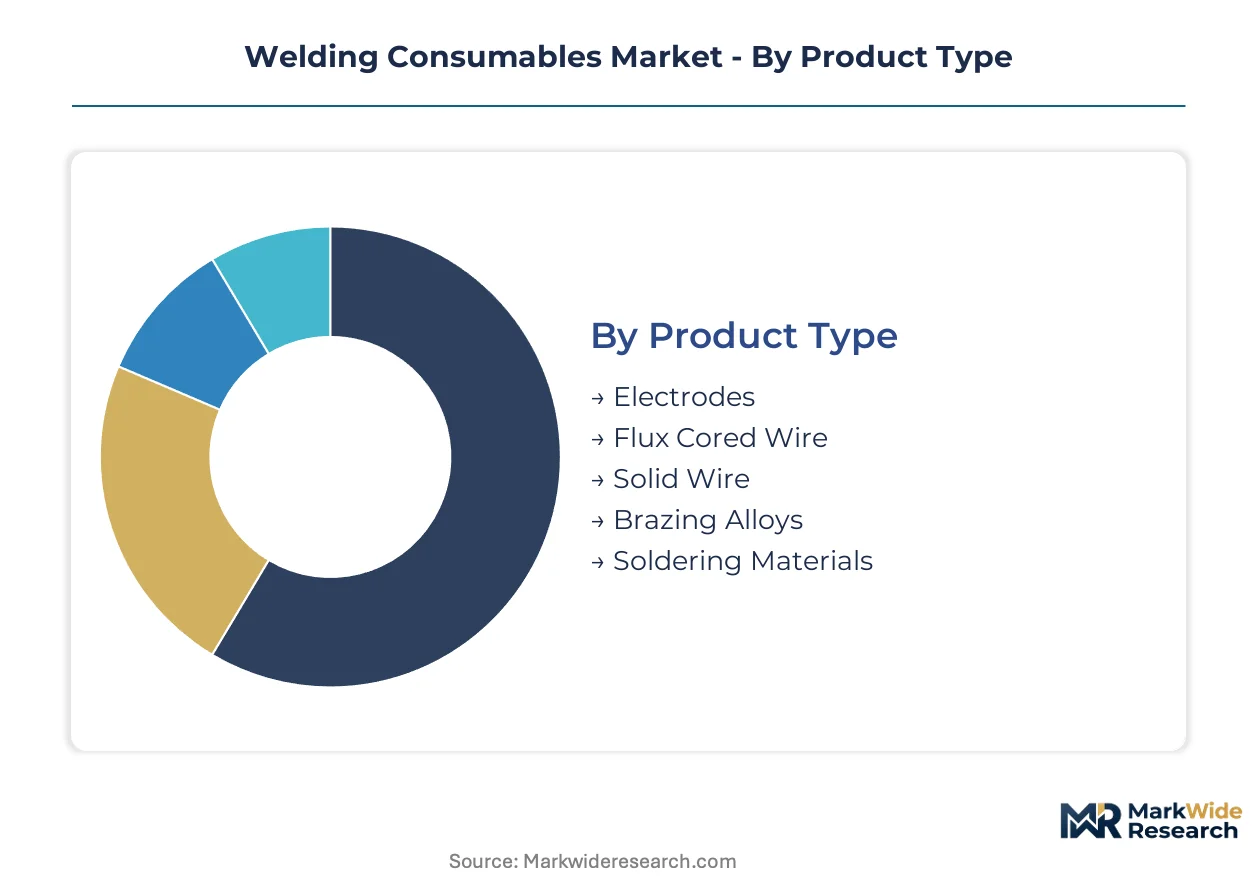
Welding consumables segmentation reveals how technical specifications, process compatibility, and logistics requirements fragment procurement decisions across heavy industry. Buyers prioritize deposition efficiency, fume characteristics, and packaging automation compatibility over unit cost alone.
Product Type:
Buyers select consumable formats based on automation level, positional flexibility requirements, and base metal metallurgy rather than price per kilogram.
- Solid Wire:Continuous copper-coated steel or aluminum alloy feedstock engineered for automated MIG systems. Shipbuilders in China's Jiangsu and Shandong provinces specify ER70S-6 grades for robotic panel lines where repeatability governs throughput economics.
- Flux Cored Wire:Tubular construction with mineral flux cores enables all-position welding without external shielding gas. Offshore wind contractors in the North Sea and South Korean shipyards deploy self-shielded formulations for field erection where portability trumps deposition rates.
- Electrodes:Mineral-coated stick electrodes serve maintenance operations and constrained-access repairs. E6010 and E7018 classifications dominate pipeline construction requiring deep penetration or low-hydrogen crack resistance.
- Brazing Alloys:Silver-copper-zinc compositions join dissimilar metals in HVAC fabrication and automotive heat exchanger assembly. JIS BCuP and AWS BAg specifications govern premium joint integrity applications.
- Soldering Materials:Tin-lead and lead-free alloys service electronics miniaturization and plumbing infrastructure. REACH compliance has displaced traditional compositions in European supply chains.
Solid wire leads on scale; flux cored wire leads on momentum.
Welding Process:
Process selection locks buyers into specific consumable formats and determines capital equipment requirements, operator skill thresholds, and joint quality repeatability.
- MIG:Gas metal arc welding consumes solid wire and metal-cored formulations in high-volume automated cells. Automotive OEMs in Germany's Baden-Württemberg region mandate pulsed MIG for aluminum body-in-white assembly.
- TIG:Tungsten inert gas precision demands bare filler rods and strict shielding gas purity. Aerospace fabricators serving Airbus and Boeing supply chains specify ER4043 and ER5356 aluminum grades for critical structural welds.
- Stick:Shielded metal arc welding retains dominance in field construction and repair where power source portability matters. API 1104 pipeline standards mandate low-hydrogen electrode classifications for high-stress transmission lines.
- Submerged Arc:Granular flux and solid wire combinations deliver highest deposition rates in flat-position heavy fabrication. Wind tower manufacturers in Texas and Alberta specify tandem wire configurations for thick-section monopile welding.
- Plasma Arc:Constricted arc technology cuts and welds exotic alloys in precision machinery OEM supply chains. Limited consumable diversity reflects concentrated application scope.
- Resistance:Spot and seam welding consumes copper alloy electrodes in automotive stamping and appliance manufacturing. Electrode cap replacement cycles dominate operational cost structures.
Stick welding retains widest installed base; submerged arc commands highest throughput intensity.
End Use Industry:
Industry-specific certification requirements and joint performance standards dictate consumable grade selection more than raw material costs.
- Shipbuilding:Classification society rules from Lloyd's Register and DNV mandate consumable approval for marine structural grades. South Korean yards in Geoje and Ulsan specify high-tensile wire formulations for LNG carrier membrane tank construction.
- Energy Production:Pressure vessel and pipeline specifications govern consumable selection across fossil and renewable generation. ASME Section IX qualification requirements restrict supplier pools for nuclear fabrication.
- Construction Firms:Structural steel erection consumes bulk electrodes and flux cored wire for field welding. India's western industrial corridor in Gujarat and Maharashtra shows fastest expansion in automated beam assembly.
- Aerospace Manufacturing:NADCAP and OEM-specific approvals constrain consumable sourcing to qualified suppliers. Titanium and nickel superalloy filler materials command substantial price premiums.
- Equipment Fabrication:General machinery OEMs balance deposition efficiency against inventory simplification. Mid-tier fabricators consolidate on multi-purpose wire grades to reduce SKU complexity.
Shipbuilding concentrates procurement volume; energy production imposes tightest qualification barriers.
Packaging Type:
Packaging format selection determines feeding system compatibility, moisture protection, and logistics economics across distribution networks.
- Spool:Precision-wound wire on plastic or fiber cores feeds semi-automatic and robotic systems. 15kg and 20kg spool dimensions dominate European automotive supplier shops.
- Drum:Bulk 250kg to 500kg containers minimize changeover downtime in high-volume automated cells. Heavy fabricators in Texas specify drum packaging for submerged arc installations.
- Coil:Large-format wire supply feeds dedicated push-pull systems in shipyard panel lines. Korean yards specify rust-inhibiting coatings for coastal storage conditions.
- Box:Electrode cartons with hermetic sealing preserve low-hydrogen coating integrity. Moisture-resistant packaging commands premium positioning in humid climates.
- Carton:Standard cardboard enclosures service low-volume maintenance and repair operations. Limited protection necessitates rapid consumption cycles.
Drum packaging dominates automated throughput; spool formats retain widest application flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Welding consumables production first achieved industrial scale in early 20th century United States and Germany, establishing the technical standards and alloy formulations that still govern global specifications. Today's demand geography reflects this legacy while shifting toward Asia-Pacific shipbuilding and energy infrastructure clusters.
United States
Pipeline construction and offshore wind fabrication drive consumable demand across the Gulf Coast and Great Lakes regions. OSHA hexavalent chromium exposure limits constrain formulation choices in Texas fabrication shops. Houston-area heavy fabricators specify low-fume wire grades for petrochemical and renewable energy infrastructure projects.
China
Jiangsu, Zhejiang, and Shandong provinces concentrate shipbuilding procurement of automated MIG wire and submerged arc fluxes. GB standards and MEE industrial emissions enforcement differentiate compliant domestic producers from import competitors. Qingdao and Nantong shipyards specify high-tensile formulations for LNG carrier and container vessel construction.
Germany
Automotive OEMs in Baden-Württemberg mandate pulsed MIG processes for aluminum body-in-white assembly. TA Luft technical instructions and EU F-Gas Regulation compress allowable fume thresholds below 0.5 micrograms per cubic meter. Bavarian fabrication shops retrofit ventilation systems and specify low-chromium wire grades under OEM audit pressure.
India
Gujarat and Maharashtra industrial corridors show fastest expansion in automated beam assembly and structural steel erection. BIS certification requirements and PLI scheme incentives favor domestic consumable manufacturers with established quality systems. Mundra and Hazira port zones concentrate fabrication capacity serving petrochemical and renewable energy projects.
South Korea
Geoje and Ulsan shipyards specify high-tensile wire formulations for LNG carrier membrane tank and offshore platform construction. MFDS industrial safety frameworks and environmental regulations align with EU fume reduction standards. Busan-Ulsan coastal cluster drives premium solid wire demand for precision machinery OEM supply chains.
Welding Consumables Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation complexity and certification depth, with automated-system compatibility commanding price premiums over standard grades. The vendor base spans integrated metals producers, specialized consumable manufacturers, and industrial gas suppliers with welding portfolios. Three archetypes dominate: vertically integrated steelmakers with captive wire production, dedicated welding technology specialists with deep R&D pipelines, and diversified industrial conglomerates bundling consumables with equipment and gas supply. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing long-term supply agreements with heavy fabricators and shipbuilders.
Within the integrated steelmaker tier, voestalpine AG and Kobe Steel, Ltd. occupy positions anchored by metallurgical expertise and captive alloy supply. Among dedicated welding specialists, Lincoln Electric Holdings, Inc. and ESAB Corporation exemplify archetypes built on equipment-consumable integration and formulation R&D depth. These named entities represent competitive positioning patterns rather than exhaustive market coverage, with each exemplifying distinct strategic approaches to certification depth, geographic footprint, and customer technical support intensity.
| Leading Market Players |
|---|
| Lincoln Electric Holdings, Inc. |
| ESAB Corporation |
| Kobe Steel, Ltd. |
| Illinois Tool Works Inc. |
| Panasonic Corporation |
| Fronius International GmbH |
| voestalpine AG |
| Hyundai Welding Co., Ltd. |
| Air Liquide S.A. |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between ASME-qualified consumables and commodity-grade electrodes splits pricing power across parallel supply channels. Premium formulations command sole-source positioning in nuclear and aerospace fabrication, while standard grades compete on logistics efficiency and volume rebates in structural steel erection.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement negotiations, with ASME Section IX certification and DNV marine approval serving as the primary price differentiation drivers. Cost compression in standard-grade solid wire is intensifying because Chinese producers with captive steel supply are expanding export volumes into Southeast Asian fabrication markets. Construction firms in India's western corridor exhibit highest price sensitivity, while automotive tier-one suppliers in Germany's Baden-Württemberg region prioritize fume reduction specifications over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and European specialty chemical suppliers controlling premium electrode coating formulations. Raw material sourcing draws from nickel and molybdenum mining clusters in Indonesia and Chile, with refined alloy production concentrating in China, Japan, and Germany. Tariff exposure on Chinese wire imports into the United States and European Union creates margin volatility for distributors without regional manufacturing footprints. Distribution runs through welding equipment OEMs, industrial gas suppliers, and specialized consumable distributors serving fabrication shops and shipyards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where fume reduction compliance costs in Germany's TA Luft-regulated fabrication shops run substantially higher than India's BIS certification requirements, creating margin expansion opportunities for producers with dual-qualification capabilities.
For Market Incumbents: Lock in long-term supply agreements with North American heavy fabricators facing certified welder scarcity and escalating OSHA hexavalent chromium enforcement. Prioritize backward integration into rutile and cellulose coating materials to reduce dependency on Japanese specialty chemical suppliers. Defend margin position by embedding predictive logistics and on-site technical support into bundled service contracts that spot-purchasing distributors cannot replicate.
For New Entrants and Emerging Players: A 40-60% price-point gap between premium ASME-qualified electrodes and economy-grade construction wire creates entry space for mid-tier players offering pre-certified low-fume formulations at standard-grade economics. Target India's Gujarat and Maharashtra industrial corridors where automated beam assembly expansion outpaces domestic consumable supply. Penetrate through equipment-consumable bundling partnerships with Korean and Chinese welding system OEMs seeking local content qualification.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized fabricators struggle to justify capital outlays for digital wire monitoring retrofits on legacy submerged arc installations. Frame long-term viability around automation-consumable convergence and regulatory compliance depth rather than volume scale alone. Acquisition targets should demonstrate established certification pathways into EU F-Gas Regulation and REACH-compliant supply chains. Watch for inflection where robotics-wire integration contracts exceed 30% of shipyard procurement value.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Materials | Captive rutile supply insulates margin from Japanese specialty chemical concentration. |
| Low-Fume Formulation Certification | Pre-certified portfolios secure sole-source agreements under EU F-Gas Regulation enforcement. |
| Long-term Supply Agreement | Guaranteed deposition rate contracts displace spot purchasing in Texas and Alberta fabrication. |
| Robotics-Wire Convergence R&D | Precision formulations for adaptive torch positioning capture collaborative robot welding cell demand. |
| Geographic Manufacturing Footprint | Regional production in India and Southeast Asia reduces tariff exposure and logistics cost. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with welding consumable procurement managers, shipyard fabrication engineers, automotive tier-one supplier quality directors, and industrial gas distribution executives with secondary validation. Trade data from customs authorities, SEC filings from Lincoln Electric and ESAB, shipbuilding production databases from Lloyd's Register and DNV, and EU ECHA REACH substance restriction updates anchored the quantitative foundation. Bottom-up volume modeling across product types and end-use industries triangulated against top-down macroeconomic indicators.
Segment-weighting approaches applied differential growth assumptions to flux cored wire versus solid wire, shipbuilding versus energy infrastructure end uses, and automated versus manual welding processes across the projection horizon. CAGRs derived from historical shipment data, capacity expansion announcements, and regulatory compliance timelines modeled through Monte Carlo simulation. Forecast inputs incorporated nickel and molybdenum price volatility indices, shipbuilding order book projections from Clarksons, and offshore wind installation capacity pipelines from 4C Offshore.
Caveats apply where alloy input price spikes, sudden regulatory threshold tightening, or trade policy shifts could materially shift the outlook. Forecasts reflect assumptions about continued automation adoption, stable certification requirements, and no major supply chain disruptions from geopolitical conflict. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
High Modulus Polyethylene Rope Market
Industrial Materials
Felt Gasket Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Modified Wood Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Global Graphite Electrodes Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
High Purity Quartz Market
Industrial Materials
Global Industrial Chain Market
Industrial Materials
North America Machined Seals Market
Industrial Materials
Shock Mat Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Stainless Steel Cable Ties Market