
 High Purity Tungsten Market | 2026-2036
High Purity Tungsten Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Tungsten Market Insights
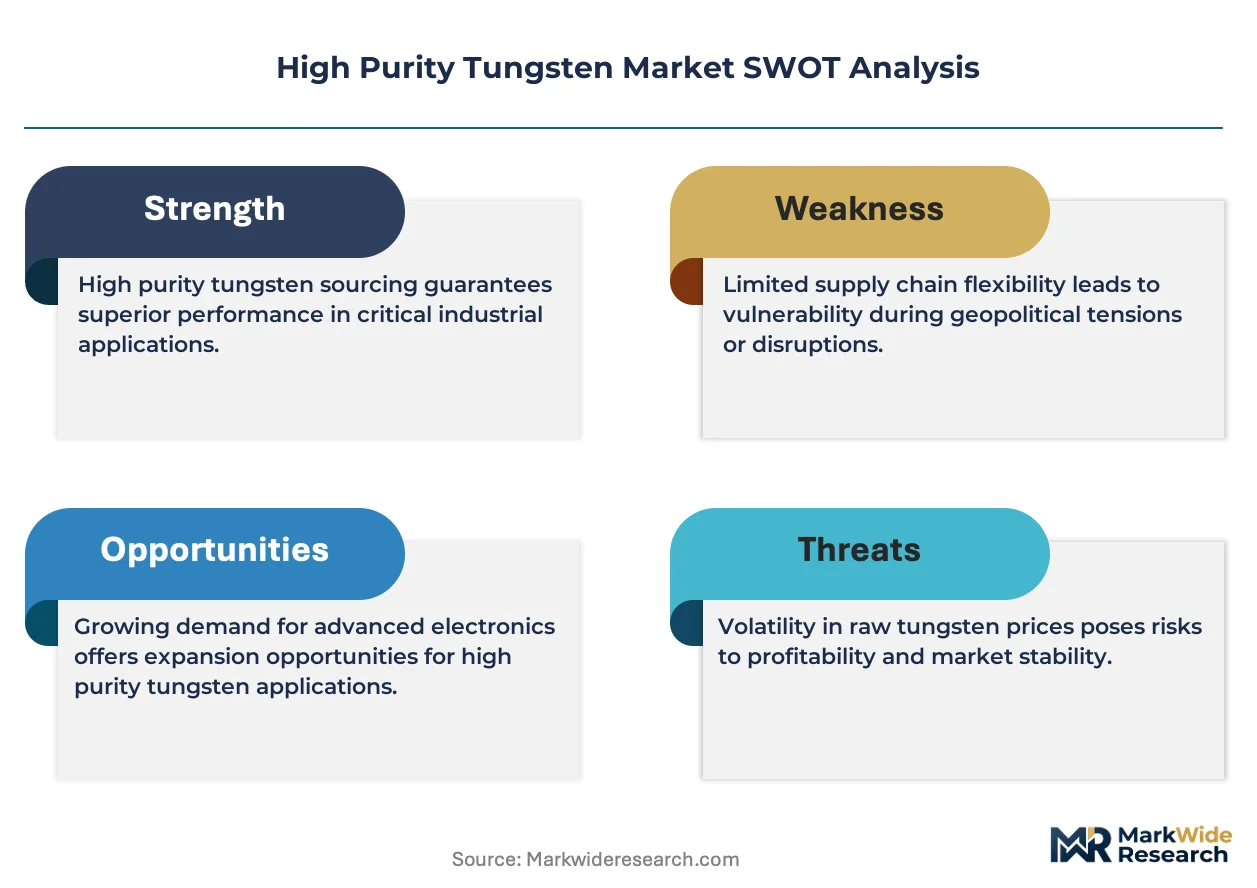
Atomic layer deposition compatibility is narrowing the supplier base for semiconductor-grade tungsten precursors. Xiamen Tungsten Company leverages integrated mining-to-powder operations to secure feedstock consistency. H.C. Starck GmbH anchors European supply through specialized reduction and sintering capabilities. Plansee SE differentiates via vertical control over refractory metal fabrication for ion implantation components.
High purity tungsten denotes material exceeding 99.95% elemental concentration, typically produced through hydrogen reduction of ammonium paratungstate followed by electron beam or vacuum arc melting to eliminate interstitial impurities. The metal's exceptional thermal stability and low vapor pressure suit it for plasma-facing components, radiation shielding, and high-temperature crucibles. Spherical powder commands premium positioning as additive manufacturing qualification expands across aerospace and medical device sectors. Electronics end use leads volume absorption, driven by tungsten's function as gate fill material and interconnect barrier in sub-7 nanometer logic devices. Custom grade segmentation reveals ultra high purity as the fastest-expanding tier, propelled by extreme ultraviolet lithography source component requirements.
China's MIIT governs tungsten export quota allocations under national strategic mineral classifications, while REACH and RoHS frameworks in Europe restrict permissible impurity thresholds for electrical and electronic equipment applications. The US Department of Commerce maintains entity list controls affecting tungsten carbide and powder shipments to designated semiconductor fabrication facilities. Stakeholders must monitor evolving critical minerals partnership agreements between governments and assess dual sourcing viability against concentrated Chinese intermediate processing capacity.
Market Dynamics
Semiconductor lithography source component requirements are compressing supplier qualification timelines while China's MIIT export quota system on tungsten concentrates is forcing downstream fabricators to secure alternative reduction capacity outside mainland China.
Growth Catalysts
- Extreme ultraviolet lithography expansion:ASML's EUV source generation requires ultra-high-purity tungsten electrodes and collector mirrors, pulling material through South Korean and Taiwanese fabrication clusters at accelerated procurement cadences.
- REACH RoHS impurity thresholds:European electrical equipment standards are mandating lower interstitial content in tungsten interconnects, creating specification premiums for hydrogen-reduced powder meeting sub-50 ppm oxygen criteria.
- Additive manufacturing qualification:Aerospace propulsion OEMs are certifying spherical tungsten powder for directed energy deposition of radiation-shielded thruster components, opening volume absorption outside traditional subtractive machining.
Market Restraints
- Ammonium paratungstate concentrate volatility:APT pricing swings on London Metal Exchange benchmarks transmit directly to hydrogen-reduced powder cost structures, compressing margin visibility for downstream sintering operations.
- Intermediate processing concentration:Over 80 percent of tungsten oxide reduction capacity resides in Chinese smelters, exposing non-Chinese fabricators to MIIT export license delays and quota exhaustion risk.
- Molybdenum substitution in thermal management:Lower-purity molybdenum alloys are displacing tungsten in non-lithography heat sink applications where vapor pressure tolerance permits material downgrade.
Strategic Opportunities
- Indian PLI scheme for semiconductors:India's production-linked incentive framework for display and chip fabrication is attracting tungsten precursor suppliers to establish localized chemical vapor deposition material finishing.
- Plasma-facing component refresh cycles:ITER and successor fusion reactor programs are specifying tungsten divertor tiles with century-level replacement horizons, creating long-dated offtake contracts for vacuum-arc-melted billets.
- Dual carbon goal compliance services:Chinese tungsten miners are monetizing carbon-intensity certification for European buyers, converting MIIT-mandated emissions audits into supply chain differentiation premiums.
Industry Challenges
- Electron beam melting operator scarcity:Vacuum metallurgy technicians capable of maintaining 99.999% purity during skull melting are concentrated at legacy nuclear and aerospace suppliers, constraining capacity expansion timelines.
- Semiconductor customer qualification duration:Advanced node foundries require 18-to-24-month precursor validation cycles, freezing supplier switching and entrenching incumbents with existing ion implantation component approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Tungsten Market |
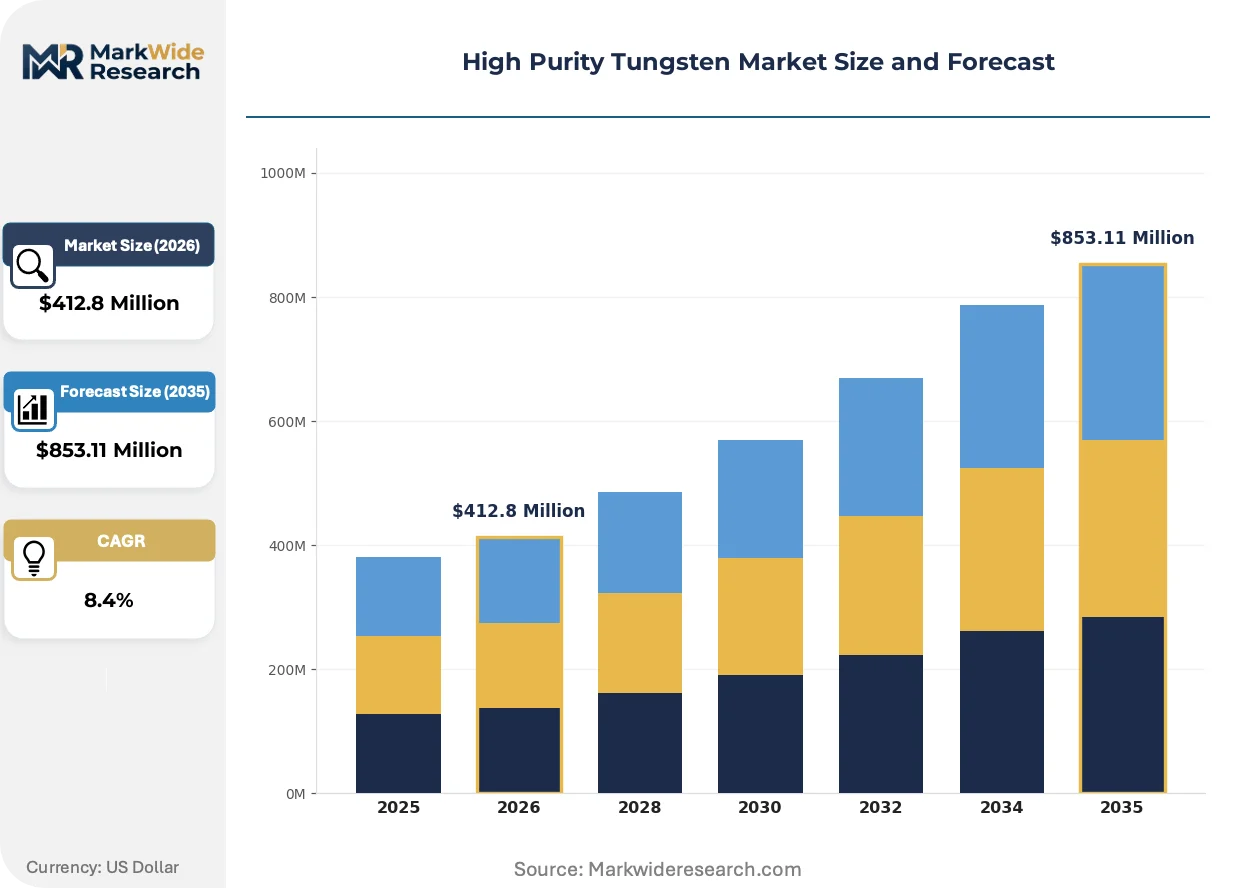
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $853.11 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wafers, Rods, Spherical Powder, Sheets End Use Industry: Aerospace, Electronics, Medical Devices, Defense Form: Solid, Powder, Alloy, Coating Custom Grade: Commercial Grade, Ultra High Purity, Research Grade, Specialty |
| Companies Covered | Xiamen Tungsten Company, China Minmetals Corporation, H.C. Starck GmbH, Japan New Metals Company, Wolfram Company JSC, Global Tungsten & Powders Corporation, Buffalo Tungsten Inc., Shaanxi Changlong Jiuzhou Metal Technology Co., Ltd., Plansee SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Tungsten Market Trends and Innovations
Plasma-facing component specifications and additive manufacturing feedstock requirements are converging to redefine purity certification protocols and spherical powder production economics across defense, energy, and electronics verticals.
Atomic layer deposition precursors based on tungsten hexacarbonyl and fluorinated organometallics are rendering obsolete traditional chemical vapor deposition tungsten silicide gate fill processes in sub-3 nanometer logic device manufacturing. Samsung Foundry and TSMC are qualifying these precursors for high-aspect-ratio contact fill, compressing thermal budget requirements and eliminating seam void defects that plagued previous-generation barrier deposition. The structural consequence is rendering obsolete horizontal furnace batch processing in favor of single-wafer spatial ALD tools.
China's MIIT is tightening tungsten concentrate export quota enforcement under national strategic mineral classifications, redirecting intermediate oxide flows toward domestic value-added processing. European fabricators dependent on Chinese APT feedstock are accelerating qualification of Russian and Vietnamese mine sources, though these alternatives lack integrated reduction capacity. The segment most affected is semiconductor-grade powder, where European sintering operations are absorbing 15-to-20 percent feedstock cost premiums to maintain REACH-compliant supply chains.
Consolidated procurement consortia among South Korean memory manufacturers are displacing spot-market tungsten bar purchases with five-year direct reduction agreements. SK Hynix and Samsung Electronics are jointly sourcing hydrogen-reduced powder from designated Japanese and Austrian smelters, bypassing traditional trader intermediaries that previously managed inventory risk. This concentration is most visible in Seoul and Suwon, where foundry procurement teams are co-locating supplier quality engineers to compress qualification cycle times for EUV source component materials.
High Purity Tungsten Market Segmentation
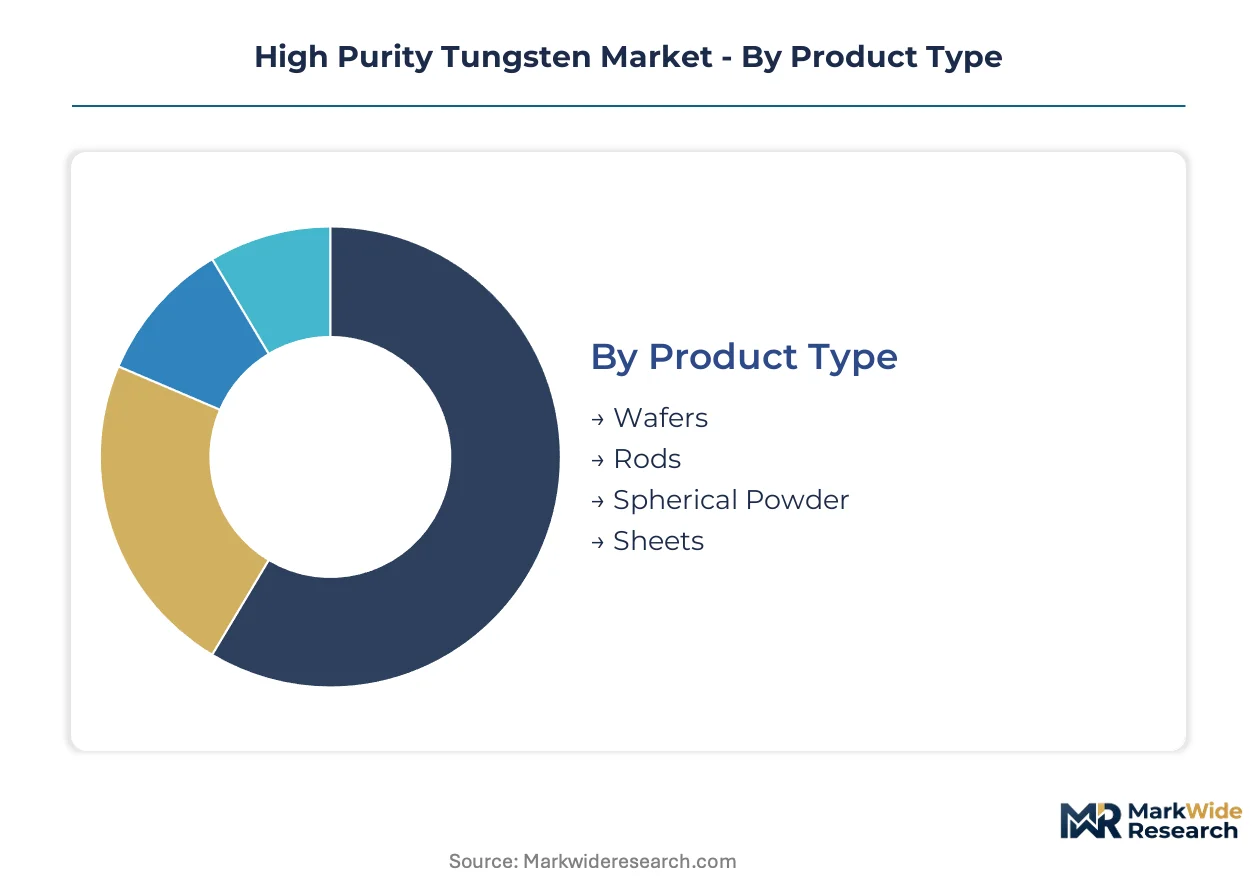
High purity tungsten procurement patterns diverge sharply across product geometries and purity tiers. Semiconductor lithography systems drive specifications for ultra-high-purity forms while additive manufacturing is reshaping powder metallurgy demand.
Product Type:
Cycle times vary dramatically: spherical powder turns over fastest as aerospace OEMs iterate qualification batches, while wafer inventories stretch across multi-year lithography source component programs.
- Wafers:These thin discs exceed 99.999% purity through vacuum arc remelting and serve as collector mirror substrates in EUV lithography systems. ASML's source generation roadmaps are pulling wafers through Taiwanese and South Korean fabrication clusters at extended contract horizons. Wafers dominate installed base. Spherical powder is where expansion concentrates.
- Spherical Powder:Gas-atomized or plasma-spheroidized particles meet 15-45 micron size distributions for directed energy deposition of radiation-shielded thruster components. Aerospace propulsion OEMs in the US and Germany are certifying this feedstock for Inconel-tungsten gradient structures, compressing traditional bar-to-part lead times. Spherical powder commands 40-60% premiums over angular morphology.
- Rods:Swaged and centerless-ground cylindrical stock serves ion implantation electrode applications where straightness tolerances reach 0.025 mm per meter.
- Sheets:Hot-rolled and cross-rolled plate provides radiation shielding for medical isotope production cassettes and fusion reactor port plugs.
Sheets anchor legacy defense and medical installed base. Spherical powder is climbing the fastest as additive manufacturing penetrates aerospace.
End Use Industry:
Margin structures stratify sharply: electronics commands specification premiums for sub-50 ppm oxygen content while defense absorbs long-dated contract volumes at cost-plus terms.
- Electronics:Sub-7 nanometer logic devices require tungsten gate fill and interconnect barrier layers with interstitial impurities below 10 ppm. Samsung Foundry and TSMC procurement teams are co-locating supplier quality engineers in Suwon and Hsinchu to compress 18-to-24-month precursor validation cycles. Electronics dominates installed base. Aerospace is where expansion concentrates.
- Aerospace:Plasma-facing thruster components and radiation-shielded propulsion assemblies specify vacuum-arc-melted billets with century-level replacement horizons. NASA and ESA programs are locking in five-year offtake agreements for directed energy deposition feedstock, bypassing spot-market volatility. REACH and RoHS compliance adds 12-18% certification overhead.
- Medical Devices:Tungsten-heavy alloy collimators and radiation shielding for gamma knife systems require biocompatibility testing under FDA 21 CFR Part 820 quality system regulations.
- Defense:Kinetic penetrators and radiation-hardened electronics housings absorb volume through US Department of Defense strategic stockpile programs and NATO long-term supply agreements.
Defense anchors government-contract installed base. Medical devices represent the steepest expansion trajectory as proton therapy installations multiply.
Form:
Supply concentration differs by physical state: solid forms flow through integrated mining-to-fabrication chains while powder processing fragments across specialized atomization houses.
- Solid:Sintered billets and wrought bar stock serve traditional subtractive machining of crucibles and electrodes. H.C. Starck GmbH and Plansee SE maintain European reduction and sintering capacity outside Chinese MIIT quota exposure. Solid dominates installed base. Powder is where expansion concentrates.
- Powder:Hydrogen-reduced and gas-atomized particulate enables near-net-shape forming and additive manufacturing qualification. Xiamen Tungsten Company leverages integrated APT-to-powder operations to secure feedstock consistency for semiconductor precursor suppliers. Oxygen content below 50 ppm commands 25-35% price premiums.
- Alloy:Tungsten-heavy alloys with nickel-iron or nickel-copper matrices provide density-matched radiation shielding and vibration-dampening masses.
- Coating:Chemical vapor deposition and physical vapor deposition layers protect semiconductor chamber components from fluorine plasma erosion.
Alloy forms anchor medical and aerospace installed base. Coating is gaining share fastest as chamber refurbishment cycles compress.
Custom Grade:
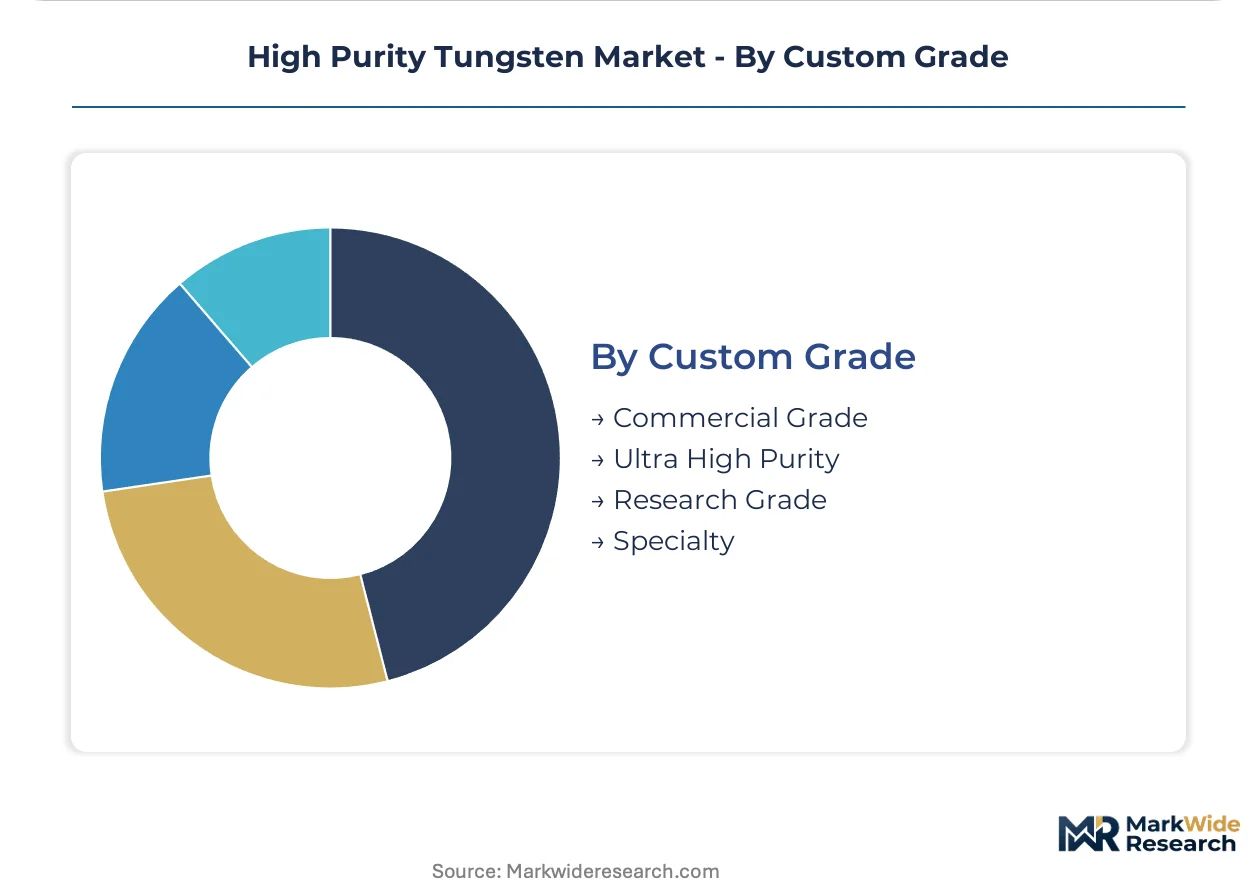
Certification intensity escalates with purity tier: commercial grade requires basic spectrographic analysis while ultra-high-purity demands glow discharge mass spectrometry and secondary ion mass spectrometry validation.
- Ultra High Purity:Material exceeding 99.999% elemental concentration with interstitial impurities below 1 ppm serves EUV lithography source components and fusion reactor divertor tiles. ITER specifications are locking in century-level replacement horizons for vacuum-arc-melted billets, creating long-dated offtake contracts. Ultra high purity dominates specification-driven installed base. Research grade is where expansion concentrates.
- Research Grade:99.95-99.99% purity with documented trace element certificates supports national laboratory plasma physics programs and university materials science departments. US Department of Energy facilities and Max Planck Institute networks are expanding procurement as fusion and quantum computing research accelerates.
- Commercial Grade:99.5-99.9% purity serves industrial heating elements and non-critical electrical contacts where vapor pressure tolerance permits modest interstitial content.
- Specialty:Doped tungsten with potassium-silicon-aluminum additions enhances creep resistance for lamp filament and high-temperature furnace applications.
Commercial grade anchors industrial heating installed base. Specialty is expanding most quickly as LED backlighting and semiconductor thermal management converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor lithography equipment buyers concentrate procurement decisions in East Asian fabrication clusters, with EUV source component demand pulling material through South Korean and Taiwanese foundry supply chains at accelerated cadences.
China
MIIT export quota allocations on tungsten concentrates redirect intermediate oxide flows toward domestic value-added processing under national strategic mineral classifications. Xiamen-based integrated mining-to-powder operations secure feedstock consistency for precursor suppliers serving Yangtze River Delta semiconductor clusters.
South Korea
Samsung Foundry and SK Hynix procurement teams co-locate supplier quality engineers in Suwon and Seoul to compress 18-to-24-month precursor validation cycles for EUV source component materials. The country's production-linked incentive frameworks for display and chip fabrication attract localized chemical vapor deposition material finishing investments.
Taiwan
TSMC advanced node production dominates ultra-high-purity tungsten procurement for sub-7 nanometer logic device gate fill applications. Hsinchu science park fabrication clusters absorb expanding volumes of hydrogen-reduced powder meeting sub-50 ppm oxygen criteria under REACH-compliant supply chain mandates.
United States
NASA and Department of Defense strategic stockpile programs lock in five-year offtake agreements for vacuum-arc-melted billets serving plasma-facing thruster components. Greater Boston and Pacific Northwest aerospace propulsion OEMs certify spherical tungsten powder for directed energy deposition of radiation-shielded assemblies.
Germany
Plansee SE and H.C. Starck GmbH maintain European reduction and sintering capacity outside Chinese MIIT quota exposure, absorbing 15-to-20 percent feedstock cost premiums. Bavarian and North Rhine-Westphalian fabricators serve ITER fusion reactor programs specifying tungsten divertor tiles with century-level replacement horizons.
High Purity Tungsten Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Integrated mining-to-powder operators hold upstream feedstock leverage while specialized reduction houses dominate semiconductor-grade certification. Three archetypes define positioning: vertically integrated Chinese miners with APT-to-powder operations, European sintering specialists with vacuum metallurgy capabilities, and Japanese precision fabricators serving lithography component OEMs. Competitive moves concentrate on dual sourcing partnerships outside Chinese intermediate processing and capacity expansion for spherical powder atomization.
Among integrated Chinese operators, Xiamen Tungsten Company and China Minmetals Corporation occupy positions anchoring upstream concentrate control. European specialists H.C. Starck GmbH exemplify the vacuum metallurgy tier with skull melting capabilities for 99.999% purity material. Plansee SE represents the refractory metal fabrication archetype with in-house production of ion implantation components. These three entities collectively illustrate the geographic and functional segmentation binding competitive dynamics.
| Leading Market Players |
|---|
| Xiamen Tungsten Company |
| China Minmetals Corporation |
| H.C. Starck GmbH |
| Japan New Metals Company |
| Wolfram Company JSC |
| Global Tungsten & Powders Corporation |
| Buffalo Tungsten Inc. |
| Shaanxi Changlong Jiuzhou Metal Technology Co., Ltd. |
| Plansee SE |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European vacuum arc remelting operations is compressing qualification timelines for semiconductor-grade material while amplifying pricing power for incumbent suppliers with skull melting capabilities. This utilization squeeze propagates through hydrogen-reduced powder markets as foundries absorb double-digit feedstock premiums to secure REACH-compliant supply chains outside Chinese MIIT quota exposure.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange APT benchmarks dominate long-term offtake agreements between South Korean memory manufacturers and Japanese smelters. Price differentiation hinges on oxygen content certification below 50 ppm and EUV source component qualification status. Pricing pressure stems from ammonium paratungstate concentrate volatility transmitting directly to hydrogen-reduced powder margins. Defense procurement teams exhibit lowest price sensitivity due to strategic stockpile mandates, while industrial heating element buyers absorb highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration rests with Xiamen Tungsten Company's integrated APT-to-powder operations and Plansee SE's specialized refractory metal fabrication. Geographic supply concentration centers on China, Austria, and Japan for reduction and sintering capacity. Raw material dependencies draw from Vietnamese and Russian mine sources as alternatives to Chinese concentrate. Single-source vulnerability pervades electron beam melting operator pools. Distribution runs through direct reduction agreements displacing traditional trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized vacuum metallurgy technicians capable of maintaining 99.999% purity during skull melting represent the critical chokepoint constraining capacity expansion across EUV source component supply chains.
For Market Incumbents: Insulate qualification advantages by embedding supplier quality engineers within TSMC and Samsung Foundry procurement teams to compress 18-to-24-month precursor validation cycles. Deepen captive supply of ammonium paratungstate through offtake agreements with Vietnamese mine operators to reduce MIIT quota exposure. Electron beam melting operator scarcity threatens margin compression if training pipelines fail to expand. For New Entrants and Emerging Players: Pursue spherical powder atomization capacity serving NASA and ESA radiation-shielded thruster component programs where additive manufacturing qualification opens volume absorption outside entrenched semiconductor precursor supply chains. India's PLI scheme for semiconductors offers the most penetrable geography for localized chemical vapor deposition material finishing. Go-to-market positioning should emphasize carbon-intensity certification for European buyers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among European sintering specialists with vacuum arc remelting capabilities and long-dated ITER divertor tile contracts. Long-term viability across the analysis window favors acquisition targets with skull melting expertise and existing ion implantation component approvals. Monitor ASML's EUV source generation roadmaps as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into APT Mining | Xiamen Tungsten Company secures feedstock consistency for semiconductor precursor suppliers under MIIT quota constraints. |
| Spherical Powder Atomization Capacity Expansion | Aerospace OEMs in Germany and the US certify directed energy deposition feedstock for radiation-shielded thruster components. |
| EUV Source Component Qualification | ASML's collector mirror specifications pull vacuum-arc-melted wafer volumes through Taiwanese fabrication clusters. |
| Dual Sourcing Partnership Formation | European fabricators absorb feedstock cost premiums to maintain REACH-compliant supply chains outside Chinese reduction capacity. |
| Carbon-Intensity Certification Program | Chinese miners monetize MIIT-mandated emissions audits into supply chain differentiation premiums for European buyers. |
Research Methodology
Operator-level perspectives from vacuum metallurgy technicians, semiconductor procurement managers, aerospace propulsion engineers, and APT trading specialists anchored the qualitative base. Primary interview data combined with secondary validation from SEC filings, customs trade records, IEA critical minerals assessments, and MIIT quota announcements. Bottom-up triangulation across hydrogen-reduced powder production volumes and top-down reconciliation with EUV lithography equipment shipment data ensured analytical consistency.
Scenario-bracketing around MIIT quota enforcement intensity and EUV adoption curves framed the analytical approach across the projection horizon. Segmentation dimensions modeled include purity tier, product geometry, end-use industry, and regional fabrication cluster. CAGRs derived from elasticity-adjusted absorption rates for sub-7 nanometer logic device gate fill applications and fusion reactor divertor tile replacement cycles.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or Chinese export license processing timelines would shift the trajectory. Forecasts reflect documented assumptions on APT pricing volatility and electron beam melting capacity expansion. Quarterly review of ASML source generation roadmaps and MIIT quota allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
High Purity Base Metals Market
Metals
Finished Steel Products Market
Metals
Aluminum Casting Market
Metals
Aluminum Wire Market
Metals
Global Flat Carbon Steel Market
Metals
Silver Sulphate Market
Metals
Cerium Market
Metals
Asia-Pacific Metal Finishing Market
Metals
North America and Europe Metal Powder Market
Metals
Europe Aluminium Cans Market
Metals
Metal Forging Parts Market
Metals
Steel Casting Market
Metals
Titanium Market
Metals
High Purity Aluminium Market
Metals
Copper and Copper Alloy Market
Metals
US Ferrochrome Market