
 France PVC Pipes Market | 2026-2036
France PVC Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
France PVC Pipes Market Intelligence
France is reshaping competitive positioning in European thermoplastic piping through sustained capacity investment in Auvergne-Rhône-Alpes. Saint-Gobain leverages backward integration into chlor-alkali feedstocks to control resin cost volatility. Pipelife France anchors its position through specialized fabrication of large-diameter pressure pipe for potable water networks. Aliaxis competes via R&D intensity in co-extruded multilayer structures that improve fatigue resistance.
France PVC Pipes comprise extruded thermoplastic conduit manufactured from polyvinyl chloride resin compounded with stabilizers, lubricants, and fillers, typically produced through twin-screw extrusion at melt temperatures between 170°C and 190°C, serving primarily to convey fluids and protect electrical cabling across civil infrastructure. Unplasticized PVC dominates municipal water supply specifications due to superior rigidity and compliance with potable health standards, while flexible PVC captures agricultural drip irrigation retrofits where soil movement tolerance matters. Drainage applications in the construction end-user segment command concentrated margin pools through specification-driven contractor loyalty and project-scale volume commitments.
ANSM and the French environmental agency enforce REACH substance restrictions and end-of-life recycling quotas that elevate compliance costs for imported compound formulations. CE marking under the Construction Products Regulation mandates continuous pressure testing protocols that filter out lower-tier extruders. Stakeholders must monitor DGCCRF enforcement trends on phthalate content and the pace of EU taxonomy alignment for circular building materials.
Market Dynamics
France's PVC pipe sector faces acute pressure from the EU Green Deal's circular economy mandates, which are redirecting capital toward recycled-content extrusion lines and away from virgin resin capacity. Saint-Gobain and Aliaxis are restructuring Auvergne-Rhône-Alpes facilities to process post-industrial scrap, while REACH compliance costs filter out smaller compound importers.
Growth Catalysts
- Municipal water infrastructure renewal:France's aging potable distribution networks are accelerating procurement of unplasticized PVC pressure pipes for leak reduction programs in Occitanie and Nouvelle-Aquitaine.
- REACH substance restrictions:ECHA's tightening limits on heavy-metal stabilizers are consolidating demand around certified domestic extruders with compliant formulation capabilities.
- Agricultural irrigation modernization:Drip-line retrofits in Languedoc-Roussillon vineyards are expanding flexible PVC demand where soil movement tolerance outweighs rigid pipe specifications.
Market Restraints
- Chlor-alkali feedstock volatility:Electrolysis energy costs for chlorine and caustic soda production are compressing resin margins for non-integrated compounders.
- Import concentration from Benelux:Belgium and Netherlands-based resin suppliers control critical feedstock flows, exposing French extruders to cross-border logistics disruptions.
- Cross-linked polyethylene substitution:PEX piping is capturing residential hot-water segments where thermal expansion tolerance exceeds PVC performance ceilings.
Strategic Opportunities
- Post-consumer recycling infrastructure:France's underdeveloped mechanical recycling capacity for construction-site PVC scrap offers first-mover advantages for circular-economy-certified producers.
- Smart water network integration:Sensor-embedded pressure pipes combining PVC conduit with IoT leak-detection systems are opening premium specification tiers in Grand Est smart-city pilots.
- EU taxonomy alignment:The sustainable finance framework's circular building materials criteria are creating procurement preference for recycled-content pipes in public infrastructure tenders.
Industry Challenges
- Multilayer co-extrusion expertise scarcity:Fatigue-resistant pipe fabrication requires polymer rheology specialists that French technical institutes are not producing at sufficient scale.
- CE marking timeline compression:Continuous pressure testing protocols under the Construction Products Regulation are extending product qualification cycles for new diameter introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France PVC Pipes Market |
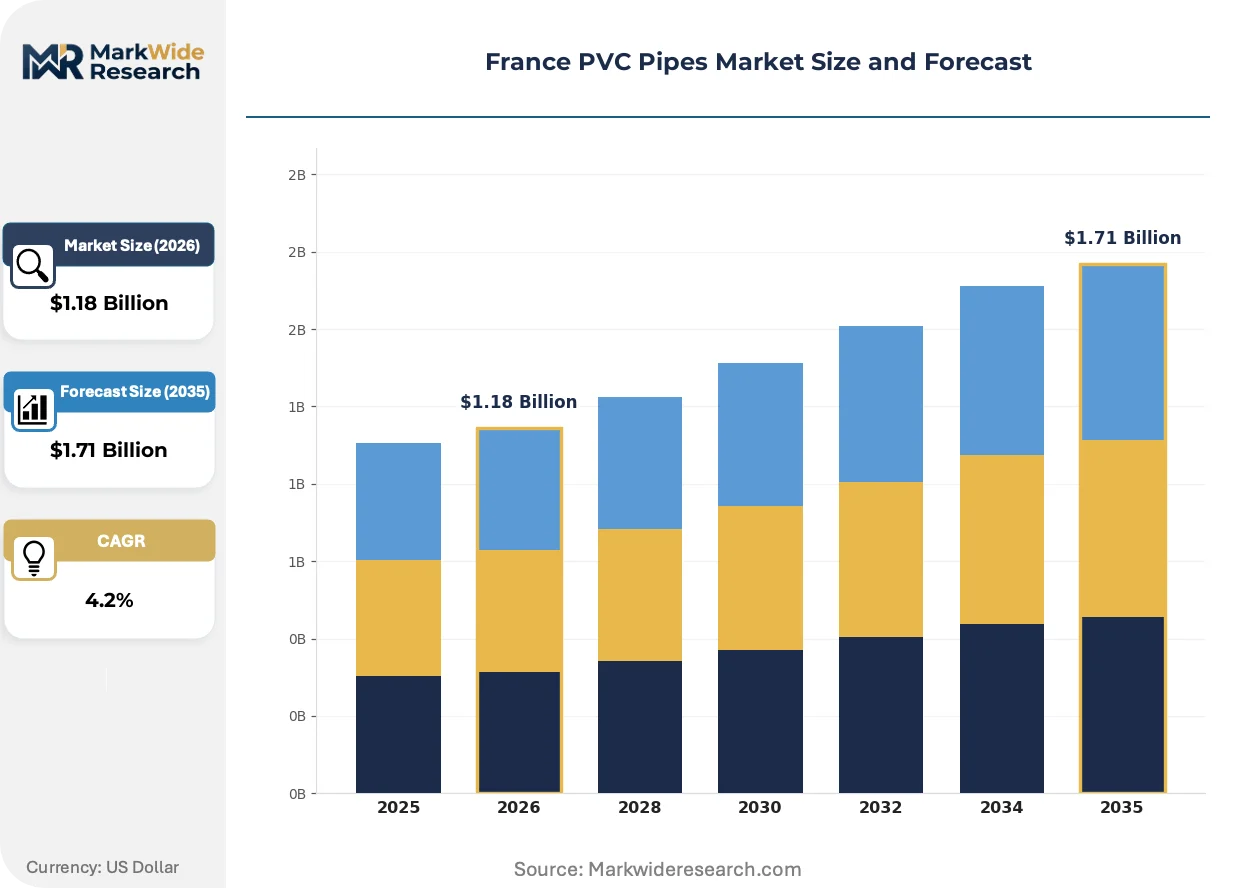
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $1.71 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
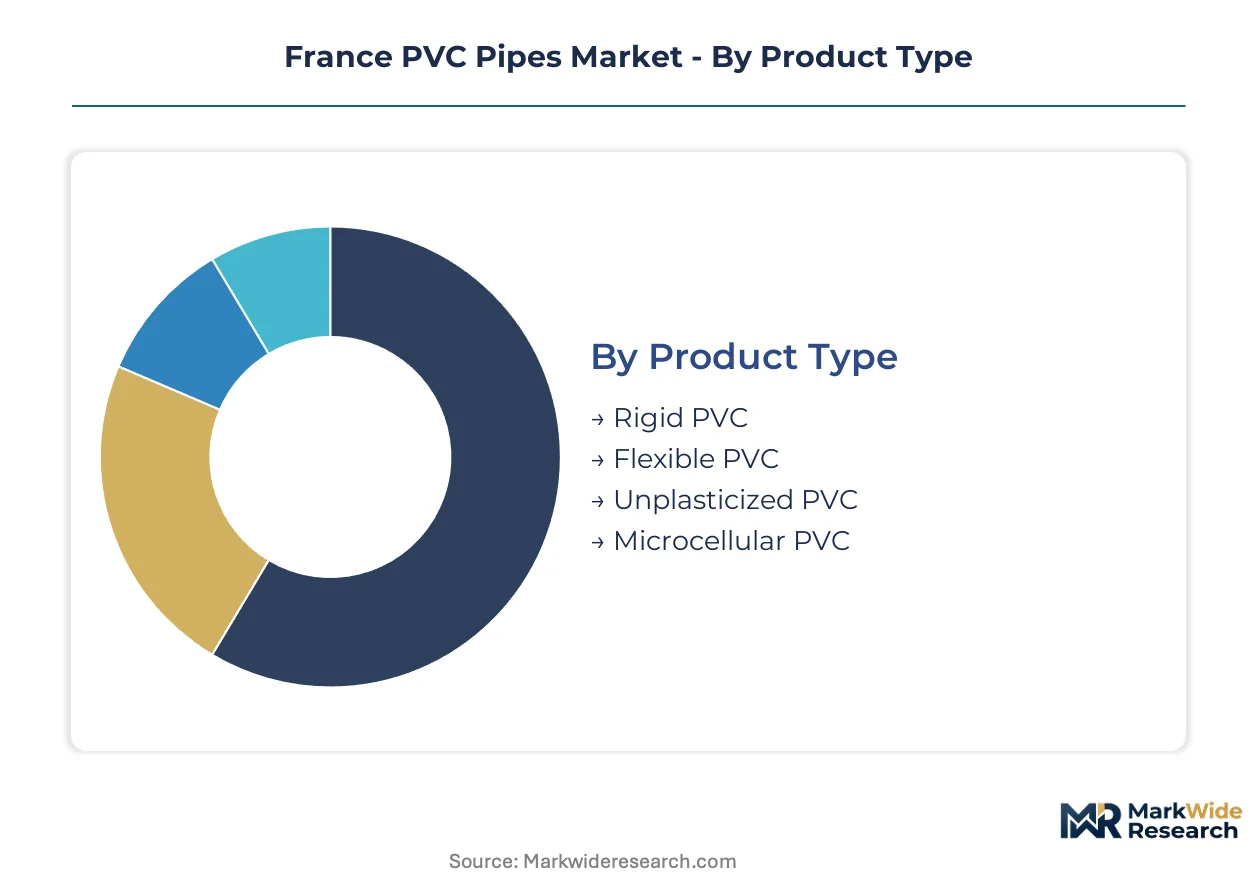
| Segmentation | Product Type: Rigid PVC, Flexible PVC, Unplasticized PVC, Microcellular PVC Application: Water Supply, Drainage, Irrigation, Electrical Conduits End User: Construction, Agriculture, Telecommunications, Infrastructure Thickness: Schedule 40, Schedule 80, Double Wall, Single Wall |
| Companies Covered | Futurepipe, Saint-Gobain, Pipelife France, Aliaxis, Wavin, Aqua’Tec, Polypipe, Rehau, Trrendis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France PVC Pipes Market Strategic Shifts & Innovations
Extrusion technology and regulatory chemistry are converging to redefine competitive advantage in French thermoplastic piping. Manufacturers are racing to deploy recycled-content formulations before circular-economy mandates harden into procurement requirements.
Co-extruded multilayer structures are collapsing the traditional trade-off between pressure rating and impact resistance in municipal water applications. Water utilities in Brittany and Pays de la Loire are specifying these constructions for trenchless installation projects where soil stress concentration exceeds single-wall performance limits. The technology is collapsing premium pricing for thick-wall unplasticized alternatives as standard-duty multilayer pipes achieve equivalent burst strength at lower material intensity.
ECHA's 2024 update to REACH Annex XVII restrictions on cadmium and lead stabilizers is forcing reformulation of legacy compound recipes. French extruders with captive chlor-alkali integration are absorbing retooling costs faster than import-dependent competitors, shifting specification influence toward vertically integrated suppliers. The regulatory pressure is concentrating procurement decisions around ANSM-certified domestic producers with documented substance traceability.
Contractor loyalty programs are fragmenting as public infrastructure buyers unbundle specification authority from installation services. Regional water agencies in Provence-Alpes-Côte d'Azur are establishing direct material certification relationships with compounders, bypassing traditional distribution channels. The disintermediation is most visible in large-diameter pressure pipe categories where project-scale volume commitments justify dedicated supply agreements over distributor stockholding.
France PVC Pipes Market Segmentation
Segmentation in France's PVC pipe market reveals how specification requirements fragment procurement decisions across pressure ratings, flexibility demands, and regulatory compliance tiers. Understanding these divisions exposes where margin pools concentrate and where formulation investments yield competitive defense.
Product Type:
After-sales service intensity varies sharply across product types, with rigid formulations demanding minimal field support while flexible installations require contractor training programs and joint integrity warranties.
- Unplasticized PVC:Manufactured without plasticizing additives, this formulation delivers maximum rigidity and chemical resistance for potable water pressure networks. Demand clusters in Occitanie's municipal renewal programs where ANSM-certified producers capture specification authority through documented lead-free stabilizer compliance.
- Flexible PVC:Plasticizer-modified compounds achieve elongation properties essential for agricultural drip irrigation and trenchless installation. Languedoc-Roussillon vineyard retrofits are expanding procurement of soil-movement-tolerant flexible lines where rigid alternatives would fracture.
- Rigid PVC:Standard extrusion formulations serve non-pressure drainage and ventilation applications with lower compound complexity.
- Microcellular PVC:Foamed-core structures reduce material intensity for non-load-bearing electrical conduit and telecommunications ducting.
Unplasticized PVC holds the largest share; momentum sits with flexible PVC as agricultural modernization accelerates.
Application:
Margin structure diverges across applications, with water supply commanding premium pricing through continuous pressure testing certification while drainage competes on volume scale.
- Water Supply:Pressure-rated unplasticized PVC for potable distribution networks requires ECHA REACH-compliant stabilizer packages and CE marking under Construction Products Regulation. Brittany and Pays de la Loire utilities are specifying multilayer co-extruded constructions for trenchless projects where soil stress exceeds single-wall limits.
- Drainage:Gravity-flow systems for building construction and civil infrastructure operate on specification-driven contractor loyalty with project-scale volume commitments.
- Irrigation:Flexible PVC drip lines and rigid mainline distribution serve agricultural modernization in Occitanie and Nouvelle-Aquitaine.
- Electrical Conduits:Microcellular and rigid formulations protect cabling across residential and commercial construction with lower regulatory burden than pressure applications.
Water supply dominates value capture; irrigation is expanding most quickly as EU Common Agricultural Policy funding redirects toward efficiency upgrades.
End User:
Customer concentration patterns split the market, with infrastructure agencies consolidating procurement through direct compounder relationships while construction channels fragment across regional distributors.
- Construction:Residential and commercial building applications span drainage, electrical conduit, and non-pressure plumbing with specification authority resting with contractors and architects.
- Infrastructure:Municipal water agencies in Provence-Alpes-Côte d'Azur are disintermediating traditional distribution through direct material certification relationships with extruders for large-diameter pressure pipe.
- Agriculture:Vineyard and orchard operators in Languedoc-Roussillon drive flexible PVC demand through drip-line retrofits.
- Telecommunications:Fiber deployment programs specify microcellular conduit for cable protection with standardized diameter requirements.
Construction holds the largest share; infrastructure is gaining share fastest as public procurement centralizes.
Thickness:
Cost tier differentiation separates specification grades, with Schedule 80 and double-wall constructions commanding premium positioning through pressure rating and installation performance advantages.
- Schedule 80:Thicker-wall construction delivers higher pressure ratings for municipal water distribution and industrial process piping. Grand Est smart-city pilots are specifying sensor-embedded Schedule 80 lines for IoT-integrated leak detection networks.
- Double Wall:Corrugated exterior with smooth interior bore combines structural rigidity for buried installation with hydraulic efficiency. Trenchless installation projects in Brittany favor these constructions for soil load distribution.
- Schedule 40:Standard-duty wall thickness serves gravity drainage and low-pressure applications with material cost advantages.
- Single Wall:Minimum material construction for electrical conduit and non-structural applications where soil loading is absent.
Schedule 40 holds the largest share; double-wall is climbing the fastest as trenchless installation methods displace open-cut techniques.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANSM certification requirements and EU Green Deal circular economy mandates are reshaping procurement patterns across French sub-regions. Municipal water infrastructure renewal and agricultural modernization are redirecting specification authority toward compliant domestic extruders with documented formulation traceability.
Auvergne-Rhône-Alpes
Saint-Gobain's chlor-alkali integration anchors resin cost control for pressure pipe manufacturing. REACH Annex XVII stabilizer restrictions are filtering specification decisions toward vertically integrated compounders with captive feedstock security. Lyon-based fabrication clusters are processing post-industrial scrap into recycled-content formulations ahead of circular-economy procurement mandates.
Occitanie
Montpellier's periphery construction and Languedoc-Roussillon vineyard irrigation retrofits are outpacing national demand averages. ANSM-certified unplasticized PVC pressure pipes capture municipal water renewal contracts in leak reduction programs. Flexible PVC drip-line procurement is expanding as EU Common Agricultural Policy funding redirects toward efficiency upgrades.
Provence-Alpes-Côte d'Azur
Regional water agencies are disintermediating traditional distribution through direct material certification relationships with extruders. CE marking under the Construction Products Regulation is filtering large-diameter pressure pipe procurement toward domestic producers with continuous testing protocols. Marseille-Toulon infrastructure corridors are specifying multilayer co-extruded constructions for trenchless installation projects.
Brittany
Water utilities are specifying multilayer co-extruded pipes for soil stress conditions exceeding single-wall performance limits. DGCCRF enforcement trends on phthalate content are consolidating demand around documented lead-free stabilizer compliance. Rennes-Brest utility networks are piloting sensor-embedded pressure pipes for IoT-integrated leak detection systems.
Nouvelle-Aquitaine
Bordeaux metropolitan expansion and agricultural irrigation modernization are accelerating procurement across both rigid and flexible PVC categories. ECHA's tightening heavy-metal stabilizer limits are redirecting specification authority toward certified domestic extruders. The region's underdeveloped mechanical recycling capacity offers first-mover positioning for circular-economy-certified producers.
France PVC Pipes Market Key Industry Players
Capability concentration sits with integrated compounders controlling chlor-alkali feedstocks; scale advantage sits with diversified building-materials conglomerates with multi-regional distribution. The market structures around three archetypes: vertically integrated resin-to-pipe manufacturers, specialized pressure-pipe fabricators, and building-systems conglomerates with piping divisions. Dominant competitive moves include backward integration into resin production and restructuring of extrusion lines for recycled-content processing.
Among France-based fabricators, Saint-Gobain S.A. exemplifies the vertically integrated archetype through captive chlor-alkali capacity, while Pipelife France occupies a position as a specialized pressure-pipe fabricator serving potable water networks. Aliaxis represents the building-systems conglomerate model with R&D intensity in multilayer structures. These three anchors illustrate how regulatory chemistry expertise and feedstock security are separating specification winners from import-dependent competitors.
| Leading Market Players |
|---|
| Futurepipe |
| Saint-Gobain |
| Pipelife France |
| Aliaxis |
| Wavin |
| Aqua'Tec |
| Polypipe |
| Rehau |
| Trrendis |
| Others |
Cost & Logistics Intelligence
Auvergne-Rhône-Alpes resin production clusters anchor French PVC pipe pricing power through captive chlor-alkali integration. Saint-Gobain's Lyon-area electrolysis capacity insulates compound costs from Benelux import volatility, compressing margin spreads for non-integrated extruders in Occitanie and Nouvelle-Aquitaine.
Pricing Analysis
Domestic-Benelux resin price spreads of 8-12 percent persist across quarterly contract cycles. Three-tier pricing structure across premium, standard, and economy levels separates ANSM-certified multilayer pressure pipe from commodity drainage grades. Cost compression in Schedule 40 drainage categories is intensifying because Belgian resin suppliers are extending payment terms to capture French market share. Agricultural irrigation contractors in Languedoc-Roussillon exhibit highest price sensitivity; Grand Est municipal water agencies show lowest sensitivity due to lifecycle cost prioritization.
Supply Chain Analysis
Contract compounding concentrates at Saint-Gobain's Pont-à-Mousson facility and Aliaxis's Lyon extrusion complex. Raw material flows draw from Belgian chlorine electrolysis, Dutch vinyl chloride monomer production, and domestic calcium carbonate fillers. Single-source vulnerability sits with cross-border resin pipelines through the ARA hub. Distribution runs through regional building-materials distributors for construction segments and direct extruder relationships for infrastructure agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France PVC Pipes Market represents a high-growth disruption as EU Green Deal circular economy mandates force €40-60 million retooling decisions across domestic extrusion bases. REACH Annex XVII stabilizer restrictions are compressing qualification timelines for non-integrated compounders.
For Market Incumbents: Insulate specification authority by accelerating backward integration into post-industrial recycling streams ahead of circular-economy procurement mandates. Secure ANSM certification renewals for lead-free stabilizer formulations before ECHA's 2024 enforcement window tightens. Defend against cross-linked polyethylene substitution in residential hot-water segments by co-developing sensor-embedded pressure pipes with Grand Est smart-city pilot operators.
For New Entrants and Emerging Players: Build out mechanical recycling capacity in Nouvelle-Aquitaine where construction-site PVC scrap collection infrastructure remains underdeveloped. Target agricultural drip-line retrofit contracts in Languedoc-Roussillon vineyards where soil-movement tolerance specifications favor flexible PVC over rigid alternatives. Pursue direct certification relationships with Provence-Alpes-Côte d'Azur regional water agencies that are disintermediating traditional distribution channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building-materials conglomerates with underperforming piping divisions lacking chlor-alkali integration. Long-term viability hinges on circular-economy certification positioning within a 5-10 year window as EU taxonomy alignment hardens into public tender requirements. Monitor DGCCRF enforcement actions on phthalate content as the inflection signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Industrial Recycling Infrastructure | Captures circular-economy procurement preference ahead of EU Green Deal mandate hardening. |
| Multilayer Co-Extrusion Capacity Expansion | Addresses Brittany and Pays de la Loire trenchless installation specifications exceeding single-wall limits. |
| Direct Agency Certification Relationships | Bypasses distributor intermediation in Provence-Alpes-Côte d'Azur large-diameter pressure pipe procurement. |
| Sensor-Embedded Pipe Development | Opens premium specification tiers in Grand Est IoT-integrated leak detection network pilots. |
| Chlor-Alkali Feedstock Integration | Absorbs REACH reformulation costs faster than import-dependent competitors in Occitanie. |
Research Approach
Operator-level perspectives from extrusion plant managers, municipal water agency procurement directors, agricultural irrigation contractors, and building-materials distribution channel heads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through ECHA REACH substance restriction filings, ANSM certification registries, and EU Construction Products Regulation testing protocols. Bottom-up volume modeling triangulated against top-down macroeconomic indicators.
Scenario-bracketing framed demand projections across the analysis window through three regulatory enforcement intensity assumptions. Segmentation dimensions modeled include product rigidity class, pressure rating tier, end-use application, and regional procurement centralization patterns. CAGRs derived from unit consumption trajectories weighted by compound price evolution and substitution elasticity to cross-linked polyethylene.
Stress conditions across chlor-alkali energy cost volatility, REACH enforcement timeline acceleration, and cross-border logistics disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of ECHA Annex XVII amendment proposals and DGCCRF inspection disclosure trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Hydrogen Tube Skids Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
Compressed Air Pipe Market
Pipes and Tubes
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market
Pipes and Tubes
Thermoplastic Pipe Market
Pipes and Tubes
India PVC Pipes Market
Pipes and Tubes
Europe PVC Pipes Market
Pipes and Tubes
FRP Pipes and Tanks Market
Pipes and Tubes
Water and Wastewater Pipe Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
GCC PVC Pipes Market
Pipes and Tubes
FRP Pipe Market
Pipes and Tubes
Saudi Arabia Copper Pipes and Tubes Market
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
Plastic Pipe Jointing and Welding Market
Pipes and Tubes
Oman PVC Pipes Market