
 Spain Ultrasound Devices Market | 2026-2036
Spain Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Ultrasound Devices Market Analytics
Specialized biomedical engineering talent is unwinding capacity constraints across Spanish healthcare technology procurement. Siemens Healthineers leverages its established service infrastructure to sustain long-term hospital contracts in Catalonia and Andalusia. GE Healthcare anchors its position through direct sales relationships with large regional health consortia. Philips competes by integrating ultrasound platforms with enterprise imaging workflows.
Ultrasound devices generate acoustic images through piezoelectric transducers operating at frequencies between two and fifteen megahertz, enabling non-invasive visualization of soft tissues, blood flow, and fetal development without ionizing radiation. Diagnostic ultrasound systems dominate installed base value across Spanish facilities, while portable ultrasound units represent the fastest-expanding product category as emergency departments and rural clinics pursue decentralized imaging capabilities. Color Doppler technology commands premium positioning in cardiology and vascular applications where hemodynamic assessment determines clinical utility.
Spain's national pharmaceutical and medical device regulator, the Spanish Agency for Medicines and Health Products (AEMPS), enforces CE marking compliance under EU MDR requirements for all commercially distributed ultrasound equipment. The EU F-Gas Regulation constrains refrigerant choices in cooled transducer designs, pushing manufacturers toward solid-state alternatives. Stakeholders must weigh MDR transition timelines against hospital budget cycles when planning product registrations and service deployments.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing certification timelines for ultrasound equipment, forcing manufacturers to accelerate clinical evidence collection while Spanish hospital networks consolidate diagnostic imaging procurement under regional health authority budgets.
Growth Catalysts
- Point-of-care expansion:Emergency departments in Madrid and Barcelona are acquiring portable systems for bedside cardiac and trauma assessment, bypassing centralized radiology workflows.
- EU F-Gas Regulation:Restrictions on refrigerants in cooled transducers are accelerating solid-state probe development, reducing maintenance burdens for rural clinics.
- Cardiology demand concentration:Public hospital networks in Catalonia and Andalusia are prioritizing hemodynamic imaging capabilities for heart failure patient management.
Market Restraints
- MDR compliance costs:Clinical evaluation requirements for high-risk diagnostic devices are extending registration timelines and absorbing R&D resources.
- Transducer supply concentration:Piezoelectric crystal fabrication relies on specialized suppliers concentrated in East Asian manufacturing clusters, creating input vulnerability.
- MRI substitution in neurology:Brain and spinal imaging applications are migrating toward magnetic resonance where tissue contrast resolution determines diagnostic confidence.
Strategic Opportunities
- Andalusian rural health expansion:Federally funded primary care centers in southern provinces lack imaging infrastructure, creating deployment white space for compact systems.
- Artificial intelligence convergence:Automated measurement algorithms for fetal biometry and cardiac ejection fraction are reducing operator dependency and examination time.
- Service unbundling:Independent technical service providers are capturing maintenance contracts from manufacturers, fragmenting the aftermarket revenue pool.
Industry Challenges
- Biomedical engineering talent scarcity:Spanish universities produce insufficient specialized technicians for probe repair and system calibration, constraining service capacity expansion.
- Legacy PACS integration complexity:Enterprise imaging archives in major hospital networks require custom connectivity modules, prolonging deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Ultrasound Devices Market |
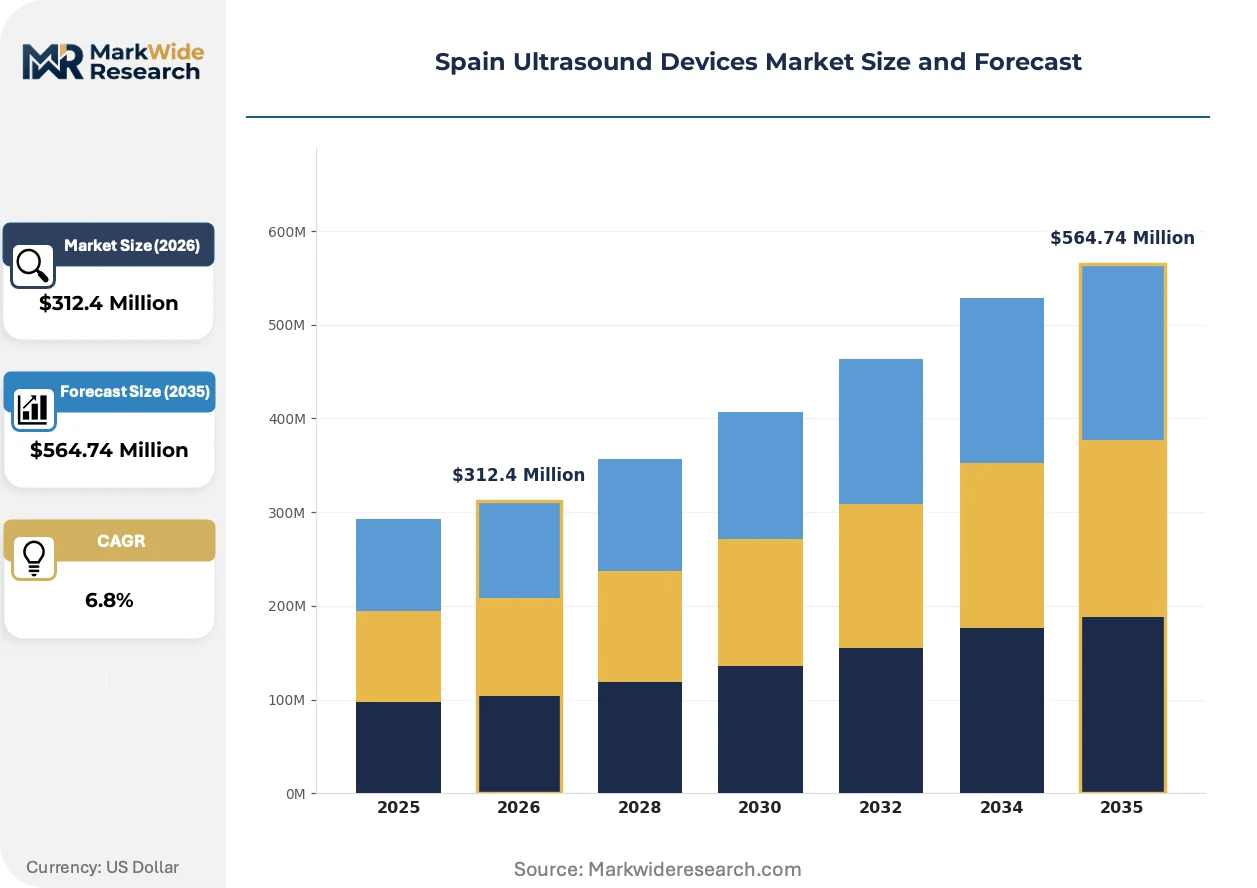
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Ultrasound, Therapeutic Ultrasound, 3D Ultrasound, Portable Ultrasound End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Technology: Digital Imaging, Analog Imaging, Color Doppler, Power Doppler Application: Obstetrics, Cardiology, Urology, Gastroenterology |
| Companies Covered | Canon Medical Systems Corporation, Esaote SpA, GE Healthcare, Mindray Medical International Limited, Samsung Electronics Co Ltd, Siemens Healthineers AG, Fujifilm Holdings Corporation, Hologic Inc., Koninklijke Philips NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Ultrasound Devices Market Evolving Landscape
Spanish ultrasound adoption is pivoting toward decentralized diagnostic workflows. Three developments are compressing equipment footprints, reshaping compliance obligations, and altering how purchasing decisions flow through health system hierarchies.
Capacitive micromachined ultrasound transducers (CMUTs) are replacing conventional piezoelectric arrays in premium cardiology systems, enabling superior bandwidth and thermal efficiency. Leading hospital networks in Catalonia are piloting these platforms for stress echocardiography protocols. The technology is miniaturizing probe head dimensions while preserving acoustic output, allowing catheter-based intracardiac imaging that conventional crystal assemblies cannot achieve.
EU MDR Article 10 technical documentation requirements are mandating systematic post-market surveillance for all Class IIa and above diagnostic devices. Manufacturers must maintain electronic systems for incident reporting and periodic safety updates, increasing regulatory affairs staffing by forty percent for most notified body interactions. Spanish regional health authorities are prioritizing MDR-certified equipment in tender evaluations, disadvantaging legacy inventory held by smaller distributors.
Hospital procurement committees are unbundelling device acquisition from multi-year service agreements, treating maintenance as separately contestable spend. Large regional consortia in Madrid and Valencia are establishing framework contracts with independent technical service organizations, displacing manufacturer-captive service models. This pattern is most pronounced in public sector tenders where budget transparency requirements favor visible price separation between capital and operating expenditures.
Spain Ultrasound Devices Market Segmentation
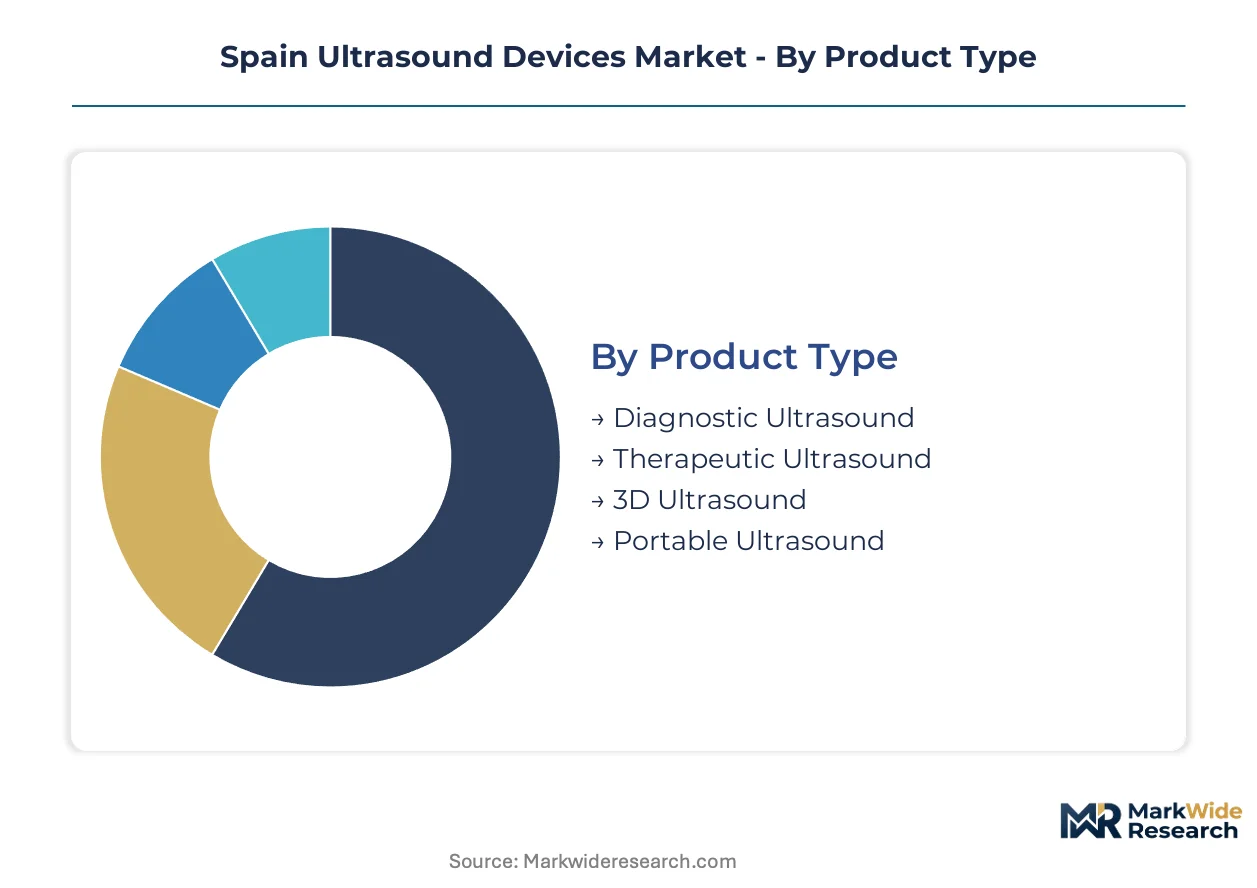
Ultrasound device segmentation in Spain reflects divergent compliance burdens under EU MDR and the operational priorities of regional health authorities. Product architecture, clinical setting, and imaging modality each shape procurement pathways and service requirements across Catalonia, Andalusia, and Madrid hospital networks.
Product Type:
EU MDR classification tiers split this category between high-risk diagnostic systems requiring extensive clinical evidence and lower-risk therapeutic platforms with streamlined certification.
- Diagnostic Ultrasound:Multi-modality imaging systems integrate B-mode, M-mode, and spectral Doppler capabilities for comprehensive anatomical assessment. Public hospital networks in Madrid and Barcelona concentrate procurement of these platforms under centralized radiology budgets, with AEMPS enforcing CE marking compliance for Class IIa and above devices.
- Portable Ultrasound:Battery-powered compact units enable point-of-care deployment in emergency departments and rural primary care centers. Federally funded clinics in Andalusian provinces are acquiring these systems to bypass centralized imaging workflows, though transducer durability constraints elevate total cost of ownership in high-utilization settings.
- Therapeutic Ultrasound:Phonophoresis and thermal ablation systems target physiotherapy and pain management applications with lower regulatory classification.
- 3D Ultrasound:Volume rendering platforms reconstruct fetal and cardiac anatomy from multi-planar acquisitions, commanding premium positioning in specialized obstetrics units.
Established volume favors Diagnostic Ultrasound; emerging adoption favors Portable Ultrasound.
End User:
Procurement authority concentration varies sharply across this category, with regional health consortia controlling hospital budgets while independent clinics operate under fragmented purchasing patterns.
- Hospitals:Tertiary care facilities in Catalonia and Andalusia deploy enterprise ultrasound platforms integrated with PACS infrastructure. The EU F-Gas Regulation constrains cooled transducer designs in these high-throughput settings, accelerating solid-state probe adoption.
- Clinics:Primary care centers and specialty practices prioritize compact systems with simplified operator interfaces. Rural health expansion programs in southern Spanish provinces are channeling federal funds toward these facilities, creating deployment opportunities for mid-range equipment.
- Diagnostic Centers:Independent imaging providers compete on examination throughput and reporting speed.
- Research Institutions:Academic medical centers in Barcelona and Madrid pilot CMUT technology and AI-integrated measurement protocols.
Capital concentration sits with Hospitals; volume expansion is climbing the fastest among Clinics.
Technology:
Signal processing architecture determines regulatory classification and service complexity, with digital platforms commanding distinct post-market surveillance obligations under MDR Article 10.
- Color Doppler:Velocity-encoded flow mapping enables hemodynamic assessment for cardiac ejection fraction and vascular stenosis evaluation. Cardiology departments within Spanish public hospitals prioritize these capabilities for heart failure patient management, with premium pricing reflecting transducer bandwidth requirements.
- Digital Imaging:Software-beamforming platforms replace analog hardware with programmable signal paths, reducing probe head size while enabling firmware-based feature upgrades. Leading hospital networks are piloting these architectures for stress echocardiography protocols.
- Analog Imaging:Legacy beamformer designs persist in cost-sensitive installations with established service infrastructure.
- Power Doppler:Amplitude-based flow detection visualizes low-velocity perfusion in small vessels and parenchymal organs.
Clinical utility concentrates in Color Doppler; technology transition favors Digital Imaging.
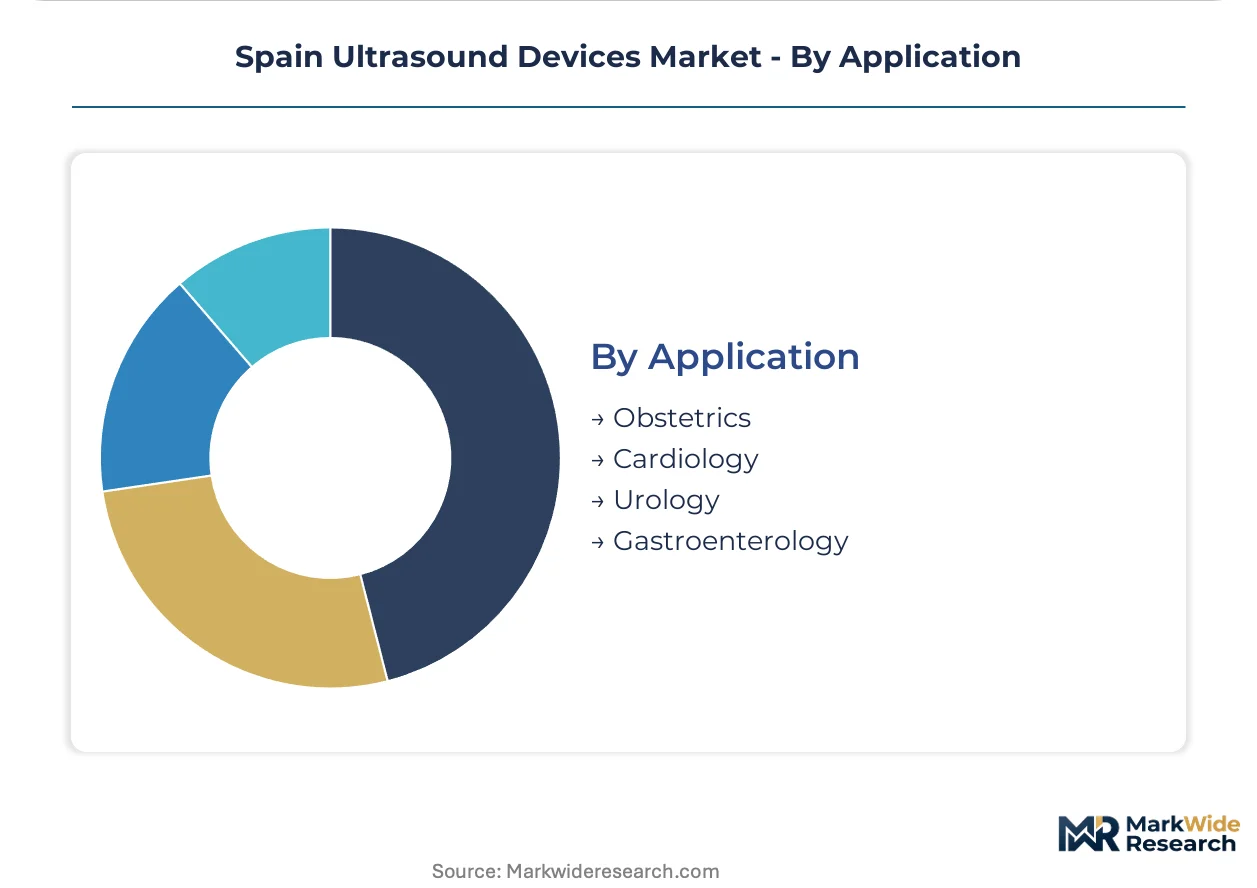
Application:
Specialty-specific imaging protocols create divergent transducer requirements and operator training demands across Spanish healthcare facilities.
- Cardiology:Echocardiography systems with phased-array transducers and continuous-wave Doppler capabilities dominate hemodynamic assessment. Public hospital networks in Catalonia and Andalusia are expanding procurement of point-of-care cardiac systems for bedside evaluation, bypassing centralized radiology queues.
- Obstetrics:Fetal biometry and anomaly screening drive demand for high-frequency linear and curvilinear probes. Automated measurement algorithms are reducing examination time and operator dependency in high-volume maternity units.
- Urology:Transrectal and transabdominal imaging guides prostate and renal assessment.
- Gastroenterology:Endoscopic ultrasound and abdominal imaging support hepatobiliary and pancreatic evaluation.
Installed base value concentrates in Cardiology; procedure volume expansion is gaining share fastest in Obstetrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish ultrasound deployment patterns diverge sharply between the centralized hospital networks of Madrid and Barcelona and the federally funded rural expansion programs across southern provinces. AEMPS enforcement of EU MDR certification timelines compresses procurement cycles differently across these geographies.
Madrid
The capital's regional health authority consolidates diagnostic imaging budgets across twelve tertiary hospitals, prioritizing enterprise ultrasound platforms with PACS integration. EU F-Gas Regulation constraints on cooled transducers accelerate solid-state probe procurement for high-throughput cardiology departments. Hospital networks in the Madrid metropolitan area pilot CMUT-enabled stress echocardiography systems.
Catalonia
Barcelona anchors the region's concentration of research institutions piloting AI-integrated measurement algorithms for fetal biometry. The Catalan health service channels procurement toward point-of-care cardiac systems for bedside heart failure assessment. Siemens Healthineers leverages established service infrastructure to sustain long-term contracts across public hospital networks here.
Andalusia
Federally funded primary care centers in southern provinces lack imaging infrastructure, creating deployment white space for compact portable systems. Rural health expansion programs bypass centralized radiology workflows, elevating total cost of ownership concerns for transducer durability. Seville and Málaga hospital consortia prioritize hemodynamic imaging capabilities under regional authority budgets.
Valencia
The regional health consortium unbundles device acquisition from multi-year service agreements, establishing framework contracts with independent technical service organizations. Budget transparency requirements favor visible price separation between capital and operating expenditures. Alicante and Castellón clinics pursue mid-range equipment with simplified operator interfaces.
Basque Country
San Sebastián and Bilbao academic medical centers focus on automated cardiac ejection fraction measurement protocols. The region's biomedical engineering programs address technician scarcity for probe repair and system calibration. Local health authorities evaluate MDR-certified equipment in tender evaluations, disadvantaging legacy inventory held by smaller distributors.
Spain Ultrasound Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Spanish ultrasound market structure. The upper tier comprises diversified medical technology conglomerates with captive service infrastructure and direct sales relationships with regional health consortia. The specialist tier includes imaging-focused manufacturers and Asian equipment suppliers competing on capital cost. Three archetypes dominate: integrated diagnostics platforms, portable system specialists, and transducer technology innovators. Competitive moves concentrate on multi-year service contract capture and AI-integrated software differentiation.
Among diversified health technology groups, GE Healthcare, Siemens Healthineers AG, and Koninklijke Philips NV occupy positions representing the integrated platform archetype. GE Healthcare anchors relationships through direct engagement with large regional health consortia. Siemens Healthineers exemplifies service infrastructure leverage across Catalonia and Andalusia. Philips sits within the enterprise imaging workflow integration segment. These three represent distinct geographic origin patterns—American, German, and Dutch corporate structures respectively—while competing through similar hospital network penetration strategies.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Esaote SpA |
| GE Healthcare |
| Mindray Medical International Limited |
| Samsung Electronics Co Ltd |
| Siemens Healthineers AG |
| Fujifilm Holdings Corporation |
| Hologic Inc. |
| Koninklijke Philips NV |
| Others |
Value Network & Pricing Analysis
Ninety-day transducer inventory cycles at Spanish distributors compress working capital buffers while amplifying pricing leverage for East Asian piezoelectric crystal suppliers. This lead-time exposure concentrates procurement power among manufacturers with captive probe fabrication, forcing independent distributors toward volume-based discounting to maintain hospital contract competitiveness.
Pricing Analysis
Long-term service contracts dominate hospital procurement, with Madrid and Barcelona health consortia favoring bundled capital-plus-maintenance agreements over spot equipment purchases. Price differentiation rests on MDR certification tier and after-sales service bundling, with AEMPS-compliant Class IIa systems commanding premiums against legacy CE-marked inventory. Cost compression in portable ultrasound tiers is intensifying as Mindray and Samsung Electronics compete on capital cost for Andalusian rural clinic deployments. Public sector tenders exhibit highest price sensitivity due to budget transparency mandates, while private diagnostic centers prioritize throughput speed over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for probe assemblies manufactured in South Korea, Japan, and China. Piezoelectric crystal fabrication draws from specialized suppliers concentrated in East Asian manufacturing clusters, creating single-source vulnerability for bandwidth-optimized transducer designs. Distribution runs through authorized distributor networks with regional service depots in Madrid, Barcelona, and Seville, though independent technical service providers are fragmenting aftermarket revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as regional health authority procurement decentralization creates niche openings for specialized service providers and mid-tier equipment suppliers. Point-of-care workflow migration splinters historically centralized radiology budgets into departmental purchasing authority.
For Market Incumbents: Compound service infrastructure density across Catalonia and Andalusia to defend against independent technical service organization encroachment. Deepen backward integration into solid-state transducer development to offset F-Gas Regulation compliance costs. Prioritize MDR Article 10 post-market surveillance system investments to accelerate notified body recertification timelines ahead of hospital tender evaluations. For New Entrants and Emerging Players: Lead with AI-integrated measurement algorithms for fetal biometry and cardiac ejection fraction to bypass established brand preference in obstetrics and cardiology departments. Target Andalusian federally funded primary care centers lacking imaging infrastructure, where simplified operator interfaces outweigh enterprise PACS integration requirements. Pursue direct relationships with biomedical engineering programs to address technician scarcity for probe repair capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core ultrasound service operations. Five-to-ten year viability hinges on MDR compliance infrastructure and AI software differentiation rather than hardware manufacturing scale. Watch AEMPS enforcement intensity against legacy CE-marked inventory as inflection indicator for distributor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 10 compliance accelerates hospital tender eligibility for Class IIa diagnostic systems. |
| Hospital System Partnership | Direct engagement with Madrid and Barcelona regional health consortia secures multi-year framework contracts. |
| Software Companion Development | Automated cardiac ejection fraction algorithms reduce operator dependency in point-of-care deployments. |
| Backward Integration | In-house piezoelectric crystal fabrication mitigates East Asian supply concentration risk for premium transducers. |
| Service Unbundling Response | Independent technical service organization alliances capture maintenance contracts from manufacturer-captive models. |
Research Methodology
The analysis maps diagnostic ultrasound, portable ultrasound, and therapeutic ultrasound segments, each validated through purchasing committee directors, biomedical engineering managers, and GPO contracts specialists. Primary interviews with hospital procurement leads and regional health authority budget officers combined with secondary validation against AEMPS device registrations, EU MDR notified body databases, and hospital tender documentation. Bottom-up installed base estimates triangulate with top-down regional health expenditure allocations.
Consistency checks validated volume and value outputs against external benchmarks across product architecture, clinical setting, imaging modality, and regional adoption pattern segmentation dimensions. CAGRs derive from equipment replacement cycle analysis and point-of-care expansion trajectory modeling. Probe durability assumptions and F-Gas Regulation compliance cost curves inform portable system adoption forecasts.
Forecasts assume regulatory continuity in EU MDR implementation and AEMPS enforcement regimes; material policy shifts would require re-modeling. Transducer supply disruption scenarios and AI algorithm reimbursement decisions represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Sweden Respiratory Devices Market
Medical Devices
Europe Aligner Sheet Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Global Concussion Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Intravenous Access Devices Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Catheter Introducer Sheaths Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Europe Spinal Surgery Devices Market
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
Interphalangeal Fusion Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Japan Hemostats Market