
 Global Digital Therapeutic Devices Market | 2026-2036
Global Digital Therapeutic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Therapeutic Devices Market Foresight
Israeli digital health startups is broadening the supplier base for algorithm-driven therapeutic platforms. Omada Health leverages behavioral coaching protocols to anchor its position in diabetes prevention. Pear Therapeutics sustains FDA-cleared prescription digital therapeutic portfolios across addiction and insomnia. Akili Interactive Labs specializes in cognitive training software delivered through action video game interfaces.
Digital therapeutic devices are software-driven medical interventions that deliver evidence-based therapeutic protocols through smartphones, wearables, or immersive hardware, typically requiring clinical validation through randomized controlled trials and regulatory clearance before reimbursement. Their primary commercial purpose is to treat, manage, or prevent medical conditions as standalone or adjunct therapies under physician oversight. Software programs lead current revenue pools due to lower marginal distribution costs, while wearable devices represent the fastest-expanding segment as biosensor accuracy improves and form factors shrink. Behavioral therapy applications command premium pricing because payer reimbursement for mental health digital interventions is consolidating faster than in pain management.
FDA, EMA, and Japan's PMDA each maintain distinct evidentiary thresholds for digital therapeutic approval, with FDA's breakthrough device pathway and Japan's fast-track review system compressing time-to-market for qualifying platforms while EMA's MDR transition imposes heavier clinical documentation burdens on European entrants. The EU AI Act adds algorithmic transparency requirements that reshape development roadmaps for machine-learning-based therapeutic software. Stakeholders must monitor divergence in national reimbursement catalogs as Germany's DiGA framework and Japan's Sakigake designation create parallel commercialization tracks with incompatible evidence standards.
Market Dynamics
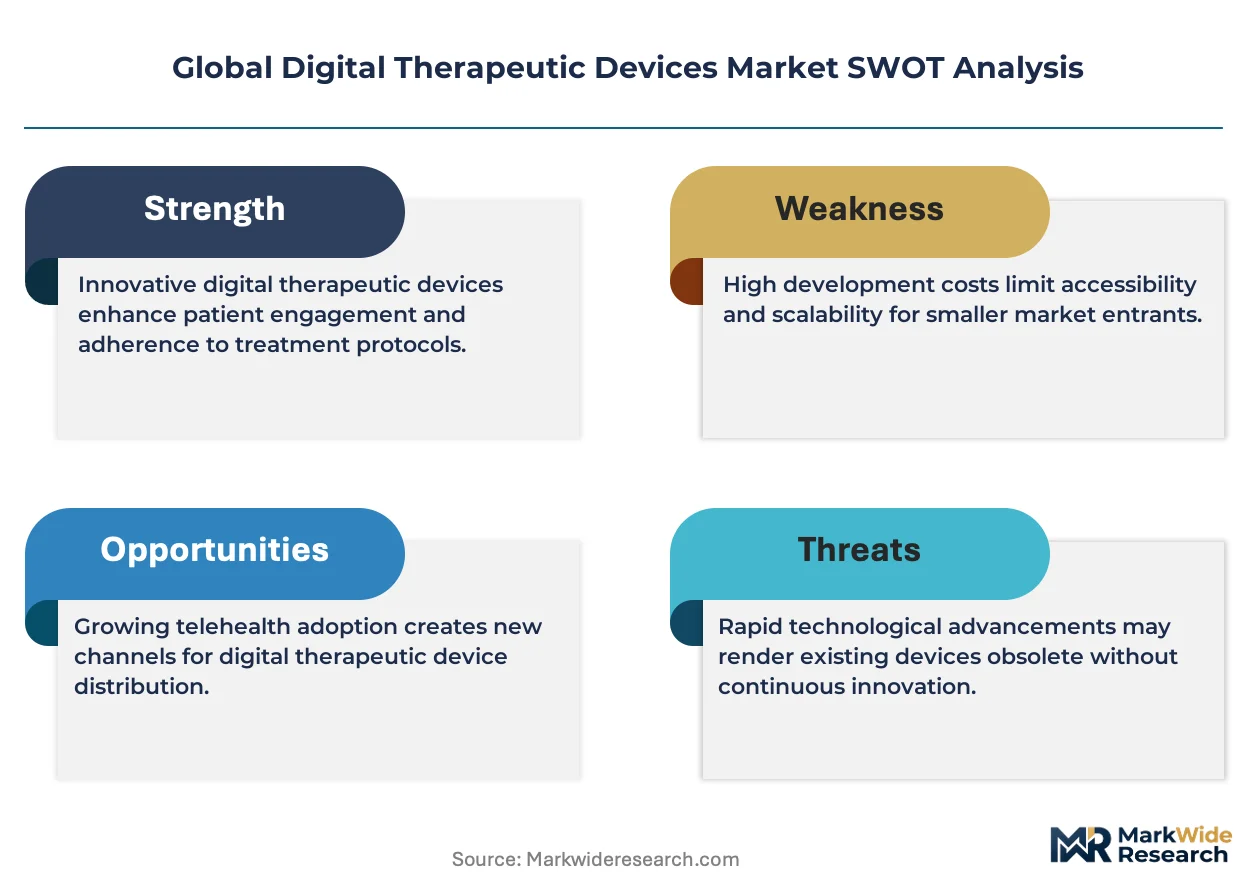
Reimbursement pathway fragmentation between Germany's DiGA framework, Japan's Sakigake designation, and the United States' evolving coverage codes is forcing developers to maintain parallel evidence-generation strategies for the same therapeutic software.
Growth Catalysts
- DiGA Fast-Track:Germany's statutory health insurance reimbursement catalog for prescription digital therapeutics compresses commercialization timelines for qualifying platforms.
- Chronic Disease Burden:Diabetes and cardiovascular management protocols are migrating from clinic-based care to smartphone-delivered behavioral interventions.
- Biosensor Miniaturization:Photoplethysmography and accelerometer accuracy improvements are enabling continuous physiological monitoring through consumer-grade wearables.
Market Restraints
- Clinical Validation Costs:Randomized controlled trial requirements for FDA 510(k) and De Novo pathways demand multi-million dollar evidence packages before commercial access.
- Algorithmic Opacity:Machine-learning-based therapeutic software faces heightened scrutiny under EU AI Act transparency mandates, extending development cycles.
- Physician Workflow Friction:Electronic health record integration complexity limits prescribing enthusiasm among time-constrained primary care providers.
Strategic Opportunities
- Pediatric Neurodevelopment:Attention-deficit therapeutic game interfaces remain underpenetrated relative to adult behavioral health applications.
- Japan's Sakigake:Priority review designation for regenerative medicine and breakthrough devices accelerates PMDA approval timelines for qualifying platforms.
- Remote Patient Monitoring:Convergence of continuous glucose monitors and insulin dosing algorithms creates closed-loop therapeutic ecosystems.
Industry Challenges
- Regulatory Science Talent:Shortage of professionals fluent in both clinical trial design and software lifecycle management slows submission preparation.
- Interoperability Certification:HL7 FHIR and proprietary health system integration requirements extend implementation timelines for health system contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Therapeutic Devices Market |
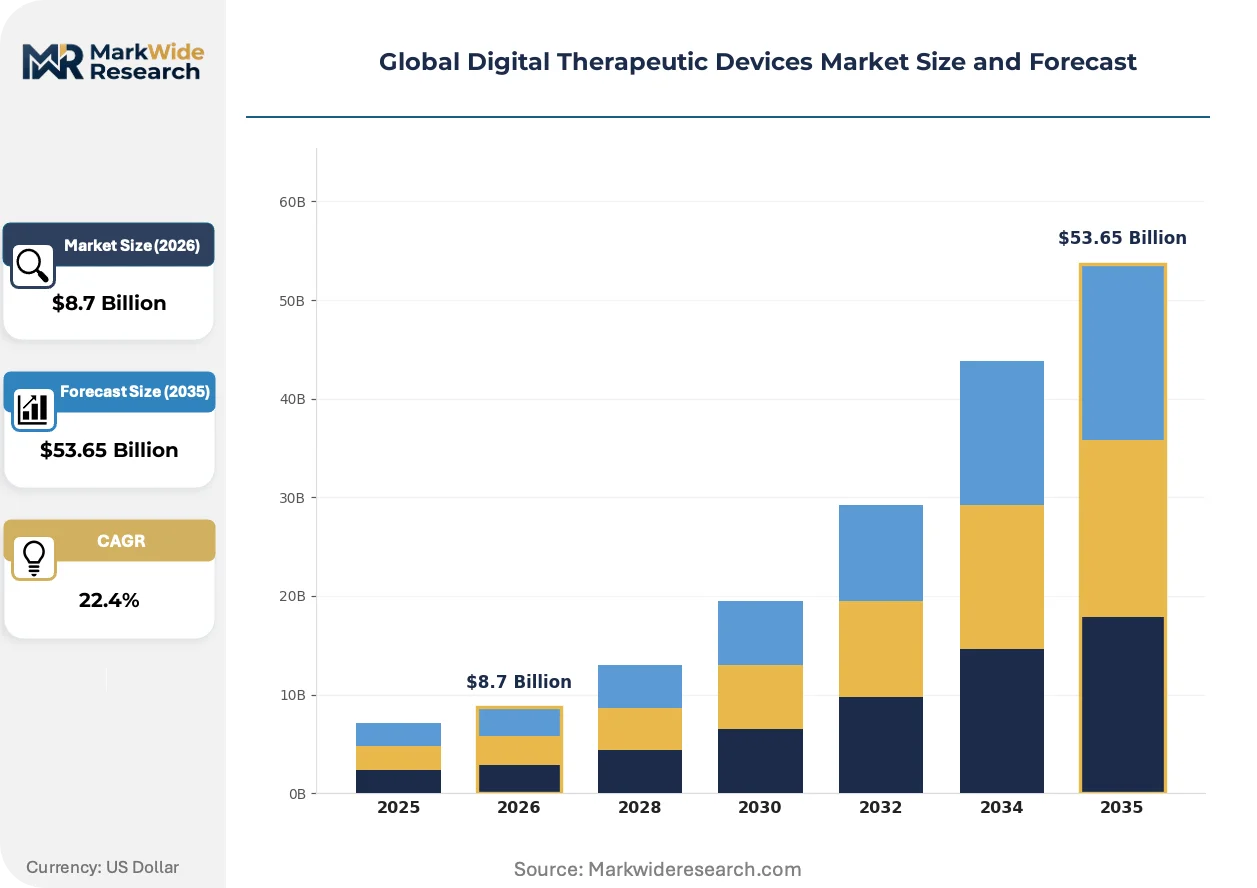
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Programs, Wearable Devices, Mobile Applications, Virtual Reality Systems Application: Chronic Disease Management, Behavioral Therapy, Cognitive Training, Pain Management End User: Hospitals, Mental Health Clinics, Rehabilitation Centers, Home Care Providers Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Platforms |
| Companies Covered | Omada Health, Inc., Pear Therapeutics, Inc., ResMed, WellDoc, Akili Interactive Labs, Inc., Biofourmis, Teladoc Health, Koninklijke Philips N.V., Proteus Digital Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Therapeutic Devices Market Shifts & Advancements
Algorithmic personalization is displacing one-size-fits-all therapeutic protocols across mental health and chronic disease management applications. Developers are embedding real-time biometric feedback loops to tighten adherence and outcome correlation.
Generative AI is automating adaptive cognitive behavioral therapy content generation, tailoring intervention intensity to patient-reported mood scores and passive behavioral signals. Mental health platforms are deploying these systems to reduce human coach dependency while maintaining therapeutic alliance. The compression of content production costs is enabling smaller developers to compete with established behavioral health incumbents.
EMA's Medical Device Regulation transition imposes heavier clinical documentation burdens on European software entrants relative to FDA's breakthrough device pathway. The divergence is redirecting early-stage commercialization energy toward United States and Japanese markets with clearer evidentiary thresholds. European developers are responding by front-loading post-market surveillance infrastructure to satisfy MDR periodic safety update requirements.
Health system procurement is consolidating vendor relationships around platforms demonstrating measurable hospital admission reduction. Payers are unbundling digital therapeutic reimbursement from traditional pharmaceutical contracts, creating direct-to-employer channels that bypass pharmacy benefit managers. This shift is most visible in United States self-insured employer populations seeking alternatives to escalating specialty pharmacy costs.
Global Digital Therapeutic Devices Market Segmentation
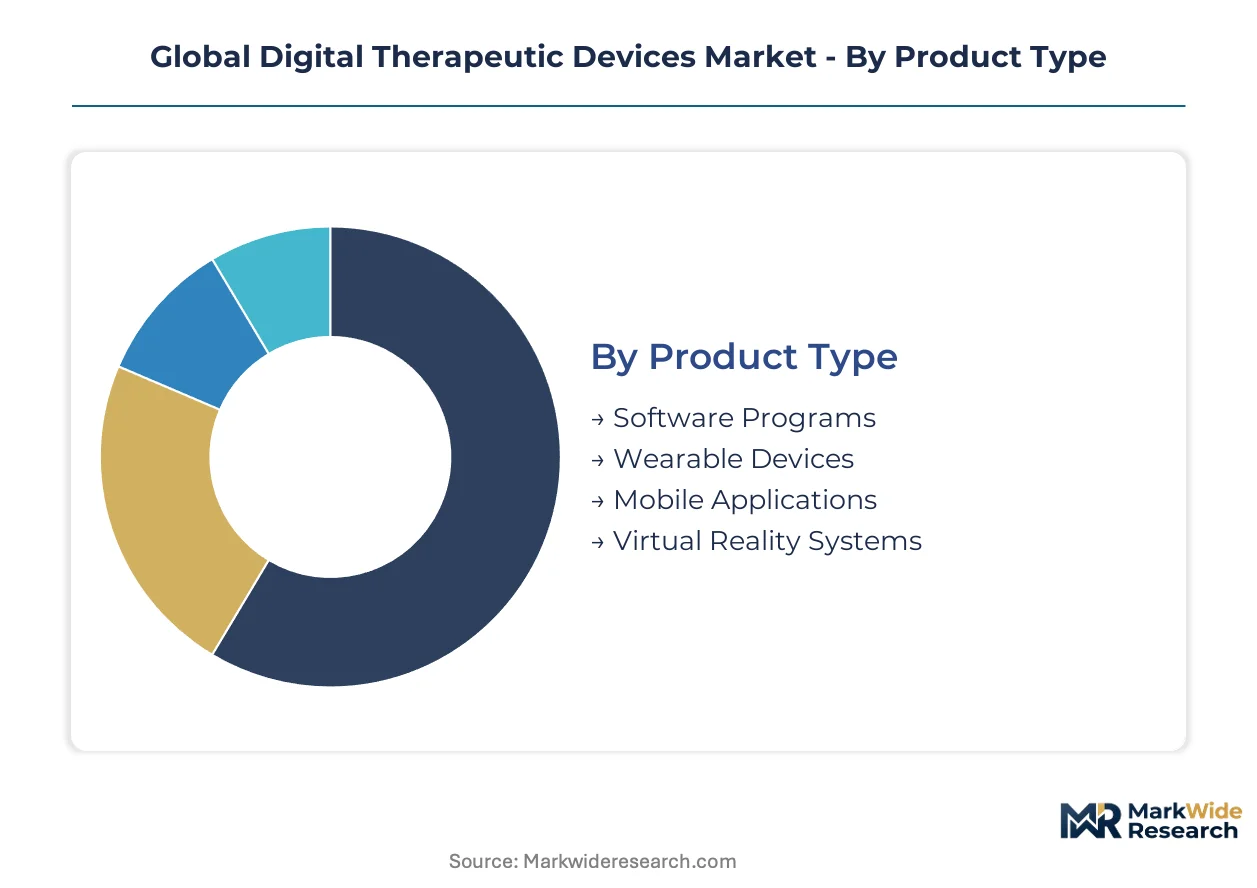
Digital therapeutic devices fragment across four critical dimensions that determine reimbursement pathways, regulatory requirements, and commercial scalability. Product architecture dictates evidence-generation costs. Application focus shapes payer contracting velocity. End-user channel selection determines integration complexity with clinical workflows.
Product Type:
Buyers prioritize total cost of ownership over upfront license fees, with integration and validation expenses often exceeding acquisition costs.
- Software Programs:Algorithm-driven therapeutic protocols delivered through smartphones or web portals dominate current revenue pools due to near-zero marginal distribution costs. Demand concentrates among United States payers seeking alternatives to specialty pharmacy spending, constrained by FDA De Novo pathway timelines.
- Wearable Devices:Biosensor-embedded hardware enabling continuous physiological monitoring is climbing the fastest as photoplethysmography accuracy improves and form factors shrink. Germany's DiGA framework accelerates reimbursement for qualifying continuous glucose monitor integrations.
- Mobile Applications:Smartphone-native therapeutic interfaces requiring clinical validation through randomized controlled trials. Japan's PMDA maintains distinct evidentiary thresholds for app-based interventions relative to hardware-coupled systems.
- Virtual Reality Systems:Immersive hardware delivering cognitive and exposure-based therapies through head-mounted displays. European adoption faces EMA MDR documentation burdens that compress margins.
Volume sits with Software Programs; growth tilts toward Wearable Devices.
Application:
Reimbursement consolidation velocity varies sharply by clinical domain, with mental health digital interventions achieving payer coverage faster than pain management alternatives.
- Behavioral Therapy:Cognitive behavioral therapy protocols delivered through digital platforms command premium pricing as United States commercial payers unbundle reimbursement from traditional pharmaceutical contracts. FDA breakthrough device designations for addiction and insomnia applications compress time-to-market.
- Chronic Disease Management:Diabetes and cardiovascular protocols migrating from clinic-based care to smartphone-delivered interventions. Germany's statutory health insurance catalog anchors European demand for hypertension and heart failure platforms.
- Cognitive Training:Neuroplasticity-focused software delivered through action video game interfaces. Pediatric neurodevelopment applications remain underpenetrated relative to adult behavioral health.
- Pain Management:Digital interventions for chronic pain face slower payer adoption due to outcome measurement complexity and opioid substitution sensitivities.
Revenue concentrates in Behavioral Therapy; steepest expansion trajectory belongs to Chronic Disease Management.
End User:
Procurement authority is shifting from individual clinicians to health system value analysis committees demanding admission reduction evidence.
- Hospitals:Integrated delivery networks consolidating vendor relationships around platforms demonstrating measurable length-of-stay reduction. Electronic health record integration requirements extend implementation timelines.
- Mental Health Clinics:Specialized outpatient facilities prescribing FDA-cleared prescription digital therapeutics for addiction and insomnia. Workflow friction limits enthusiasm among time-constrained providers.
- Rehabilitation Centers:Post-acute facilities deploying cognitive training and pain management protocols. Japan's Sakigake designation accelerates PMDA approval for regenerative medicine-adjacent platforms.
- Home Care Providers:Remote patient monitoring convergence with continuous glucose monitors and insulin dosing algorithms creates closed-loop therapeutic ecosystems.
Contract value peaks with Hospitals; fastest share gains occur in Home Care Providers.
Deployment:
Health system IT infrastructure maturity determines architecture preference, with cloud adoption accelerating among newer market entrants.
- Cloud-Based:Scalable infrastructure enabling real-time algorithmic personalization and biometric feedback loops. EU AI Act transparency mandates reshape development roadmaps for machine-learning-based therapeutic software.
- SaaS Platforms:Subscription models reducing upfront capital requirements for mental health clinics and small rehabilitation networks. Generative AI integration automates adaptive content generation.
- Hybrid:Mixed architectures balancing data sovereignty requirements with computational scalability. Germany's DiGA framework imposes specific interoperability standards.
- On-Premise:Localized deployment for health systems with strict data residency requirements. Implementation complexity limits penetration outside large integrated delivery networks.
Subscription volume favors SaaS Platforms; infrastructure investment flows toward Cloud-Based architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's algorithm development clusters anchor United States digital therapeutic innovation. Tel Aviv's startup density supplies machine-learning talent to European and Asian markets. Tokyo's precision manufacturing base enables biosensor miniaturization for wearable therapeutic hardware.
United States
Self-insured employers drive direct-to-payer contracting for diabetes prevention and behavioral health platforms. FDA's breakthrough device pathway compresses De Novo review timelines for qualifying software. Boston's health system density anchors clinical validation partnerships for prescription digital therapeutics targeting addiction management.
Germany
Statutory health insurance funds anchor European reimbursement for hypertension and heart failure digital interventions. The DiGA fast-track framework mandates specific interoperability standards for cloud-based therapeutic software. Berlin's health tech cluster concentrates post-market surveillance infrastructure builders serving MDR compliance requirements.
Japan
Aging demographics accelerate demand for home-based cognitive training and chronic disease management platforms. PMDA's Sakigake priority review designation compresses approval timelines for breakthrough therapeutic devices. Osaka's medical device manufacturing corridor supplies miniaturized biosensor components for continuous glucose monitor integrations.
Israel
Defense technology spinoffs supply machine-learning engineering talent to algorithm-driven therapeutic developers. The national digital health strategy channels government funding toward clinical validation infrastructure. Tel Aviv's venture capital density enables early-stage funding for behavioral coaching protocol developers seeking CE marking pathways.
United Kingdom
NHS England's digital-first patient care mandate creates procurement demand for mental health and chronic disease platforms. MHRA's Software as a Medical Device guidance imposes distinct evidentiary requirements relative to FDA pathways. London's health system integration specialists concentrate on HL7 FHIR certification services for EHR-embedded therapeutics.
Global Digital Therapeutic Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pediatric neurodevelopment and generative AI content automation. The vendor base stratifies across three tiers: FDA-cleared prescription digital therapeutic specialists, wellness-to-medical bridge platforms, and hardware-coupled biosensor developers. Two dominant competitive moves reshape positioning: health system EHR integration partnerships that lock in prescribing workflows, and DiGA framework pre-certification investments that secure German statutory reimbursement.
Within the prescription digital therapeutic tier, Pear Therapeutics and Omada Health exemplify divergent archetypes. Pear Therapeutics occupies the FDA-cleared specialty position across addiction and insomnia indications. Omada Health anchors behavioral coaching protocols for diabetes prevention among self-insured employers. Akili Interactive Labs represents the cognitive training game interface specialization targeting pediatric neurodevelopment gaps. Each firm situates within distinct reimbursement channel strategies—Pear Therapeutics through pharmacy benefit managers, Omada Health through direct employer contracting, and Akili Interactive Labs through specialty pharmacy networks seeking alternatives to traditional pharmaceutical spend.
| Leading Market Players |
|---|
| Omada Health, Inc. |
| Pear Therapeutics, Inc. |
| ResMed |
| WellDoc |
| Akili Interactive Labs, Inc. |
| Biofourmis |
| Teladoc Health |
| Koninklijke Philips N.V. |
| Proteus Digital Health |
| Others |
Supply & Pricing Matrix
Captive software development teams in United States and Israeli clusters anchor both supply security and pricing power for algorithm-driven therapeutic platforms, insulating developers from third-party engineering cost volatility while compressing marginal distribution economics. This vertical integration into clinical validation and regulatory affairs functions concentrates cost control among established players.
Pricing Analysis
Warranty and post-market surveillance bundling separates FDA-cleared prescription digital therapeutics from wellness-adjacent applications, with the former commanding SaaS subscription premiums tied to outcome guarantees. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth: FDA breakthrough device designation and Germany's DiGA pre-certification anchor premium tiers, while CE-marked wellness platforms compete on price. Cost compression in standard-tier behavioral health applications intensifies as generative AI content automation reduces human coach dependency. Self-insured employer populations exhibit lowest price sensitivity due to specialty pharmacy cost avoidance calculus, while small mental health clinics face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements for photoplethysmography sensors and accelerometer modules compel hardware-coupled therapeutic developers to qualify suppliers across Japan, Taiwan, and South Korea. Raw material dependencies center on silicon wafer substrates, lithium-polymer cells, and medical-grade polymer housings. Single-source vulnerability in specialized biosensor foundries concentrates risk for continuous glucose monitor integrations. Distribution runs through health system value analysis committees and direct-to-employer channels, bypassing traditional pharmaceutical wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical validation infrastructure scarcity props pricing for FDA-cleared platforms, as multi-million dollar randomized controlled trial requirements filter out undercapitalized entrants and sustain incumbent margin structures.
For Market Incumbents: Acquire post-market surveillance infrastructure builders to satisfy EMA MDR periodic safety update requirements and compress European compliance timelines. Lock in health system EHR integration partnerships through HL7 FHIR certification investments, defending against workflow friction that limits prescribing enthusiasm among primary care providers. Vertical integration into generative AI content generation preserves therapeutic alliance quality while reducing human coach dependency costs. For New Entrants and Emerging Players: Specialty pharmacy networks seeking alternatives to traditional pharmaceutical spend represent the most penetrable channel for pediatric neurodevelopment platforms targeting attention-deficit indications. Japan's Sakigake priority review designation offers faster regulatory validation than FDA De Novo pathways for qualifying cognitive training game interfaces. White-space concentration in home care provider closed-loop ecosystems—combining continuous glucose monitors with insulin dosing algorithms—permits bypass of hospital procurement consolidation. For Investors and Strategic Acquirers: Exit pathways concentrate in health system EHR integration specialists and DiGA framework pre-certification holders, with acquisition premiums accruing to platforms demonstrating measurable hospital admission reduction. Long-term viability hinges on reimbursement catalog inclusion velocity across Germany, Japan, and United States markets. Watch FDA breakthrough device designation grant rates as inflection indicator for regulatory risk appetite in algorithm-driven therapeutics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Compresses De Novo review timelines for qualifying software platforms seeking prescription status. |
| DiGA Pre-Certification Investment | Secures German statutory health insurance reimbursement eligibility ahead of commercial launch. |
| Hospital System EHR Integration | Locks prescribing workflows through HL7 FHIR certification and reduces physician friction. |
| Generative AI Content Automation | Reduces human coach dependency while maintaining therapeutic alliance in mental health platforms. |
| Continuous Glucose Monitor Partnership | Creates closed-loop therapeutic ecosystems converging biosensor hardware with insulin dosing algorithms. |
Research Methodology
Document review covered FDA 510(k) and De Novo clearance databases, EMA MDR transition guidance, and Japan PMDA Sakigake designation records, complemented by interviews with digital therapeutic developers, health system value analysis committee members, and payer formulary directors. Secondary validation drew from clinical trial registries, GPO contract databases, and statutory health insurance reimbursement catalogs. Bottom-up segment sizing triangulated against top-down market aggregation across software programs, wearable devices, and immersive hardware categories.
Cross-referencing historical reimbursement adoption curves against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, application focus, end-user channel, and deployment model, with regional regulatory cluster as an additional healthcare-specific dimension. CAGRs derived from algorithmic personalization adoption trajectories and biosensor miniaturization cost curves, calibrated against chronic disease management platform migration rates from clinic-based to smartphone-delivered care.
Caveats apply where FDA evidentiary requirement shifts or EMA MDR enforcement intensity changes could materially shift the outlook. Deviation in Germany's DiGA framework inclusion velocity or Japan's Sakigake approval timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
EMG Biosensors Market
Medical Devices
Ablation Devices Market
Medical Devices
Bunion Correction Systems Market
Medical Devices
Graft Delivery Devices Market
Medical Devices
Intervertebral Implants Market
Medical Devices
Leadless Pacemakers Market
Medical Devices
Dosing Units Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
Flexible Spinal Implants Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
India Static Compression Therapy Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Automated CPR Devices Market
Medical Devices
Cervical Implants Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market