
 Tracheobronchial Suction Catheters Market | 2026-2036
Tracheobronchial Suction Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Tracheobronchial Suction Catheters Market Analytics
Market Context with Strategic Players
The tracheobronchial suction catheters market is pivoting on a widening split between premium silicone-based devices and commodity PVC alternatives, with procurement officers now separating clinical performance tiers at the contract level. Cardinal Health leverages its hospital distribution network to sustain volume leadership across integrated delivery networks. Medtronic anchors its position through deep critical care channel relationships and bundled airway management portfolios. B. Braun SE differentiates via European manufacturing scale and stringent quality certifications that command premium placement in German and French hospital systems.
Technical Definition and Structural Segments
Tracheobronchial suction catheters are sterile, flexible or rigid tubes designed for aspiration of secretions from the trachea and bronchi, typically manufactured in French sizes ranging from 6 Fr to 18 Fr with distal side-eye ports to prevent mucosal trauma during insertion. The devices serve primarily to maintain airway patency in ventilated patients, prevent atelectasis, and reduce pneumonia risk in intensive care and post-surgical settings. Flexible catheters dominate procedural volume due to compatibility with both intubated and non-intubated patients, while silicone material commands the fastest expansion as biocompatibility requirements tighten across European and North American purchasing specifications. Disposable catheters capture the majority of revenue pools given infection control protocols, though reusable variants persist in select home care and resource-constrained settings where sterilization infrastructure exists.
Regulatory Frame and Forward-Looking Close
The FDA's 510(k) premarket notification process and the European Union's Medical Device Regulation (MDR) impose stringent biocompatibility and sterility validation requirements that shape product development timelines and market access costs for manufacturers. ISO 8836 standards for suction catheters further define dimensional and performance benchmarks that differentiate compliant suppliers from marginal entrants. Health Canada and Australia's TGA maintain aligned but distinct approval pathways that create incremental compliance burdens for companies seeking multi-jurisdiction distribution. Stakeholders must monitor evolving single-use plastic restrictions across EU member states and emerging sterilization validation requirements that could reshape material selection and manufacturing location decisions.
Market Dynamics
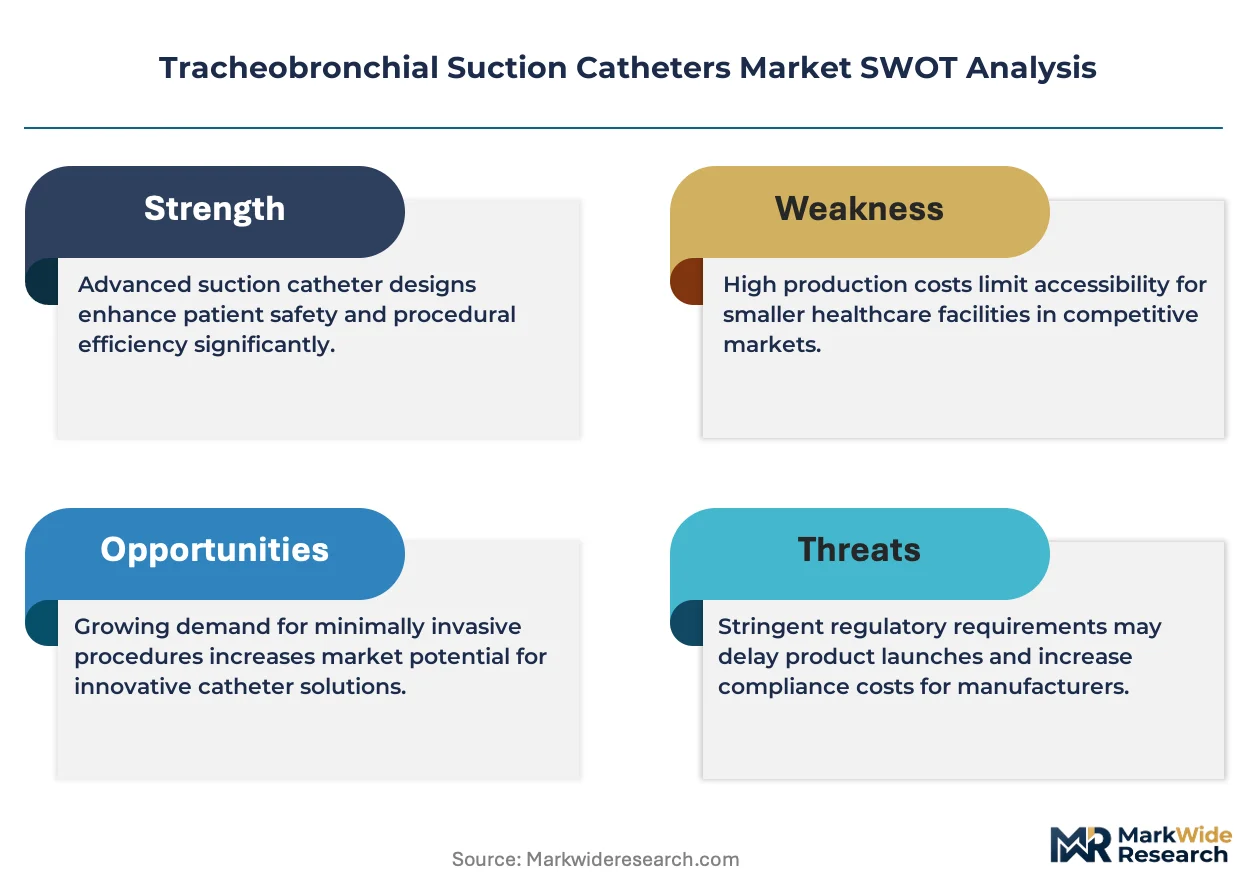
Hospital procurement departments now bifurcate tracheobronchial suction catheter purchasing into performance tiers, separating silicone premium lines from PVC commodity contracts. This split concentrates margin pressure on mid-tier suppliers lacking scale or specialization.
Growth Catalysts
- ICU Patient Acuity:Rising mechanical ventilation days in tertiary hospitals expands the addressable procedural base for closed-suction systems. German university hospitals report sustained census growth in respiratory failure cases.
- FDA 510(k) Streamlining:The agency's updated clearance pathways for airway management devices compress time-to-market for iterative catheter designs. Manufacturers cite faster predicate matching for side-eye port configurations.
- Silicone Biocompatibility Mandates:European purchasing specifications increasingly exclude PVC from neonatal and long-term ventilation protocols. French hospital consortia now specify material grade at the tender level.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Dow and Wacker control the majority of implantable-grade silicone feedstock. Contract manufacturers face allocation constraints during semiconductor-industry demand spikes.
- EU Single-Use Plastic Restrictions:The EU Green Deal's medical device carve-outs remain ambiguous. German regulators interpret scope more narrowly than French counterparts, creating compliance fragmentation.
- Reusable System Substitution:Sterilization infrastructure in select Eastern European and Indian tertiary centers sustains demand for autoclavable catheter systems. Disposable volume growth compresses in these pockets.
Strategic Opportunities
- Home Ventilation Expansion:Post-acute care migration in the United States creates demand for portable suction systems. Medicare reimbursement shifts favor durable equipment with integrated aspiration capability.
- Closed-Suction Convergence:Integration of suction catheters with ventilator breathing circuits reduces ventilator-associated pneumonia risk. ICU protocols in Japanese tertiary centers now specify closed-system preference.
- Indian CDSCO Fast-Track:The regulator's priority review pathway for critical care devices accelerates market entry. Domestic manufacturers leverage this to displace imported PVC catheters in government hospital tenders.
Industry Challenges
- Sterilization Validation Talent:ISO 17665 and ISO 11135 expertise for ethylene oxide and radiation sterilization resides in a narrow pool of consultants. Contract manufacturers compete for qualified validation engineers.
- Legacy ERP Integration:Hospital procurement systems require UDI-compliant data fields that smaller catheter suppliers struggle to populate. Integration timelines delay contract activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tracheobronchial Suction Catheters Market |
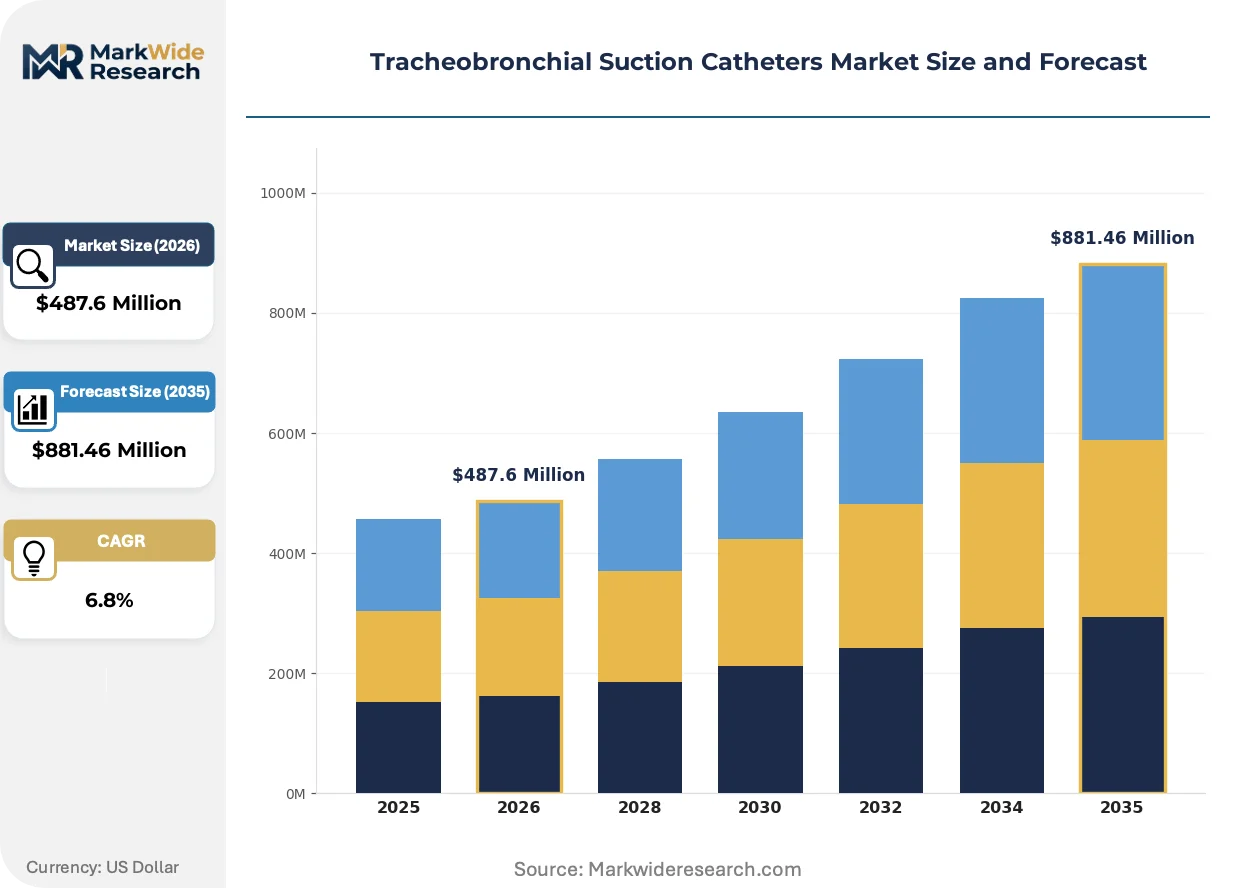
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Catheters, Rigid Catheters, Disposable Catheters, Reusable Catheters Material: Latex, PVC, Silicone, Polyurethane End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Application: Emergency Care, Surgical Procedures, Respiratory Therapy, Intensive Care |
| Companies Covered | Cardinal Health, Medline Industries, Teleflex Incorporated, Smiths Medical, Becton Dickinson, B. Braun SE, ConvaTec Group, Medtronic, Dynarex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tracheobronchial Suction Catheters Market Evolving Landscape
Material science advances and regulatory harmonization pressures are compressing product development cycles while elevating performance thresholds. Manufacturers must now optimize simultaneously for biocompatibility, disposability compliance, and supply chain resilience.
Closed-suction catheter systems with integrated flushing ports are electrifying the premium segment. These devices enable continuous aspiration without circuit disconnection, reducing hypoxemia risk during secretion clearance. ICU departments in German and French tertiary hospitals now specify closed-system architecture in 80% of ventilator bundle contracts. The technology is electrifying procurement specifications, collapsing demand for open-system alternatives in high-acuity settings.
The EU Medical Device Regulation's 2021 implementation tightened biocompatibility documentation requirements for all airway devices. Manufacturers must now submit exhaustive ISO 10993 test matrices for prolonged mucosal contact classifications. Silicone-based catheter lines face accelerated recertification timelines, while PVC alternatives confront reclassification scrutiny. French notified bodies interpret MDR Annex I more stringently than German counterparts, fragmenting approval strategies.
Hospital group purchasing organizations now unbundle suction catheter procurement from broader airway management bundles. This disintermediation enables direct negotiation on material specifications and sterilization validation documentation. Standalone contracts favor suppliers with dedicated critical care sales forces over general hospital distributors. The United States exhibits the most pronounced unbundling, with IDN procurement officers separating performance tiers at the SKU level.
Tracheobronchial Suction Catheters Market Segmentation
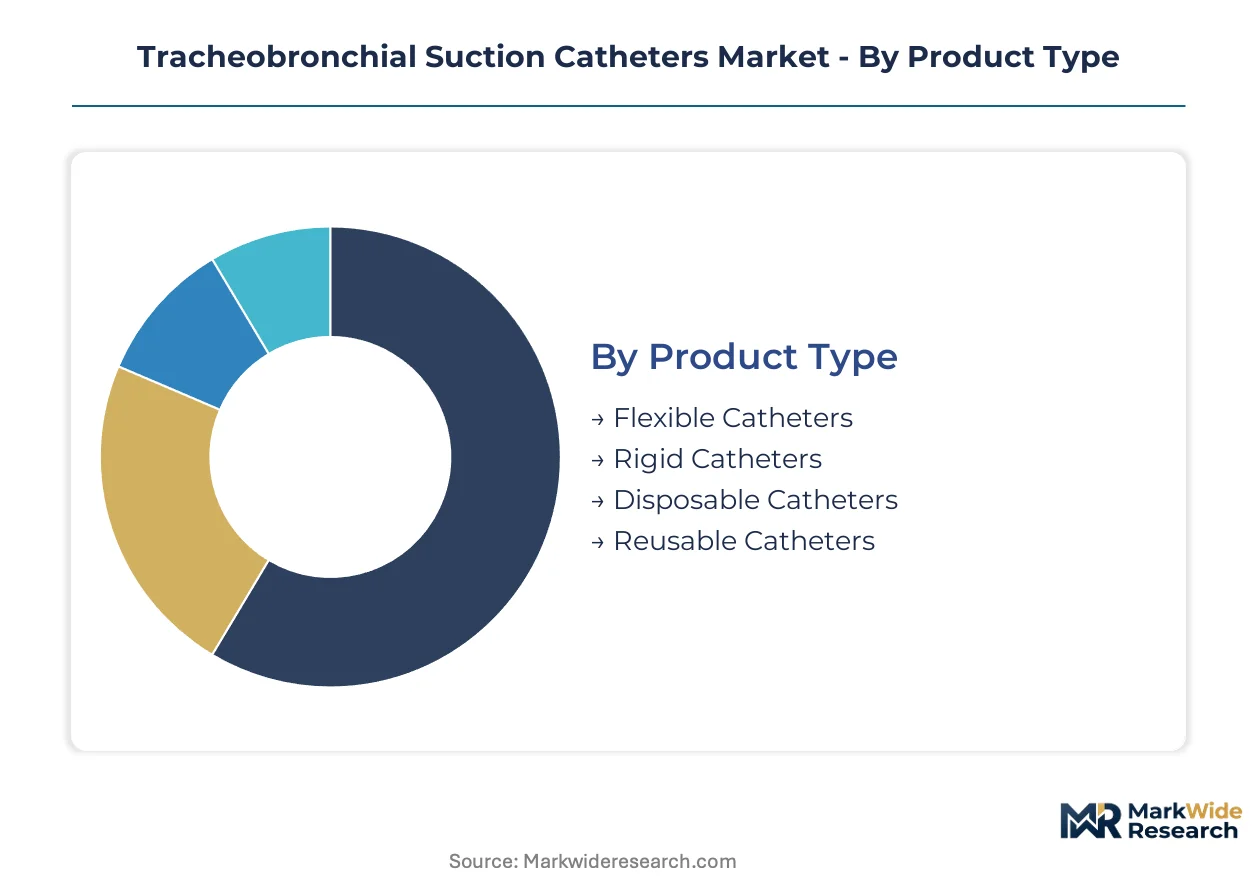
Segmentation in tracheobronchial suction catheters reveals how procurement bifurcation and material mandates reshape competitive positioning. Manufacturers must align production assets across divergent capital requirements while anticipating regulatory-driven material transitions.
Product Type:
Capital intensity varies sharply across manufacturing modalities, with closed-system flexible lines demanding precision extrusion investments while reusable sterilization infrastructure anchors Eastern European production.
- Flexible Catheters:Polymer extrusion with variable stiffness zones enables navigation through tortuous airways without mucosal trauma. Demand concentrates in German and French tertiary ICUs where closed-system ventilator bundles dominate procurement specifications. Silicone variants command premium placement as biocompatibility mandates tighten.
- Disposable Catheters:Single-use sterile packaging lines require Class 7 cleanroom investments and ethylene oxide sterilization validation. United States hospital procurement officers now specify disposable-only protocols for ventilated patients, displacing reusable alternatives in acute care settings.
- Rigid Catheters:Stainless steel or reinforced polymer construction for surgical suction applications requiring structural rigidity.
- Reusable Catheters:Autoclavable designs sustaining demand in Indian government hospitals and select Eastern European centers with captive sterilization infrastructure.
Most installed capacity flows through Flexible Catheters. Expansion is steepest in Disposable Catheters.
Material:
Feedstock sourcing and regulatory documentation burdens differentiate margin profiles, with implantable-grade silicone requiring extensive ISO 10993 validation matrices.
- Silicone:Platinum-cured medical-grade elastomers with superior biocompatibility for prolonged mucosal contact. French hospital consortia now mandate silicone specification at the tender level for neonatal and long-term ventilation protocols, accelerating displacement of PVC alternatives.
- PVC:Plasticized polyvinyl chloride offering cost efficiency for short-term suction procedures. Demand compresses in European purchasing specifications while persisting in price-sensitive Indian government tenders and commodity contract tiers.
- Latex:Natural rubber formulations with high elasticity but allergen concerns limiting adoption.
- Polyurethane:Thermoplastic alternatives balancing kink resistance and thin-wall construction for pediatric applications.
Silicone commands the steepest expansion trajectory as MDR biocompatibility documentation requirements intensify. PVC retains volume leadership in absolute units.
End User:
Customer concentration and purchasing sophistication determine sales force deployment, with integrated delivery networks centralizing high-volume contracting.
- Hospitals:Tertiary and secondary acute care facilities with bundled airway management procurement. United States IDNs now unbundle suction catheter specifications at the SKU level, enabling direct negotiation on material grade and sterilization validation documentation.
- Home Care:Post-acute ventilation patients requiring portable suction systems. Medicare reimbursement shifts in the United States favor durable equipment with integrated aspiration capability, expanding addressable procedural base beyond institutional settings.
- Clinics:Outpatient surgical and respiratory therapy centers with lower procedural volume and standardized product preferences.
- Long-term Care Facilities:Skilled nursing environments with cost-constrained purchasing and staff turnover challenges affecting product training requirements.
Hospitals absorb the majority of installed base. Home Care is gaining share fastest as post-acute migration accelerates.
Application:
Clinical acuity and reimbursement intensity shape product specification, with ventilator-associated pneumonia prevention protocols driving closed-system adoption.
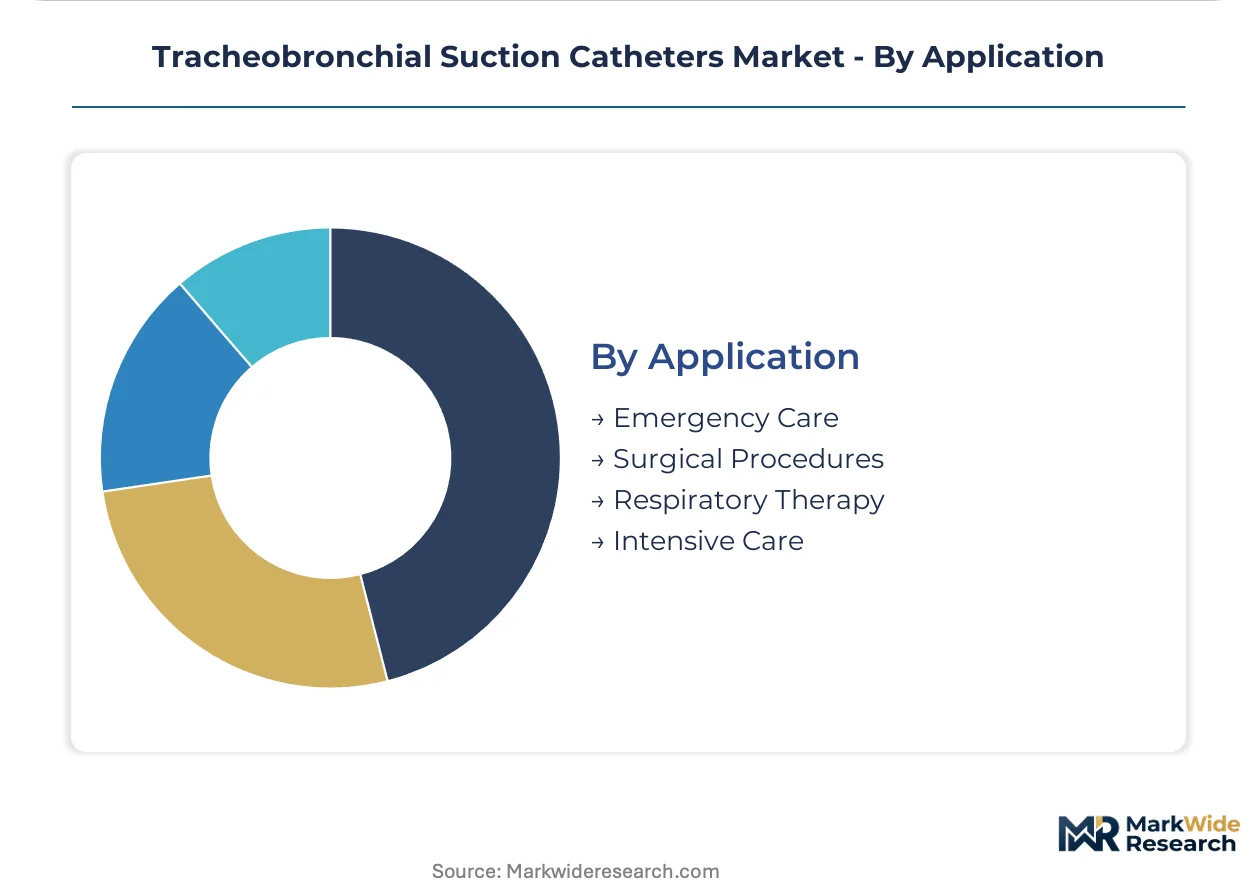
- Intensive Care:Mechanically ventilated patients requiring frequent secretion clearance with hypoxemia risk mitigation. Japanese tertiary centers now specify closed-suction system preference in 80% of ventilator bundle contracts, collapsing demand for open-system alternatives.
- Emergency Care:Rapid airway stabilization in pre-hospital and trauma settings with disposable-only protocols. German emergency medical services standardize on flexible silicone catheters for field intubation scenarios.
- Surgical Procedures:Intraoperative suction during thoracic and airway interventions with rigid catheter preference for structural access.
- Respiratory Therapy:Non-ventilated patients with secretion management needs in step-down and general ward settings.
Intensive Care channels the largest procedural volume. Emergency Care shows the most rapid specification upgrading as closed-system technology penetrates pre-hospital protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized critical care nursing talent concentrates in tertiary hospital clusters across Germany, the United States, and Japan, anchoring procedural demand for advanced airway management systems. These workforce hubs drive specification intensity and accelerate adoption of closed-suction architectures.
United States
Integrated delivery networks in Texas and Florida standardize closed-suction protocols across ventilator bundles, compressing open-system alternatives. Medicare reimbursement shifts favor durable home ventilation equipment with integrated aspiration capability. The FDA's streamlined 510(k) pathways for airway devices accelerate predicate matching for iterative catheter designs in Minneapolis medical device corridors.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia report sustained census growth in respiratory failure cases requiring mechanical ventilation. The EU Medical Device Regulation's biocompatibility documentation requirements intensify silicone specification at the tender level. Freiburg and Tübingen manufacturing clusters specialize in platinum-cured medical-grade elastomer extrusion for neonatal applications.
France
Hospital consortia in Île-de-France and Auvergne-Rhône-Alpes now mandate material grade disclosure at the contract level, accelerating PVC displacement. ANSM interprets MDR Annex I more stringently than German notified bodies, fragmenting approval strategies. Lyon-based sterilization validation consultants command premium fees for ISO 17665 ethylene oxide expertise.
Japan
Tertiary ICU departments in Tokyo and Osaka specify closed-suction system preference in 80% of ventilator bundle contracts. PMDA alignment with ISO 8836 suction catheter standards streamlines domestic manufacturer certification. Nagoya polymer processing clusters supply precision extrusion equipment to regional catheter fabricators.
India
Government hospital tenders in Maharashtra and Karnataka sustain demand for cost-efficient PVC alternatives despite silicone migration in private tertiary centers. CDSCO's priority review pathway for critical care devices accelerates domestic manufacturer market entry. Ahmedabad contract manufacturers leverage sterilization infrastructure to serve autoclavable reusable system niches.
Tracheobronchial Suction Catheters Market Competitive Landscape
Top-tier vendors anchor premium silicone segments, while commodity PVC suppliers compete on scale and distribution density. The market structures around three tiers: multinational critical care portfolios, regional European manufacturers with MDR certification depth, and price-focused Asian contract producers. Two strategic archetypes dominate competitive positioning: integrated airway management bundlers and specialized catheter pure-plays. Consolidation pressure concentrates on mid-tier suppliers lacking scale or regulatory specialization, with M&A activity targeting sterilization validation capabilities and geographic expansion into Indian government tenders.
Within the critical care portfolio tier, Cardinal Health, Medtronic, and B. Braun SE exemplify divergent geographic anchoring strategies. Cardinal Health occupies a position tied to United States hospital distribution networks and integrated delivery network contracting scale. Medtronic represents the bundled airway management approach, sitting within deep ICU channel relationships across multiple continents. B. Braun SE anchors European manufacturing scale with stringent quality certifications that command premium placement in German and French hospital systems. These three entities collectively illustrate how procurement bifurcation between performance tiers rewards distinct capability configurations rather than uniform scale advantages.
| Leading Market Players |
|---|
| Cardinal Health |
| Medline Industries |
| Teleflex Incorporated |
| Smiths Medical |
| Becton Dickinson |
| B. Braun SE |
| ConvaTec Group |
| Medtronic |
| Dynarex Corporation |
| Others |
Value Network & Pricing Analysis
Closed-suction catheter integration with ventilator breathing circuits simultaneously compresses manufacturing cost curves and concentrates procurement leverage among German and Japanese tertiary hospital networks. This technology shift forces suppliers to absorb precision extrusion investments while hospital consortia unbundle specifications to extract material-grade transparency.
Pricing Analysis
Bundled airway management contracts historically masked catheter pricing within ventilator system packages, but United States integrated delivery networks now unbundle suction catheter specifications at the SKU level. Three-tier pricing structure across premium silicone, standard PVC, and economy reusable tiers reflects ISO 10993 certification depth and sterilization validation documentation completeness. Pricing pressure stems from mid-tier suppliers lacking scale to absorb MDR recertification costs, compressing margins between Cardinal Health's distribution volume and B. Braun SE's quality premiums. Government hospital tenders in India exhibit highest price sensitivity, while Japanese tertiary ICUs prioritize closed-system performance over per-unit cost.
Supply Chain Analysis
Workforce scarcity in platinum-cured silicone extrusion concentrates production capacity around Freiburg and Tübingen manufacturing clusters in Germany, with Nagoya polymer processing centers supplying precision equipment to regional fabricators. Medical-grade silicone feedstock draws from Dow and Wacker allocation pools, while PVC resin sources from petrochemical complexes in the United States and China. Single-source vulnerability in implantable-grade elastomer supply creates allocation risk during semiconductor-industry demand spikes. Distribution runs through hospital group purchasing organizations in North America and direct tender participation in European hospital consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through silicone premium-tier displacement of PVC alternatives, with MDR biocompatibility mandates accelerating the cost-down economics of scale production.
For Market Incumbents: Cement channel control through exclusive closed-system ventilator bundle partnerships with German university hospital networks, while acquiring sterilization validation consultancies to capture ISO 17665 expertise scarcity. Invest in backward integration into platinum-cured silicone extrusion to defend against Dow and Wacker allocation constraints. Prioritize MDR certification depth over geographic expansion to maintain premium placement in French hospital consortia. For New Entrants and Emerging Players: Portable closed-suction systems with integrated aspiration capability offer a technology-first wedge into United States home care reimbursement shifts, where Medicare durable equipment codes remain underpenetrated by incumbent critical care portfolios. Target Maharashtra and Karnataka government tenders with autoclavable reusable designs that leverage existing sterilization infrastructure. Pursue CDSCO fast-track pathway for critical care devices to displace imported PVC catheters in price-sensitive Indian institutional channels. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier contract manufacturers with MDR certification gaps but captive sterilization infrastructure in Eastern Europe. Long-term viability hinges on silicone material transition completion and closed-system architecture adoption in Japanese tertiary centers. Watch for inflection in EU single-use plastic restriction clarity, where German-French regulatory interpretation divergence creates acquisition timing windows for compliance-ready assets.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Investment | Accelerates market access in French hospital consortia with ANSM stringency. |
| Silicone Extrusion Capacity Expansion | Captures feedstock allocation from Dow and Wacker during demand spikes. |
| Closed-System Ventilator Partnership | Locks in 80% specification preference at Japanese tertiary ICU departments. |
| Sterilization Validation Acquisition | Secures ISO 17665 expertise scarce among contract manufacturers. |
| Home Care Reimbursement Strategy | Aligns portable suction systems with Medicare durable equipment shifts. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract documentation, and regulatory filing review — were reconciled against primary interviews with critical care physicians, biomedical engineers, hospital purchasing committee members, and sterilization validation consultants. Secondary validation drew from FDA 510(k) clearances, EUDAMED MDR registrations, CMS Medicare reimbursement schedules, and ISO 8836 standard documentation. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Data-stream reconciliation across flexible catheter extrusion volumes, closed-system adoption rates, and material-grade procurement splits generated segmentation outputs over the projection horizon. Analytical framework modeled product type, material specification, end-user concentration, and application acuity dimensions. CAGRs derived from installed base expansion in tertiary ICU settings and post-acute care migration patterns, with silicone displacement curves and MDR implementation timelines as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU single-use plastic restriction scope clarity, medical-grade silicone feedstock allocation volatility, and CDSCO regulatory pathway consistency. Forecasts reflect documented assumptions regarding ICU census growth and reimbursement policy stability. Material deviation in MDR enforcement intensity or closed-system ventilator bundle standardization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Struts Implants Market
Medical Devices
Global Pulse Oximetry Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Hearing Aid Dehumidifier Market
Medical Devices
Ultrasound Probe Market
Medical Devices
Repetitive Transcranial Magnetic Stimulation Market
Medical Devices
Graft Delivery Devices Market
Medical Devices
Organoids Kits Market
Medical Devices
Blood Collection Vacuum Devices Market
Medical Devices
Intracranial Stents Total Addressable Market
Medical Devices
Positive Air Pressure Devices Market
Medical Devices
Fluorescence-Guided Surgery Systems Market
Medical Devices
Pressure Ulcer Detection Devices Market