
 Europe Serine Proteases Market | 2026-2036
Europe Serine Proteases Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Serine Proteases Market Intelligence
The EU Green Deal's emphasis on sustainable biomanufacturing is restructuring procurement priorities for serine proteases across Europe. Novozymes A/S leverages its significant R&D investment in enzyme engineering to meet these new sustainability benchmarks. Concurrently, BASF SE specializes in large-scale production for industrial applications, focusing on cost and efficiency. Merck KGaA differentiates through its portfolio of high-purity enzymes for pharmaceutical and diagnostic end-users.
Serine proteases are a family of proteolytic enzymes defined by the presence of a crucial serine residue within their active site. Their primary function is to catalyze the cleavage of peptide bonds in proteins, a fundamental process in biotechnology and diagnostics. Within product types, trypsin maintains a dominant position due to its widespread use in proteomics and cell culture applications. The drug development application segment shows the most significant growth trajectory, driven by biologic drug discovery.
The European Medicines Agency (EMA) imposes strict quality and consistency standards on proteases used in biopharmaceutical manufacturing. Concurrently, compliance with REACH regulations affects the chemical components used in enzyme stabilization and formulation within the EU. Future success for enzyme producers hinges on their ability to navigate the complex validation pathways for novel bio-engineered proteases.
Market Dynamics
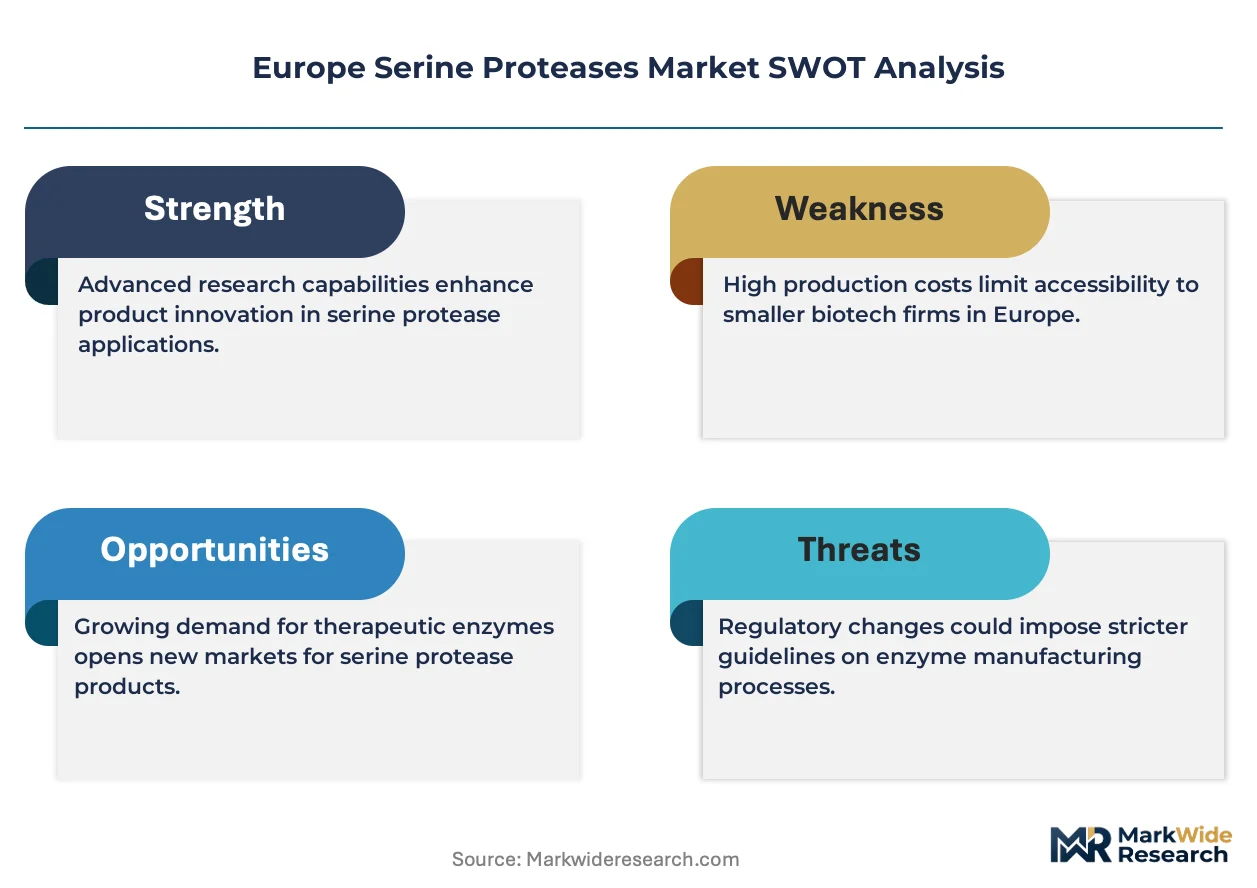
The convergence of stringent clinical regulations and sustainability mandates defines the competitive landscape for serine proteases in Europe. The EU's Medical Device Regulation (MDR) elevates validation requirements, while the Green Deal simultaneously promotes biomanufacturing, creating a dual pressure for high-purity, sustainably sourced enzymes.
Growth Catalysts
- Biopharmaceutical Expansion:Robust investment in biologic drug discovery, particularly for monoclonal antibodies and cell therapies, creates consistent demand for high-purity proteases like trypsin for protein characterization and cell culture detachment.
- Regulatory Scrutiny:The European Union's Medical Device Regulation (MDR) imposes stricter validation and documentation requirements for diagnostic reagents, compelling manufacturers to use well-characterized, high-grade enzymes to ensure assay accuracy and reproducibility.
- Food & Beverage Innovation:Demand for proteases in the food processing industry for applications like dough conditioning, meat tenderization, and dairy modification is expanding, driven by consumer preference for clean-label ingredients and improved product textures.
Market Restraints
- High Production Costs:Manufacturing pharmaceutical-grade serine proteases requires significant investment in GMP-compliant facilities, downstream purification processes, and extensive quality control, leading to high unit costs that can limit adoption in price-sensitive applications.
- Regulatory Validation Hurdles:The European Medicines Agency (EMA) imposes a complex and lengthy approval process for novel bio-engineered proteases used as processing aids in drug manufacturing, slowing the introduction of innovative enzymes.
- Substitution by Alternative Technologies:In specific analytical workflows like proteomics, non-enzymatic chemical cleavage methods and alternative enzyme classes can offer different specificities, posing a substitution threat to traditional proteases like trypsin.
Strategic Opportunities
- Engineered Enzymes for Biocatalysis:There is a significant opportunity in developing custom-engineered serine proteases with enhanced stability in organic solvents or at extreme pH levels for use in industrial biocatalysis and fine chemical synthesis.
- Diagnostic Assay Development:The rising incidence of thrombotic and fibrotic diseases presents an opportunity for developing novel diagnostic kits that utilize specific serine proteases as biomarkers or reagents for coagulation testing.
- Expansion into Plant-Based Protein:The growing plant-based food sector requires effective enzymatic solutions to modify plant proteins, improve their functional properties like solubility and texture, and reduce off-flavors, opening a new application frontier.
Industry Challenges
- Supply Chain Consistency:Ensuring consistent batch-to-batch activity and purity of enzymes derived from biological sources is a persistent operational challenge, directly impacting the reproducibility of downstream processes for end-users in diagnostics and pharma.
- REACH Compliance Complexity:Enzyme manufacturers must navigate the EU's REACH regulation for chemical components used in stabilization and formulation, adding administrative overhead and potential reformulation costs to ensure market access.
- Specialized Talent Scarcity:A shortage of bioprocess engineers and enzymologists with expertise in large-scale fermentation, protein purification, and enzyme characterization can constrain production scale-up and innovation efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Serine Proteases Market |
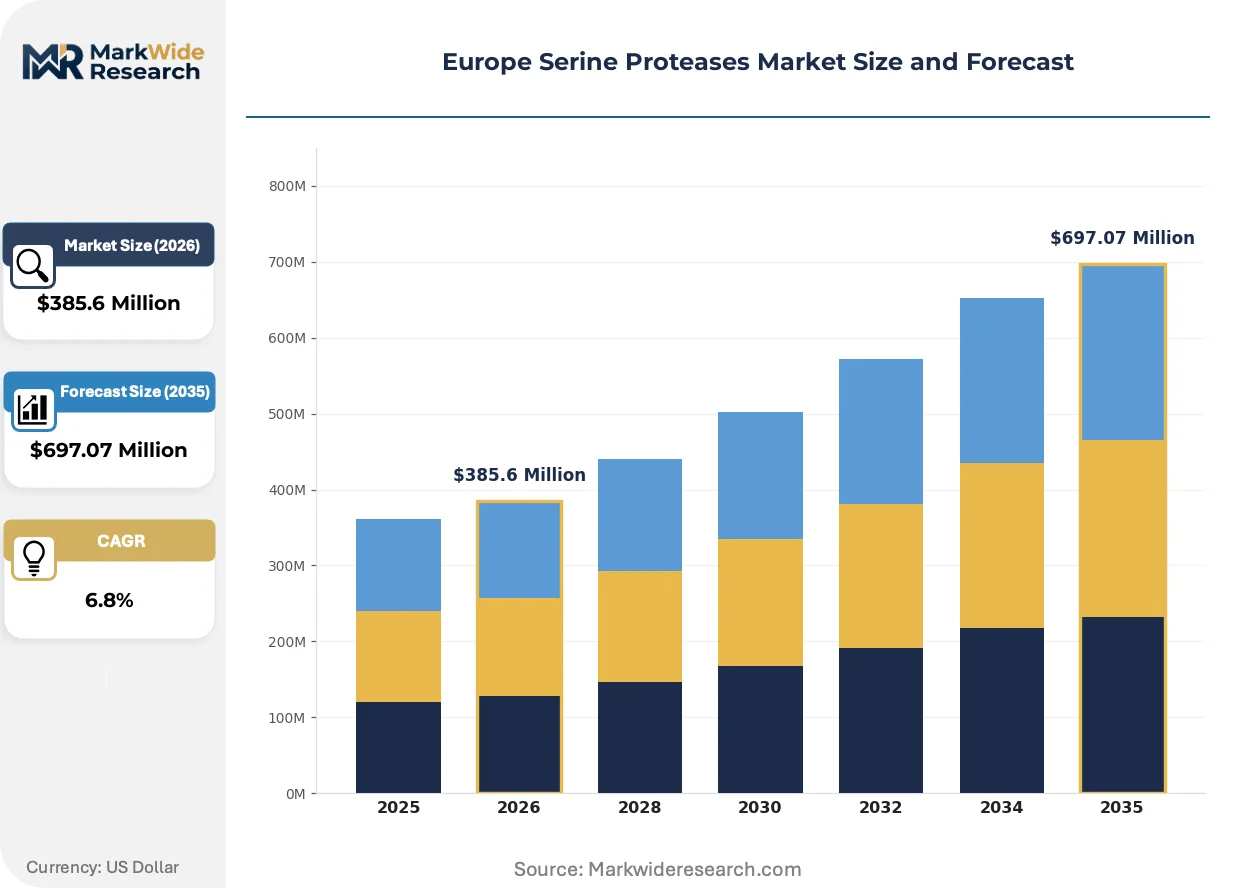
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trypsin, Chymotrypsin, Elastase, Thrombin Application: Biotechnology, Drug Development, Clinical Diagnostics, Research End User: Pharmaceutical Companies, Academic Institutions, Contract Research Organizations, Hospitals Distribution Channel: Direct Sales, Online Platforms, Distributors, Retailers |
| Companies Covered | Novozymes A/S, Biocatalysts, DSM, BASF SE, Merck KGaA, DuPont, Amano Enzyme Inc., AB Enzymes GmbH, Provencale SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Serine Proteases Market Strategic Shifts & Innovations
Innovation in the European serine proteases market is driven by the dual needs for enhanced specificity in biopharmaceutical applications and improved sustainability in industrial processes. This push is leading to the development of highly engineered enzymes and new manufacturing paradigms aligned with circular economy principles.
AI-driven enzyme engineering uses predictive algorithms to design novel proteases with customized substrate specificity, thermal stability, and catalytic efficiency. Pharmaceutical R&D departments are early adopters, using these tools to accelerate the development of targeted biocatalysts for specific manufacturing steps. This computational biology approach is integrating with high-throughput screening systems, significantly reducing the time required to develop and validate new enzymes for clinical and industrial use.
The EU Green Deal and its emphasis on sustainable biomanufacturing are creating powerful regulatory tailwinds for enzymatic solutions. This policy framework encourages the substitution of harsh chemical processes with greener, enzyme-based alternatives in industries such as detergents, textiles, and biofuels. Industrial enzyme producers, particularly in Germany and Denmark, are most affected, now positioning their protease portfolios based on documented reductions in energy consumption, water usage, and carbon footprint.
A clear shift toward quality-by-design (QbD) principles is altering sourcing patterns among biopharmaceutical manufacturers. This moves procurement decisions beyond simple cost-per-unit analysis to a total-cost-of-ownership framework that prioritizes batch-to-batch consistency, robust validation data, and supply chain security. The trend is most visible within the pharmaceutical clusters of Switzerland and Ireland, where process reliability is paramount for regulatory compliance and manufacturing efficiency.
Europe Serine Proteases Market Segmentation
Understanding the segmentation of the Europe serine proteases market offers critical insights into demand patterns and strategic allocation of resources. This granular view helps stakeholders identify specific niches, assess competitive dynamics, and align product development with distinct end-user requirements across the region.
Product Type:
The market for serine proteases demonstrates distinct upgrade and replacement cycles across various product types, driven by evolving application demands and technological advancements in enzyme engineering.
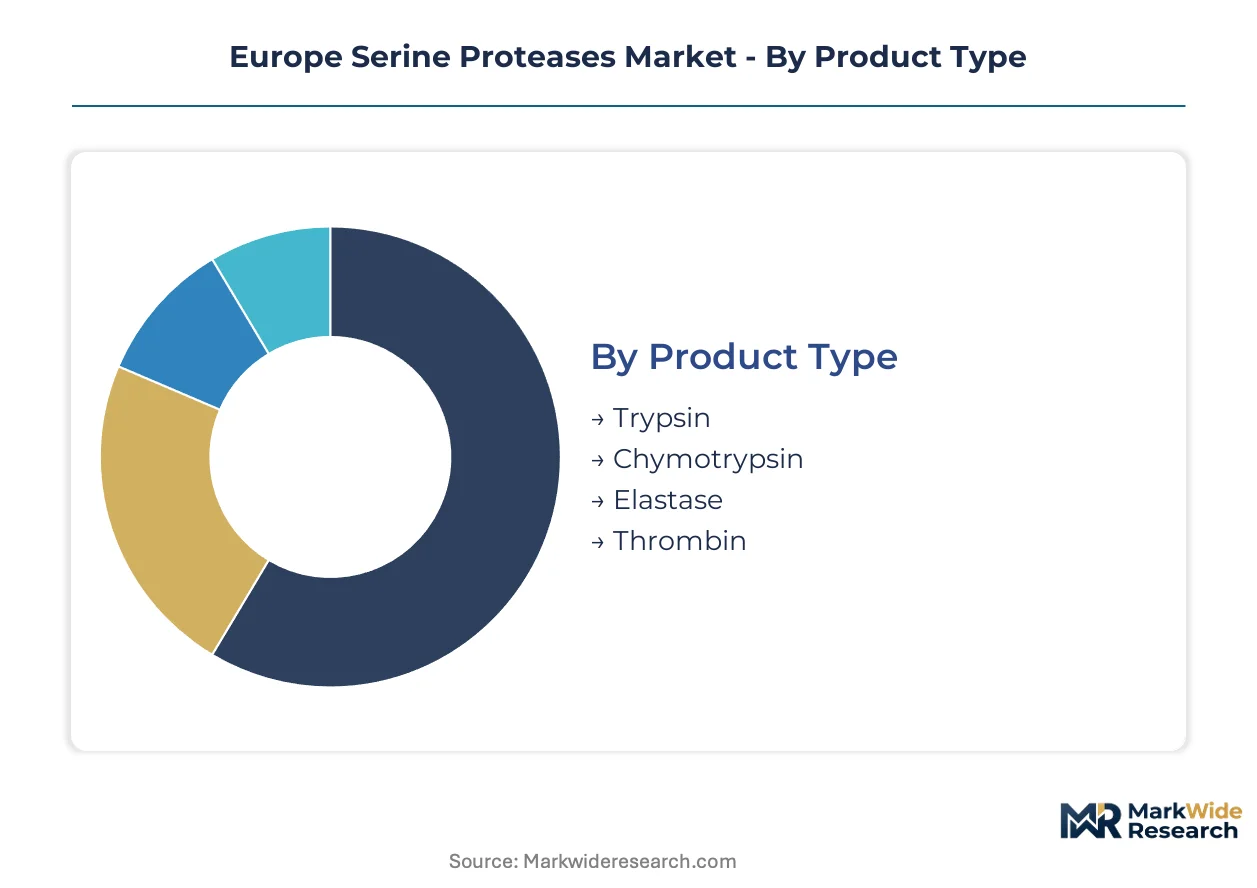
- Trypsin:A serine protease that specifically cleaves peptide chains at the carboxyl side of lysine and arginine residues. Its demand is concentrated in biopharmaceutical manufacturing within Germany and Switzerland, driven by its essential role in protein digestion for proteomics and cell culture detachment.
- Chymotrypsin:A digestive enzyme that hydrolyzes peptide bonds, preferentially at the carboxyl side of aromatic amino acids like tyrosine, tryptophan, and phenylalanine. Demand from biotechnology applications across Europe is expanding, particularly for its use in tissue dissociation and specific protein modification.
- Elastase:A proteolytic enzyme capable of degrading a wide range of proteins, including elastin, a key component of connective tissue. It finds use in wound debridement and cell isolation protocols.
- Thrombin:A serine protease that converts fibrinogen into fibrin, playing a central role in blood coagulation and hemostasis. Clinical diagnostics in France utilize thrombin for coagulation assays.
Trypsin sits at the top of the volume ranking, with Thrombin climbing the fastest.
Application:
Different applications for serine proteases often exhibit varying cost-tier sensitivities, influencing the purity grades and production scales required by end-users.
- Drug Development:Involves the use of serine proteases for protein characterization, purification of biologics, and cell culture processing in the discovery of new therapeutic compounds. This segment's demand is concentrated in the pharmaceutical clusters of Switzerland and Ireland, propelled by the surge in monoclonal antibody and cell therapy research.
- Clinical Diagnostics:Utilizes serine proteases as reagents in diagnostic kits for detecting biomarkers, analyzing coagulation pathways, or processing patient samples. The demand here is elevated by the EU's Medical Device Regulation (MDR), which mandates high-purity enzymes for accurate and reproducible assay results across European laboratories.
- Biotechnology:Encompasses the application of serine proteases in various industrial and research processes, including enzyme engineering and bioprocessing.
- Research:Serine proteases are fundamental tools in academic and industrial research for studying protein structure, function, and interactions.
Supply concentration for serine proteases is most pronounced in drug development, while clinical diagnostics exhibits a steady demand.
End User:
The volume of serine proteases consumed varies significantly across different end-user segments, reflecting their scale of operations and specific research or manufacturing needs.
- Pharmaceutical Companies:These entities are primary consumers of high-purity serine proteases for drug discovery, development, and manufacturing of biopharmaceuticals. Demand is notably high in Germany and Switzerland, driven by extensive R&D investments in biologics and advanced therapies.
- Academic Institutions:Universities and research institutes utilize serine proteases for fundamental scientific inquiry, protein analysis, and cell biology studies. Their demand often focuses on research-grade enzymes for experimental validation and mechanism elucidation.
- Contract Research Organizations:CROs leverage serine proteases in outsourced research and development services for pharmaceutical and biotechnology clients, often requiring customized enzyme solutions.
- Hospitals:Hospitals use serine proteases primarily in clinical laboratories for diagnostic testing, particularly in coagulation studies and certain disease marker detection.
Pharmaceutical companies represent the most mature end-user segment, with contract research organizations demonstrating increasing adoption.
Distribution Channel:
Distribution channels for serine proteases are highly tailored to the specific customer types, ranging from large pharmaceutical corporations to individual academic laboratories.
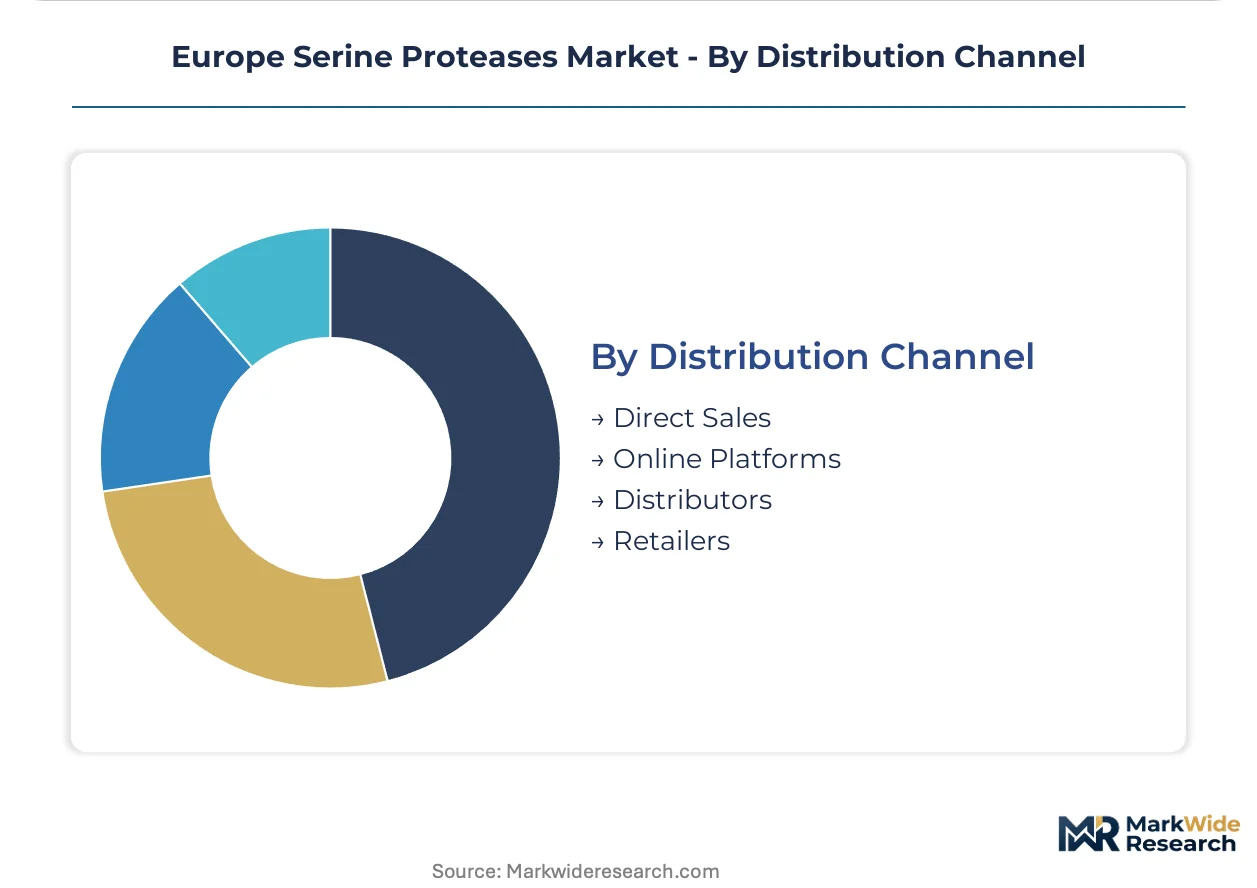
- Direct Sales:Involves manufacturers selling serine proteases directly to end-users, often for large volume orders or highly specialized, custom-engineered enzymes. This channel is preferred by pharmaceutical companies in regions like Germany for ensuring supply chain consistency and technical support.
- Distributors:Intermediaries that procure serine proteases from manufacturers and supply them to a broader range of end-users, including smaller laboratories and academic institutions. Distributors play a crucial role in market penetration across diverse European countries, managing logistics and regional inventory.
- Online Platforms:E-commerce websites and digital marketplaces facilitate the purchase of standard-grade serine proteases, offering convenience and wider product selection for researchers.
- Retailers:Less common for specialized enzymes, retailers might handle basic laboratory supplies including some lower-grade serine proteases for general use.
Direct sales channels typically yield higher margins for specialized enzymes, while online platforms contribute to broader market accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A concentrated pool of bioprocess engineers and enzymologists anchors the European serine proteases market, driving both innovation and advanced manufacturing capabilities. This specialized talent base, coupled with robust regulatory frameworks, fosters a dynamic environment for enzyme production and application across the continent. The region's commitment to sustainable biomanufacturing further influences procurement and development strategies for these critical enzymes.
Germany
Strong demand from pharmaceutical companies for drug development applications drives the German market for serine proteases. The EU Green Deal encourages sustainable biomanufacturing practices, influencing enzyme procurement decisions. Extensive pharmaceutical and biotech clusters in cities like Munich and Berlin focus heavily on biologics research and production.
Switzerland
Switzerland's market demands high-purity enzymes for pharmaceutical and diagnostic end-users, reflecting its strong life sciences sector. The European Medicines Agency (EMA) imposes strict quality standards on proteases used in biopharmaceutical manufacturing. Pharmaceutical clusters in Basel and Zurich are key centers for advanced therapeutic development and specialized diagnostics.
France
Clinical diagnostics in France utilize serine proteases, particularly thrombin, for essential coagulation assays and disease marker detection. The EU's Medical Device Regulation (MDR) mandates high-purity enzymes for accurate and reproducible diagnostic results. Major diagnostic and research hubs in Paris and Lyon consistently require reliable enzyme supplies.
Ireland
The Irish market experiences significant demand for serine proteases in drug development, especially for monoclonal antibody and cell therapy research. Compliance with EMA quality standards is paramount for biopharmaceutical manufacturing processes. Pharmaceutical clusters around Dublin and Cork are expanding their biologics production capacities.
Denmark
Denmark's industrial enzyme producers position their protease portfolios based on documented reductions in energy and carbon footprint. The EU Green Deal promotes the substitution of harsh chemical processes with greener, enzyme-based alternatives. Novozymes A/S, based near Copenhagen, leverages significant R&D investment in enzyme engineering for sustainable solutions.
Europe Serine Proteases Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the European serine proteases market, creating a tiered competitive structure. The market sees a division between large-scale industrial enzyme manufacturers and specialized suppliers focused on high-purity biopharmaceutical applications. Strategic archetypes include diversified chemical giants, dedicated enzyme specialists, and research-intensive bioprocess solution providers. Companies pursue portfolio diversification and technology licensing as dominant competitive moves.
Specialists in enzyme engineering, like Novozymes A/S, actively develop novel proteases with customized properties for biopharmaceutical and industrial applications. BASF SE, a diversified chemical company, focuses on large-scale production for industrial sectors, emphasizing cost-efficiency. Merck KGaA exemplifies a supplier differentiating through its portfolio of high-purity enzymes tailored for demanding pharmaceutical and diagnostic end-users across Europe.
| Leading Market Players |
|---|
| Novozymes A/S |
| Biocatalysts |
| DSM |
| BASF SE |
| Merck KGaA |
| DuPont |
| Amano Enzyme Inc. |
| AB Enzymes GmbH |
| Provencale SA |
| Others |
Cost & Logistics Intelligence
AI-driven enzyme engineering simultaneously reshapes cost economics by optimizing production while concentrating high-purity enzyme supply among specialized manufacturers. This technological advancement influences both the pricing strategies for novel proteases and the geographic distribution of advanced production facilities.
Pricing Analysis
Pricing stratifies across premium, standard, and economy tiers, reflecting distinct purity requirements and application sensitivities. Quality grade for pharmaceutical use and stringent EMA certification levels are primary drivers of price differentiation. Cost compression in industrial applications stems from the need for efficiency and volume. Pharmaceutical companies exhibit the lowest price sensitivity for critical enzymes, while food and beverage manufacturers are more price-conscious.
Supply Chain Analysis
Direct sales channels predominantly handle large-volume orders for pharmaceutical companies, ensuring technical support and supply consistency. Geographic supply concentration for high-purity serine proteases centers in Germany, Switzerland, and Denmark, leveraging established biotech infrastructure. The supply chain draws from specialized biological sources and chemical components used in enzyme stabilization. Batch-to-batch consistency presents a persistent operational risk for end-users, directly impacting reproducibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cost differential for GMP-compliant facilities in Western Europe versus potential Eastern European manufacturing sites creates a geographic-arbitrage play within the European serine proteases market.
For Market Incumbents: To counter substitution by alternative technologies, incumbents must invest heavily in AI-driven enzyme engineering to develop highly specific and stable proteases. Deepen vertical integration into specialized raw material sourcing to secure critical inputs and mitigate supply chain risks. Focus on strengthening validation data for existing products to meet evolving regulatory scrutiny under the EU's Medical Device Regulation.
For New Entrants and Emerging Players: Plant-based protein manufacturers represent an underserved buyer archetype requiring novel enzymatic solutions. Target the development of custom-engineered proteases to improve functional properties like solubility and texture in plant-based foods. A go-to-market angle focusing on documented sustainability benefits and clean-label compatibility will resonate with this segment.
For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light designers focused on niche biocatalysis applications with strong intellectual property. The market remains attractive for long-term investors due to persistent demand from biopharma and sustainable industrial transitions. Acquire specialized enzyme engineering firms with proprietary AI platforms for accelerated enzyme discovery. The successful navigation of EMA approval for novel bio-engineered proteases is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Engineered Enzymes | Develops proteases with enhanced specificity for complex drug development processes. |
| Capacity Expansion in GMP Facilities | Ensures reliable supply for growing biopharmaceutical demand in Germany and Switzerland. |
| Acquisition of Specialist Firms | Expands portfolio of high-purity enzymes for diagnostic assay development. |
| Green Manufacturing Transition | Aligns production with EU Green Deal mandates, attracting eco-conscious buyers. |
| Long-term Supply Agreements | Secures consistent supply for pharmaceutical companies, mitigating batch variation risks. |
Research Approach
Direct dialogue with drug development executives, bioprocess engineers, regulatory affairs leads, and procurement managers provided critical primary insights. These qualitative inputs were triangulated with secondary data from EMA guidelines, REACH regulations, corporate sustainability reports, and scientific literature. The analysis utilized both bottom-up market sizing and top-down validation to ensure data robustness.
Volume and value projections were developed using a multi-factor analytical framework that modeled segmentation across product type, application, end-user, distribution channel, and regional regulatory compliance. CAGRs were determined by modeling historical growth patterns and future demand drivers across the analysis window. Key forecast inputs included biopharmaceutical R&D spending and EU Green Deal investment in biomanufacturing.
Underlying measurement precision varies by segment; pharmaceutical and diagnostic applications carry tighter precision than industrial uses. Forecasts reflect inherent assumptions regarding technological advancements and regulatory stability. Supply chain disruptions or unforeseen shifts in biomanufacturing trends could alter projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Ligation Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
France Flow Cytometry Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Exosomes Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Global Optogenetics Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
Drug Delivery Technology Market
Biomedical Technology
Fluorescent in Situ Hybridization Market
Biomedical Technology
Inhalable Biologics Market
Biomedical Technology
Liquid Biopsy Market
Biomedical Technology
North America Proteomics Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market