
 Asia-Pacific Digital PCR Market | 2026-2036
Asia-Pacific Digital PCR Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital PCR Market Analytics
Platform licensing revenue is reshaping how instrument vendors monetize digital PCR ecosystems in Asia-Pacific. Thermo Fisher Scientific leverages its Applied Biosystems franchise to anchor installed-base expansion across Chinese research hospitals. Bio-Rad Laboratories sustains technology leadership through droplet-based workflows that dominate liquid biopsy validation protocols. Qiagen N.V. competes by extending sample-to-insight automation that reduces manual nucleic acid handling steps.
Digital PCR quantifies nucleic acid targets through absolute molecule counting without standard curves, achieving sensitivity thresholds below 0.1% allele frequency for rare mutation detection. The technology partitions individual PCR reactions into thousands of microcompartments using microfluidic channels or oil-water emulsion droplets. Reagents and consumables capture the recurring revenue stream as installed instruments require proprietary cartridges and master mixes at predictable intervals. Oncology applications command premium positioning due to clinical trial volume and companion diagnostic mandates, while infectious disease testing gains traction from residual COVID-19 surveillance infrastructure repurposed for multiplex pathogen panels. Droplet digital PCR technology leads instrument placements, though microfluidics chip-based systems are displacing legacy quantitative PCR in high-throughput genomics facilities.
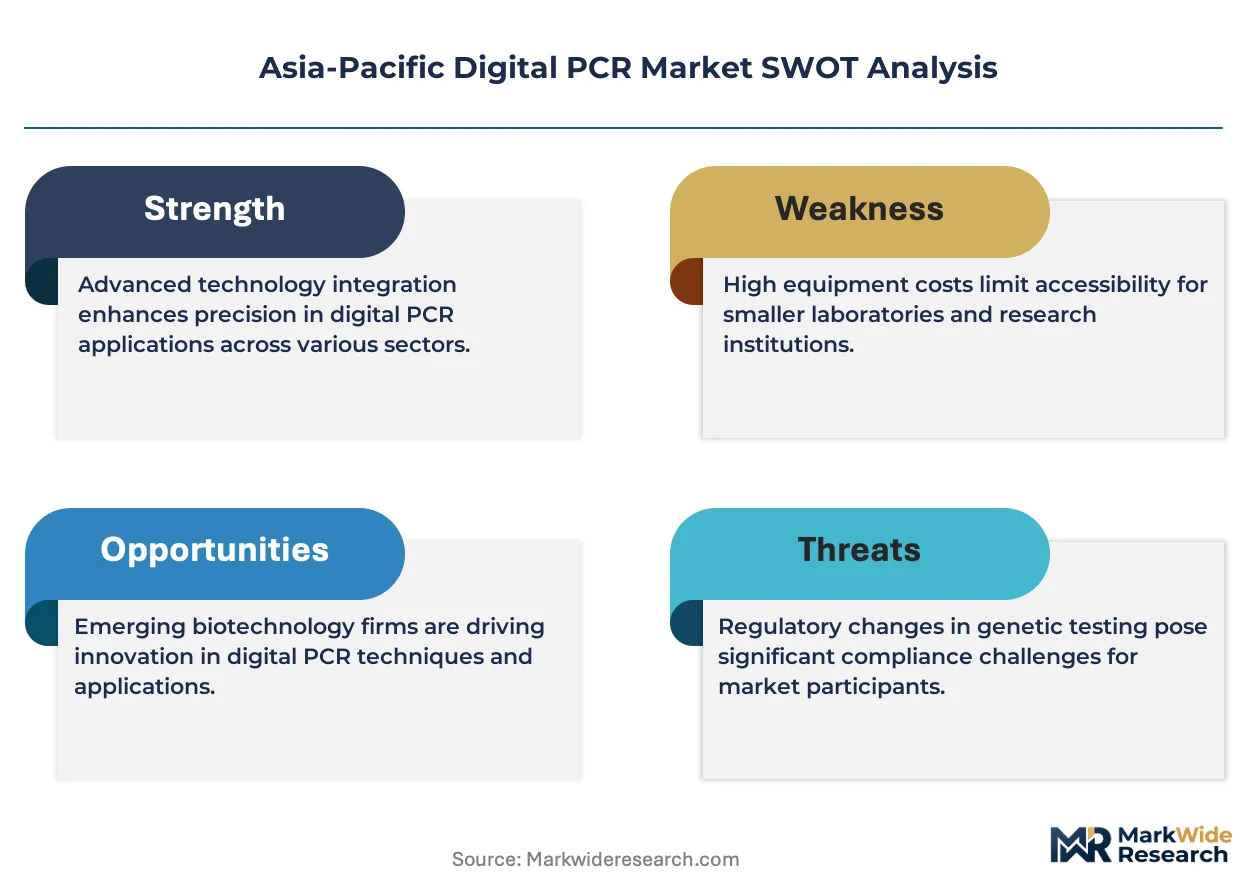
Japan's PMDA and Australia's TGA enforce stringent analytical validation standards for in vitro diagnostic claims, compelling manufacturers to submit clinical performance dossiers before market authorization. China's NMPA revised its innovative medical device review pathway to accelerate locally manufactured digital PCR platforms. India's CDSCO aligns with ISO 13485 quality management benchmarks for import licensing of molecular diagnostics. Stakeholders must monitor regulatory divergence between harmonized ASEAN medical device directives and country-specific clinical evidence requirements that fragment go-to-market timelines.
Market Dynamics
Platform licensing revenue models are restructuring vendor economics across Asia-Pacific digital PCR markets, as instrument manufacturers pivot from hardware margins to recurring consumable streams and software subscriptions.
Growth Catalysts
- Oncology companion diagnostics:Japan's PMDA mandates molecular profiling for targeted therapies, driving hospital laboratory adoption of absolute quantification workflows. Liquid biopsy validation protocols now require digital PCR sensitivity thresholds.
- China's NMPA pathway acceleration:Streamlined innovative device reviews compress approval timelines for locally manufactured platforms. Domestic manufacturers gain first-mover advantage in Tier-3 city hospital procurement.
- Residual COVID-19 infrastructure:Multiplex pathogen panel deployment repurposes installed qPCR capacity. Public health laboratories across Australia and South Korea integrate droplet-based workflows for respiratory surveillance.
Market Restraints
- Proprietary consumable lock-in:Cartridge and master mix pricing concentrates recurring revenue with original equipment vendors. Third-party reagent compatibility remains technically restricted.
- Capital intensity:Microfluidics chip-based systems require 40-60% higher instrument investment than legacy qPCR. Budget-constrained research institutes defer replacement cycles.
- Regulatory fragmentation:Divergent ASEAN medical device directives versus country-specific clinical evidence requirements extend go-to-market timelines. India's CDSCO import licensing aligns with ISO 13485 but lacks regional harmonization.
Strategic Opportunities
- India's diagnostic network expansion:CDSCO regulatory alignment with international quality standards enables import licensing for molecular diagnostics. Tier-2 and Tier-3 cities remain undersupplied with absolute quantification platforms.
- Sample-to-insight automation:Integration of nucleic acid extraction with digital PCR quantification reduces manual handling steps. Automated workflows address technician scarcity in high-throughput genomics facilities.
- Australia's TGA precision medicine framework:Stringent analytical validation standards for in vitro diagnostic claims create premium positioning for clinically validated platforms. Tertiary hospital networks prioritize regulatory-compliant systems.
Industry Challenges
- Technical specialist scarcity:Microfluidics engineering expertise and bioinformatics interpretation skills lag platform deployment. Training pipelines for droplet digital PCR assay development remain underdeveloped.
- Legacy system integration:Hospital laboratory information management systems require custom middleware for digital PCR data output. Interoperability gaps delay clinical adoption timelines.
- Reagent cold chain integrity:Temperature-sensitive proprietary cartridges face distribution challenges across archipelagic Southeast Asian markets. Logistics infrastructure gaps increase spoilage risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital PCR Market |
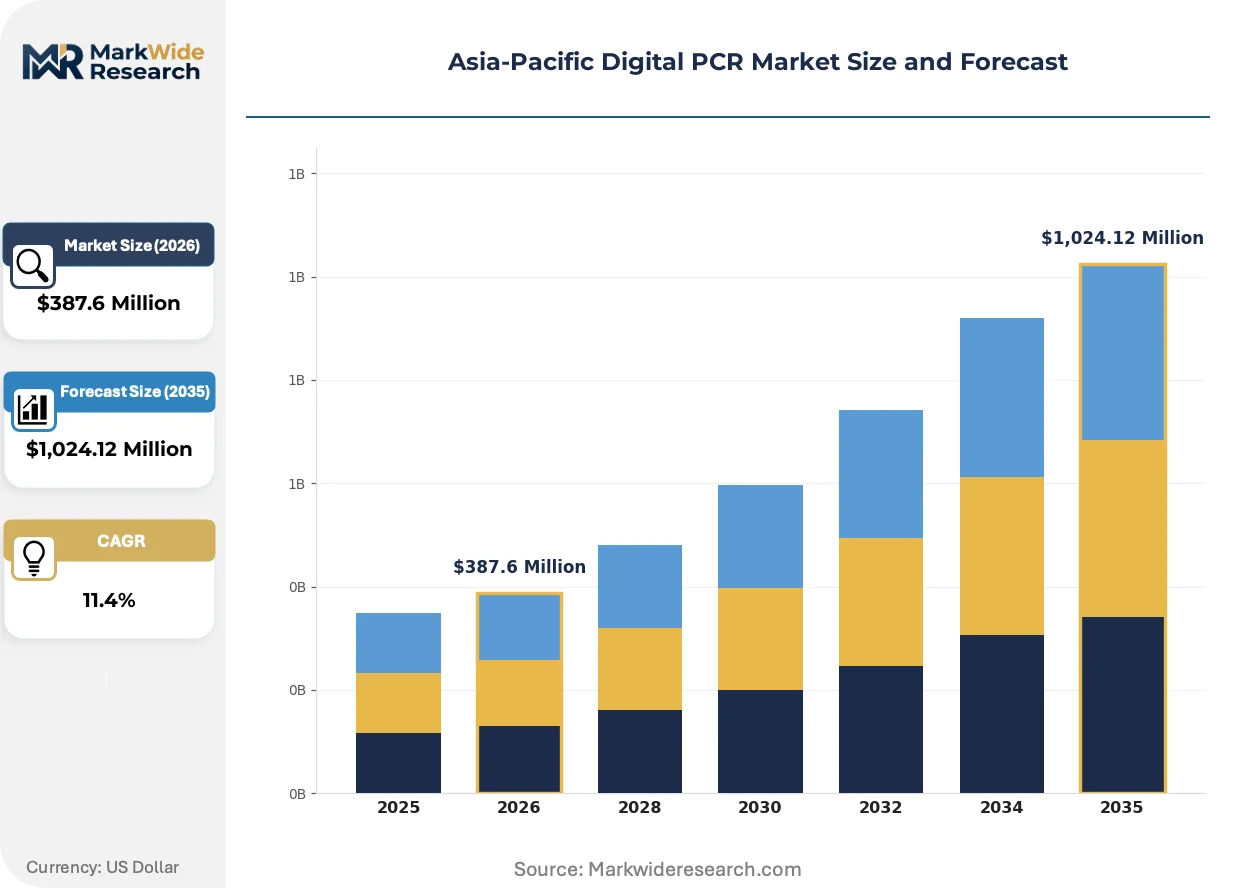
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Consumables, Software End User: Hospitals, Research Labs, Academic Institutions, Pharmaceutical Companies Technology: Microfluidics, Droplet Digital PCR, Quantitative PCR, Multiplex PCR Application: Oncology, Infectious Diseases, Genetic Disorders, Environmental Testing |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories, F. Hoffmann-La Roche Ltd, Qiagen N.V., Takara Bio Inc., Agilent Technologies Inc., Danaher Corporation, Abbott Laboratories, Shimadzu Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital PCR Market Evolving Landscape
Microfluidics engineering advances are compressing reaction volumes while preserving analytical sensitivity, enabling new deployment models beyond centralized reference laboratories.
Chip-based digital PCR systems are collapsing the cost-per-sample economics that previously constrained high-throughput genomics facilities. Research hospitals in China and Japan accelerate instrument placement for pharmacokinetic monitoring and transplant chimerism testing. The technology is collapsing workflow bottlenecks by eliminating standard curve preparation and reducing technician hands-on time.
China's NMPA revised its innovative medical device review pathway to accelerate locally manufactured platform authorizations. Domestic manufacturers now compete directly with imported systems in public hospital procurement tenders. The policy shift most affects oncology companion diagnostic segments, where local clinical evidence generation satisfies regulatory requirements faster than foreign dossier submissions.
Service unbundling is fragmenting traditional instrument-plus-consumable contracts across Australian and South Korean research markets. Core facilities now negotiate reagent supply separately from hardware maintenance, pressuring vendor margin structures. This behavioral shift appears most visible in academic medical centers with established procurement offices and multi-vendor instrument parks.
Asia-Pacific Digital PCR Market Segmentation
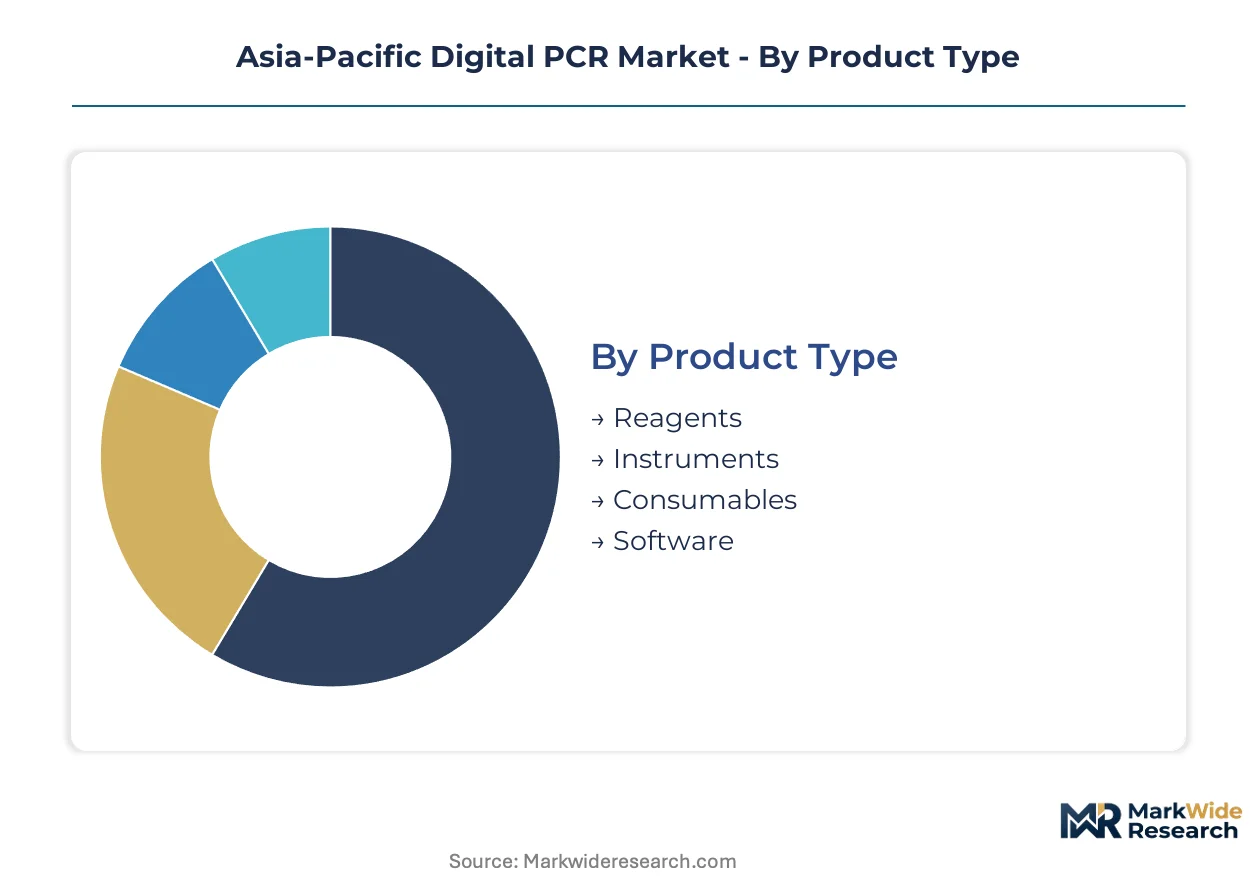
Digital PCR market segmentation in Asia-Pacific reflects distinct procurement patterns across clinical diagnostics and research applications. Product mix varies sharply between hospital laboratories prioritizing regulatory-compliant systems and academic centers optimizing for cost-per-sample economics.
Product Type:
Mature consumable streams anchor vendor revenue stability while emerging software layers capture analytics value.
- Reagents:Proprietary master mixes and reaction buffers constitute the highest-margin recurring revenue stream. China's NMPA approval pathways for locally manufactured reagents accelerate substitution of imported chemistries in Tier-2 hospital procurement.
- Instruments:Microfluidics chip-based and droplet-based detection systems require substantial capital investment with 5-7 year replacement cycles. Japan's PMDA validation mandates for clinical diagnostic claims concentrate demand in regulatory-compliant platforms at tertiary medical centers.
- Consumables:Single-use cartridges and partition plates generate predictable replacement demand tied to test volume. Temperature-sensitive logistics constrain distribution across archipelagic Southeast Asian markets.
- Software:Bioinformatics pipelines for absolute quantification and rare mutation detection are gaining attach rates. Cloud-based analysis modules address technician scarcity in high-throughput genomics facilities.
Reagents handle the majority of throughput; software is the fastest mover on share.
End User:
Customer concentration spans centralized reference laboratories and distributed research networks with divergent technical requirements.
- Hospitals:Clinical diagnostic laboratories in Japan and Australia prioritize regulatory-compliant platforms for companion diagnostic workflows. PMDA and TGA analytical validation standards mandate documented clinical performance dossiers.
- Research Labs:Core facilities across China and South Korea optimize for multiplexing capacity and cost-per-sample economics. Liquid biopsy validation protocols require digital PCR sensitivity thresholds below 0.1% allele frequency.
- Academic Institutions:University medical centers negotiate unbundled procurement separating reagent supply from hardware maintenance. Budget constraints defer instrument replacement cycles relative to hospital counterparts.
- Pharmaceutical Companies:Drug developers deploy absolute quantification for pharmacokinetic monitoring and clinical trial biomarker analysis. Oncology companion diagnostic mandates drive platform standardization across multinational trial sites.
Hospitals command premium pricing; pharmaceutical companies are expanding most quickly on absolute spend.
Technology:
Technology adoption curves separate established quantitative methods from next-generation partitioning approaches.
- Microfluidics:Chip-based systems partition reactions into nanoliter chambers with integrated fluorescence detection. Research hospitals in China accelerate placement for transplant chimerism testing and residual disease monitoring.
- Droplet Digital PCR:Oil-water emulsion droplets achieve absolute molecule counting without standard curves. The technology dominates liquid biopsy validation protocols across Asia-Pacific precision medicine networks.
- Quantitative PCR:Legacy real-time systems face displacement in high-throughput genomics facilities. Residual installed base supports COVID-19 surveillance infrastructure repurposed for respiratory pathogen panels.
- Multiplex PCR:Simultaneous target detection reduces per-sample reagent consumption. Public health laboratories integrate multiplex panels for syndromic surveillance across Australia and South Korea.
Droplet digital PCR handles the majority of throughput; microfluidics is climbing the fastest on new instrument placements.
Application:
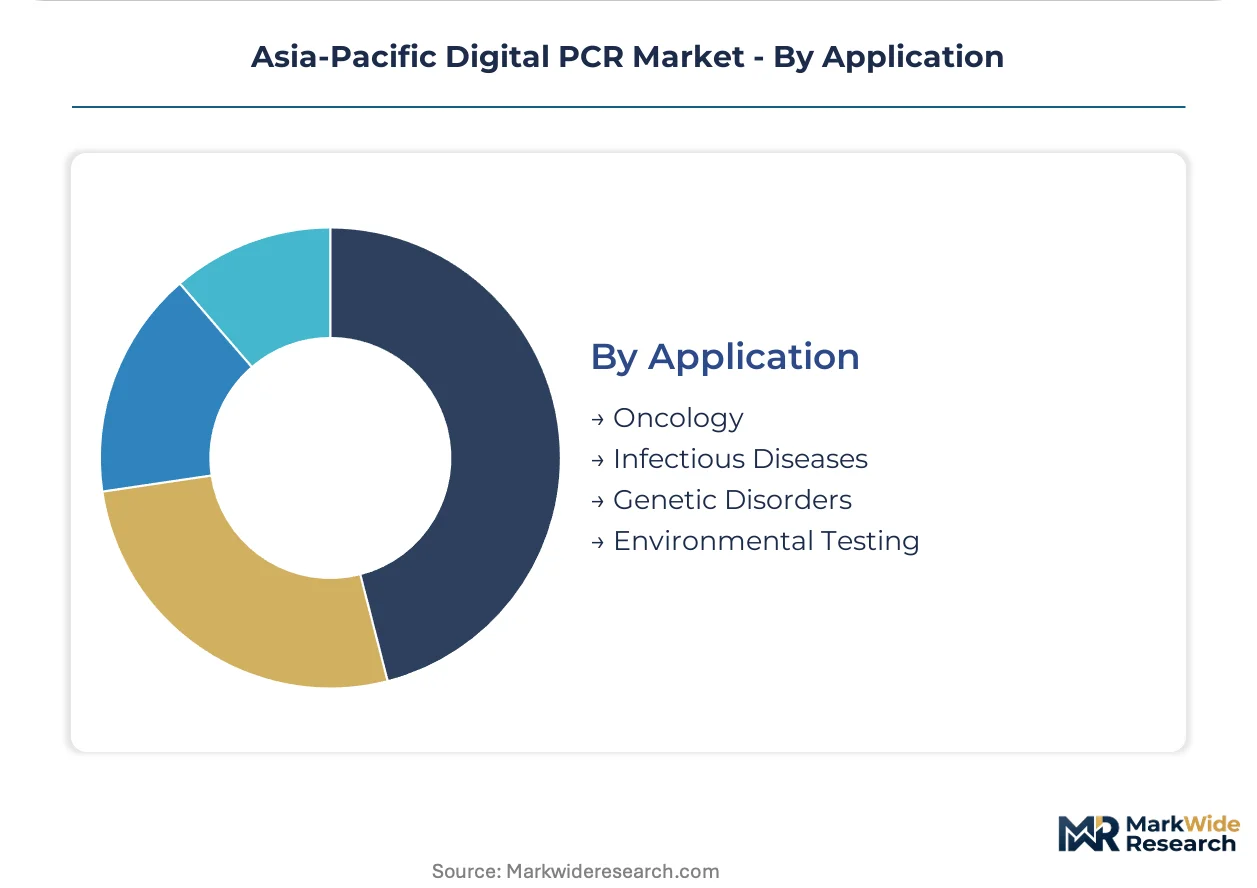
Application demand concentrates in oncology while infectious disease testing leverages pandemic-era infrastructure investments.
- Oncology:Companion diagnostic mandates and clinical trial volume command premium platform positioning. Japan's PMDA requires molecular profiling for targeted therapy eligibility.
- Infectious Diseases:Multiplex pathogen panels repurpose residual COVID-19 surveillance capacity. Droplet-based workflows integrate into public health laboratory networks for respiratory and bloodstream infection surveillance.
- Genetic Disorders:Non-invasive prenatal testing and carrier screening applications expand in urban hospital networks. Sample-to-insight automation reduces manual handling steps for high-volume screening programs.
- Environmental Testing:Water quality and food safety applications remain nascent outside specialized reference laboratories. Regulatory enforcement gaps limit commercial scale in most Asia-Pacific jurisdictions.
Oncology commands the steepest expansion trajectory; infectious diseases holds the largest installed base leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments across Asia-Pacific digital PCR procurement, with Tier-3 Chinese hospitals demanding steep instrument discounts while Japanese tertiary centers absorb premium positioning for PMDA-validated platforms.
China
Domestic manufacturers capture Tier-2 and Tier-3 hospital procurement through NMPA's accelerated innovative device pathway. The regulator's revised review timelines compress market entry for locally manufactured platforms against imported systems. Beijing-Shanghai-Guangzhou hospital clusters anchor installed-base expansion, with research hospitals in Hangzhou and Chengdu accelerating microfluidics chip placements for transplant chimerism testing.
Japan
PMDA companion diagnostic mandates for targeted oncology therapies concentrate demand in absolute quantification workflows at tertiary medical centers. The regulator's analytical validation standards for in vitro diagnostic claims filter platform selection toward clinically validated systems. Tokyo-Osaka-Nagoya metropolitan hospital networks standardize on droplet-based liquid biopsy protocols, with Kobe and Fukuoka academic centers driving pharmacokinetic monitoring adoption.
Australia
TGA's precision medicine framework creates premium positioning for regulatory-compliant platforms across tertiary hospital networks. The regulator's stringent clinical evidence requirements extend procurement timelines but concentrate demand in validated systems. Sydney-Melbourne research corridors anchor public health laboratory integration of multiplex pathogen panels repurposed from COVID-19 surveillance infrastructure.
South Korea
MFDS alignment with international quality standards enables rapid authorization of imported digital PCR platforms for hospital laboratory networks. The regulator's efficiency supports pharmaceutical company demand for clinical trial biomarker standardization. Seoul-Busan metropolitan clusters drive core facility automation, with Daejeon research institutes negotiating unbundled reagent supply contracts separate from hardware maintenance.
India
CDSCO import licensing alignment with ISO 13485 quality management benchmarks opens molecular diagnostics access for Tier-2 and Tier-3 city hospital networks. The regulator's framework lacks regional harmonization with ASEAN directives, fragmenting go-to-market timelines. Mumbai-Delhi-Bangalore diagnostic networks concentrate absolute quantification platform deployment, with Hyderabad and Chennai emerging as pharmaceutical R&D biomarker analysis hubs.
Asia-Pacific Digital PCR Market Competitive Landscape
Capability concentration sits with specialized microfluidics engineering houses; scale advantage sits with diversified life science conglomerates. The market structures around three tiers: integrated diagnostic platforms, precision instrument specialists, and consumables-dominant suppliers. Two strategic archetypes define competitive positioning: technology originators leveraging patent estates for licensing revenue, and systems integrators bundling sample-to-insight automation. M&A activity targets assay development boutiques; geographic expansion focuses on China's Tier-3 hospital procurement corridors.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation anchor the integrated platform tier through broad installed-base leverage. Bio-Rad Laboratories exemplifies the precision instrument specialist archetype with droplet-based workflow dominance. Qiagen N.V. occupies a position bridging consumables scale with automation integration. These three represent distinct competitive vectors: one through franchise breadth, one through technology specificity, one through sample-prep-to-analysis continuity.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche Ltd |
| Qiagen N.V. |
| Takara Bio Inc. |
| Agilent Technologies Inc. |
| Danaher Corporation |
| Abbott Laboratories |
| Shimadzu Corporation |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Japanese microfluidics component suppliers determines both pricing tier spreads and supply chain shape across Asia-Pacific digital PCR markets. Proprietary cartridge lock-in at the consumables tier concentrates vendor pricing power while exposing buyers to temperature-sensitive logistics vulnerabilities across archipelagic Southeast Asian distribution corridors.
Pricing Analysis
Consumables and reagent service contracts drive lifetime value capture for instrument vendors. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-validated clinical systems from research-grade platforms and refurbished installed-base units. Price differentiation rests on regulatory certification tier and after-sales service bundling intensity. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers exploit NMPA accelerated pathways to undercut imported cartridge pricing. Academic medical centers with unbundled procurement offices exhibit highest price sensitivity; Japanese tertiary hospitals absorb premium positioning for companion diagnostic compliance.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculus for microfluidics chip substrates and fluorescence detection modules. Component manufacturing concentrates in Japan, Germany, and the United States for precision optical elements, while plastic consumables molding feeds from Chinese and South Korean suppliers. Raw material dependencies span medical-grade polycarbonate resins, fluorinated surfactants for droplet generation, and rare-earth phosphors for signal detection. Single-source vulnerability persists at the microfluidics foundry tier where specialized cleanroom capacity remains limited. Distribution runs through authorized distributor networks with cold-chain custody requirements for temperature-sensitive reagent cartridges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. Switching costs between proprietary cartridge ecosystems and validated assay protocols create substantial barriers to displacement for installed-base incumbents.
For Market Incumbents: Harden consumables lock-in through exclusive assay partnership programs with oncology drug developers. Expand backward integration into master mix chemistry production to capture margin compression from domestic Chinese reagent competitors. Certification investment in India's CDSCO import licensing pathway represents the priority defensive lever against emerging local platform manufacturers.
For New Entrants and Emerging Players: India's Tier-2 and Tier-3 city hospital networks represent the most penetrable entry point for absolute quantification platforms. Microfluidics chip-based systems for transplant chimerism testing in Chinese research hospitals offer secondary white-space access. Go-to-market execution should emphasize unbundled reagent supply contracts that mirror procurement patterns already established in South Korean academic core facilities.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors assay development boutiques with companion diagnostic validation dossiers. Long-term viability over the next decade hinges on regulatory data package depth rather than hardware differentiation alone. Acquisition target archetypes include liquid biopsy assay shops with PMDA analytical validation experience. The signal to watch is NMPA approval velocity for locally manufactured platforms as inflection indicator for import displacement pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Assay Partnership | Locks in recurring cartridge revenue through oncology drug developer exclusivity agreements. |
| NMPA Innovative Device Pathway Submission | Accelerates market entry against imported systems in Chinese Tier-3 hospital procurement. |
| Sample-to-Insight Automation Integration | Reduces technician handling steps in high-throughput genomics facilities facing labor scarcity. |
| CDSCO Import Licensing Alignment | Enables molecular diagnostics access for India's undersupplied Tier-2 city hospital networks. |
| Cloud-Based Bioinformatics Module Launch | Addresses absolute quantification interpretation skills gap across Asia-Pacific research markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital laboratory directors, biomedical engineers at research core facilities, regulatory affairs specialists navigating PMDA and NMPA pathways, and procurement officers at academic medical centers. Secondary validation drew from hospital procurement databases, GPO contracts, CDSCO import licensing records, and PMDA clinical performance dossier submissions. Bottom-up instrument placement tracking and top-down consumables revenue modeling were triangulated to anchor market size estimates.
Calibration against historical placement data and vendor-reported installed-base figures informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-user category, technology platform, and application area with regulatory pathway clustering. CAGRs were derived from instrument replacement cycle analysis and consumables attach-rate trending. Industry-specific forecast inputs encompass NMPA approval velocity metrics and liquid biopsy clinical trial protocol adoption rates.
Practitioners should monitor regulatory pathway divergence between ASEAN harmonization initiatives and country-specific clinical evidence requirements for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Ligation Market
Biomedical Technology
Multiplex Biomarker Imaging Market
Biomedical Technology
Cosmid DNA Isolation Market
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
Protein Characterization and Identification Market
Biomedical Technology
Neuro Immunoassay Market
Biomedical Technology
Global Exosome Research Products Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
France Flow Cytometry Market
Biomedical Technology
Global Protein Crystallization Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market
Biomedical Technology
Reverse Transcriptase Enzymes Market