
 Drug Delivery Technology Market | 2026-2036
Drug Delivery Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Delivery Technology Market Analysis
Oncology administration is hardening as the dominant end-use vertical for advanced delivery systems. Pfizer Inc. leverages its biologics portfolio to sustain injectable platform leadership across major therapeutic categories. Novartis AG anchors its position through sustained investment in liposome and nanoparticle engineering capabilities. Becton, Dickinson and Company dominates prefillable syringe and autoinjector manufacturing scale, supplying device infrastructure to multiple pharmaceutical partners.
Drug delivery technology encompasses engineered systems that transport pharmaceutical agents to targeted physiological sites at controlled release rates, utilizing mechanisms such as polymeric degradation, osmotic pressure differentials, or pH-responsive material transitions to achieve therapeutic concentration windows. Its primary commercial purpose centers on improving bioavailability, reducing dosing frequency, and enabling administration of molecules with poor solubility or stability profiles. Injectable platforms lead current revenue generation due to biologics expansion, while microneedle technology represents the fastest-growing segment as patients and payers seek reduced pain profiles and self-administration options. Liposome formulations maintain mature margin pools in oncology despite manufacturing complexity, whereas hydrogel platforms are gaining traction in localized sustained-release applications.
FDA oversees combination product classifications that determine whether drug-device platforms follow pharmaceutical or medical device review pathways, directly impacting development timelines and capital requirements. EMA's MDR alignment pressures European manufacturers to strengthen clinical evidence packages for delivery mechanisms classified as active therapeutic devices. Japan's PMDA maintains distinct quality standards for novel polymer excipients that constrain formulation choices for entrants. Stakeholders must monitor evolving regulator convergence on human factors testing requirements as self-administration expands beyond supervised clinical environments.
Market Dynamics
Biologics pipeline expansion is compressing development timelines for injectable platforms while FDA-EMA convergence on combination product pathways accelerates regulatory clarity for novel delivery mechanisms.
Growth Catalysts
- Self-Administration Mandates:Payers in Germany and Japan now require home-compatible delivery formats for chronic disease reimbursement, forcing formulation redesign toward autoinjectors and microneedle systems.
- EMA MDR Alignment:Streamlined clinical evidence requirements for active therapeutic devices reduce duplicate testing burdens, shortening European market entry cycles for drug-device combinations.
- Oncology Administration Concentration:Targeted therapy pipelines in the United States favor nanoparticle and liposome carriers that enable tumor-specific payload release.
Market Restraints
- Polymer Excipient Supply Concentration:Japan's PMDA maintains distinct quality standards for novel polymers that limit qualified supplier pools to domestic and select European sources.
- Manufacturing Complexity Premium:Liposome formulation requires specialized aseptic processing equipment that constrains batch scale-up and inflates per-unit production costs.
- Biologics Stability Constraints:Temperature-sensitive protein therapeutics demand cold-chain infrastructure that fragments distribution reach in emerging markets.
Strategic Opportunities
- Microneedle-Dermal Convergence:Microneedle arrays paired with hydrogel reservoirs enable vaccine and biologic delivery through skin barriers, opening pediatric and needle-phobic patient segments.
- Home Care Channel Expansion:Chronic disease management shifts beyond hospital walls in the United States, creating demand for connected delivery devices with dose-tracking capabilities.
- Reimbursement Framework Tailwinds:Japan's revised pricing methodology for advanced delivery modalities rewards improved patient adherence outcomes with premium reimbursement tiers.
Industry Challenges
- Human Factors Engineering Talent Scarcity:Self-administration device design requires specialized usability expertise that outpaces current training pipeline output.
- Combination Product Classification Uncertainty:FDA pathway determinations between pharmaceutical and medical device review queues create timeline unpredictability that complicates capital planning.
- Legacy System Integration Friction:Smart delivery platforms with connectivity features must interface with hospital electronic health record systems lacking standardized data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Delivery Technology Market |
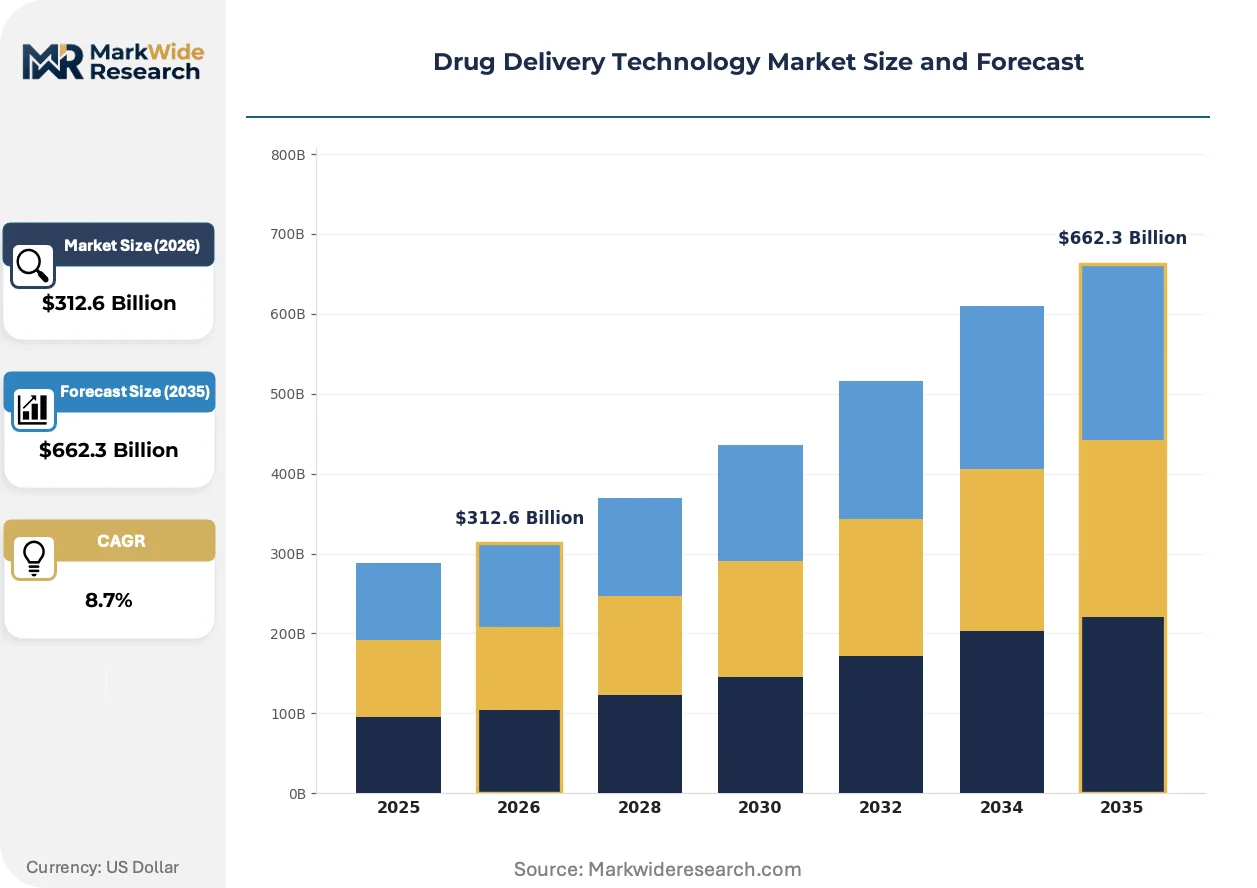
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Transdermal, Inhalation Technology: Nanoparticles, Hydrogels, Microneedles, Liposomes Therapy Area: Oncology, Cardiovascular, Diabetes, Neurology End User: Hospitals, Home Care, Clinics, Research Laboratories |
| Companies Covered | Johnson & Johnson Services, Inc., Novartis AG, Pfizer Inc., Becton, Dickinson and Company, West Pharmaceutical Services, Inc., Baxter International Inc., Gerresheimer AG, Medtronic, AstraZeneca PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Delivery Technology Market Emerging Trajectories
Microneedle technology is compressing pain profiles and administration settings while regulatory harmonization and patient-centric design philosophies reshape competitive requirements across delivery platform categories.
Polymeric microneedle arrays fabricated from dissolvable sugar or silk fibroin matrices enable painless transdermal delivery of vaccines and biologics without sharps disposal requirements. Pediatric immunization programs in Germany and Japan are piloting these formats for seasonal vaccine campaigns. This technology is electrifying patient acceptance metrics and enabling pharmacy-based administration that bypasses clinical infrastructure.
EMA's Medical Device Regulation implementation pressures European manufacturers to strengthen post-market surveillance and clinical evidence packages for delivery mechanisms classified as active therapeutic devices. Device firms now embed pharmacovigilance capabilities previously reserved for pharmaceutical sponsors. Prefillable syringe and autoinjector categories face the steepest compliance cost adjustments.
Hospital procurement departments in the United States increasingly bundle delivery devices with drug contracts, compressing standalone device vendor access. Integrated supply agreements favor pharmaceutical partners with captive manufacturing or exclusive device alliances. Oncology and immunology therapeutic categories show the most pronounced bundling behavior.
Drug Delivery Technology Market Segmentation
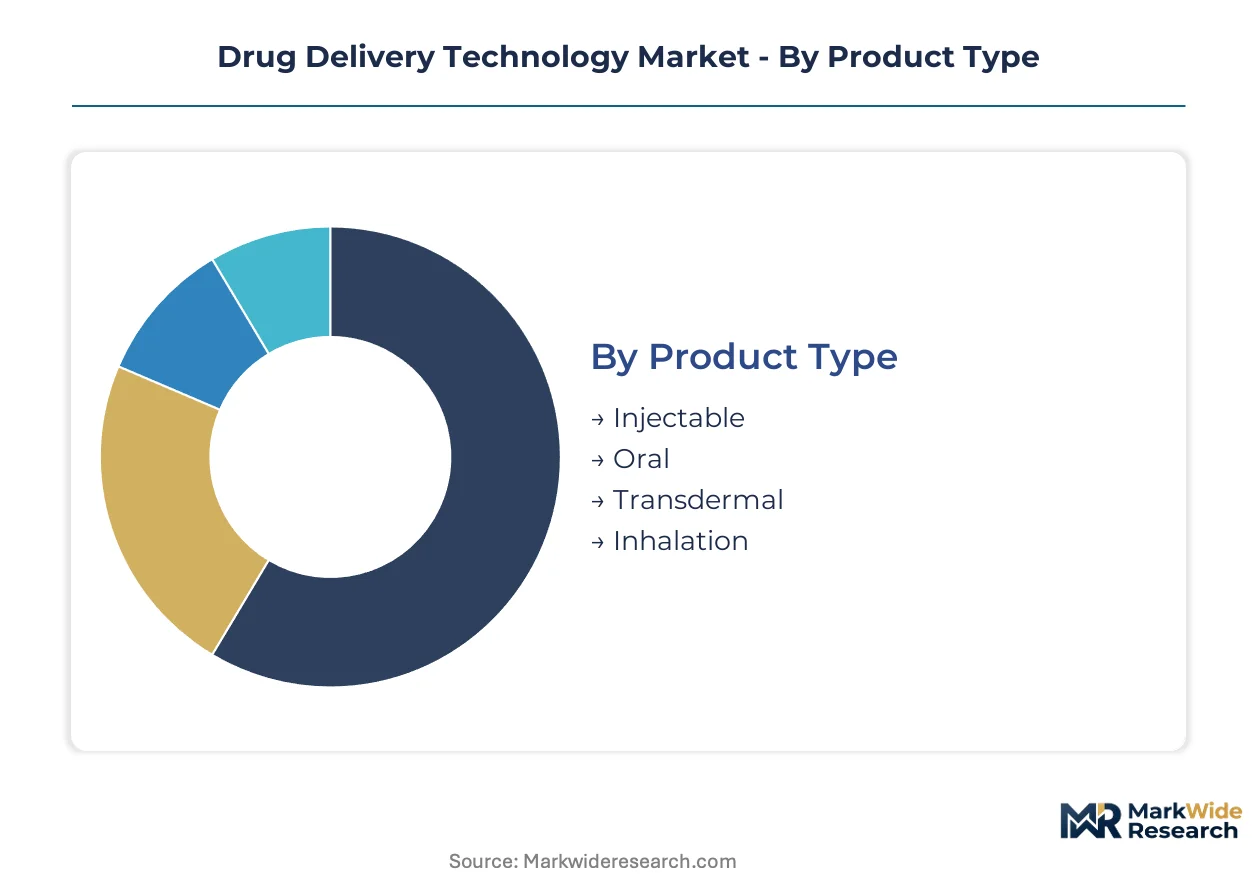
Drug delivery technology segmentation reveals divergent technical requirements across administration routes, with biologics expansion favoring injectable platforms while patient-centric design drives transdermal and oral innovation. Understanding these category boundaries enables targeted capital allocation toward platforms aligned with reimbursement and regulatory trajectories.
Product Type:
Route selection hinges on bioavailability requirements and patient self-administration capability, with chronic disease management shifting preferences toward less invasive options.
- Injectable:Encompasses prefillable syringes, autoinjectors, and infusion systems for biologics and biosimilars. Demand concentrates in the United States where oncology and immunology pipelines favor subcutaneous and intravenous protein therapeutics, constrained by cold-chain infrastructure costs in emerging markets.
- Oral:Modified-release tablets, capsules, and targeted-release formulations using polymeric coatings or osmotic pumps. Germany's reimbursement frameworks reward improved adherence profiles for chronic cardiovascular and diabetes medications, accelerating investment in gastroretentive and colon-targeted systems.
- Transdermal:Patches and passive absorption systems for hormone replacement, pain management, and smoking cessation. Japan's aging population drives demand for weekly dosing formats that reduce pill burden.
- Inhalation:Metered-dose inhalers, dry powder inhalers, and nebulizers for respiratory and systemic delivery. Regulatory scrutiny of propellant environmental impact reshapes device chemistry requirements.
Injectable leads on scale; transdermal leads on momentum.
Technology:
Platform selection reflects the tension between manufacturing maturity and therapeutic precision, with nanoparticle systems commanding premium pricing for tumor-targeting applications.
- Nanoparticles:Polymeric or lipid-based carriers ranging from 1-1000 nm enabling enhanced permeation, sustained release, and active targeting. United States oncology pipelines favor albumin-bound and polymeric nanoparticle formulations for taxanes and kinase inhibitors, though scale-up complexity limits supplier pools.
- Hydrogels:Three-dimensional hydrophilic polymer networks absorbing substantial water content for localized or sustained release. Post-surgical pain management and ophthalmic applications in Germany and Japan drive demand for biodegradable implantable reservoirs.
- Microneedles:Dissolvable or metallic arrays penetrating the stratum corneum for painless transdermal delivery. Pediatric vaccine programs pilot these formats for seasonal immunization campaigns.
- Liposomes:Phospholipid bilayer vesicles encapsulating hydrophilic or hydrophobic payloads. Manufacturing complexity sustains margin premiums despite competition from solid lipid nanoparticles.
Liposomes anchor current revenue; microneedles capture the steepest expansion trajectory.
Therapy Area:
Disease-specific pharmacokinetic requirements dictate platform choices, with oncology's narrow therapeutic windows demanding the most sophisticated targeting mechanisms.
- Oncology:Targeted delivery systems for cytotoxic agents, immunotherapies, and nucleic acid therapeutics. United States clinical pipelines concentrate investment in tumor microenvironment-responsive nanoparticles and liposomal formulations to reduce systemic toxicity.
- Cardiovascular:Oral and transdermal platforms for antihypertensives, anticoagulants, and lipid-lowering agents. Germany's chronic disease management programs reward adherence-improving extended-release formulations.
- Diabetes:Injectable insulin delivery systems transitioning toward closed-loop pumps and glucose-responsive formulations. Japan's reimbursement tiers favor devices demonstrating improved glycemic control outcomes.
- Neurology:Platforms addressing blood-brain barrier penetration for neurodegenerative and psychiatric indications. Intranasal and focused ultrasound-mediated delivery gain research traction.
Oncology dominates development investment; neurology presents the largest unmet need gap.
End User:
Site-of-care migration reshapes device requirements, with hospital-centric designs giving way to home-compatible formats that satisfy payer mandates.
- Hospitals:Acute care settings utilizing infusion pumps, implantable ports, and sophisticated controlled-release systems for inpatient oncology and critical care. United States health systems increasingly bundle device procurement with pharmaceutical contracts.
- Home Care:Self-administration formats including autoinjectors, prefilled syringes, and connected devices with dose-tracking capabilities. Germany and Japan now require home-compatible formats for chronic disease reimbursement eligibility.
- Clinics:Outpatient facilities administering long-acting injectables and physician-supervised infusion therapies. Microneedle pilot programs for seasonal vaccines target this channel.
- Research Laboratories:Preclinical and clinical trial supply of specialized formulations, including radiolabeled and placebo-matched delivery systems for pharmacokinetic studies.
Hospitals retain the highest per-patient device spend; home care is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as firms relocate production to jurisdictions with streamlined combination-product pathways and favorable reimbursement frameworks. Cost-of-compliance gaps between the FDA, EMA, and PMDA are accelerating facility investment decisions.
United States
Oncology pipeline concentration and biologics expansion drive demand for nanoparticle and liposomal formulations. FDA's combination product classification rules determine whether drug-device platforms follow pharmaceutical or medical device review pathways. The Boston-Cambridge corridor anchors preclinical development, while North Carolina's Research Triangle hosts commercial-scale aseptic processing facilities.
Germany
Chronic disease management programs reward adherence-improving extended-release oral formulations and home-compatible delivery devices. EMA's MDR alignment reduces duplicate testing burdens for active therapeutic devices. The Rhine-Ruhr industrial basin concentrates prefillable syringe and autoinjector manufacturing infrastructure serving European distribution networks.
Japan
Aging demographics fuel demand for weekly transdermal patches and self-administration formats that reduce pill burden. PMDA maintains distinct quality standards for novel polymer excipients that constrain qualified supplier pools. The Kansai region around Osaka hosts specialized liposome formulation facilities with dedicated aseptic processing capabilities.
China
Domestic biologics manufacturing scale-up creates demand for injectable platform infrastructure and connected delivery devices. NMPA's evolving combination product guidelines are converging toward international standards. The Yangtze River Delta around Shanghai concentrates contract manufacturing organizations serving multinational pharmaceutical partners.
India
Cost-competitive manufacturing attracts fill-finish operations for prefillable syringes and generic injectable platforms. CDSCO's quality enforcement is tightening for polymer excipient sourcing and device sterilization validation. Hyderabad's pharmaceutical cluster hosts specialized facilities for complex generic injectable formulations targeting regulated markets.
Drug Delivery Technology Market Vendor Landscape
Strategic partnerships dominate the current landscape as pharmaceutical sponsors seek captive device supply agreements and manufacturing scale. The vendor base stratifies across three tiers: diversified healthcare conglomerates with integrated delivery device divisions, specialized contract manufacturers focused on prefillable syringes and autoinjectors, and emerging technology developers advancing microneedle and hydrogel platforms. Consolidation pressures intensify as hospital procurement departments bundle device contracts with pharmaceutical supply agreements.
Within the diversified healthcare tier, Johnson & Johnson Services, Inc. and Pfizer Inc. represent archetypal players leveraging biologics portfolios to sustain injectable platform leadership. Novartis AG exemplifies the specialized pharmaceutical anchor investing in liposome and nanoparticle engineering capabilities. Becton, Dickinson and Company occupies a position as the dominant manufacturing-scale supplier of prefillable syringes and autoinjectors to multiple pharmaceutical partners.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Novartis AG |
| Pfizer Inc. |
| Becton, Dickinson and Company |
| West Pharmaceutical Services, Inc. |
| Baxter International Inc. |
| Gerresheimer AG |
| Medtronic |
| AstraZeneca PLC |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up contract manufacturing specialists have consolidated prefillable syringe and autoinjector production across the Rhine-Ruhr basin and North Carolina's Research Triangle, creating pricing discipline through captive supply agreements while constraining spot-market availability for standalone device purchasers. This ownership concentration enables volume-tiered contracting leverage with pharmaceutical sponsors but fragments price transparency for mid-tier entrants seeking smaller batch scales.
Pricing Analysis
Distributor margins on combination products compress pricing visibility, with three-tier pricing structure across premium, standard, and economy levels anchored by FDA certification tier and batch scale minimums. Quality grade differentiation separates aseptic-processed liposome formulations from standard prefilled syringes, while geographic delivery cost premiums apply to cold-chain biologics infrastructure. Pricing pressure stems from hospital procurement bundling mandates in the United States, forcing standalone device vendors toward direct-to-OEM discount structures. Research laboratories and emerging market distributors exhibit highest price sensitivity; oncology-focused pharmaceutical sponsors demonstrate lowest sensitivity due to reimbursement pass-through mechanisms.
Supply Chain Analysis
Cold-chain freight costs for temperature-sensitive biologics constrain distribution radius and inflate landed cost differentials between regional manufacturing hubs. Supply concentrates in the United States, Germany, and Japan for aseptic processing equipment and novel polymer excipients, with qualified supplier pools tethered to PMDA and EMA quality certifications. Raw material dependencies center on pharmaceutical-grade silicone for syringe barrels, borosilicate glass for cartridges, and specialized phospholipids for liposome formulations. Single-source vulnerability pervades novel polymer excipient sourcing approved under Japan's distinct quality standards. Distribution runs through pharmaceutical sponsor captive networks and specialized medical device distributors serving hospital procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Drug Delivery Technology Market functions as a stable compounder, with biologics pipeline expansion and chronic disease management decentralization generating durable demand for injectable and self-administration platforms across therapeutic categories.
For Market Incumbents: Deepen backward integration into novel polymer excipient production to circumvent PMDA-qualified supplier constraints and capture margin pools currently flowing to European and Japanese specialty chemical producers. Expand aseptic processing capacity in the Research Triangle corridor to serve United States oncology pipeline concentration. Prioritize human factors engineering talent acquisition to defend against emerging connected-device entrants threatening self-administration platform leadership.
For New Entrants and Emerging Players: Contract research organizations serving mid-cap biopharma sponsors represent the most penetrable channel partner type for microneedle and hydrogel platform commercialization, bypassing incumbent-dominated hospital procurement bundling. Target pediatric vaccine programs in Germany and Japan piloting dissolvable microneedle arrays for seasonal immunization campaigns. Pursue pharmacy-based administration partnerships that bypass clinical infrastructure requirements and accelerate patient acceptance metrics.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized liposome formulation facilities with dedicated aseptic processing capabilities in the Kansai region and North Carolina, where manufacturing complexity sustains margin premiums despite competition from solid lipid nanoparticles. Long-term viability centers on platforms demonstrating reimbursement pathway clarity across FDA, EMA, and PMDA jurisdictions. Monitor EMA MDR implementation enforcement as the signal to watch for compliance cost inflection and vendor consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA combination product classification determination shapes development timelines and capital requirements for drug-device platforms. |
| Manufacturing Scale-Up | Aseptic processing capacity expansion in Research Triangle and Rhine-Ruhr corridors serves biologics pipeline concentration. |
| Hospital System Partnership | Integrated supply agreements with United States health systems bypass standalone device vendor access constraints. |
| Reimbursement Strategy | Japan's revised pricing methodology rewards improved patient adherence outcomes with premium reimbursement tiers. |
| Strategic Partnership | Exclusive device alliances with pharmaceutical sponsors secure captive supply positions in bundled procurement environments. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with regulatory affairs leads, formulary directors, hospital procurement managers, and payer access specialists with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity across administration routes, technology platforms, and therapy areas.
Input-output matrices map unit economics from raw material excipients through finished device production to end-user administration, with segmentation dimensions spanning treatment line, dosage form, administration route, and regional regulatory cluster across the modeling period. CAGRs derive from patient population projections, pipeline advancement rates, and reimbursement framework evolution without year-specific anchoring. Forecast inputs incorporate cold-chain infrastructure expansion trajectories and human factors testing requirement harmonization between FDA and EMA jurisdictions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory pathway divergence, polymer excipient supply disruption, and hospital procurement consolidation patterns. Stakeholders should weight assumptions against their own operating context and monitor evolving combination product classification determinations for timeline revision signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Global Autologous Conditioned Plasma Market
Biomedical Technology
Asia-Pacific Exosome Research Products Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Global Neuroscience Antibodies and Assays Market
Biomedical Technology
Ontogenetic Market
Biomedical Technology
Biochips Market
Biomedical Technology
Europe Serine Proteases Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
Latin America Flow Cytometry Market
Biomedical Technology
Bioprocess Technology Market
Biomedical Technology
Global Automated Cell Cultures Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Ocular Drug Delivery Technology Market
Biomedical Technology
Human Biobanking Ownership Market