
 Liquid Biopsy Market | 2026-2036
Liquid Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Biopsy Market Analysis
Subscription-based assay panel renewals and software-defined variant reporting is rebalancing how laboratories contract for liquid biopsy services. Guardant Health leverages longitudinal patient monitoring programs to sustain recurring revenue streams. Exact Sciences Corporation anchors its commercial strategy in oncology practice integration, while QIAGEN competes through decentralized PCR-based workflows that reduce sample logistics burdens.
Liquid biopsy isolates and analyzes circulating biomarkers—primarily cell-free DNA, circulating tumor cells, and exosomes—from peripheral blood without tissue invasion, with analytical sensitivity thresholds often reaching 0.1% variant allele frequency for early-stage malignancy detection. Its primary commercial purpose centers on real-time cancer surveillance, therapy selection, and minimal residual disease monitoring where tissue re-biopsy proves impractical. Cell-free DNA assays command the dominant share of current test volumes, though exosome-based platforms represent the fastest-growing technology segment as researchers unlock proteomic and transcriptomic cargo profiling. Digital droplet PCR occupies a mature niche in single-gene companion diagnostics, while next generation sequencing captures expanding multi-gene panel demand.
The FDA and CMS shape market access through premarket approval pathways and national coverage determination frameworks that dictate reimbursement eligibility for ctDNA assays. EMA's IVDR transition and WHO classification standards for in vitro diagnostics impose additional conformity requirements on manufacturers seeking multi-regional distribution. Stakeholders must monitor evolving payer evidence requirements as health technology assessment bodies tighten criteria for analytical and clinical validity demonstrations.
Market Dynamics
The liquid biopsy market restructures around Medicare reimbursement determinations for circulating tumor DNA assays, which compress decision timelines for oncology departments evaluating blood-based molecular profiling platforms.
Growth Catalysts
- Companion diagnostic pathway expansion:FDA premarket approvals for ctDNA-based therapy selection claims accelerate clinical utility demonstrations. Pathology departments integrate these assays into standard care protocols.
- Cell-free DNA analytical sensitivity advances:Detection thresholds reaching 0.1% variant allele frequency enable minimal residual disease monitoring applications previously requiring tissue re-biopsy.
- Centralized reference laboratory networks:United States payer frameworks favor high-throughput processing hubs that standardize variant reporting and reduce per-test operational costs.
Market Restraints
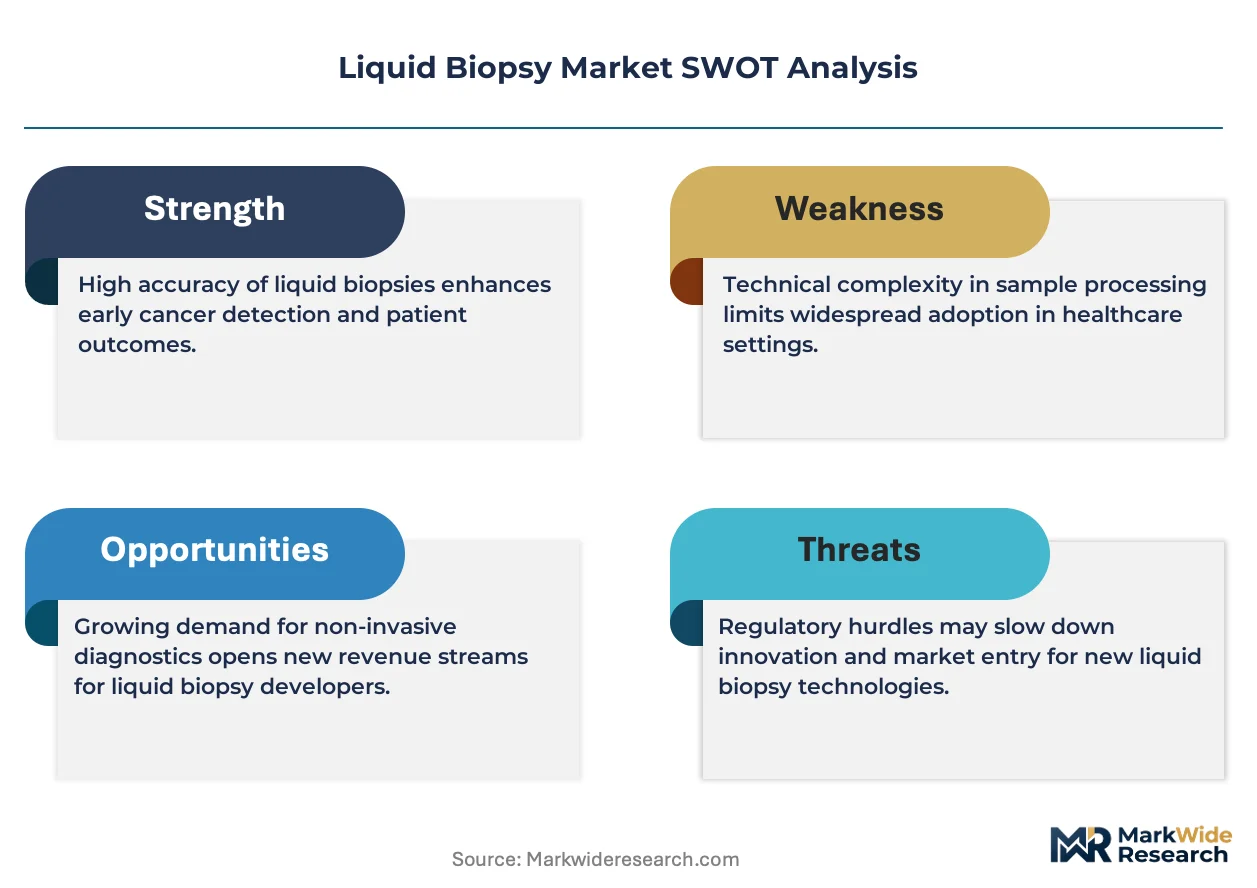
- Sample logistics cold-chain requirements:Pre-analytical variables including hemolysis and cfDNA degradation impose strict temperature controls on peripheral blood transport from collection sites to processing facilities.
- EMA IVDR conformity costs:European Union in vitro diagnostic regulation transition demands expanded clinical evidence packages and notified body involvement, extending time-to-market for multi-regional manufacturers.
- Exosome isolation technical complexity:Ultracentrifugation and size-exclusion chromatography methods require specialized equipment and trained operators, limiting decentralized deployment of proteomic cargo profiling platforms.
Strategic Opportunities
- Digital droplet PCR workflow decentralization:QIAGEN's instrument placement strategies reduce sample logistics burdens for community oncology practices seeking rapid single-gene companion diagnostic turnaround.
- Longitudinal patient monitoring programs:Subscription-based assay panel renewals create recurring revenue structures as Guardant Health anchors commercial relationships through therapy response surveillance contracts.
- Exosome transcriptomic cargo profiling:Emerging platforms unlock microRNA and mRNA analysis from blood-derived vesicles, expanding biomarker discovery beyond cfDNA mutation detection.
Industry Challenges
- Bioinformatics pipeline validation:Variant calling algorithm standardization across laboratories requires extensive analytical validation studies to satisfy FDA and CMS evidentiary requirements.
- Health technology assessment evidence thresholds:Payer bodies tighten criteria for clinical validity demonstrations, demanding prospective interventional data rather than retrospective analytical performance studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Biopsy Market |
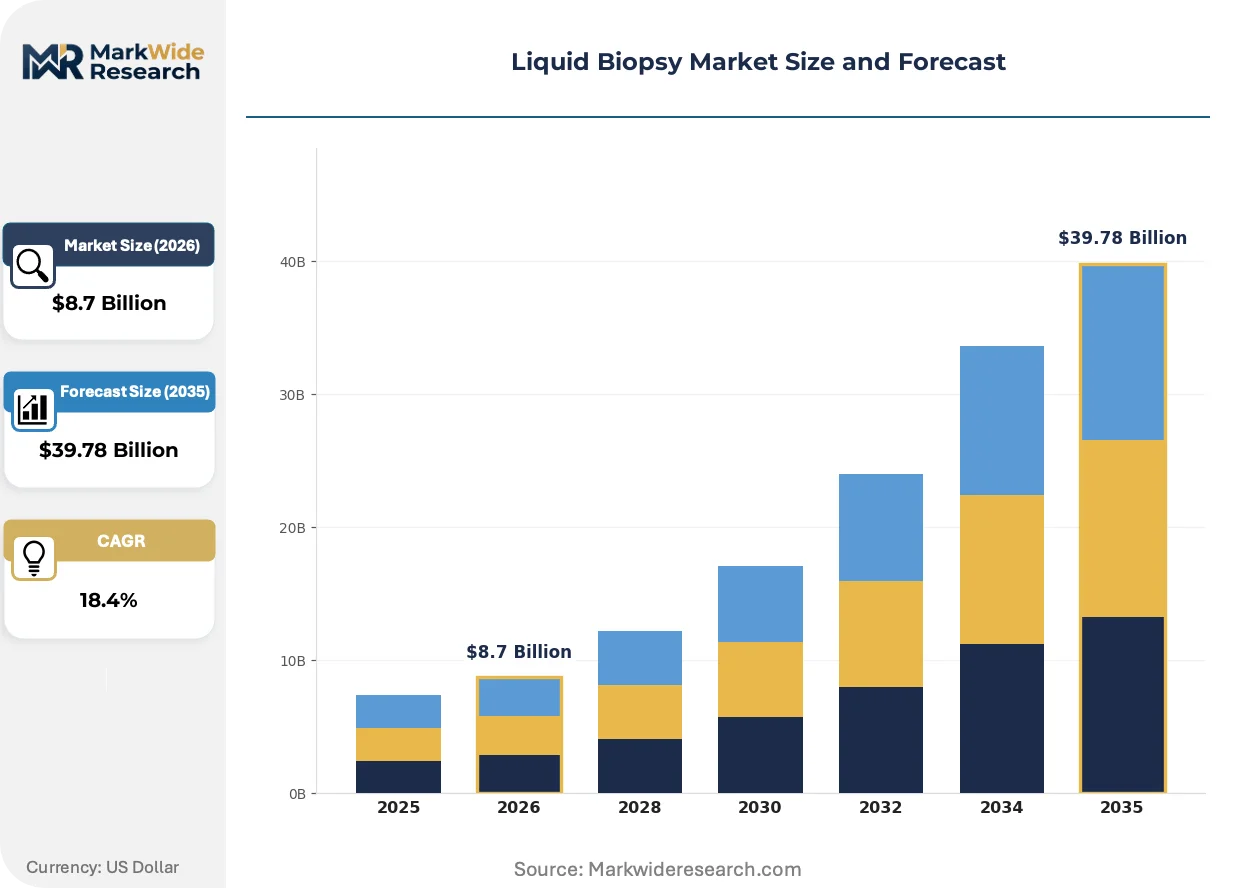
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circulating Tumor Cells, Cell-Free DNA, Exosomes, Circulating RNA Technology: Next Generation Sequencing, PCR, Microarray, Digital Droplet PCR End User: Hospitals, Research Laboratories, Diagnostic Centers, Academic Institutions Application: Cancer Screening, Treatment Monitoring, Recurrence Detection, Biomarker Discovery |
| Companies Covered | Guardant Health, Natera, Inc., F. Hoffmann-La Roche Ltd, QIAGEN, Thermo Fisher Scientific Inc., Illumina, Inc., Myriad Genetics, Inc., Exact Sciences Corporation, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Biopsy Market Emerging Trajectories
Multi-omics platform convergence and software-defined reporting architectures reshape competitive positioning as laboratories renegotiate service contracts around recurring panel access rather than per-test transactions.
Next-generation sequencing multi-gene panels is integrating exome-wide copy number alteration detection with targeted mutation profiling. Major cancer centers deploy these platforms for comprehensive molecular characterization, compressing the analytical window between sample receipt and therapy-matched report generation. The technology is integrating longitudinal mutation tracking capabilities that enable clonal evolution monitoring across treatment lines.
EMA's In Vitro Diagnostic Regulation imposes quality management system requirements and post-market surveillance obligations on manufacturers seeking CE marking. European reference laboratories now demand enhanced traceability documentation for consumables and reagents, shifting procurement criteria toward vertically integrated suppliers. Smaller IVD developers face capital constraints in building notified body relationships, consolidating commercial access around established multi-regional players.
Oncology practice consolidation alters purchasing authority structures as hospital systems centralize molecular pathology decisions under enterprise laboratory medicine committees. Independent community oncologists lose direct vendor negotiation leverage, channeling assay selection through integrated delivery network formulary processes. This concentration is most visible in United States metropolitan markets where vertically aligned payers steer volume toward captive reference laboratories.
Liquid Biopsy Market Segmentation
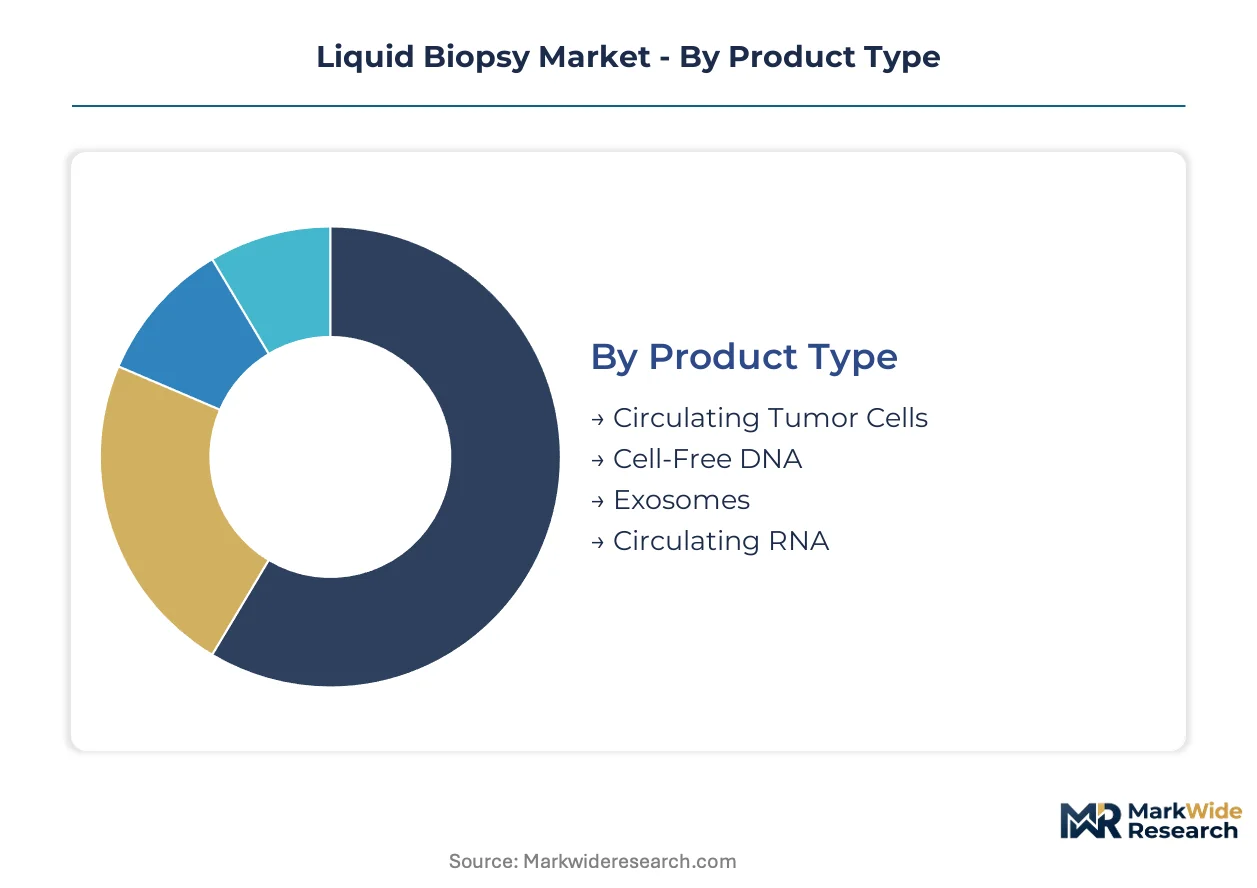
Segmentation in liquid biopsy reflects divergent regulatory pathways and reimbursement thresholds. FDA premarket approval requirements and CMS coverage determinations create distinct commercialization timelines across biomarker types and technology platforms.
Product Type:
FDA breakthrough device designation and companion diagnostic claims concentrate in cell-free DNA and circulating tumor cell assays, while exosome platforms navigate earlier-stage regulatory frameworks.
- Cell-Free DNA:Fragmented tumor-derived DNA circulating in plasma enables mutation profiling with analytical sensitivity reaching 0.1% variant allele frequency. Oncology departments at major hospital systems in the United States drive demand for therapy selection and minimal residual disease monitoring applications.
- Circulating Tumor Cells:Intact viable cells shed from primary tumors permit functional analysis beyond genotyping, including protein expression and drug sensitivity testing. Research laboratories utilize these platforms for biomarker discovery where single-cell resolution proves essential.
- Exosomes:Membrane-bound vesicles carry proteomic and transcriptomic cargo for multi-omics profiling.
- Circulating RNA:Messenger RNA and microRNA species offer dynamic gene expression readouts.
Leading the category by volume: Cell-Free DNA. Growing fastest: Exosomes.
Technology:
Platform selection determines laboratory capital requirements, personnel training intensity, and turnaround time commitments to clinical customers.
- Next Generation Sequencing:Massively parallel sequencing of multi-gene panels enables comprehensive mutation profiling across hundreds of cancer-related genes. Major cancer centers deploy these platforms for complex cases requiring broad molecular characterization beyond single-gene companion diagnostic scope.
- Digital Droplet PCR:Partitioned reaction chambers achieve absolute quantification of rare mutations with high precision. Community oncology practices favor this technology for rapid single-gene companion diagnostic turnaround where sample logistics constraints limit centralized laboratory access.
- PCR:Conventional amplification methods serve established single-analyte testing workflows.
- Microarray:Hybridization-based detection supports copy number alteration and methylation profiling applications.
Highest installed base: Next Generation Sequencing. Steepest expansion trajectory: Digital Droplet PCR.
End User:
Purchasing authority consolidation shifts procurement decisions from individual physicians to enterprise laboratory medicine committees.
- Hospitals:Integrated delivery networks centralize molecular pathology decisions under enterprise formulary processes. United States metropolitan markets exhibit pronounced consolidation as vertically aligned payers steer volume toward captive reference laboratories.
- Research Laboratories:Academic medical centers and contract research organizations drive demand for exploratory biomarker discovery platforms. These facilities prioritize analytical flexibility over regulatory clearance status for early-stage clinical trial applications.
- Diagnostic Centers:Independent reference laboratories compete on turnaround time and panel customization.
- Academic Institutions:University-affiliated research programs focus on technology development and validation studies.
Primary volume concentration: Hospitals. Fastest-growing procurement authority: Research Laboratories.
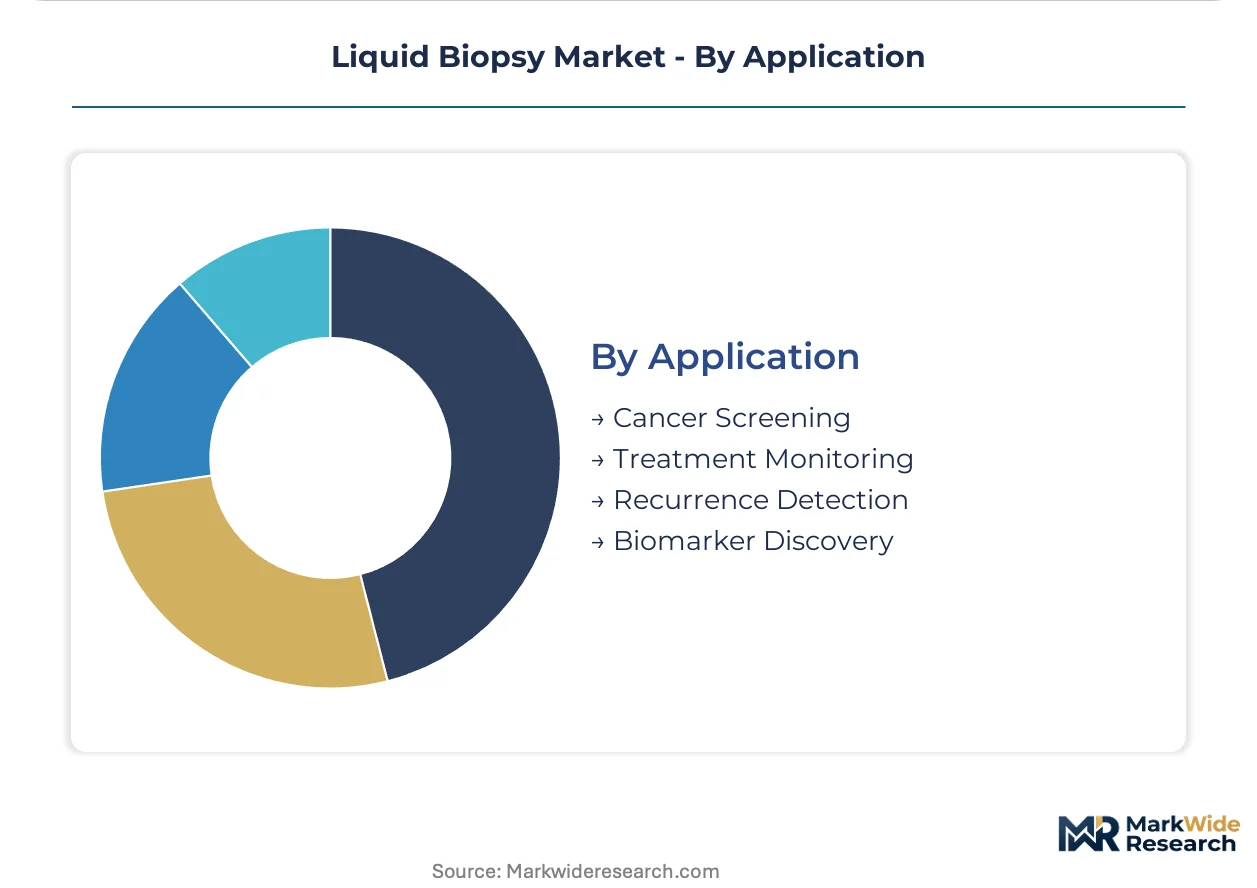
Application:
Reimbursement coding and coverage determinations segment commercial opportunity by clinical use case maturity.
- Treatment Monitoring:Serial ctDNA assessment during therapy enables real-time response evaluation and early resistance detection. Medicare coverage determinations for circulating tumor DNA assays accelerate clinical adoption in the United States for this indication.
- Cancer Screening:Multi-cancer early detection panels target asymptomatic populations for tumor-agnostic screening. Regulatory pathways remain under development as manufacturers generate prospective interventional evidence for health technology assessment bodies.
- Recurrence Detection:Post-treatment surveillance identifies molecular relapse before radiographic progression.
- Biomarker Discovery:Exploratory research applications support pharmaceutical companion diagnostic development partnerships.
Most established reimbursement: Treatment Monitoring. Expanding most quickly: Cancer Screening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical and Academic Area anchors the densest concentration of liquid biopsy commercialization activity, with Massachusetts General Hospital and Dana-Farber Cancer Institute driving clinical validation studies that shape FDA premarket approval precedents for circulating tumor DNA assays.
United States
Medicare coverage determinations for ctDNA assays and companion diagnostic pathway expansion drive hospital system procurement decisions. FDA breakthrough device designations accelerate market access for multi-cancer early detection panels. The San Francisco Bay Area concentrates venture-backed platform developers alongside Stanford Medicine and UCSF's molecular pathology laboratories.
Germany
EMA's In Vitro Diagnostic Regulation transition demands expanded clinical evidence packages from manufacturers seeking CE marking for circulating biomarker platforms. The country's statutory health insurance system reimburses liquid biopsy tests for therapy selection in advanced lung and colorectal malignancies. Heidelberg's German Cancer Research Center and University Hospital drive biomarker discovery collaborations with industrial partners.
China
NMPA regulatory reforms streamline innovative medical device approvals for domestic liquid biopsy developers targeting multi-gene panels. Hospital procurement reform concentrates purchasing authority at provincial centralized tendering platforms. Shanghai's Zhangjiang Hi-Tech Park hosts the highest density of cell-free DNA assay developers serving the domestic oncology market.
Japan
PMDA's Sakigake designation system accelerates review timelines for liquid biopsy platforms demonstrating superior analytical performance against tissue-based alternatives. National health insurance reimbursement for circulating tumor DNA testing covers non-small cell lung cancer resistance monitoring. Tokyo's Koto Ward clusters precision medicine startups alongside University of Tokyo Hospital's clinical trial infrastructure.
United Kingdom
NHS England's genomic medicine service integrates liquid biopsy testing into standardized cancer pathways through designated genomic laboratory hubs. MHRA post-Brexit regulatory autonomy permits accelerated access pathways for innovative diagnostics. Cambridge's biomedical campus concentrates exosome isolation technology developers alongside Cancer Research UK-funded translational research programs.
Liquid Biopsy Market Vendor Landscape
Capital-heavy reference laboratory operators compete with asset-light assay developers outsourcing manufacturing and clinical processing to contracted partners. The vendor base stratifies across three tiers: vertically integrated platform owners controlling instrument, consumable, and service revenue streams; specialized assay developers licensing detection chemistry to third-party laboratories; and decentralized technology providers enabling point-of-care molecular testing workflows. Consolidation pressures intensify as hospital system procurement centralization favors enterprise-scale contract negotiators. Strategic moves concentrate on Medicare coverage determination alignment and longitudinal patient monitoring program anchoring.
Among precision oncology platform specialists, Guardant Health and Exact Sciences Corporation exemplify the integrated service model, while QIAGEN occupies a position within the decentralized workflow enablement archetype. These three entities represent divergent commercial strategies: comprehensive laboratory service provision versus technology licensing and instrument placement. Their positioning reflects fundamental segmentation in customer acquisition economics between high-throughput centralized processing and distributed rapid-turnaround deployment.
| Leading Market Players |
|---|
| Guardant Health |
| Natera, Inc. |
| F. Hoffmann-La Roche Ltd |
| QIAGEN |
| Thermo Fisher Scientific Inc. |
| Illumina, Inc. |
| Myriad Genetics, Inc. |
| Exact Sciences Corporation |
| Sysmex Corporation |
| Others |
Supply Flow & Price Mechanics
FDA Quality System Regulation compliance gates both qualified reagent supply and premium-tier pricing access for circulating tumor DNA assay manufacturers, as notified body certification costs stratify vendor tiers by analytical validation depth.
Pricing Analysis
Outcome-linked reimbursement anchors value-based pricing for minimal residual disease monitoring contracts, with Medicare coverage determinations setting the benchmark for commercial payer negotiations. Pricing stratifies across FDA-cleared companion diagnostic tiers, laboratory-developed test services, and research-use-only reagent bundles. Cost compression in decentralized digital PCR workflows intensifies as QIAGEN's instrument placement programs reduce per-test operational overhead. Community oncology practices exhibit highest price sensitivity due to sample volume constraints, while major cancer centers prioritize analytical sensitivity over unit economics.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and China coordinate hub-and-spoke logistics for temperature-controlled plasma collection kits and stabilized nucleic acid reagents. Manufacturing draws from specialized inputs including fluorophore-conjugated probes, microfluidic cartridges, and sequencing flow cells. Single-source vulnerability concentrates in semiconductor-dependent digital PCR instrumentation and proprietary sequencing chemistries. Distribution runs through centralized reference laboratory networks that standardize pre-analytical processing and reduce cold-chain degradation risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid biopsy market sits in a technology-transition phase as next-generation sequencing multi-gene panels displace single-analyte PCR workflows for therapy selection decisions.
For Market Incumbents: Hedge against margin compression in centralized laboratory services by deepening backward integration into consumable manufacturing and locking hospital system formulary positions through longitudinal patient monitoring contracts. The threat of decentralized digital PCR deployment by community oncology practices demands rapid companion diagnostic claim expansion to maintain pricing power. For New Entrants and Emerging Players: The mid-tier pricing gap between premium NGS comprehensive panels and economy single-gene PCR assays opens white-space for targeted exosome transcriptomic platforms serving biomarker discovery laboratories. Penetrable entry points concentrate in Asia-Pacific research institutions prioritizing analytical flexibility over FDA clearance status, with go-to-market execution anchored through pharmaceutical companion diagnostic development partnerships. For Investors and Strategic Acquirers: Medicare national coverage determination for multi-cancer early detection is the leading indicator that screening applications will command valuation premiums over surveillance-only platforms. Long-term viability across the analysis window favors vertically integrated platform owners controlling instrument, consumable, and service revenue streams. Acquisition targets should demonstrate notified body relationships under EMA IVDR and anchored hospital system contracts. Watch FDA breakthrough device designation velocity as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA premarket approval for ctDNA companion diagnostic claims accelerates hospital system formulary adoption. |
| Reimbursement Strategy | Medicare coverage determination alignment secures commercial payer contracts for minimal residual disease monitoring. |
| Hospital System Partnership | Enterprise laboratory medicine committee relationships channel volume through centralized reference networks. |
| Software Companion Development | Variant reporting algorithms integrated with EHR systems reduce pathology department workflow friction. |
| CE Marking Pathway | EMA IVDR conformity enables multi-regional distribution into European Union oncology departments. |
Methodological Framework
FDA 510(k) and PMA filings, CMS national coverage determination documents, and EMA IVDR technical documentation formed the secondary backbone, cross-referenced with primary interviews involving molecular pathology laboratory directors, hospital procurement committee members, regulatory affairs specialists at IVD manufacturers, and payer access strategists at commercial insurance plans. Bottom-up and top-down triangulation validated segment-level demand estimates against instrument placement data and reagent consumption patterns.
The analytical lens combined bottom-up modeling of installed instrument bases and consumable throughput with top-down reconciliation against hospital system procurement budgets and pharmaceutical companion diagnostic partnership disclosures. Segmentation dimensions spanned biomarker type, technology platform, end-user setting, and clinical application maturity across the projection horizon. CAGRs derived from logistic diffusion curves fitted to Medicare coverage expansion timelines and FDA approval precedent analysis, with sensitivity testing around analytical sensitivity improvement trajectories and sample logistics automation adoption rates.
Inputs from CMS coverage determination databases and hospital procurement contract repositories were available through the study window; gaps in real-time pharmaceutical pipeline disclosure introduce uncertainty bands around companion diagnostic addressable market sizing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Biochips Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market
Biomedical Technology
Global Protein Crystallization and Crystallography Market
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
Europe Serine Proteases Market
Biomedical Technology
Global RNA Analysis Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Latin America Flow Cytometry Market
Biomedical Technology
Global Plant Stem Cell Market
Biomedical Technology
Protein Characterization and Identification Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Enzymatic DNA Synthesis Market