
 North America Proteomics Market | 2026-2036
North America Proteomics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Proteomics Market Analytics
Pharmaceutical company demand for biomarker discovery is hardening as oncology pipelines require deeper protein-level characterization. Thermo Fisher Scientific leverages its Orbitrap platform dominance to anchor high-resolution mass spectrometry supply chains across the region. Danaher Corporation sustains competitive pressure through Beckman Coulter's automation-integrated sample prep workflows. Bruker differentiates with timsTOF technology for high-throughput proteomics in academic core facilities.
Proteomics encompasses the large-scale study of proteins, including their structures, functions, and interactions, typically analyzed through mass spectrometry with resolution thresholds below 10 parts per million for confident peptide identification. The field serves pharmaceutical development, clinical diagnostics, and systems biology research by quantifying protein expression changes across disease states and therapeutic interventions. Reagents capture recurring revenue through consumable antibodies and enrichment kits tied to instrument installed bases. Mass spectrometry instruments command premium pricing but face elongating replacement cycles as sensitivity improvements plateau. Services segments expand fastest as pharmaceutical companies outsource complex quantitative proteomics workflows to specialized providers.
FDA oversight of laboratory-developed tests and mass spectrometry-based clinical assays shapes instrument validation requirements and software compliance burdens for manufacturers. The Clinical Laboratory Improvement Amendments framework, administered through CMS, establishes quality standards that filter which proteomics platforms qualify for diagnostic revenue. Stakeholders must monitor evolving FDA guidance on multi-analyte proteomic signatures and their pathway toward approved companion diagnostics.
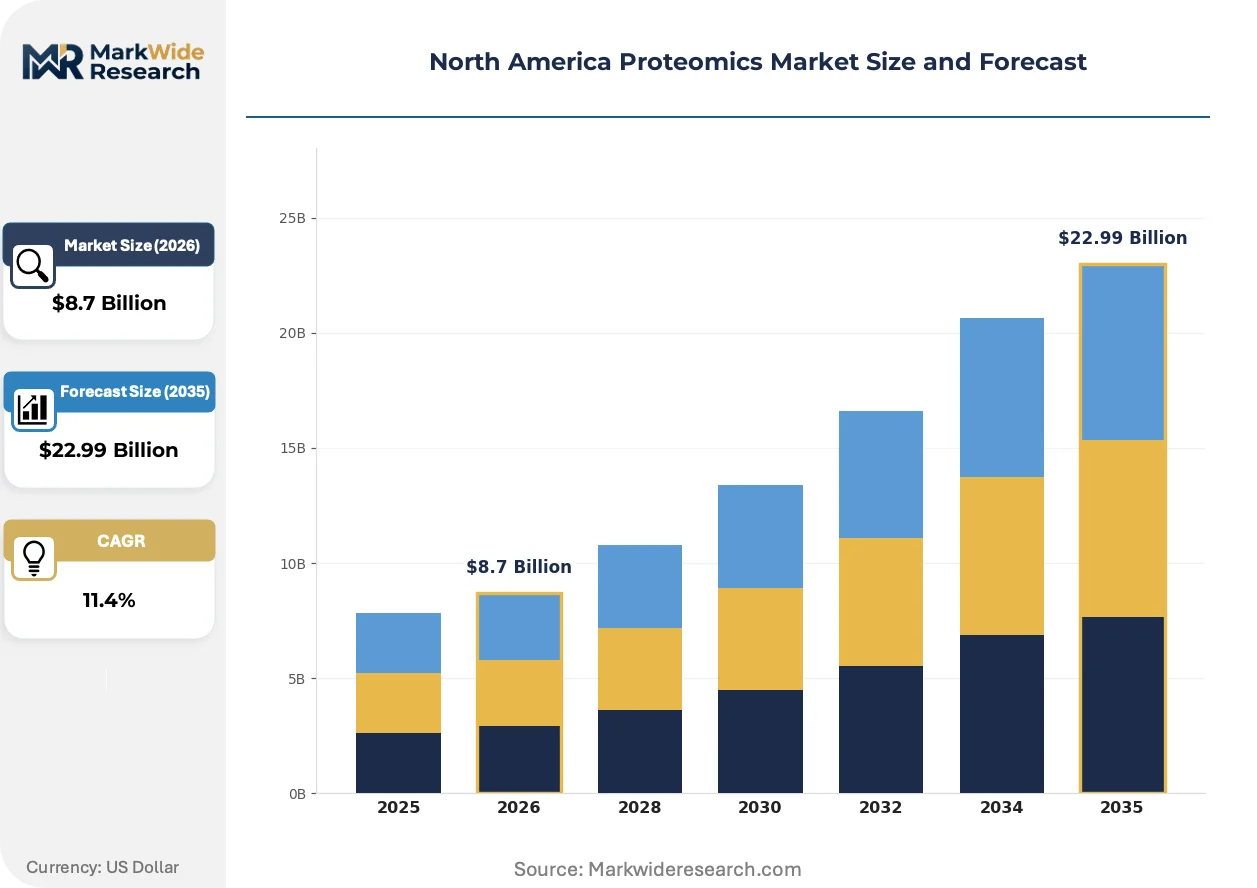
Market Dynamics
FDA guidance on mass spectrometry-based clinical assays is compressing instrument qualification timelines while pharmaceutical biomarker discovery budgets harden against sensitivity plateaus in legacy platforms.
Growth Catalysts
- Companion diagnostic pipelines:Oncology drug developers require protein-level biomarker validation for FDA-approved therapeutics, expanding core facility instrument utilization rates.
- CLIA quality framework:CMS-administered laboratory standards filter platform eligibility for diagnostic revenue, creating compliant-installed base lock-in effects.
- Boston-San Diego corridor concentration:Biotech cluster density accelerates specialized service provider expansion and talent pool depth.
Market Restraints
- Helium supply volatility:Mass spectrometry cooling systems depend on concentrated Middle East and US federal reserve helium sources.
- Orbitrap platform concentration:High-resolution instrument supply chains anchor to single dominant vendor architecture.
- Peptide identification sensitivity ceilings:Resolution thresholds below 10 parts per million face diminishing returns on incremental R&D investment.
Strategic Opportunities
- AI-driven spectral interpretation:Machine learning deconvolution algorithms are converging with cloud-based bioinformatics pipelines to compress analysis turnaround.
- Multi-analyte proteomic signatures:FDA pathway clarification for companion diagnostic submissions creates regulatory tailwind for qualified assay developers.
- Sample prep automation integration:Academic core facilities and CROs adopt modular liquid-handling robotics to scale throughput without linear headcount expansion.
Industry Challenges
- Cross-trained mass spectrometry-bioinformatics talent scarcity:Hybrid skill requirements outpace university pipeline output.
- Legacy LIMS integration friction:New platform deployments face data architecture compatibility barriers with established pharmaceutical IT systems.
- Software compliance documentation burden:FDA 21 CFR Part 11 validation timelines elongate product release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Proteomics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Services Technology: Mass Spectrometry, Chromatography, Electrophoresis, Protein Microarrays Application: Biomarker Discovery, Drug Development, Clinical Diagnostics, Toxicology End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Hospitals |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Danaher Corporation, Bio-Rad Laboratories, Illumina, Bruker, Promega Corporation, Merck KGaA, Waters Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Proteomics Market Evolving Landscape
Instrumentation sensitivity plateaus are redirecting competitive investment toward workflow automation and computational analysis layers rather than raw hardware performance.
Trapped ion mobility spectrometry is converging with time-of-flight mass detection to enable high-throughput proteomics without sacrificing peptide identification confidence. Academic core facilities in California and Massachusetts deploy timsTOF platforms for large-scale biomarker discovery. This convergence compresses the cost-per-sample economics that previously favored lower-resolution alternatives.
FDA draft guidance on multi-analyte proteomic signatures is clarifying validation requirements for laboratory-developed tests. Instrument manufacturers face expanded software documentation burdens and quality system audits. Pharmaceutical sponsors in the United States accelerate companion diagnostic partnership discussions to secure parallel approval pathways.
Pharmaceutical companies now unbundle complex quantitative proteomics workflows from internal core facilities to specialized CRO providers. This restructuring displaces capital-intensive instrument ownership with fee-for-service access to cutting-edge platforms. The shift concentrates most visibly among mid-cap biotech firms in San Diego and Cambridge lacking scale for captive proteomics infrastructure.
North America Proteomics Market Segmentation
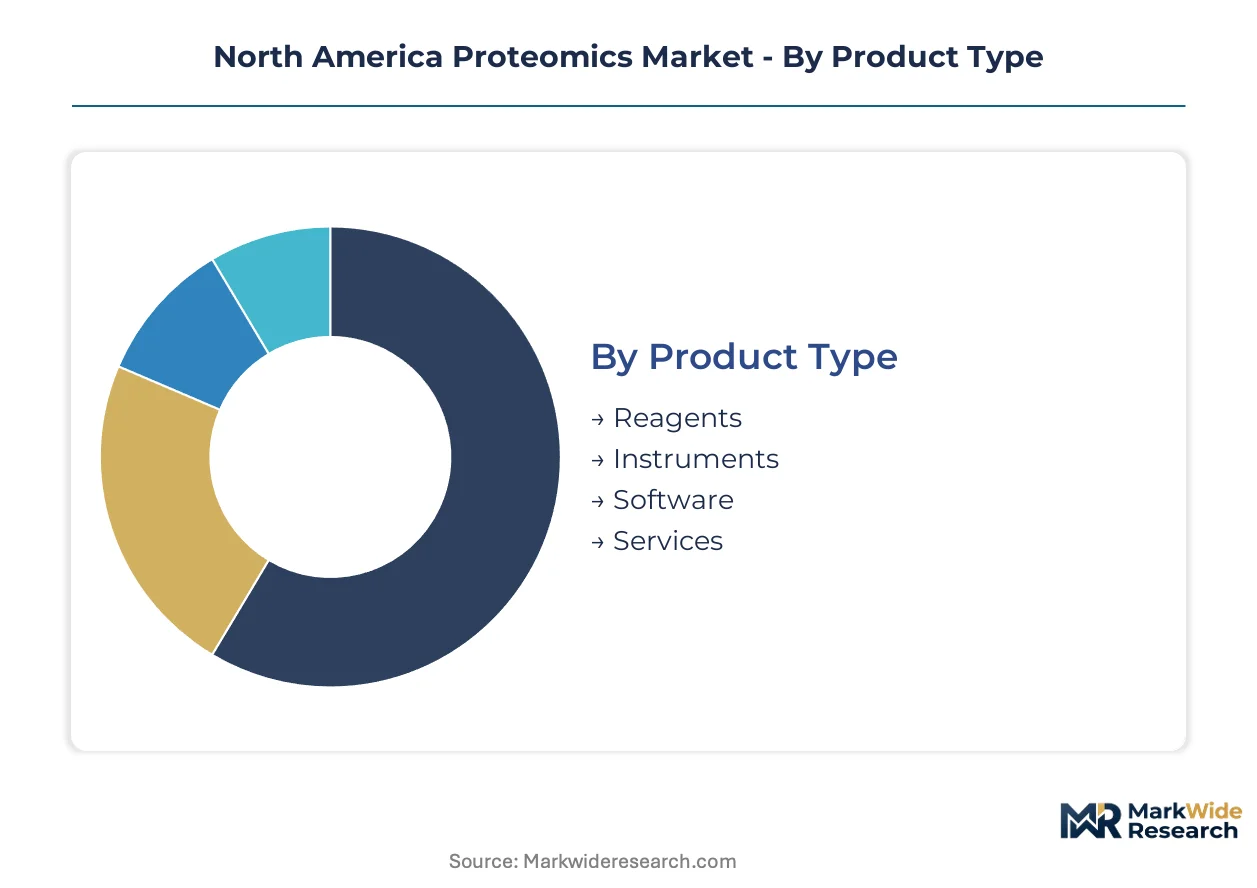
Proteomics market segmentation reveals how value pools concentrate around consumable reagents and high-resolution instrumentation, while services capture expanding outsourcing demand from pharmaceutical sponsors seeking flexible access to advanced workflows.
Product Type:
Supply concentration tilts toward recurring revenue streams anchored to installed instrument bases across the United States and Canada.
- Reagents:Consumable antibodies, enrichment kits, and sample preparation chemicals generate predictable revenue tied to mass spectrometry platform installed bases. Academic core facilities in Boston and San Diego drive bulk purchasing through centralized procurement consortia.
- Instruments:High-resolution mass spectrometry systems command capital budgets exceeding seven figures, with replacement cycles elongating as sensitivity improvements plateau. Thermo Fisher Scientific's Orbitrap architecture dominates hospital and pharmaceutical laboratory deployments.
- Software:Bioinformatics platforms for spectral interpretation and peptide identification face FDA 21 CFR Part 11 compliance burdens that filter vendor eligibility.
- Services:Outsourced quantitative proteomics workflows expand fastest among mid-cap biotech firms lacking captive infrastructure.
Reagents absorb the bulk of installed capacity; services are expanding most quickly.
Technology:
Cost tier differentiation separates premium high-resolution platforms from standardized separation techniques serving routine applications.
- Mass Spectrometry:Orbitrap and timsTOF platforms define the performance frontier for peptide identification below 10 parts per million resolution. FDA guidance on clinical assay validation is reshaping software documentation requirements for manufacturers serving diagnostic laboratories.
- Chromatography:Liquid chromatography upstream of mass detection remains essential for complex sample separation. Pharmaceutical quality control laboratories in New Jersey and Pennsylvania standardize on ultra-high-pressure systems for batch release testing.
- Electrophoresis:Gel-based protein separation persists in academic teaching laboratories and resource-constrained settings.
- Protein Microarrays:Multiplexed affinity assays compete for biomarker screening applications against mass spectrometry alternatives.
Mass spectrometry commands the steepest expansion trajectory; electrophoresis maintains share in cost-sensitive segments.
Application:
Customer type concentration distinguishes pharmaceutical sponsor requirements from clinical diagnostic quality mandates.
- Biomarker Discovery:Large-scale protein quantification across disease states demands high-throughput platforms with statistical power for cohort studies. Oncology pipeline investments by sponsors in Cambridge, Massachusetts, accelerate core facility utilization.
- Drug Development:Pharmacokinetic and mechanistic studies require precise protein quantification to support regulatory submissions. CLIA-compliant laboratories filter platform eligibility for diagnostic revenue streams.
- Clinical Diagnostics:FDA-cleared proteomic assays for companion diagnostics face validation timelines that elongate product release cycles.
- Toxicology:Protein biomarker panels for safety assessment support preclinical and clinical trial monitoring.
Biomarker discovery absorbs the bulk of installed capacity; clinical diagnostics is climbing the fastest.
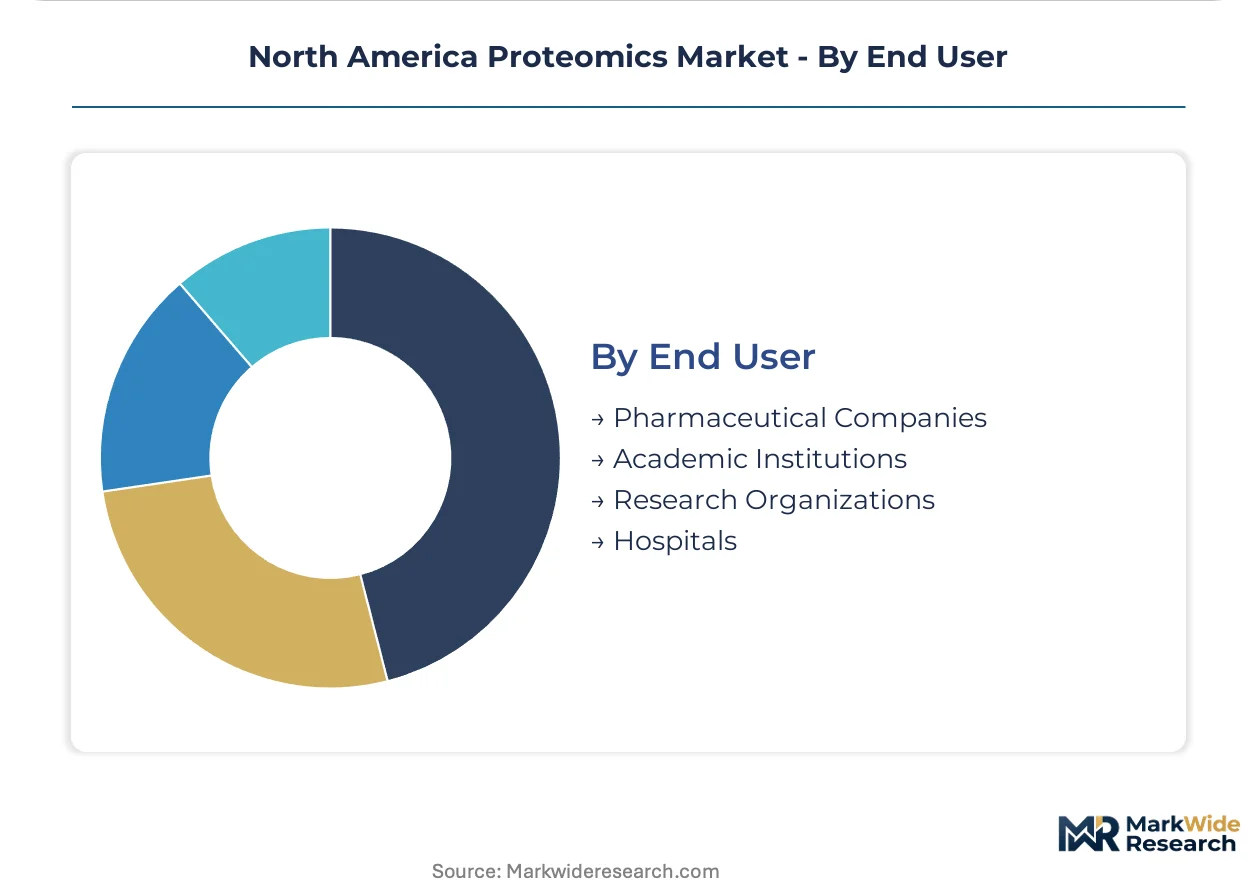
End User:
Geography concentration around the Boston-San Diego corridor shapes demand patterns and service provider expansion strategies.
- Pharmaceutical Companies:Large sponsors and mid-cap biotech firms unbundle proteomics workflows from internal core facilities to specialized CRO providers. San Diego cluster density accelerates fee-for-service access to cutting-edge platforms.
- Academic Institutions:University core facilities deploy timsTOF and Orbitrap instrumentation funded by National Institutes of Health instrumentation grants. Massachusetts and California institutions lead large-scale biomarker discovery consortia.
- Research Organizations:Non-profit institutes bridge basic science translation through collaborative access to pharmaceutical sponsors.
- Hospitals:Clinical laboratories face CMS-administered quality standards that determine platform eligibility for diagnostic reimbursement.
Pharmaceutical companies absorb the bulk of installed capacity; academic institutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Opportunity Zone incentives around Boston and San Diego biotech corridors accelerate proteomics infrastructure concentration. FDA guidance on mass spectrometry-based clinical assays shapes instrument qualification requirements across all three North American markets.
United States
Pharmaceutical sponsors in Cambridge and San Diego unbundle proteomics workflows to specialized CRO providers. FDA 21 CFR Part 11 compliance burdens filter software vendor eligibility for diagnostic laboratories. The Boston-San Diego corridor captures the bulk of high-resolution mass spectrometry deployments through NIH instrumentation grants.
Canada
Academic core facilities in Toronto and Vancouver expand timsTOF platform access for large-scale biomarker discovery consortia. Health Canada oversight of laboratory-developed tests aligns validation requirements with FDA frameworks. Ontario and British Columbia institutions lead national proteomics infrastructure through federal research funding programs.
Mexico
Contract research organizations in Mexico City and Querétaro capture fee-for-service proteomics demand from US pharmaceutical sponsors seeking cost-advantaged outsourcing. COFEPRIS regulatory pathways for clinical laboratory standards evolve toward international harmonization. The Bajío Region attracts specialized service provider expansion through proximity to US border logistics.
North America Proteomics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with instrument vendors commanding consolidated positions in high-resolution mass spectrometry while reagent suppliers fragment across antibody and enrichment kit niches. Three archetypes dominate: integrated life science conglomerates with captive proteomics portfolios, precision instrument specialists anchored to single technology platforms, and modular service providers scaling through automation-integrated workflows. Competitive maneuvering concentrates on strategic partnerships for companion diagnostic co-development and geographic expansion into qualified opportunity zones.
Among integrated life science conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify platform-dominant archetypes. Thermo Fisher Scientific anchors high-resolution mass spectrometry supply chains through its Orbitrap architecture. Danaher Corporation sustains competitive pressure through automation-integrated sample preparation workflows under its Beckman Coulter subsidiary. Bruker occupies a differentiated position with timsTOF technology deployment across academic core facilities.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Danaher Corporation |
| Bio-Rad Laboratories |
| Illumina |
| Bruker |
| Promega Corporation |
| Merck KGaA |
| Waters Corporation |
| Others |
Value Network & Pricing Analysis
EPA helium conservation mandates gate qualified supply access for mass spectrometry cooling systems and anchor premium-tier pricing for FDA-validated instrument platforms serving CLIA-compliant diagnostic laboratories.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to Orbitrap and timsTOF platforms with validated software documentation, while spot inventory discounts emerge for legacy quadrupole systems facing replacement pressure from sensitivity plateaus. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared companion diagnostic platforms from research-grade instrumentation and refurbished hospital surplus units. Price differentiation hinges on CLIA certification tier and geographic delivery cost from Massachusetts and California manufacturing clusters. Cost compression in mid-resolution segments is intensifying because pharmaceutical sponsors consolidate vendor relationships around qualified automation-integrated workflows.
Supply Chain Analysis
Helium supply for mass spectrometry cooling systems rests on concentrated Middle East extraction and US federal reserve releases, with specialty magnet wire and high-vacuum pumps drawing from German and Japanese precision component manufacturers. Raw material dependencies span rare earth elements for superconducting magnets, ultra-high-purity gases for ionization sources, and specialized ceramics for detector assemblies. Single-source vulnerability concentrates in Orbitrap platform architecture supply chains anchored to single-vendor component specifications. Distribution runs through direct field service organizations for capital instruments and academic consortia procurement for reagent bulk purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where FDA 21 CFR Part 11 software compliance burdens force weaker instrumentation vendors without validated quality systems toward exit or acquisition.
For Market Incumbents: Anticipate displacement pressure from AI-driven spectral interpretation platforms by deepening automation-integrated sample prep capabilities and securing captive helium supply contracts through long-term offtake agreements with US federal reserve distributors. Anchor installed base lock-in through CLIA-compliant software validation investments that elongate pharmaceutical laboratory switching costs.
For New Entrants and Emerging Players: Launch via fee-for-service proteomics CRO models targeting mid-cap biotech firms in San Diego and Cambridge lacking captive infrastructure, with modular liquid-handling robotics as the anchor capability. White-space concentration sits in multi-analyte proteomic signature assay development for companion diagnostic partnerships, where FDA pathway clarification creates regulatory tailwind for qualified developers.
For Investors and Strategic Acquirers: FDA draft guidance publication on multi-analyte proteomic signatures is the leading indicator that companion diagnostic co-development partnerships will concentrate value capture among qualified assay developers with validated software platforms. Acquisition target archetypes include specialized CROs with timsTOF platform access and cross-trained mass spectrometry-bioinformatics talent pools. Long-term viability favors vertically integrated service providers with automation-integrated workflows over pure-play instrument vendors facing sensitivity plateau constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Secures parallel FDA approval pathways for oncology drug sponsors and assay developers. |
| Helium Supply Contracting | Locks in cooling gas access for mass spectrometry platforms amid federal reserve volatility. |
| Sample Prep Automation Integration | Compresses cost-per-sample economics for academic core facilities and CRO scaling. |
| AI Spectral Interpretation Licensing | Accelerates peptide identification turnaround without hardware sensitivity breakthroughs. |
| CLIA Quality System Investment | Qualifies platforms for diagnostic revenue streams under CMS-administered laboratory standards. |
Research Methodology
FDA 510(k) filings, Clinical Laboratory Improvement Amendments quality standards documentation, and National Institutes of Health instrumentation grant awards formed the secondary backbone, cross-referenced against primary interviews with mass spectrometry platform directors, pharmaceutical biomarker discovery leads, academic core facility managers, and CLIA laboratory quality officers. Bottom-up triangulation combined installed base estimates from instrument vendor service records with reagent consumption rates by platform type, while top-down validation referenced pharmaceutical R&D expenditure disclosures and federal research funding allocations.
Bottom-up modeling segmented the market by product type, technology platform, application endpoint, and end-user category, with geographic clustering around the Boston-San Diego corridor treated as a distinct analytical lens. CAGRs were derived from instrument replacement cycle analysis and outsourcing penetration trends across the projection horizon, incorporating sensitivity assumptions around FDA guidance timeline acceleration and helium supply disruption scenarios.
The model assumes a particular technology adoption path; alternative pathways for trapped ion mobility spectrometry convergence would alter the outlook if resolution thresholds advance beyond current peptide identification ceilings. Forecasts reflect assumptions about regulatory harmonization between FDA and Health Canada frameworks, with cross-trained talent pipeline output and multi-analyte signature validation timelines as the specific risk factors warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Reverse Transcriptase Enzymes Market
Biomedical Technology
ST2 Biomarker Market
Biomedical Technology
Middle East and Africa Cell Counting Market
Biomedical Technology
Pyrosequencing Market
Biomedical Technology
Drug Discovery Enzymes Market
Biomedical Technology
Biochips Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
Protein Characterization and Identification Market
Biomedical Technology
Exonucleases Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Global Biocompatibility Testing Services Market
Biomedical Technology
Drug Delivery Technology Market
Biomedical Technology
Global Immunofluorescence Assay Market