
 Global Cell Dissociation Market | 2026-2036
Global Cell Dissociation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell Dissociation Market Foresight
Stem cell research is recalibrating procurement patterns across the Global Cell Dissociation Market as developers demand higher viability yields from primary tissue sources. Thermo Fisher Scientific leverages its reagent portfolio breadth to anchor supply relationships with multi-site academic consortia. Miltenyi Biotec specializes in automated tissue dissociators that dominate workflow integration in European cell therapy manufacturing facilities. Danaher Corporation extends its life sciences instrumentation footprint through diagnostic lab partnerships requiring standardized dissociation protocols.
Cell dissociation encompasses enzymatic, mechanical, and chemical methods for separating adherent cells from culture substrates or fragmenting solid tissues into viable single-cell suspensions, with collagenase and trypsin concentrations typically calibrated to tissue density and desired downstream assay compatibility. The primary commercial purpose centers on enabling reproducible cell yields for flow cytometry, cell sorting, and bioproduction scale-up. Enzymatic Solutions command the largest revenue share due to protocol familiarity across biopharmaceutical firms, while Composite Kits represent the fastest-growing category as vendors bundle optimized enzyme cocktails with mechanical dissociation tools to reduce user optimization burden. Mechanical Tools occupy a mature niche in high-throughput drug screening where automated homogenizers replace manual mincing to preserve membrane receptor integrity.
FDA guidance on cell therapy manufacturing and EMA's Advanced Therapy Medicinal Products framework shape validation requirements for dissociation reagents used in clinical-grade production, compelling vendors to document absence of animal-derived components and endotoxin thresholds. China's NMPA bioprocessing standards and Japan's PMDA cell processing facility regulations add compliance layers for multinational suppliers seeking market access across Asia-Pacific manufacturing hubs. Stakeholders must monitor evolving pharmacopeial standards for dissociation enzymes as regulatory agencies tighten traceability requirements for critical raw materials in regenerative medicine supply chains.
Market Dynamics
Automated enzymatic dissociation systems are compressing manual protocol margins as biopharmaceutical manufacturers scale single-cell analysis workflows for precision medicine pipelines.
Growth Catalysts
- EMA Advanced Therapy Medicinal Products framework:Clinical-grade manufacturing mandates validate dissociation reagent suppliers, creating procurement pull from European cell therapy developers seeking pre-qualified raw materials.
- Collagenase-trypsin enzyme cocktails:Optimized composite kits reduce user optimization burden, accelerating adoption among academic consortia running multi-site reproducibility studies.
- China's NMPA bioprocessing standards:Regulatory harmonization compels multinational suppliers to establish local endotoxin documentation capabilities, opening manufacturing hub access.
Market Restraints
- Animal-derived component documentation:FDA and EMA traceability requirements for xeno-free reagent certification inflate supplier compliance costs and elongate validation timelines.
- Enzyme supply concentration:Collagenase production clusters in specialized fermentation facilities, exposing buyers to batch-to-batch variability risks during demand surges.
- Mechanical dissociation substitution:Automated homogenizers preserve membrane receptor integrity for flow cytometry applications, eroding enzymatic method share in high-throughput drug screening.
Strategic Opportunities
- India CDMO infrastructure buildout:Contract development and manufacturing organizations scaling cell therapy capacity create demand for standardized dissociation protocols and training services.
- Japan PMDA cell processing facility regulations:Compliance requirements for regenerative medicine commercialization favor vendors offering integrated reagent-instrument bundles with documented GMP workflows.
- Microfluidic-mechanical convergence:Lab-on-chip dissociation devices enable point-of-care tissue processing, opening clinical diagnostic applications beyond research laboratories.
Industry Challenges
- GMP-grade enzyme purification expertise:Cell therapy manufacturers report 12-18 month lead times to qualify alternative suppliers, constraining supply flexibility during demand spikes.
- Legacy protocol standardization:Academic laboratories maintain heterogeneous manual methods, complicating vendor efforts to demonstrate automated system ROI across fragmented customer workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell Dissociation Market |
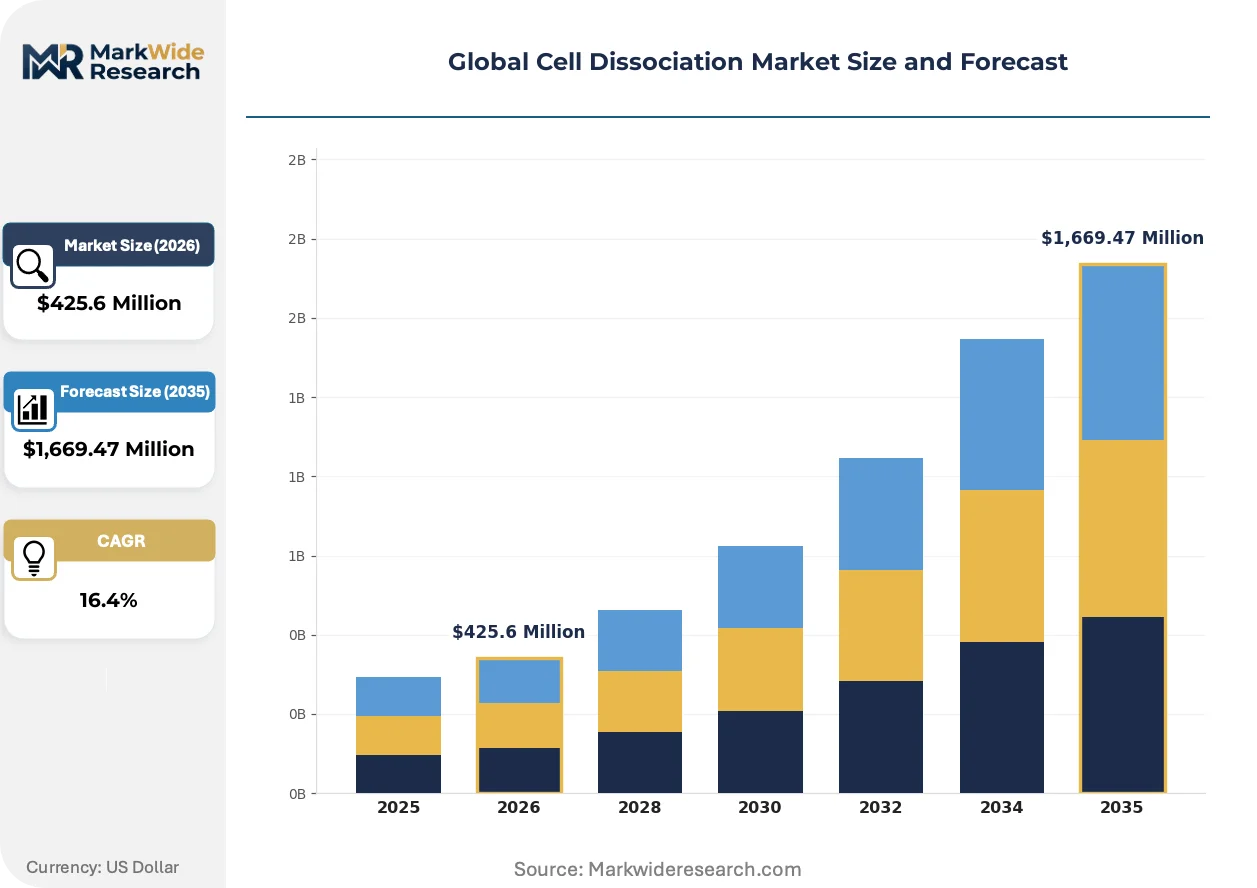
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $1,669.47 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymatic Solutions, Mechanical Tools, Chemical Agents, Composite Kits Application: Tissue Engineering, Single Cell Analysis, Drug Screening, Stem Cell Research, Regenerative Biology End User Sector: Biopharmaceutical Firms, Academic Research Centers, Contract Research Organizations, Diagnostic Labs Solution Format: Liquid Reagents, Powder Formulations, Ready-to-Use Kits, Concentrated Stocks |
| Companies Covered | Becton, Dickinson and Company, Miltenyi Biotec, Thermo Fisher Scientific, Corning Incorporated, Sartorius AG, Merck KGaA, STEMCELL Technologies, PromoCell GmbH, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell Dissociation Market Shifts & Advancements
Instrument-reagent integration is reshaping competitive positioning as vendors bundle hardware with optimized enzyme cocktails to capture recurring consumable revenue streams.
Gentle mechanical dissociation platforms using microfluidic shearing is expanding into cell therapy manufacturing workflows. CDMOs adopt these systems to preserve cell surface marker integrity for downstream cell sorting applications. The technology is expanding into quality control protocols where viability yields directly determine batch release decisions.
REACH registration requirements for industrial enzymes are tightening substance documentation obligations for European suppliers. Dissociation reagent manufacturers must now submit extended safety data sheets covering enzyme subtypes used in clinical applications. European cell therapy developers increasingly require suppliers to demonstrate SVHC-free formulations ahead of scheduled regulatory deadlines.
Consolidated procurement frameworks are emerging as multi-site biopharmaceutical firms negotiate enterprise-wide dissociation reagent contracts. CDMOs and large pharma centralize purchasing decisions to standardize protocols across manufacturing networks. Germany and the United States show the strongest concentration of these consolidated buying arrangements, pressuring mid-tier suppliers on price and service bundling.
Global Cell Dissociation Market Segmentation
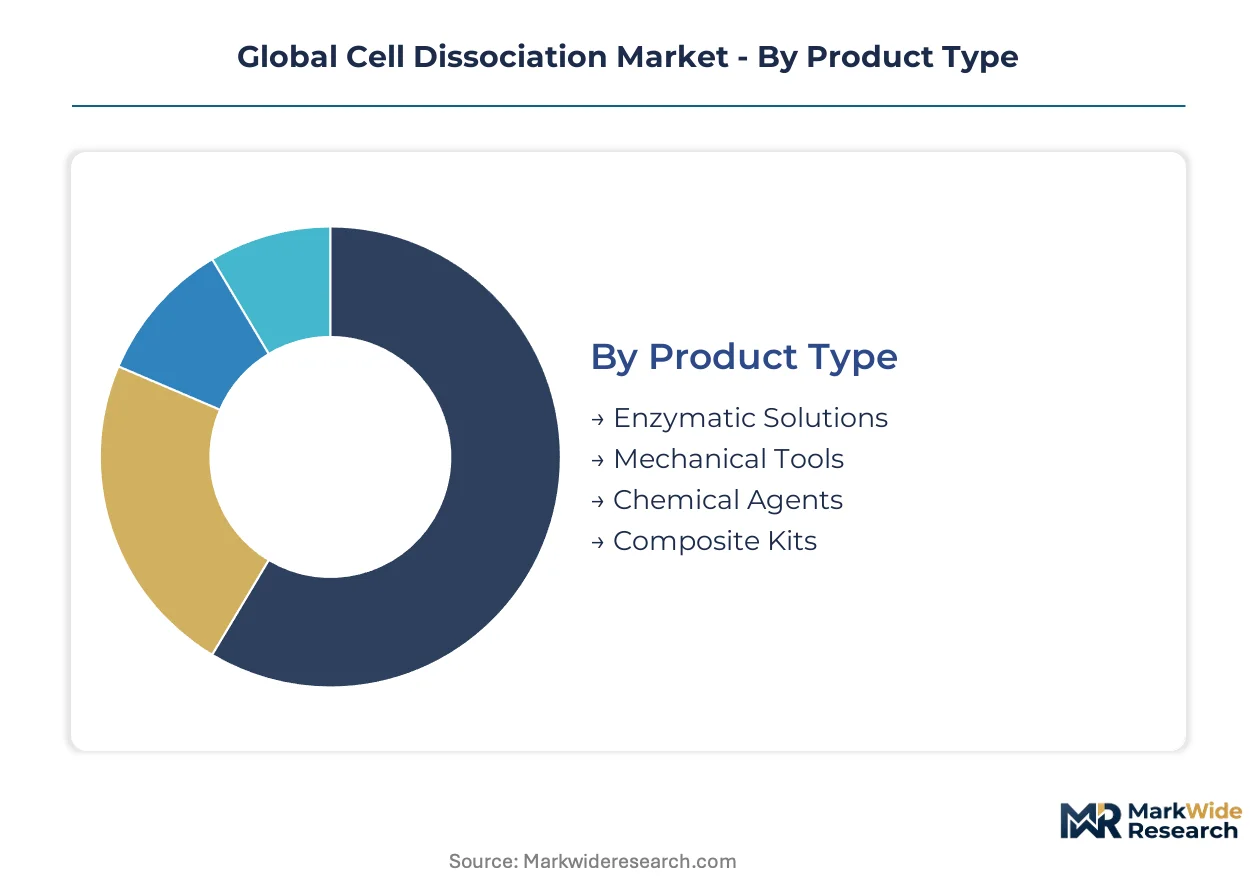
Cell dissociation procurement follows distinct upgrade cycles across product formats and end-use applications. Biopharmaceutical manufacturers prioritize validated reagent-instrument bundles while academic centers optimize for protocol flexibility and cost efficiency.
Product Type:
Replacement cycles accelerate as automated workflows displace manual protocols in high-throughput environments.
- Enzymatic Solutions:Collagenase and trypsin formulations dominate current procurement volumes due to established protocol familiarity across biopharmaceutical quality control labs. Demand concentrates in United States and German cell therapy manufacturing facilities where FDA and EMA validation requirements favor documented enzyme subtypes.
- Mechanical Tools:Automated homogenizers and tissue disruptors preserve membrane receptor integrity for flow cytometry applications. Adoption accelerates in drug screening laboratories seeking to reduce enzyme-induced cell surface marker degradation during dissociation.
- Chemical Agents:Chelating solutions and non-enzymatic dissociation buffers serve specialized applications where enzyme activity would compromise downstream assays.
- Composite Kits:Pre-optimized enzyme cocktails bundled with dissociation protocols reduce user optimization burden. Steepest expansion trajectory as vendors capture recurring consumable revenue through integrated reagent-instrument contracts.
Volume placements concentrate in Enzymatic Solutions; the faster expansion belongs to Composite Kits.
Application:
End-use prioritization shifts with funding allocations toward precision medicine and regenerative therapy pipelines.
- Tissue Engineering:Scaffold-based organoid development requires gentle dissociation preserving extracellular matrix attachment factors. Procurement concentrates in academic consortia and biopharmaceutical firms scaling 3D culture workflows for therapeutic screening.
- Single Cell Analysis:RNA sequencing and multi-omics pipelines demand high-viability yields from primary tissue sources. Adoption accelerates in precision medicine programs across United States and China where single-cell atlases guide therapeutic target identification.
- Drug Screening:High-throughput compound libraries require standardized dissociation protocols ensuring reproducible cell yields across automated liquid handling platforms.
- Stem Cell Research:Pluripotent cell maintenance and differentiation studies favor xeno-free dissociation reagents meeting evolving regulatory documentation requirements.
- Regenerative Biology:Cell therapy manufacturing applications impose GMP-grade purity standards with extended supplier qualification timelines.
Procurement scale tilts toward Single Cell Analysis; Regenerative Biology shows the steepest margin expansion as clinical-grade validation commands premium pricing.
End User Sector:
Customer sophistication determines format preferences and supplier relationship structures.
- Biopharmaceutical Firms:Enterprise-wide standardization initiatives consolidate dissociation reagent purchasing across multi-site manufacturing networks. These buyers negotiate integrated reagent-instrument bundles with documented GMP workflows and audit-ready supplier qualification packages.
- Academic Research Centers:Heterogeneous manual protocols persist across individual laboratories, fragmenting vendor efforts to demonstrate automated system return on investment. Procurement prioritizes cost efficiency and protocol flexibility over standardization.
- Contract Research Organizations:Client-mandated protocols drive reagent diversity requirements, complicating inventory management and supplier consolidation efforts.
- Diagnostic Labs:Regulatory compliance for clinical-grade cell processing favors pre-qualified reagent suppliers with established quality management systems.
Revenue concentration sits with Biopharmaceutical Firms; Diagnostic Labs represent the most rapidly expanding customer category as clinical cell processing scales.
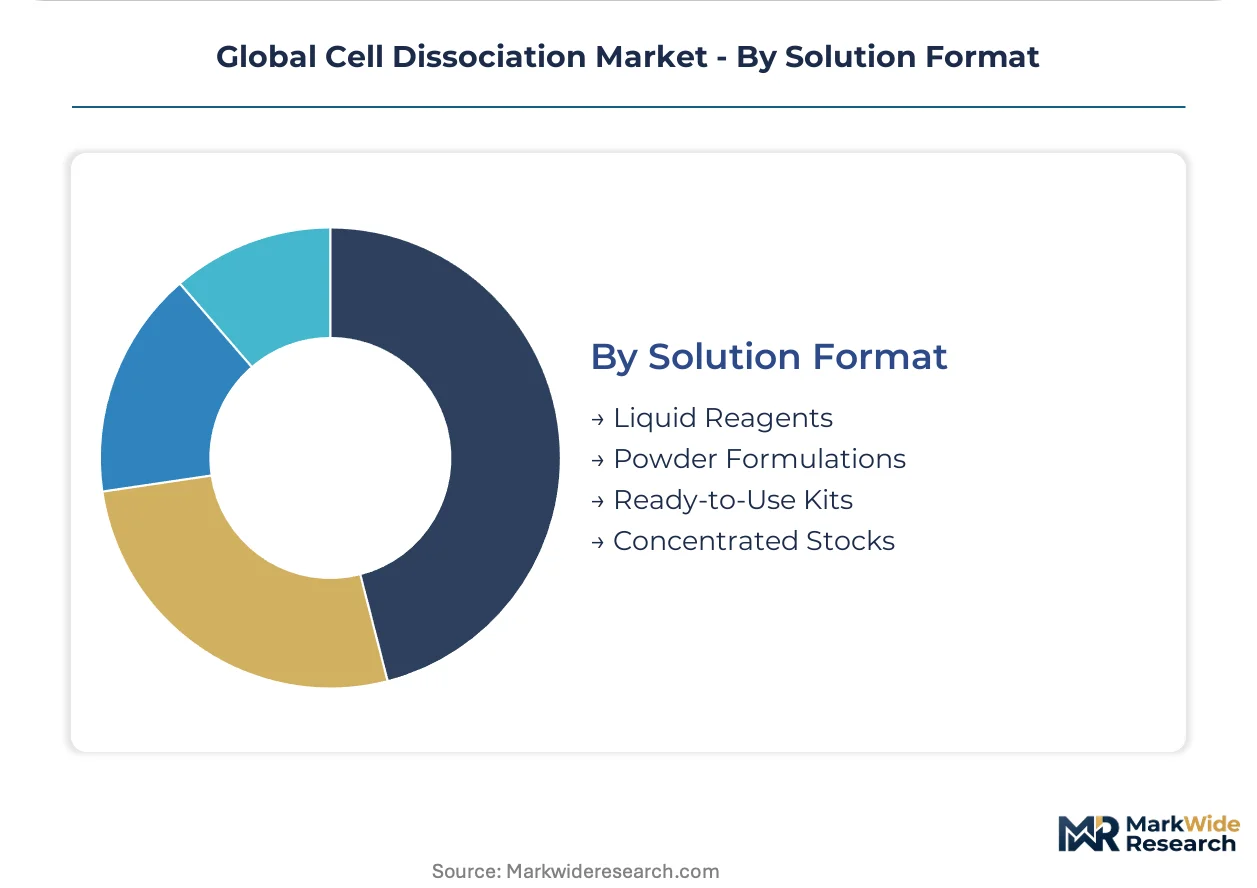
Solution Format:
Format selection trade-offs balance convenience against storage logistics and per-use economics.
- Liquid Reagents:Ready-to-pour enzyme solutions eliminate reconstitution steps, reducing technician time in high-throughput screening environments. Cold chain requirements constrain distribution reach to established logistics corridors.
- Powder Formulations:Lyophilized enzymes extend shelf stability and reduce shipping costs for international procurement. Reconstitution protocols introduce batch-to-batch variability risks that complicate multi-site reproducibility studies.
- Ready-to-Use Kits:Pre-aliquoted dissociation cocktails with standardized protocols accelerate method deployment in resource-constrained laboratories. Premium pricing reflects convenience value capture.
- Concentrated Stocks:Bulk enzyme procurement enables custom dilution protocols optimized to specific tissue densities and desired digestion kinetics.
Shipment volumes favor Liquid Reagents; Ready-to-Use Kits gain share fastest as standardization pressures intensify across contract manufacturing networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell therapy manufacturing clusters in designated special economic zones concentrate procurement demand for validated dissociation systems across three continents. FDA, EMA, and NMPA regulatory frameworks reshape supplier qualification requirements in each jurisdiction.
United States
Biopharmaceutical firms scaling single-cell analysis pipelines drive enzyme solution procurement in Greater Boston and the San Francisco Bay Area. FDA guidance on cell therapy manufacturing mandates xeno-free reagent documentation, extending supplier validation timelines. Maryland's I-270 biotech corridor hosts multiple GMP-grade dissociation protocol development facilities serving regenerative medicine startups.
Germany
EMA's Advanced Therapy Medicinal Products framework validates dissociation reagent suppliers for European cell therapy developers. REACH registration requirements for industrial enzymes tighten substance documentation obligations for manufacturers. The Rhine-Main biotech cluster around Frankfurt anchors automated tissue dissociator adoption in contract manufacturing networks.
China
NMPA bioprocessing standards compel multinational suppliers to establish local endotoxin documentation capabilities for manufacturing hub access. Shanghai's Zhangjiang Hi-Tech Park concentrates cell therapy CDMO infrastructure buildout. Beijing-Tianjin-Hebei corridor facilities adopt standardized dissociation protocols to meet dual carbon goals in bioproduction energy efficiency.
Japan
PMDA cell processing facility regulations favor vendors offering integrated reagent-instrument bundles with documented GMP workflows. The Kansai region around Osaka hosts regenerative medicine commercialization facilities requiring gentle mechanical dissociation platforms. Tokyo's Koto Ward bioclusters drive demand for viability-preserving protocols in stem cell research applications.
India
CDSCO oversight of cell therapy manufacturing creates compliance requirements for imported dissociation reagents used in clinical applications. Hyderabad's Genome Valley and Bengaluru's Electronic City concentrate CDMO infrastructure scaling cell therapy capacity. Maharashtra's biotech parks attract contract research organizations requiring standardized training services for dissociation protocol deployment.
Global Cell Dissociation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated reagent-instrument bundles capturing premium positioning in biopharmaceutical procurement. The vendor base organizes around three strategic archetypes: diversified life sciences conglomerates with broad reagent portfolios, specialized automation firms with workflow-integrated hardware, and regional enzyme suppliers with fermentation-based production expertise. Competitive dynamics center on M&A activity consolidating enzyme supply chains and strategic partnerships locking in multi-site academic consortia.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and Danaher Corporation anchor the premium tier through enterprise-wide standardization contracts. Miltenyi Biotec exemplifies the specialized automation archetype with European manufacturing facility penetration. Sartorius AG occupies a position bridging both categories with integrated bioprocessing solutions. These three entities represent distinct competitive vectors: portfolio breadth, workflow integration depth, and bioproduction scale-up capability respectively.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Miltenyi Biotec |
| Thermo Fisher Scientific |
| Corning Incorporated |
| Sartorius AG |
| Merck KGaA |
| STEMCELL Technologies |
| PromoCell GmbH |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
Captive fermentation capacity in specialized European and North American facilities anchors both supply security and pricing power for collagenase producers serving GMP-grade cell therapy manufacturers. This vertical integration into enzyme production insulates incumbent suppliers from spot-market volatility while commanding premium contract terms for validated reagent-instrument bundles.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as cell therapy manufacturers facing 12-18 month supplier qualification timelines pay substantial markups for pre-qualified GMP-grade enzymes. Pricing stratifies across clinical-grade, research-grade, and bulk industrial tiers based on endotoxin documentation depth and animal-derived component certification. Cost compression in research-grade segments intensifies as academic consortia consolidate procurement through multi-site framework agreements. Biopharmaceutical firms show lowest price sensitivity due to batch release liability exposure, while academic centers drive hardest bargain terms.
Supply Chain Analysis
Reverse logistics for temperature-sensitive liquid reagents remains underdeveloped, forcing manufacturers to absorb write-offs for cold-chain excursions rather than refurbish compromised inventory. Fermentation capacity clusters in Germany, the United States, and specialized Chinese facilities producing collagenase and trypsin variants. Raw material flows draw from porcine tissue sourcing, microbial expression systems, and recombinant DNA substrates. Single-source vulnerability concentrates in GMP-grade enzyme purification expertise. Distribution runs through authorized distributor networks with documented chain-of-custody protocols for clinical-grade shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity scarcity for GMP-grade collagenase production props pricing power across the analysis window, constraining supply elasticity even as cell therapy manufacturing scales.
For Market Incumbents: Anchor market position through backward integration into recombinant enzyme production, eliminating porcine-derived component traceability burdens that elongate FDA and EMA validation timelines. Expand captive fermentation capacity in Germany and Maryland's I-270 corridor to capture regenerative medicine startup demand. Defend against mechanical dissociation substitution by bundling automated tissue dissociators with exclusive enzyme supply contracts. For New Entrants and Emerging Players: Direct-to-CDMO digital platforms offer the most penetrable route into India's Hyderabad and Bengaluru manufacturing clusters, where standardized training services and protocol deployment tools command premium positioning. Target academic consortia in China's Zhangjiang Hi-Tech Park with lyophilized powder formulations that bypass cold-chain infrastructure gaps. White-space opportunity concentrates in microfluidic-mechanical convergence devices for point-of-care clinical diagnostics. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified life sciences conglomerates seeking enzyme supply chain control. Long-term viability hinges on GMP-grade purification expertise moats rather than commodity research-grade production. Monitor NMPA bioprocessing standard harmonization progress as inflection indicator for multinational supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| GMP-Grade Enzyme Purification Capacity Expansion | Captive production of xeno-free collagenase insulates against EMA and FDA traceability mandates. |
| Reagent-Instrument Bundle Integration | Thermo Fisher and Miltenyi Biotec models demonstrate recurring consumable revenue capture from automated workflows. |
| India CDMO Training Services Partnership | Hyderabad Genome Valley facilities require standardized dissociation protocol deployment expertise. |
| REACH SVHC-Free Formulation Certification | European cell therapy developers pre-qualify suppliers ahead of scheduled regulatory deadlines. |
| Microfluidic-Mechanical Device Development | Lab-on-chip dissociation opens clinical diagnostic applications beyond research laboratory boundaries. |
Research Methodology
Regulatory filings, trade customs databases, and GMP facility inspection records formed the secondary backbone, supplemented by primary interviews with cell therapy manufacturing executives, quality control directors at CDMOs, academic consortium procurement leads, and dissociation reagent product managers. Bottom-up and top-down triangulation validated volume estimates across enzymatic solutions, mechanical tools, and composite kit segments.
Bottom-up modeling anchored forecasts in installed base of automated tissue dissociators and reagent consumption rates per instrument, while top-down validation checked against biopharmaceutical R&D expenditure patterns and cell therapy clinical trial pipeline scaling. Segmentation dimensions included product type, application, end-user sector, and solution format. CAGRs derived from regression analysis of historical procurement volumes against precision medicine funding allocations and regulatory approval timelines for advanced therapy medicinal products.
The model holds under continued EMA and FDA harmonization on xeno-free reagent documentation; deviation in NMPA bioprocessing standard enforcement timelines or collagenase fermentation capacity expansion would shift supply elasticity assumptions. Practitioners should monitor CDMO infrastructure buildout announcements in India and Japan for early signals of regional demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
Global Biocompatibility Testing Services Market
Biomedical Technology
Needle Based Biopsy Guns Market
Biomedical Technology
Fluoro Enzymatic Assays Market
Biomedical Technology
France Flow Cytometry Market
Biomedical Technology
Macrophage Marker Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Middle East and Africa Cell Counting Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Cell Disrupters Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
Vaccine Technology Market
Biomedical Technology
Global Cell Counting Market
Biomedical Technology
Rat and Mouse Model Market
Biomedical Technology
Europe Biobanks Market