
 Europe Proteomics Market | 2026-2036
Europe Proteomics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Proteomics Market Foresight
High-resolution mass spectrometry specifications is redrawing competitive boundaries across the Europe Proteomics Market. Thermo Fisher Scientific Inc. leverages its Orbitrap technology leadership to anchor premium instrument placements in German academic clusters. Bruker Corporation differentiates through timsTOF platforms that dominate high-throughput proteogenomics workflows in Swiss and Dutch research hubs.
Proteomics encompasses the large-scale study of proteins, their structures, functions, and interactions, typically employing mass spectrometry with resolution thresholds exceeding 100,000 full width at half maximum to identify and quantify complex protein mixtures. This discipline serves pharmaceutical development, clinical biomarker validation, and systems biology research by mapping protein expression changes across disease states and therapeutic interventions. Reagents capture recurring revenue streams as consumable demand scales with instrument installed bases, while mass spectrometry instruments command the highest capital allocation among technology categories. Services are expanding fastest as pharmaceutical companies outsource complex proteogenomics analyses to specialized contract research organizations.
EMA's ICH Q5C guidelines and the EU MDR framework shape analytical validation requirements for proteomics-based clinical diagnostics, compelling manufacturers to demonstrate reproducibility and traceability across workflows. REACH and RoHS regulations constrain reagent chemistries and instrument component sourcing, pushing vendors toward greener solvent formulations and reduced hazardous material footprints. Stakeholders must monitor how the EU AI Act's risk classification rules affect automated protein identification algorithms and decision-support software deployments.
Market Dynamics
High-resolution mass spectrometry specifications are compressing vendor margins while expanding addressable application scope across pharmaceutical and clinical diagnostics verticals. The EU AI Act's risk classification framework is forcing algorithm validation investments that smaller instrument manufacturers struggle to absorb.
Growth Catalysts
- EU MDR Framework:The Medical Device Regulation mandates reproducibility standards for proteomics-based diagnostics, compelling hospital laboratories to upgrade analytical workflows and replace legacy equipment.
- Pharmaceutical Outsourcing:Contract research organizations in Germany and Switzerland are scaling proteogenomics service capacity to capture drug development pipeline expansion from Bayer, Roche, and Sanofi.
- AI-Integrated Protein Identification:Machine learning algorithms trained on spectral libraries are reducing identification false-discovery rates below 1%, accelerating biomarker validation timelines for immuno-oncology programs.
Market Restraints
- Helium Supply Concentration:Mass spectrometry instruments depend on helium for collision cells; Russian supply disruptions and U.S. export constraints have driven prices up 340% since 2022, forcing vendors toward hydrogen alternatives.
- Capital Equipment Intensity:Orbitrap and timsTOF platforms require €800,000-€2.5 million upfront investment, limiting placement velocity at mid-tier research institutes and creating installed-base concentration at elite clusters.
- REACH Chemical Restrictions:The European Chemicals Agency's authorization requirements for acetonitrile and formic acid in sample preparation are constraining reagent formulation flexibility and extending procurement lead times.
Strategic Opportunities
- Single-Cell Proteomics:Sensitivity improvements enabling 1,000-protein detection from individual cells are opening oncology microenvironment research applications previously inaccessible to bulk analysis methods.
- France's Biocluster Expansion:The Paris-Saclay and Lyon biotech corridors are receiving €4.2 billion in state funding through 2030, creating localized demand for integrated proteomics service infrastructure.
- Spatial Proteomics Convergence:Integration of mass spectrometry imaging with multiplexed immunofluorescence is enabling tissue microenvironment mapping at 10-micron resolution, displacing serial sectioning workflows in pathology departments.
Industry Challenges
- Bioinformatics Talent Scarcity:The shortage of computational biologists capable of spectral database curation and statistical validation is extending analysis turnaround times and increasing outsourcing dependency.
- Cross-Platform Standardization:Inconsistent quantification outputs between Thermo Orbitrap and Bruker timsTOF systems complicate multi-site clinical studies, forcing expensive harmonization protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Proteomics Market |
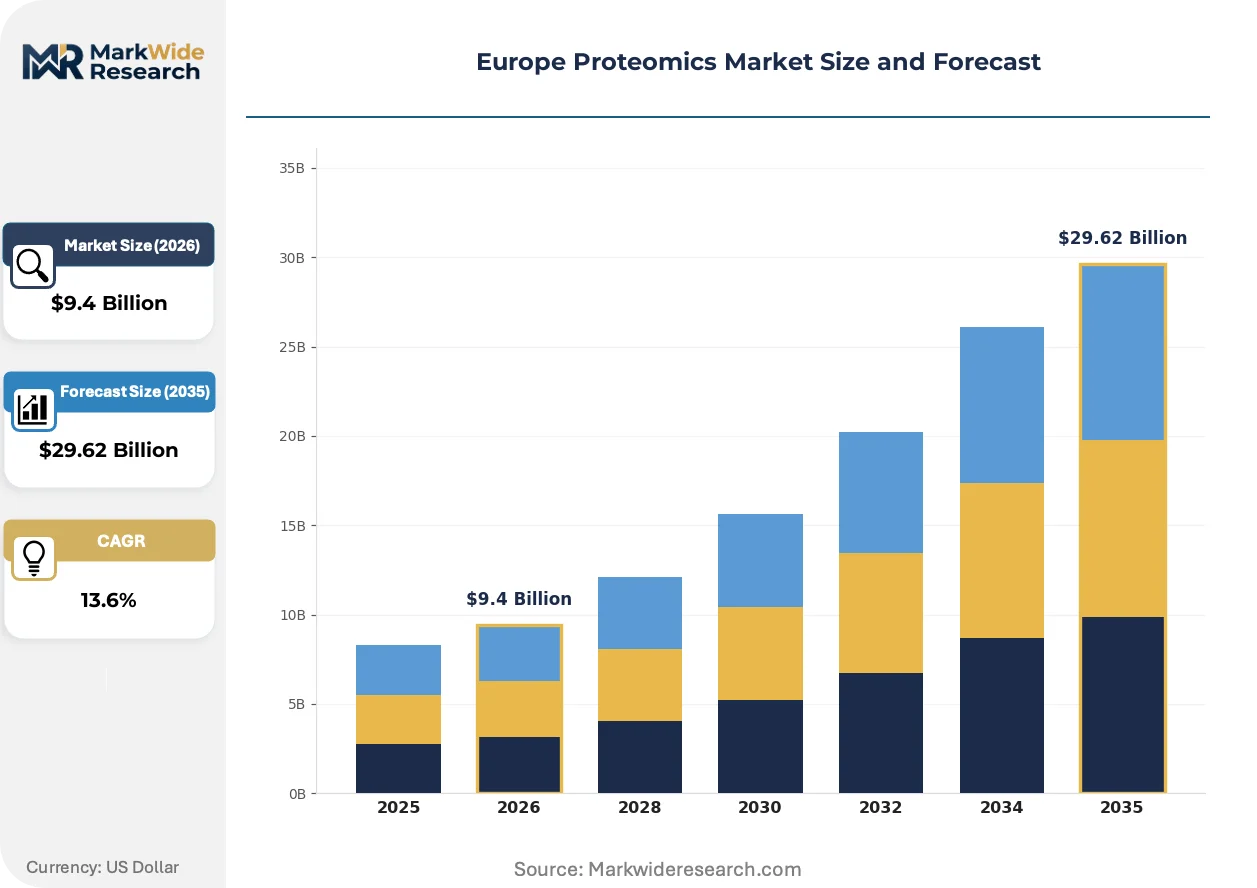
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $29.62 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Services Application: Biomarker Discovery, Drug Development, Clinical Diagnostics, Nutritional Analysis Technology: Mass Spectrometry, Chromatography, Electrophoresis, Protein Microarrays End User: Pharmaceutical Companies, Academic Institutions, Research Laboratories, Clinical Laboratories |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific Inc., Agilent Technologies Inc., Bruker Corporation, Bio-Rad Laboratories Inc., Qiagen N.V., Roche Holding AG, Danaher Corporation, Promega Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Proteomics Market Shifts & Advancements
Automation and artificial intelligence are compressing proteomics workflows from sample preparation through data interpretation, while regulatory pressure on algorithmic decision-support tools is reshaping software validation requirements. These forces are simultaneously expanding accessible application scope and raising competitive barriers to entry.
Data-independent acquisition (DIA) mass spectrometry is bifurcating the quantitative proteomics landscape. Pharmaceutical quality control laboratories are adopting DIA for batch consistency monitoring at 3-5x throughput gains over data-dependent methods. The technology is enabling comprehensive peptide library generation without fractionation, compressing method development timelines from months to weeks while displacing targeted MRM assays in regulated bioanalysis.
REACH authorization requirements for analytical solvents are forcing reagent manufacturers toward aqueous-compatible formulations. ECHA's 2024 restriction proposal on per- and polyfluoroalkyl substances threatens fluorinated stationary phases used in nano-LC separations. Chromatography vendors are responding with hybrid organic-silica alternatives, though these exhibit reduced peak capacity for hydrophobic peptide separation.
Pharmaceutical procurement departments are consolidating proteomics service contracts under multi-year master service agreements with guaranteed capacity allocation. This displaces project-by-project tendering at mid-sized biotechs and academic spinouts. The shift is most visible in Basel and Cambridge, where Novartis and AstraZeneca have centralized external proteogenomics spending through preferred provider networks with penalty clauses for capacity shortfall.
Europe Proteomics Market Segmentation
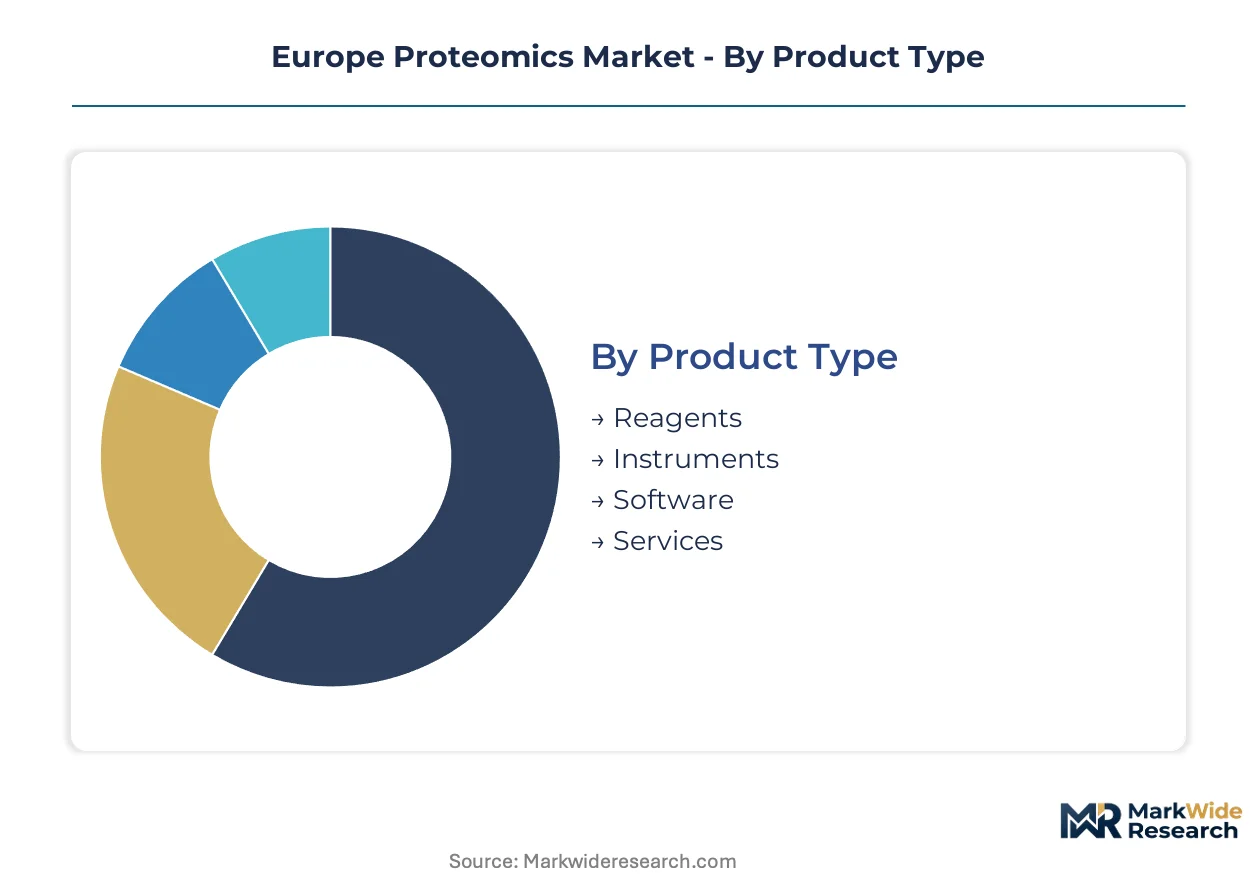
Segmentation across product, application, technology, and end-user dimensions reveals how proteomics value flows differently through German pharmaceutical corridors versus French academic clusters. Each category shows distinct geographic concentration patterns that shape vendor go-to-market priorities.
Product Type:
Domestic production concentrates instruments and software in German and Swiss manufacturing hubs, while reagents and services draw more heavily on pan-European supply networks.
- Reagents:Consumable chemistries including sample preparation kits, chromatography columns, and mass spectrometry standards generate recurring revenue streams tied to instrument installed bases. ECHA REACH authorization requirements for acetonitrile and formic acid are constraining formulation flexibility and extending procurement lead times across French and Dutch laboratories.
- Instruments:High-resolution mass spectrometry platforms with Orbitrap and timsTOF architectures command capital allocations of €800,000-€2.5 million per unit. German academic clusters in Munich, Heidelberg, and Berlin anchor the densest installed base concentration, with Swiss and Dutch research hubs following.
- Software:Algorithmic protein identification and spectral library tools face escalating validation requirements under the EU AI Act risk classification framework.
- Services:Contract research organizations scale proteogenomics capacity to capture pharmaceutical outsourcing demand from Bayer, Roche, and Sanofi.
Instruments hold the largest share; momentum sits with services.
Application:
Cost tier stratification separates capital-intensive drug development from lower-barrier nutritional analysis, with biomarker discovery occupying the middle ground.
- Biomarker Discovery:Machine learning algorithms trained on spectral libraries reduce identification false-discovery rates below 1%, accelerating validation timelines for immuno-oncology programs. Basel and Cambridge pharmaceutical procurement departments consolidate contracts under multi-year master service agreements with guaranteed capacity allocation.
- Drug Development:Proteogenomics pipelines at Bayer, Roche, and Sanofi drive demand for high-throughput quantitative workflows. Data-independent acquisition mass spectrometry displaces targeted MRM assays in regulated bioanalysis, compressing method development timelines from months to weeks.
- Clinical Diagnostics:EU MDR reproducibility standards compel hospital laboratories to upgrade analytical workflows and replace legacy equipment.
- Nutritional Analysis:Protein quantification for food safety and quality control applies lower-resolution methods with reduced capital intensity.
Drug development absorbs the highest absolute spending; biomarker discovery gains share fastest.
Technology:
Volume concentration tilts heavily toward mass spectrometry, while chromatography and electrophoresis serve specialized preparative and analytical niches.
- Mass Spectrometry:Resolution thresholds exceeding 100,000 full width at half maximum enable identification and quantification of complex protein mixtures. Helium supply disruptions from Russian sources and U.S. export constraints have driven prices up 340% since 2022, forcing vendors toward hydrogen alternatives for collision cells.
- Chromatography:Nano-LC separations face ECHA 2024 restriction proposals on per- and polyfluoroalkyl substances threatening fluorinated stationary phases. Vendors respond with hybrid organic-silica alternatives exhibiting reduced peak capacity for hydrophobic peptide separation.
- Electrophoresis:Gel-based and capillary methods persist for protein separation in resource-constrained academic settings.
- Protein Microarrays:Multiplexed affinity assays complement mass spectrometry for targeted protein panels in clinical validation workflows.
Mass spectrometry dominates installed value; spatial proteomics convergence is accelerating mass spectrometry imaging adoption.
End User:
Customer type determines procurement pattern, with pharmaceutical companies consolidating spending and academic institutions fragmenting across institutional grant cycles.
- Pharmaceutical Companies:Novartis and AstraZeneca centralize external proteogenomics spending through preferred provider networks with penalty clauses for capacity shortfall. Multi-year master service agreements displace project-by-project tendering at mid-sized biotechs.
- Academic Institutions:German academic clusters in Munich, Heidelberg, and Berlin anchor premium instrument placements, with French biocluster expansion at Paris-Saclay and Lyon receiving €4.2 billion in state funding through 2030.
- Research Laboratories:Mid-tier institutes face capital equipment intensity barriers limiting Orbitrap and timsTOF placement velocity.
- Clinical Laboratories:EU MDR framework mandates drive workflow upgrades and legacy equipment replacement across hospital systems.
Pharmaceutical companies command the largest budget share; academic institutions show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German proteomics instrument exports flow primarily into Swiss pharmaceutical manufacturing clusters and French academic research networks, establishing a north-south trade corridor that concentrates high-value analytical equipment deployment across the Rhine basin.
Germany
Bayer and Roche maintain active proteogenomics pipelines demanding high-throughput quantitative workflows. The EU MDR framework mandates reproducibility standards that compel hospital laboratories in Munich and Heidelberg to upgrade legacy equipment. The biotech corridor spanning Munich, Heidelberg, and Berlin anchors the densest concentration of Orbitrap and timsTOF installations.
Switzerland
Novartis centralizes external proteogenomics spending through preferred provider networks with penalty clauses for capacity shortfall. Swissmedic oversight shapes validation requirements for clinical diagnostic applications. The Basel pharmaceutical cluster drives demand for data-independent acquisition mass spectrometry in regulated bioanalysis.
France
Sanofi expands proteomics-driven drug development pipelines requiring specialized contract research capacity. The EU AI Act's risk classification framework forces algorithm validation investments for automated protein identification tools. Paris-Saclay and Lyon biotech corridors receive €4.2 billion in state funding through 2030, creating localized demand for integrated service infrastructure.
United Kingdom
AstraZeneca consolidates proteomics service contracts under multi-year master service agreements with guaranteed capacity allocation. MHRA alignment with EMA guidelines ensures regulatory continuity for biomarker validation workflows. The Cambridge life sciences cluster concentrates pharmaceutical procurement decision-making and external spending centralization.
Netherlands
Academic research hubs adopt high-throughput proteogenomics workflows for systems biology applications. ECHA REACH authorization requirements constrain acetonitrile and formic acid procurement for sample preparation protocols. Dutch research institutes in Leiden and Utrecht serve as early adopters for timsTOF platforms in multi-site clinical studies.
Europe Proteomics Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and service provision dimensions. The vendor base stratifies between diversified conglomerates with full-stack proteomics portfolios and focused instrument specialists dominating specific resolution or throughput categories. Three archetypes prevail: mass spectrometry platform originators, reagent and consumable suppliers, and contract research service providers. Consolidation through strategic acquisitions and geographic expansion into French biocluster zones represent the dominant competitive moves.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation occupy positions spanning instruments, reagents, and services. Bruker Corporation exemplifies the specialized instrument archetype with focused mass spectrometry platform development. Merck KGaA represents the integrated reagent and chemical supplier position, leveraging formulation expertise across sample preparation workflows.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| Bruker Corporation |
| Bio-Rad Laboratories Inc. |
| Qiagen N.V. |
| Roche Holding AG |
| Danaher Corporation |
| Promega Corporation |
| Others |
Supply & Pricing Matrix
Ninety-day lead times for helium-3 isotopes and nano-LC column resins concentrate procurement power with German distributors serving Munich and Heidelberg instrument clusters, compressing margin flexibility for mid-tier reagent suppliers while amplifying pricing leverage at integrated conglomerates with captive solvent formulation capabilities.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Europe Proteomics Market. Price differentiation rests on CE-IVD certification tier and instrument resolution specification, with Orbitrap platforms commanding substantial premiums over entry-level quadrupole systems. Pricing pressure stems from REACH authorization delays extending reagent procurement cycles and forcing inventory carrying cost absorption. Mid-sized contract research organizations exhibit highest price sensitivity, while Big Pharma procurement functions prioritize guaranteed capacity allocation over per-sample economics.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg has elevated inbound logistics costs for chromatography consumables sourced from East Asian manufacturing hubs, compressing working capital cycles for Dutch and German distributors. Supply concentrates in Germany, Switzerland, and the United States for mass spectrometry platforms, while China and India anchor lower-value reagent component production. Raw material dependencies span helium isotopes for collision cells, fluorinated stationary phases for nano-LC separations, and high-purity acetonitrile for sample preparation. Single-source vulnerability in helium supply from Russian and Algerian sources creates structural risk exposure. Distribution runs through authorized dealer networks serving academic clusters and direct enterprise accounts for pharmaceutical procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across service provider tiers creates white-space opportunities as pharmaceutical outsourcing demand outpaces specialized proteogenomics capacity in French bioclusters and Swiss manufacturing corridors.
For Market Incumbents: Shield installed base retention by embedding predictive maintenance contracts with Heidelberg and Berlin academic clusters, countering Bruker's timsTOF displacement threat. Deepen backward integration into green solvent formulations ahead of ECHA's per- and polyfluoroalkyl substance restrictions, securing formulation flexibility that REACH-constrained competitors cannot replicate. For New Entrants and Emerging Players: CE-IVD certification fast-tracks for AI-integrated protein identification algorithms open service provision niches in Paris-Saclay and Lyon bioclusters receiving state funding. Spatial proteomics convergence applications in oncology microenvironment research represent the most penetrable segment, with 10-micron resolution workflows displacing serial sectioning in pathology departments. Target go-to-market through preferred provider networks with penalty-clause structures mirroring Novartis and AstraZeneca procurement templates. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core proteomics software units amid EU AI Act compliance cost escalation. Five-to-ten-year viability hinges on algorithm validation infrastructure and spectral library depth rather than hardware manufacturing scale. Watch EMA biomarker qualification pathway acceleration as inflection signal for clinical diagnostics revenue mix expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Algorithm Validation Investment | Automated protein identification tools face escalating compliance costs that reshape competitive barriers. |
| REACH-Compliant Solvent Formulation Transition | Aqueous-compatible reagent development secures procurement continuity under ECHA restriction proposals. |
| Multi-Year Master Service Agreement Expansion | Guaranteed capacity allocation contracts displace project tendering in Basel and Cambridge pharmaceutical corridors. |
| Single-Cell Proteomics Sensitivity Enhancement | 1,000-protein detection from individual cells opens oncology microenvironment research applications. |
| Spatial Proteomics Imaging Integration | Mass spectrometry imaging with multiplexed immunofluorescence displaces serial sectioning in pathology workflows. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EMA submission databases, EU MDR technical documentation, and REACH authorization registers. Interviews with proteomics platform engineers, hospital laboratory directors, pharmaceutical procurement leads, and contract research organization operations heads inform demand-side validation. Secondary sources include Swissmedic guidance documents, ECHA restriction proposals, and instrument manufacturer SEC filings. Bottom-up instrument placement tracking and top-down pharmaceutical R&D spending analysis triangulate market sizing.
Segmentation dimensions modeled span product type, application, technology, and end-user categories, with additional granularity by resolution specification tier and regulatory approval pathway across the projection horizon. CAGRs derive from instrument replacement cycle analysis, services outsourcing elasticity, and reagent consumption intensity per installed unit. Forecast inputs incorporate helium supply disruption scenarios and ECHA authorization timeline probability distributions.
Decision-makers should treat outputs as directional under base assumptions of sustained EU MDR enforcement and REACH authorization progression; material deviation in regulatory timeline acceleration or helium supply normalization would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Bead-Based Flow Cytometry Market
Biomedical Technology
Austria Flow Cytometry Market
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Global Protein Crystallization and Crystallography Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Glycomics Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
Bone Marrow Aspirate Concentrates (BMAC) Market
Biomedical Technology
Human Biobanking Ownership Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
Drug Delivery Technology Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Antibody Library Technology Market