
 Cell and Tissue Culture Supplies Market | 2026-2036
Cell and Tissue Culture Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Cell and Tissue Culture Supplies Market Analysis
Biopharmaceutical manufacturers are rotating demand away from academic buyers toward commercial-scale bioproduction clients. Thermo Fisher Scientific leverages its vertically integrated portfolio spanning media, sera, and bioprocess equipment to capture this shift. Lonza Group AG anchors its position through specialized cell-line engineering services tied to supply contracts. Sartorius AG differentiates via membrane-based perfusion technologies that reduce media consumption in fed-batch processes.
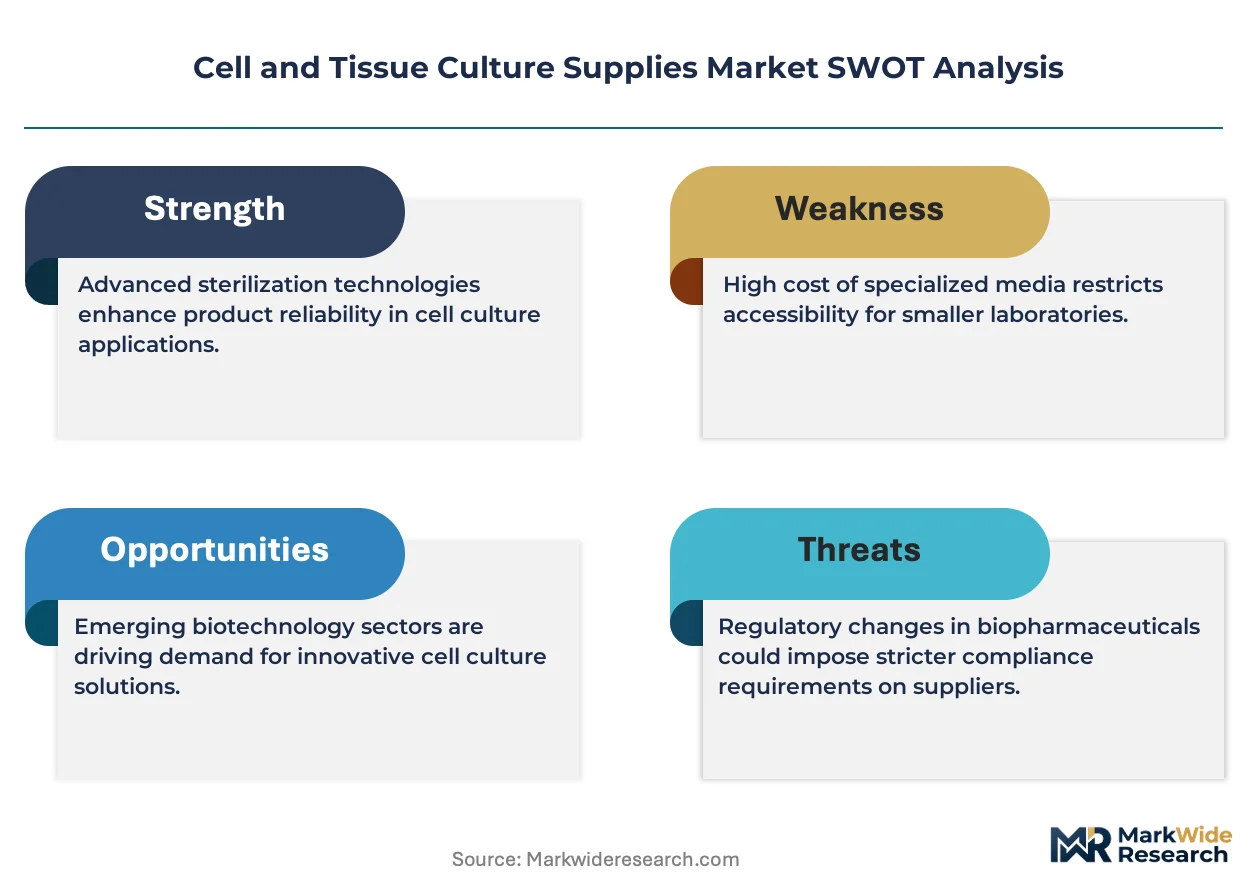
Cell and tissue culture supplies encompass sterile nutrient media, sera, reagents, and specialized plasticware engineered for adherent and suspension cell propagation under controlled temperature, pH, and gas-exchange conditions. These products enable reproducible expansion of mammalian, insect, and microbial cells for therapeutic protein production, vaccine manufacturing, and regenerative medicine research. Media formulations command the largest revenue share due to recurring purchase cycles and proprietary serum-free chemistry, while 3D culture technologies represent the fastest-expanding segment as organoid models displace planar cultures in immuno-oncology screening. Plasticware margins concentrate in surface-treated vessels where Corning Inc. and Eppendorf AG hold established positions.
FDA guidelines on adventitious agent testing and EMA's Annex 1 revision on sterile manufacturing reshape raw-material qualification requirements for media and sera suppliers. China's NMPA has aligned its biologics master file system with ICH Q5D standards, accelerating local media validation timelines. Stakeholders must monitor how dual-use export controls on cell lines and CRISPR reagents redirect procurement strategies across North American, European, and Chinese biomanufacturing networks.
Market Dynamics
Serum-free media chemistry is compressing raw-material qualification timelines while simultaneously elevating technical barriers for new entrants, forcing suppliers to restructure R&D spending toward proprietary formulation science.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revision:Mandates for closed-system bioprocessing accelerate demand for single-use plasticware and pre-sterilized media formulations.
- Organoid-based immuno-oncology screening:Pharmaceutical toxicology departments are replacing planar cultures with 3D tumor models, expanding addressable plasticware surface area per experiment.
- CDMO clustering near Boston, Basel, and Suzhou:Geographic concentration of contract manufacturing creates predictable demand spikes for regional media distribution centers.
Market Restraints
- Bovine serum supply volatility:Foot-and-mouth disease outbreaks in South American grazing regions periodically constrain fetal bovine serum availability and pricing stability.
- Chinese domestic media self-sufficiency mandates:NMPA localization requirements for biologics master files reduce import dependency for multinational suppliers.
- Perfusion culture technical complexity:Membrane-based cell retention systems require specialized operator training that limits adoption outside top-tier biomanufacturing facilities.
Strategic Opportunities
- India's biologics PLI scheme:Production-linked incentives for biosimilar manufacturing create greenfield demand for serum-free media validation services.
- AI-guided media optimization:Machine learning platforms that predict nutrient depletion kinetics are converging with automated bioreactor control systems.
- Direct-to-laboratory e-procurement:Specialized distributors bypass traditional catalog houses to serve principal investigator labs with just-in-time reagent replenishment.
Industry Challenges
- Cell-line authentication expertise gap:Shortage of qualified biosafety officers capable of STR profiling and mycoplasma detection slows facility qualification timelines.
- Multi-supplier raw material traceability:Reconciling batch records across chemically defined media components from disparate vendors complicates audit readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell and Tissue Culture Supplies Market |
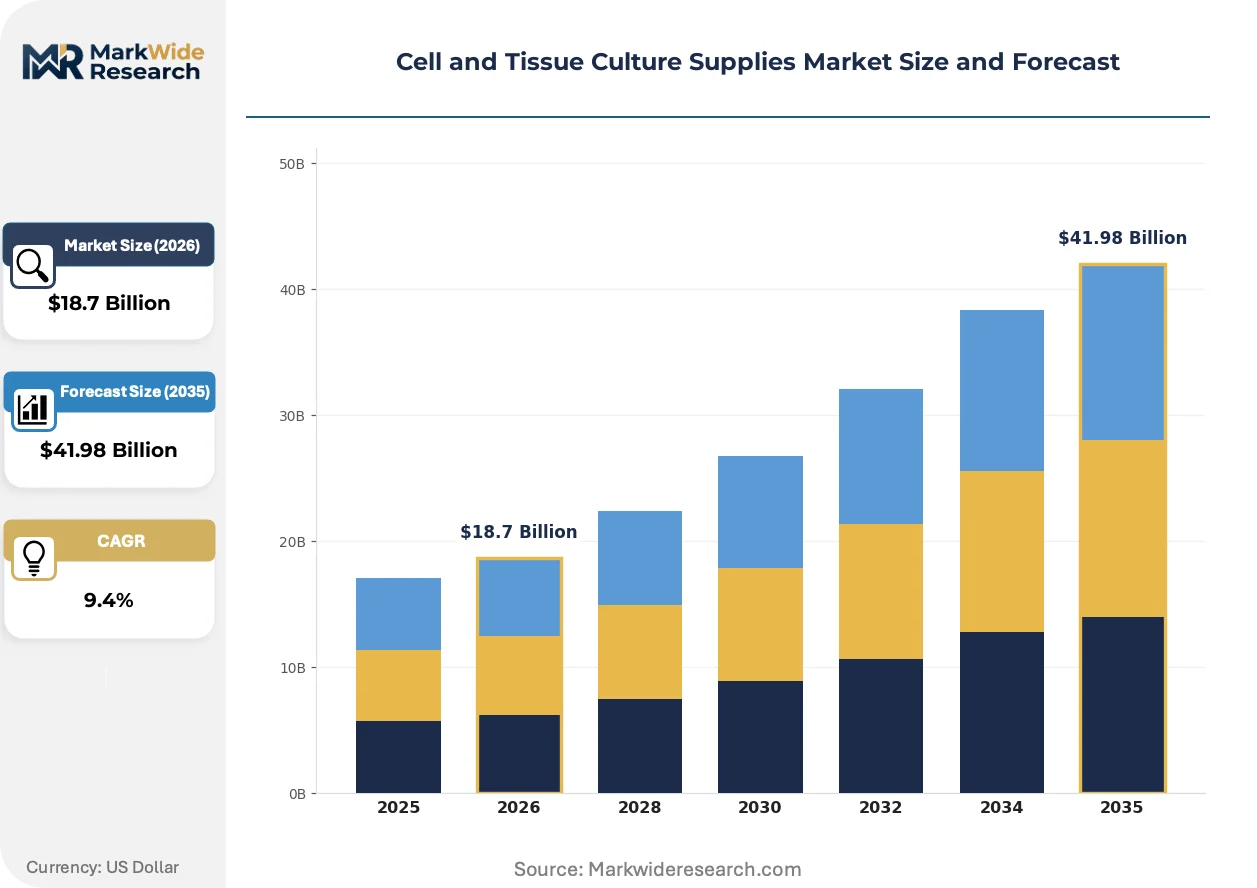
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Media, Serum, Reagents, Plasticware Application: Research, Drug Development, Clinical Applications, Bioproduction End User: Pharmaceuticals, Biotechnology Firms, Academic Institutions, Clinical Labs Technology: Cryopreservation, 3D Culture, Stem Cell Technology, Bioreactors |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Corning Inc., Lonza Group AG, Becton, Dickinson and Company, Sartorius AG, GE Healthcare, Eppendorf AG, Danaher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell and Tissue Culture Supplies Market Emerging Trajectories
Automation and chemically defined chemistry are compressing manual intervention points while expanding reproducibility standards across upstream bioprocessing workflows.
Microcarrier bead technology is decomposing the distinction between adherent and suspension culture platforms. Vaccine manufacturers are adopting dissolvable microcarriers for Vero cell propagation at commercial scale. This convergence is collapsing the traditional plasticware segmentation between roller bottles and stirred-tank bioreactors.
FDA guidance on continuous manufacturing introduces real-time release testing expectations for media lot consistency. Bioproduction facilities must install in-line metabolite monitoring to satisfy parametric release protocols. Small-molecule CDMOs entering biologics manufacturing face steepest compliance adaptation costs.
Consolidated procurement through group purchasing organizations concentrates contract negotiation leverage among top-twenty research universities. Independent principal investigators are migrating to subscription-based reagent replenishment models. This behavioral shift is most pronounced in German Max Planck Institutes and US NIH-funded core facilities.
Cell and Tissue Culture Supplies Market Segmentation
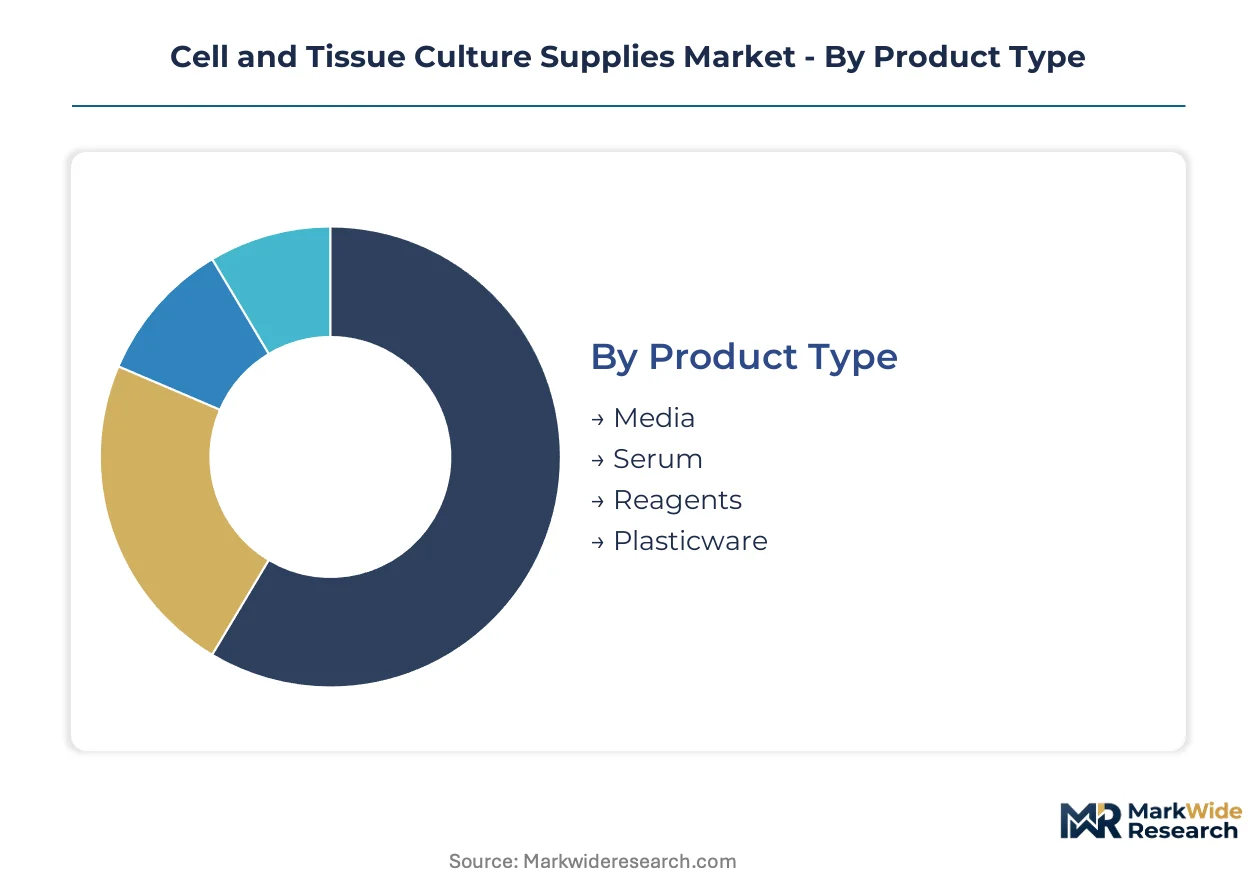
Segmentation in cell and tissue culture supplies reveals how margin pools shift between commodity reagents and specialized technologies. Procurement patterns diverge sharply between academic volume buyers and biopharmaceutical quality-sensitive accounts.
Product Type:
Margin concentration follows formulation complexity, with chemically defined media commanding premium pricing over commodity sera.
- Media:Serum-free and chemically defined formulations dominate revenue through recurring purchase cycles tied to bioproduction campaigns. Biopharmaceutical manufacturers in Germany and the United States drive demand for proprietary formulations that compress raw-material qualification timelines under FDA and EMA guidelines.
- Serum:Fetal bovine serum retains volume significance despite regulatory pressure, though pricing volatility from South American supply constraints erodes margin stability. Foot-and-mouth disease outbreaks periodically disrupt availability, accelerating migration toward serum-free alternatives.
- Reagents:Growth factors and attachment matrices support specialized applications.
- Plasticware:Surface-treated vessels for adherent culture capture margin in cell therapy manufacturing.
The dominant share belongs to Media, while Reagents is closing the gap fastest through growth factor innovation.
Application:
Commercial bioproduction applications carry margin premiums over research-scale consumption through validation and documentation requirements.
- Bioproduction:Therapeutic protein and vaccine manufacturing demands GMP-grade materials with full batch traceability. CDMO clustering near Boston, Basel, and Suzhou creates predictable demand spikes for regional distribution centers serving commercial campaigns.
- Drug Development:Toxicology and pharmacokinetic studies require qualified reagent lots that satisfy regulatory submission standards. Organoid-based immuno-oncology screening is displacing planar cultures, expanding addressable plasticware surface area per experiment.
- Research:Academic laboratories prioritize cost efficiency over documentation depth.
- Clinical Applications:Cell therapy manufacturing imposes patient-specific material tracking requirements.
Bioproduction captures the largest margin pool, with Drug Development expanding most quickly through 3D model adoption.
End User:
Procurement sophistication varies dramatically between multinational biopharmaceuticals and distributed academic accounts.
- Pharmaceuticals:Integrated bioproduction divisions negotiate multi-year supply agreements with formulation customization clauses. In-house cell line development programs are expanding, rotating demand away from academic buyers toward commercial-scale clients.
- Biotechnology Firms:Venture-funded startups favor flexible procurement terms and rapid media validation services. These organizations cluster near regulatory agencies and research universities to accelerate IND timelines.
- Academic Institutions:Consolidated procurement through group purchasing organizations concentrates negotiation leverage among top-twenty research universities.
- Clinical Labs:Diagnostic applications require ISO-compliant material handling protocols.
Pharmaceuticals retain the dominant procurement volume, though Biotechnology Firms are gaining share fastest through venture-backed expansion.
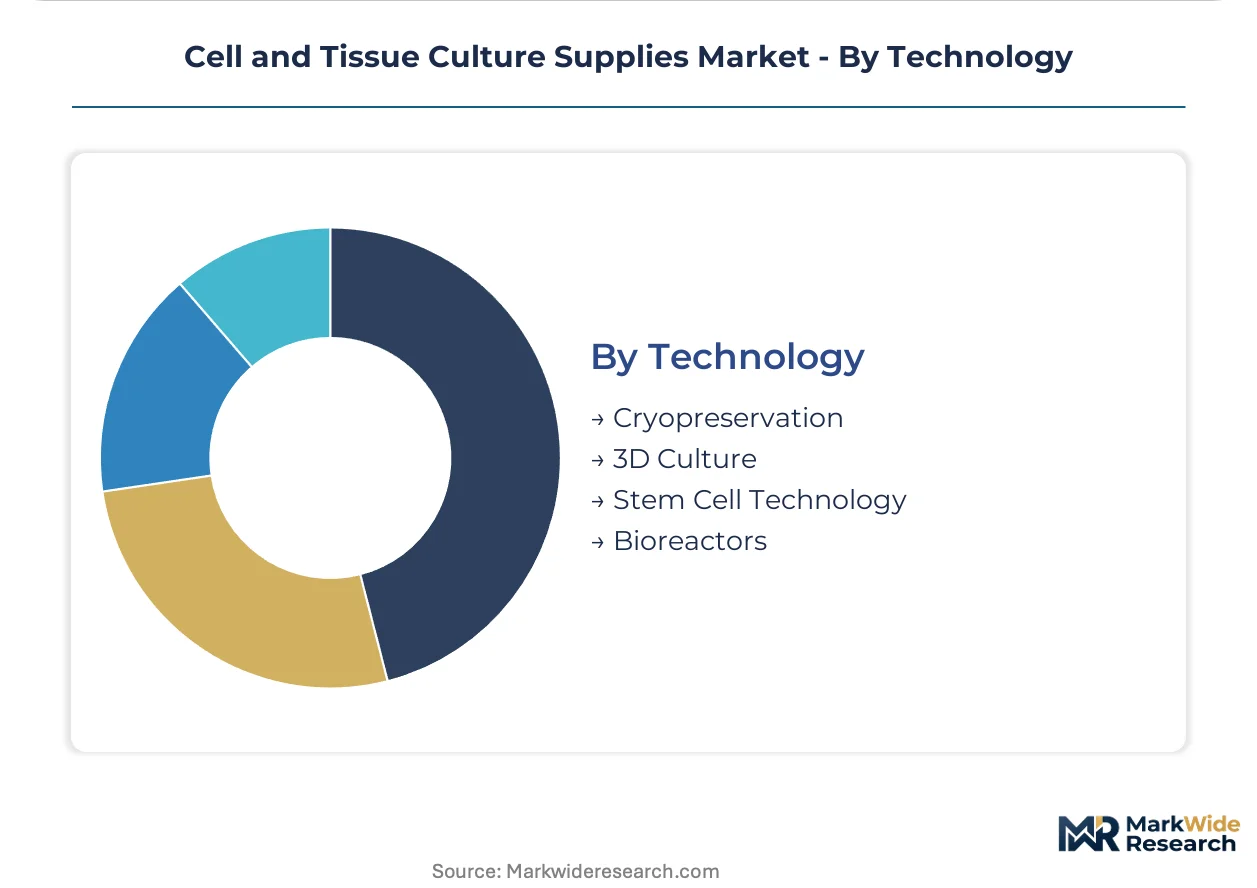
Technology:
Technology segmentation tracks automation intensity and dimensional complexity in cell propagation systems.
- 3D Culture:Organoid and spheroid models enable physiologically relevant screening platforms that displace traditional planar cultures. Pharmaceutical toxicology departments are adopting these systems for immuno-oncology applications, driving demand for specialized matrices and perfusion-compatible vessels.
- Bioreactors:Single-use stirred-tank and perfusion systems support commercial-scale manufacturing under closed-system mandates from EMA Annex 1 revisions. Membrane-based cell retention technologies reduce media consumption but require specialized operator training.
- Cryopreservation:Cell banking and transport applications demand controlled-rate freezing protocols.
- Stem Cell Technology:Pluripotent and adult stem cell propagation requires feeder-free culture surfaces.
3D Culture leads technology investment, while Bioreactors show the steepest expansion trajectory through continuous manufacturing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites European biologics distribution, while Singapore's Changi Pharma Zone anchors Asia-Pacific supply consolidation. These physical assets determine where media manufacturers locate regional distribution centers.
United States
FDA's updated guidance on continuous manufacturing drives demand for real-time release testing capabilities. The Greater Boston cluster concentrates CDMO activity near MIT and Harvard Medical School facilities. Thermo Fisher Scientific maintains vertically integrated production across Massachusetts and North Carolina to serve commercial bioproduction campaigns.
Germany
EMA Annex 1 sterile manufacturing revisions accelerate closed-system bioprocessing adoption. The Rhine-Main region around Frankfurt hosts specialized media formulation facilities serving Basel-based pharmaceutical headquarters. Sartorius AG anchors its membrane-based perfusion technology development in Göttingen.
China
NMPA's biologics master file alignment with ICH Q5D standards compresses local media validation timelines. The Suzhou Industrial Park clusters contract manufacturing organizations near Shanghai's regulatory expertise. Domestic serum-free media self-sufficiency mandates redirect procurement toward local suppliers.
India
CDSCO's production-linked incentive scheme for biosimilars generates greenfield demand for media validation services. The Genome Valley cluster in Telangana attracts venture-funded biotech startups seeking rapid IND timelines. Hyderabad's vaccine manufacturers expand Vero cell propagation capacity for export markets.
Switzerland
Swissmedic's alignment with EMA standards enables seamless cross-border qualification for Basel-headquartered multinationals. The Basel-Land canton concentrates Lonza Group AG's cell-line engineering services. Roche and Novartis procurement teams negotiate multi-year supply agreements with formulation customization clauses.
Cell and Tissue Culture Supplies Market Vendor Landscape
Listed leaders compete with private specialists across formulation science and bioprocess equipment integration. The market structures around three tiers: diversified life-science conglomerates, specialized media and reagent houses, and niche plasticware fabricators. Strategic differentiation converges on proprietary serum-free chemistry and automated bioreactor control systems. Consolidation activity concentrates in media formulation assets, while capacity expansion targets perfusion-compatible manufacturing lines.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Danaher occupy positions spanning media, sera, and analytical instrumentation. Merck KGaA exemplifies the European-centered specialty chemicals archetype with backward integration into raw material supply. These three entities anchor competitive dynamics through captive distribution networks and multi-year pharmaceutical supply contracts.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Corning Inc. |
| Lonza Group AG |
| Becton, Dickinson and Company |
| Sartorius AG |
| GE Healthcare |
| Eppendorf AG |
| Danaher |
| Others |
Supply Flow & Price Mechanics
FDA's adventitious agent testing requirements and EMA's Annex 1 sterile manufacturing revisions gate both supplier qualification timelines and price differentiation across serum-free media tiers. These regulatory frameworks compress raw-material approval cycles for premium formulations while elevating technical barriers that protect incumbent pricing power against commodity entrants.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations between multinational biopharmaceuticals and media suppliers, with three-tier pricing separating GMP-validated custom formulations from catalog chemically defined media and economy-grade research-use products. Price differentiation rests on certification grade and batch documentation depth, with FDA master file-backed products commanding substantial premiums over ISO-compliant alternatives. Cost compression in research-grade tiers is intensifying because academic procurement consolidation through group purchasing organizations concentrates leverage among top-twenty universities. Biotechnology firms exhibit highest price sensitivity due to venture-funded budget constraints, while integrated pharmaceutical manufacturing divisions prioritize supply security over unit cost.
Supply Chain Analysis
Just-in-time replenishment models predominate among principal investigator laboratories and CDMOs operating campaign-based manufacturing, though strategic stockpiling persists for fetal bovine serum given South American supply volatility. Raw material sourcing draws from United States specialty chemical manufacturers, German precision equipment fabricators, and Chinese domestic media producers responding to NMPA localization mandates. Single-source vulnerability concentrates in proprietary serum-free formulation components where patent-protected chemistries limit qualified alternative suppliers. Distribution runs through specialized life-science distributors with cold-chain capabilities, bypassing traditional catalog houses for direct-to-laboratory e-procurement in academic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified biosafety officers capable of STR profiling and mycoplasma detection remain scarce relative to facility qualification demand, creating persistent bottlenecks that favor incumbents with established technical service teams.
For Market Incumbents: Consolidate formulation science capabilities through targeted acquisition of regional media specialists possessing validated master files in growth markets. Defend margin position by expanding in-house cell line engineering services that lock in multi-year supply contracts, while accelerating perfusion-compatible manufacturing capacity to capture EMA Annex 1-driven demand for closed-system bioprocessing. For New Entrants and Emerging Players: Rapid media validation services for venture-funded biotechnology clusters represent the most penetrable service-layer gap, as incumbents prioritize pharmaceutical-scale accounts. Target India's Genome Valley and Telangana biosimilar manufacturers through production-linked incentive-aligned partnerships, leveraging direct-to-laboratory e-procurement platforms to bypass established distributor relationships. For Investors and Strategic Acquirers: NMPA's biologics master file alignment with ICH Q5D standards reshapes the acquisition landscape toward Chinese domestic media assets with validated local supply chains. Long-term viability favors targets with proprietary chemically defined chemistry and automated bioreactor control integration. Watch FDA guidance on continuous manufacturing adoption rates as the primary inflection signal for real-time release testing infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Serum-Free Media Validation Services | Compresses raw-material qualification timelines for CDMOs under FDA and EMA guidelines. |
| Perfusion-Compatible Manufacturing Capacity | Captures EMA Annex 1 demand for closed-system bioprocessing in Basel and Boston clusters. |
| AI-Guided Media Optimization Platforms | Converges machine learning with automated bioreactor control at Thermo Fisher and Sartorius. |
| Direct-to-Laboratory E-Procurement | Bypasses traditional catalog houses for just-in-time reagent replenishment in Max Planck Institutes. |
| Regional Distribution Center Expansion | Positions inventory near Suzhou and Genome Valley CDMO clusters to reduce campaign lead times. |
Methodological Framework
A standing panel of bioproduction executives, regulatory affairs leads at CDMOs, media formulation scientists, and academic core facility directors provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA biologics master file submissions, EMA Annex 1 revision commentaries, NMPA ICH Q5D alignment notices, and CDSCO production-linked incentive scheme documentation. Bottom-up segment sizing triangulated against top-down industry expenditure estimates from trade associations and customs records.
Consistency checks validated volume and value outputs against external benchmarks including biopharmaceutical capital expenditure disclosures and CDMO capacity expansion announcements. The analytical framework modeled product type, application, end user, and technology dimensions across the projection horizon. CAGRs were derived from segment-level growth trajectory analysis incorporating bioproduction campaign frequency, regulatory validation timeline compression, and 3D culture adoption rates in immuno-oncology screening.
Underlying assumptions cover sustained biopharmaceutical outsourcing trends and stable regulatory alignment timelines, with deviation risk concentrated in bovine serum supply disruptions and Chinese domestic self-sufficiency mandate acceleration. Revision becomes warranted when NMPA localization requirements or EMA Annex 1 enforcement intensity crosses thresholds that materially alter regional procurement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Cell Proliferation Kit Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Biotherapeutics Virus Removal Filters Market
Biotechnology Equipment
Global Bioprocess Analyzers Market
Biotechnology Equipment
Qpcr Instruments Market
Biotechnology Equipment
Upstream Bioprocessing Equipment Market
Biotechnology Equipment
Separation Systems for Commercial Biotechnology Market
Biotechnology Equipment
Global Life Sciences Tools Market
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
Latin America Protein Purification and Isolation Market
Biotechnology Equipment
Global Biotechnology Reagents Market
Biotechnology Equipment
Global Photobiostimulation Devices Market
Biotechnology Equipment
Cryogenic Vial Rack Market
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Automated Cell Culture Equipment Market