
 Global Transfection Market | 2026-2036
Global Transfection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transfection Market Foresight
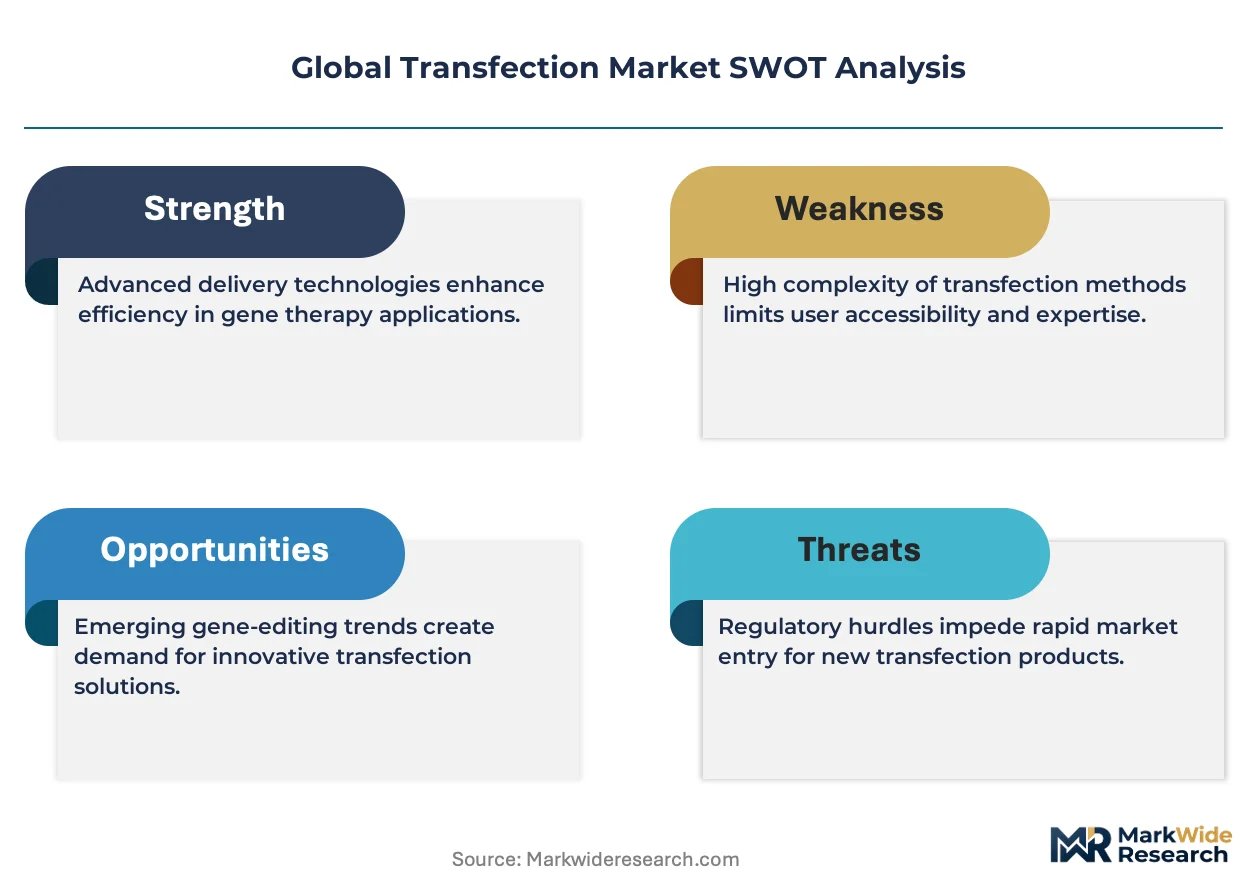
Project finance for cell therapy manufacturing facilities is fragmenting competitive access across the transfection value chain. Thermo Fisher Scientific leverages its channel density to sustain reagent supply agreements with emerging biotechs. Lonza Group anchors large-scale plasmid production capacity for viral vector programs. QIAGEN competes through nucleic acid purification integration that locks in downstream transfection workflows.
Transfection denotes the deliberate introduction of nucleic acids into eukaryotic cells using chemical, physical, or viral carrier systems, with lipid-based formulations typically achieving 80-90% efficiency in immortalized lines for protein expression and gene editing workflows. Reagent and kit segments dominate current revenue as repeat-consumable models capture ongoing academic and industrial demand, while electroporation instrumentation occupies the fastest-expanding margin pool due to precision requirements in cell therapy manufacturing. Viral vector technology leads gene therapy applications despite biosafety handling costs, and polymer-based alternatives capture price-sensitive screening workflows.
The FDA governs nucleic acid therapy approval pathways and plasmid master file requirements, while the EMA enforces genetically modified organism containment standards that shape European facility investment. Japan's PMDA and China's NMPA are tightening comparability criteria for ex vivo electroporation devices used in CAR-T production. Stakeholders must monitor how regulator convergence on viral vector release specifications reshapes supplier qualification burdens and capital deployment priorities.
Market Dynamics
Cell therapy manufacturing scale-up is compressing transfection technology procurement cycles as CDMOs race to secure GMP-compliant electroporation capacity ahead of IND filings. This demand surge is restructuring supplier qualification hierarchies and locking in multi-year reagent supply commitments.
Growth Catalysts
- FDA accelerated approval pathways:Nucleic acid therapeutic designations compress clinical timelines and expand plasmid production capacity investments across contract manufacturing networks.
- Lipid nanoparticle platform maturation:Pharmaceutical companies are deploying mRNA delivery infrastructure originally validated for COVID-19 vaccines into oncology and rare disease pipelines.
- Boston-San Francisco biotech clusters:Concentrated venture deployment in these metropolitan areas sustains premium reagent consumption and early-stage electroporation instrumentation adoption.
Market Restraints
- Plasmid DNA supply concentration:Limited GMP-certified fermentation capacity in North America and Europe creates bottleneck risks for viral vector programs.
- Biosafety Level 3 handling costs:Lentiviral and retroviral vector production requires containment infrastructure that inflates per-batch manufacturing economics.
- Electroporation device comparability:PMDA and NMPA tightening of ex vivo CAR-T device validation standards extends regulatory timelines for new platform entrants.
Strategic Opportunities
- India CDMO expansion:Contract research organizations in Hyderabad and Bengaluru are building plasmid production capabilities to capture cost-sensitive viral vector outsourcing.
- Polymer-based screening workflows:Price-sensitive discovery operations in academic core facilities represent convertible demand from lipid reagent alternatives.
- EMA genetically modified organism containment harmonization:Streamlined cross-border facility approval processes reduce capital duplication for multi-site European manufacturers.
Industry Challenges
- GMP electroporation specialist scarcity:Cell therapy manufacturing requires operators trained in both aseptic processing and electrical parameter optimization, creating recruitment bottlenecks.
- Master file synchronization:Viral vector release specifications diverge between FDA and EMA guidelines, forcing dual qualification pathways for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transfection Market |
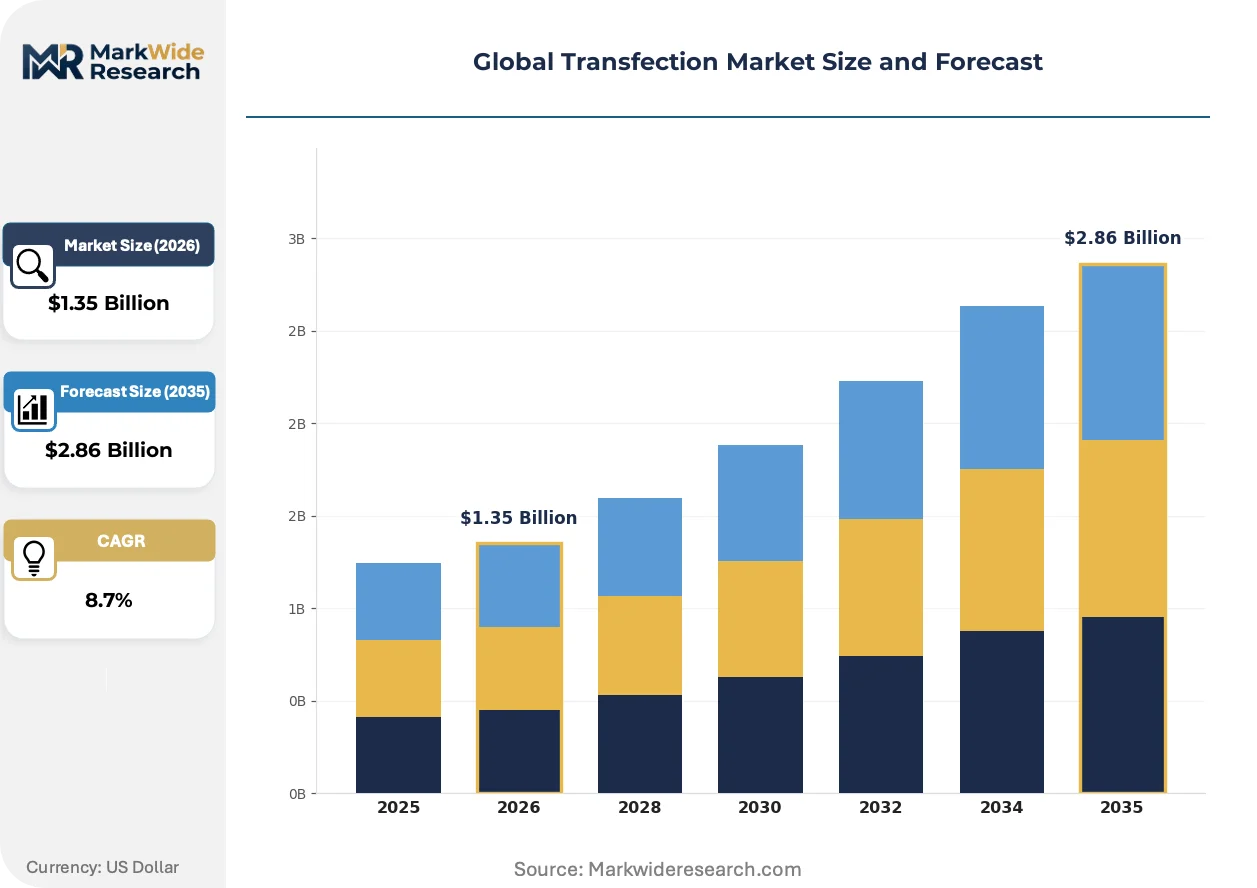
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.86 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Vectors, Instruments Technology: Lipid-Based, Electroporation, Calcium Phosphate, Viral Vector, Polymer-Based, Microinjection Application: Gene Function Studies, Protein Production, Cell Line Development, Gene Therapy, Drug Screening End User: Academic Research, Biotechnology Firms, Pharmaceutical Companies, Contract Research Organizations |
| Companies Covered | Merck KGaA, Promega Corporation, Thermo Fisher Scientific, Sartorius AG, MaxCyte, QIAGEN, Bio-Rad Laboratories, Takara Bio, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transfection Market Shifts & Advancements
Digital integration of transfection parameter databases with manufacturing execution systems is reshaping how cell therapy producers validate batch consistency and trace electroporation outcomes across multi-site networks.
High-throughput electroporation instrumentation is digitizing process development workflows by capturing real-time voltage-current curves and integrating them into predictive cell viability models. CDMOs serving CAR-T developers are deploying these platforms to compress protocol optimization from weeks to days. The resulting data architectures are digitizing regulatory submission packages and reducing CMC section preparation burden.
EMA's evolving genetically modified organism containment standards are forcing facility redesigns that segregate viral vector production from plasmid fermentation suites. European manufacturers are responding by consolidating these operations into single-campus configurations with dedicated HVAC zones. This regulatory compression is accelerating capital deployment into purpose-built gene therapy manufacturing sites in Switzerland and the Netherlands.
Academic core facilities are unbundling reagent procurement from instrumentation service contracts, shifting toward à-la-carte consumable purchasing through distributor marketplaces. This channel fragmentation is most visible in United States research institutions where centralized purchasing offices now negotiate spot pricing for lipid transfection kits independent of capital equipment leases. The disintermediation is compressing supplier margins while expanding price transparency across product tiers.
Global Transfection Market Segmentation
Transfection technology selection hinges on payload size, cell type sensitivity, and regulatory compliance requirements. Each segmentation dimension reveals distinct procurement patterns between discovery-phase flexibility and manufacturing-phase standardization.
Product Type:
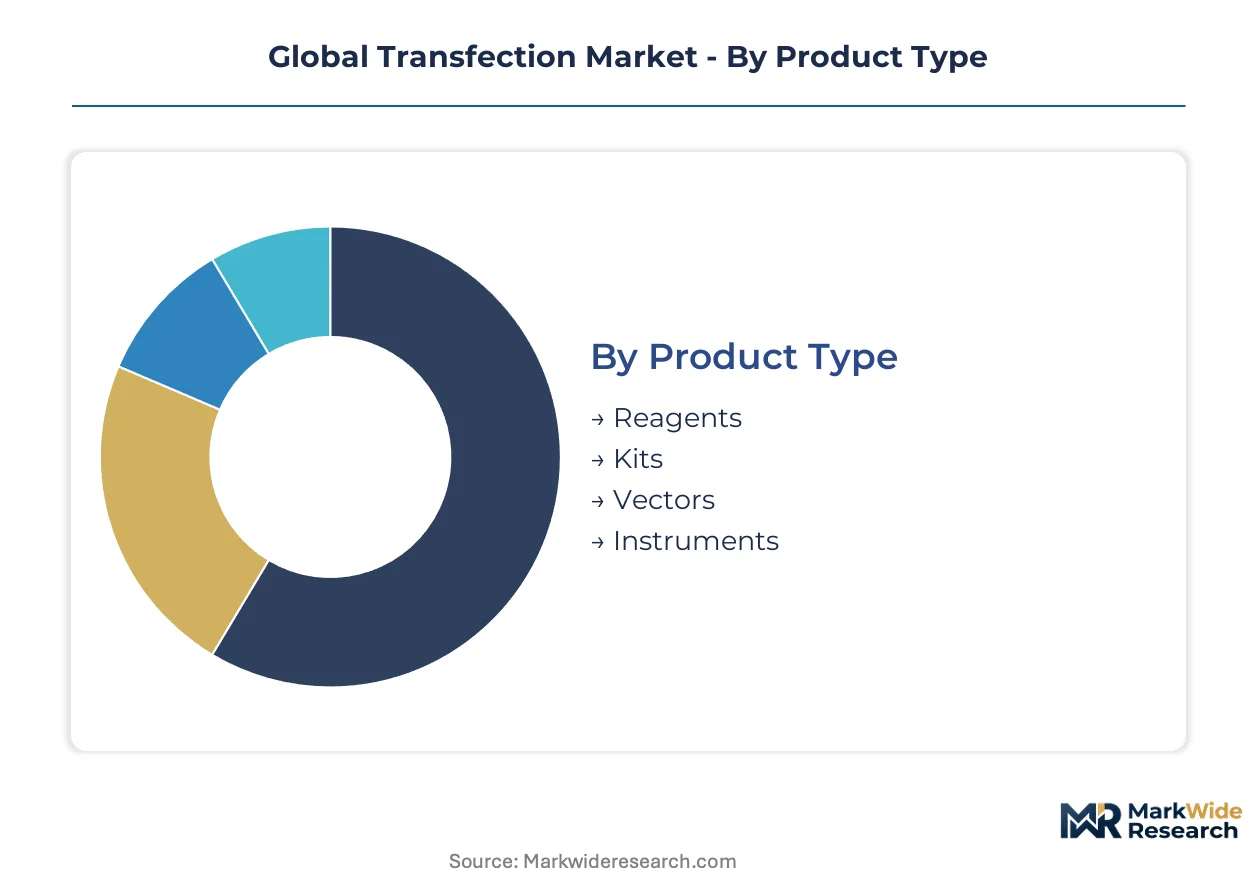
Reagent and kit formulations dominate repeat-purchase workflows across the use-case spectrum from academic screening to GMP manufacturing.
- Reagents:Lipid and polymer formulations enable rapid protocol optimization with minimal capital investment. Demand concentrates in Boston and San Francisco biotech clusters where early-stage programs prioritize speed over scalability.
- Kits:Pre-validated reagent combinations with standardized protocols reduce technical variability in multi-site studies. Pharmaceutical companies in Switzerland and the Netherlands are locking in multi-year kit supply agreements to secure batch consistency for regulatory submissions.
- Vectors:Plasmid DNA and viral packaging systems serve as the genetic payload foundation for gene therapy applications. Supply concentrates in North American and European GMP fermentation facilities.
- Instruments:Electroporation and microinjection platforms require substantial capital deployment with extended validation timelines. CDMOs serving CAR-T developers are prioritizing GMP-compliant electroporation capacity ahead of IND filings.
Established volume favors reagents; emerging adoption favors instruments.
Technology:
Technology selection maps directly to cell membrane compatibility and payload delivery efficiency across therapeutic and research applications.
- Lipid-Based:Cationic lipid formulations achieve 80-90% transfection efficiency in immortalized cell lines. mRNA vaccine infrastructure validated during COVID-19 programs is now redeploying into oncology pipelines.
- Electroporation:Electrical pulse delivery enables direct nucleic acid entry into primary cells and stem cell populations. Japan's PMDA and China's NMPA are tightening comparability criteria for ex vivo CAR-T electroporation devices.
- Calcium Phosphate:Cost-effective chemical precipitation remains prevalent in academic protein expression workflows. Price-sensitive screening operations in Indian research institutes continue deploying this legacy approach.
- Viral Vector:Lentiviral and retroviral systems achieve stable genomic integration for gene therapy applications. Biosafety Level 3 handling requirements inflate per-batch manufacturing economics in European facilities.
- Polymer-Based:Polyethyleneimine and derivative formulations capture price-sensitive discovery workflows. Academic core facilities are unbundling polymer procurement from instrumentation service contracts.
- Microinjection:Direct physical delivery enables precise single-cell manipulation in embryonic stem cell applications. Specialized demand concentrates in transgenic animal facilities with dedicated operator expertise.
Mature efficiency standards favor lipid-based systems; steepest expansion trajectory belongs to electroporation.
Application:
Application segmentation reflects the progression from fundamental research through therapeutic manufacturing.
- Gene Function Studies:RNA interference and CRISPR-mediated knockdown protocols drive consumable demand in academic core facilities. CRISPR workflows are expanding fastest in United States research institutions with centralized purchasing offices.
- Protein Production:Transient expression systems enable rapid recombinant protein generation for structural biology and assay development. Biotechnology firms in Germany are optimizing CHO and HEK293 expression platforms for antibody production.
- Cell Line Development:Stable transfection underpins biopharmaceutical manufacturing cell banks. FDA plasmid master file requirements shape supplier qualification for pharmaceutical companies.
- Gene Therapy:Viral vector manufacturing and non-viral delivery systems serve clinical-stage nucleic acid therapeutics. EMA genetically modified organism containment standards are forcing European facility redesigns with dedicated HVAC zones.
- Drug Screening:High-throughput transfection enables target validation and lead optimization in pharmaceutical discovery. Contract research organizations in Hyderabad and Bengaluru are building automated screening capacity.
Revenue concentration favors protein production; regulatory momentum favors gene therapy.
End User:
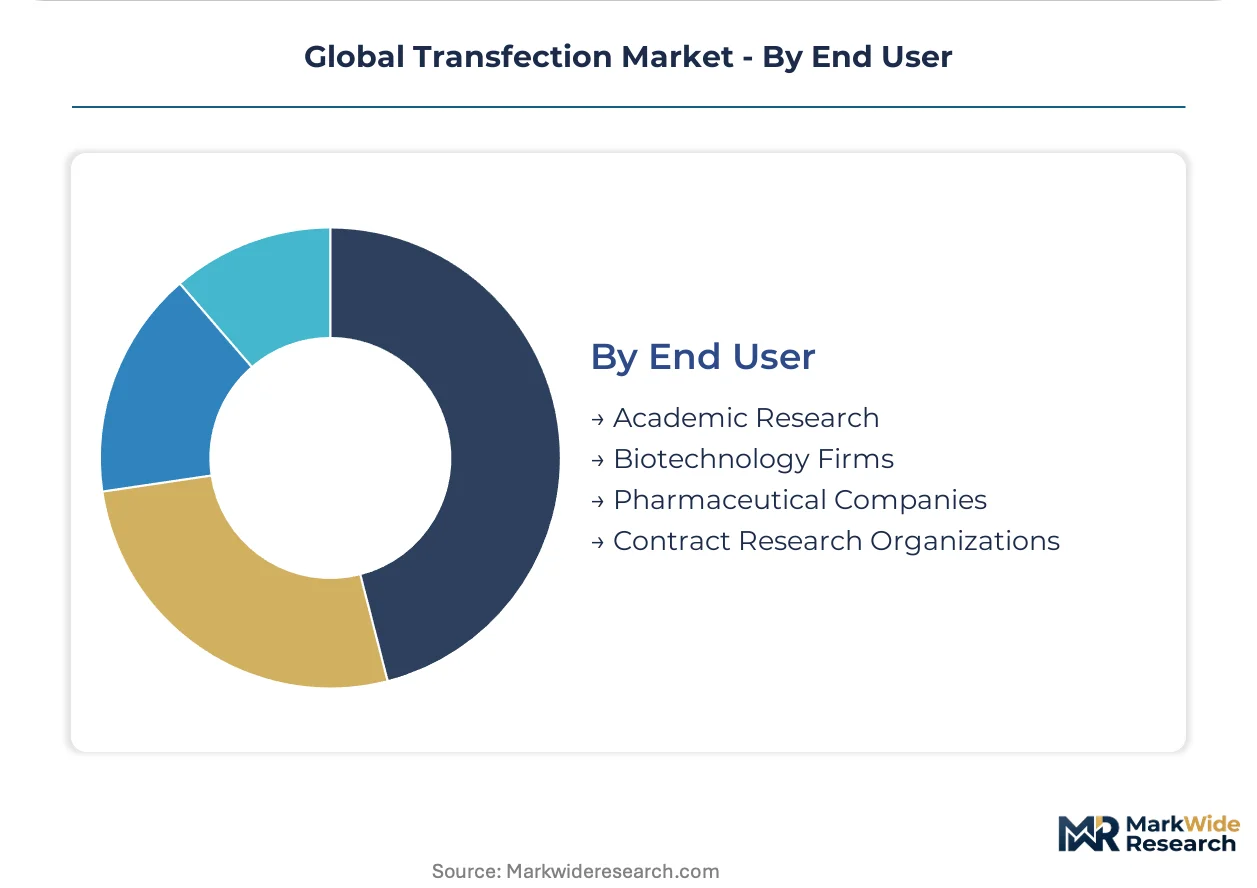
End user segmentation reveals divergent procurement priorities between research flexibility and manufacturing compliance.
- Academic Research:Core facilities balance reagent cost against protocol versatility across diverse investigator needs. Spot pricing negotiations through distributor marketplaces are compressing supplier margins.
- Biotechnology Firms:Venture-funded programs prioritize speed-to-data with scalable technology transfer pathways. Early-stage electroporation instrumentation adoption concentrates in Boston-San Francisco corridors.
- Pharmaceutical Companies:GMP-compliant infrastructure and regulatory documentation dominate vendor selection criteria. Lipid nanoparticle platform maturation is expanding internal mRNA manufacturing capabilities.
- Contract Research Organizations:CDMOs aggregate demand across client programs to justify dedicated transfection capacity investments. India-based CROs in Hyderabad and Bengaluru are capturing cost-sensitive viral vector outsourcing.
Procurement volume favors pharmaceutical companies; platform experimentation favors biotechnology firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reagent pricing commands premium multiples over Indian contract manufacturing alternatives, compressing margin arbitrage for multinational suppliers. European regulatory compliance costs inflate facility economics relative to Asia-Pacific expansion zones. Japan and China impose divergent electroporation validation standards that fragment cross-border technology transfer.
United States
FDA accelerated approval pathways compress nucleic acid therapeutic timelines and expand plasmid production capacity investments. The agency's plasmid master file requirements shape supplier qualification hierarchies for viral vector programs. Boston and San Francisco biotech clusters anchor contract research organization spending on transfection infrastructure and early-stage electroporation instrumentation adoption.
Germany
Biotechnology firms optimize CHO and HEK293 expression platforms for recombinant antibody production, driving stable transfection demand. EMA genetically modified organism containment standards enforce facility segregation between viral vector and plasmid production suites. North Rhine-Westphalia manufacturers are consolidating operations into single-campus configurations with dedicated HVAC zones to streamline cross-border approval processes.
Switzerland
Pharmaceutical companies lock in multi-year kit supply agreements to secure batch consistency for regulatory submissions. Swissmedic harmonization with EMA release specifications reduces dual qualification burdens for gene therapy suppliers. Basel and Zurich anchor purpose-built gene therapy manufacturing sites capturing European contract manufacturing demand.
India
Contract research organizations in Hyderabad and Bengaluru build plasmid production capabilities to capture cost-sensitive viral vector outsourcing from Western sponsors. CDSCO tightening of biosimilar comparability criteria shapes facility investment priorities for ex vivo cell therapy programs. CDMO expansion concentrates in Telangana and Karnataka where fermentation infrastructure costs undercut European alternatives.
Japan
PMDA tightening of ex vivo electroporation device validation standards extends regulatory timelines for CAR-T platform entrants. METI industrial policy supports domestic cell therapy manufacturing capacity to reduce import dependence for critical reagents. Kanto region bioclusters concentrate precision instrumentation demand for stem cell and primary cell applications.
Global Transfection Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and vector supply. The vendor base stratifies across three tiers: diversified life science conglomerates with channel density, mid-scale electroporation instrument developers, and regional fermentation specialists serving plasmid demand. Two strategic archetypes dominate competitive positioning: consumable-heavy reagent suppliers capturing repeat-purchase workflows, and capital equipment providers locking in multi-year service contracts. Capacity expansion and strategic partnerships represent the dominant competitive moves as CDMOs race to secure GMP-compliant infrastructure ahead of IND filings.
Among diversified platform providers, Thermo Fisher Scientific and Merck KGaA exemplify the integrated reagent-instrument archetype with global channel presence. Lonza Group occupies a position representing large-scale plasmid production specialization for viral vector programs. QIAGEN sits within the nucleic acid purification integration tier that locks in downstream transfection workflows. MaxCyte and Bio-Rad Laboratories represent the electroporation instrumentation segment where precision manufacturing requirements create specialist scarcity. Sartorius AG exemplifies European-based bioprocess integration spanning filtration through final fill. Promega Corporation, Takara Bio, and regional fermentation specialists anchor the reagent and kit tier where price transparency pressures margins.
| Leading Market Players |
|---|
| Merck KGaA |
| Promega Corporation |
| Thermo Fisher Scientific |
| Sartorius AG |
| MaxCyte |
| QIAGEN |
| Bio-Rad Laboratories |
| Takara Bio |
| Lonza Group |
| Others |
Supply & Pricing Matrix
GMP-certified fermentation capacity underutilization in North America is pressuring contract manufacturers to discount long-term plasmid supply agreements while simultaneously restricting spot-market availability for viral vector developers. This utilization asymmetry rewards multi-year commitment strategies from pharmaceutical sponsors and squeezes margin buffers for reagent suppliers serving price-sensitive academic segments.
Pricing Analysis
The customization-premium spread between configured-to-order GMP reagent formulations and standard research-grade catalog products spans three distinct certification tiers. Pricing stratifies across premium, standard, and economy levels based on FDA master file documentation depth and ISO 13485 quality system verification. Cost compression in the economy tier is intensifying because Indian CDMOs are undercutting European fermentation economics for non-GMP plasmid production. Academic core facilities exhibit highest price sensitivity, while cell therapy developers demonstrate lowest sensitivity due to regulatory submission risk.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for electroporation device manufacturers sourcing precision electrical components. Geographic supply concentration centers on the United States for GMP plasmid fermentation, Switzerland for kit formulation and fill-finish, and India for cost-sensitive viral vector outsourcing. Raw material dependencies include cationic lipid precursors, pharmaceutical-grade plasmid DNA, and borosilicate electroporation cuvettes. Single-source vulnerability concentrates in lipid nanoparticle excipient supply. Distribution runs through direct field service organizations for instrumentation and distributor marketplaces for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where electroporation parameter databases are achieving interoperability with manufacturing execution systems, enabling CDMOs to monetize process development data as a secondary revenue stream alongside physical reagent supply.
For Market Incumbents: Insulate kit formulation margins by backward integration into lipid precursor synthesis and locking multi-year supply agreements with CAR-T developers ahead of IND filings. Thermo Fisher Scientific's channel density represents a replicable defensive moat against emerging biotech-focused distributors. Prioritize GMP certification investment in Swiss and Dutch facilities to capture EMA harmonization benefits. For New Entrants and Emerging Players: Indian CDMO underpenetration in ex vivo electroporation device validation services offers the most penetrable white-space target, particularly for sponsors seeking cost-sensitive viral vector production alternatives. Academic core facility spot pricing negotiations represent a convertible demand pool from bundled service contracts. Deploy à-la-carte consumable purchasing platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consumable-recurrence play because repeat-purchase reagent models generate predictable revenue streams insulated from capital equipment cyclicality. Acquisition targets should prioritize electroporation instrumentation specialists with installed base expansion potential. Monitor FDA-EMA convergence on viral vector release specifications as the critical inflection signal for supplier qualification consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Electroporation Capacity Expansion | CDMOs in Switzerland and the Netherlands are securing multi-year service contracts ahead of IND filings. |
| Lipid Nanoparticle Platform Integration | Pharmaceutical companies are redeploying COVID-19-validated mRNA infrastructure into oncology pipelines. |
| Plasmid Master File Synchronization | Global suppliers are streamlining dual FDA-EMA qualification pathways to reduce regulatory submission burden. |
| Academic Core Facility Marketplace Disintermediation | Spot pricing negotiations through distributor platforms are compressing traditional bundled service margins. |
| India CDMO Fermentation Buildout | Hyderabad and Bengaluru facilities are capturing cost-sensitive viral vector outsourcing from Western sponsors. |
Research Methodology
A standing panel of cell therapy manufacturing executives, regulatory affairs leads at gene therapy developers, GMP facility operators, and academic core facility directors provided ongoing calibration across primary fieldwork and secondary validation. Secondary sources included FDA plasmid master file databases, EMA genetically modified organism containment guidelines, ClinicalTrials.gov nucleic acid therapeutic entries, and CDSCO biosimilar comparability criteria. Bottom-up demand modeling from reagent consumption patterns triangulated against top-down pharmaceutical R&D spending allocations.
Scenario bracketing anchored volume and value outputs across conservative, baseline, and expansion cases throughout the forecast period. Segmentation dimensions modeled included product type, technology platform, application stage, end-user archetype, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating lipid nanoparticle platform maturation rates and electroporation device adoption trajectories in CAR-T manufacturing. Industry-specific inputs encompassed CDMO capacity utilization surveys and academic procurement office pricing negotiation patterns.
Macroeconomic conditions sit as an overlay; deviation in venture capital deployment to Boston-San Francisco biotech corridors or sustained interest rate elevation would shift the trajectory for early-stage electroporation instrumentation demand. Forecasts reflect documented assumptions regarding regulatory approval pathway acceleration and EMA containment standard harmonization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
BOD Incubator Market
Biomedical Technology
Asia-Pacific Exosome Research Products Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Neoantigen Market
Biomedical Technology
Global Optogenetics Market
Biomedical Technology
Lipid Transfer Proteins Market
Biomedical Technology
Human Biobanking Ownership Market
Biomedical Technology
Life Science Analytics Market
Biomedical Technology
France Flow Cytometry Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Glycomics Market
Biomedical Technology
Global Molecular Biosensors Market
Biomedical Technology
Global Stem Cell Assay Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Drug Delivery Technology Market
Biomedical Technology
Global Tissue Microarray Market