
 Serine Protease Market | 2026-2036
Serine Protease Market Size, Share, and Industry Trends Forecast 2026-2036
Serine Protease Market Analytics
China is narrowing its reliance on imported active pharmaceutical ingredients for serine protease manufacturing through domestic fermentation capacity expansion. Novozymes A/S leverages microbial strain engineering to sustain cost leadership in industrial-grade enzymes. Roche Holding AG anchors high-purity therapeutic protease supply through captive biologics infrastructure. BASF SE competes on fermentation scale for commodity protease intermediates serving diagnostics manufacturers.
Serine proteases constitute a class of enzymes characterized by a catalytic triad of serine, histidine, and aspartate residues that hydrolyze peptide bonds with substrate specificity determined by the active site geometry. These enzymes function in blood coagulation cascade modulation, protein digestion, and immune response regulation across pharmaceutical and industrial biotechnology applications. Trypsin dominates research-grade consumption due to its established role in cell culture and proteomics workflows, while recombinant-source production represents the fastest-expanding supply category as manufacturers eliminate animal-origin contamination risks. Therapeutic applications command the deepest margin pools because cGMP compliance and viral clearance validation create qualification barriers that commodity suppliers cannot readily cross.
FDA enforces stringent viral safety requirements for animal-derived enzymes used in biologics manufacturing, compelling migration toward recombinant or plant-source alternatives. EMA's MDR and ISO 13485 standards shape diagnostic-grade protease specifications across European Union member states, while China's NMPA accelerates local biosimilar approval pathways that incorporate serine protease components. Stakeholders must monitor regulatory divergence between recombinant certification requirements in major jurisdictions to anticipate qualification cost shifts and supply chain reconfiguration needs.
Market Dynamics
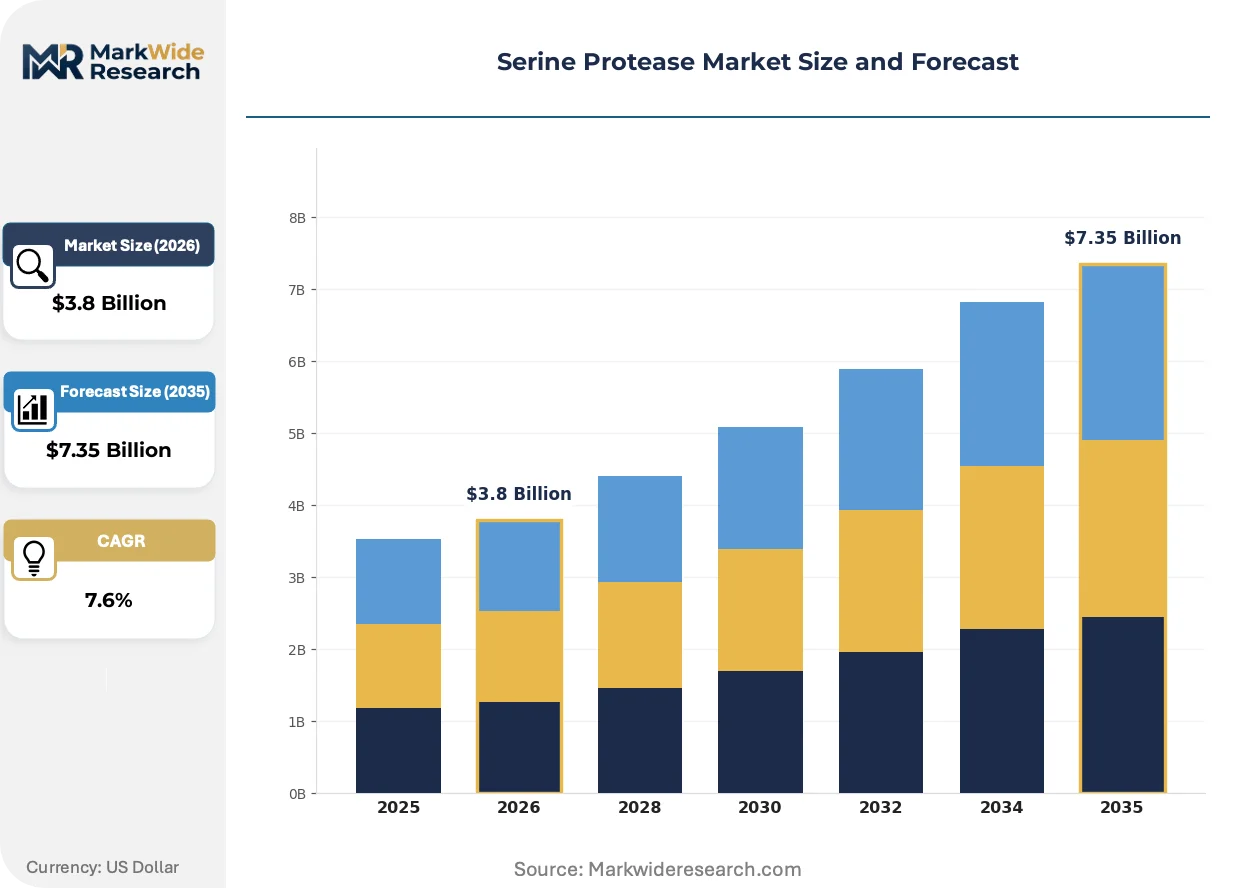
Recombinant production technologies are collapsing the cost premium between animal-derived and microbial-source serine proteases, redistributing margin pools from legacy extraction suppliers to precision fermentation specialists.
Growth Catalysts
- EMA MDR compliance mandates:Diagnostic manufacturers across European Union member states must source ISO 13485-certified proteases, accelerating qualification of recombinant alternatives to animal-origin enzymes.
- Oncology therapeutic pipelines:Blood coagulation cascade modulators utilizing engineered serine proteases are advancing through Phase III trials, expanding addressable patient populations for hematology applications.
- China's dual carbon goals:NMPA incentives for green biomanufacturing are redirecting capital toward domestic fermentation capacity, reducing import dependency for active pharmaceutical ingredients.
Market Restraints
- Fermentation feedstock volatility:Glucose and nitrogen source price swings compress margins for microbial protease producers operating at industrial scale.
- Viral clearance validation costs:FDA's stringent safety requirements for animal-derived enzymes impose six-figure qualification burdens that exclude commodity suppliers from therapeutic-grade markets.
- Substitute enzyme classes:Cysteine and metalloproteases are capturing share in industrial protein digestion applications where substrate specificity requirements are less stringent.
Strategic Opportunities
- Plant-source expression systems:Moss and duckweed platforms eliminate endotoxin concerns while satisfying vegan certification requirements for cosmetic and nutraceutical formulations.
- Continuous bioprocessing adoption:Perfusion fermentation technology integration enables real-time protease harvesting, reducing downstream purification bottlenecks.
- India's PLI scheme:Production-linked incentives for biotechnology manufacturing are attracting contract development organizations to establish regional fill-finish capabilities.
Industry Challenges
- cGMP talent scarcity:Qualified fermentation scientists capable of viral clearance protocol design command premium compensation, constraining mid-scale facility expansion.
- Legacy equipment retrofit costs:Stainless steel bioreactor fleets require seven-figure automation upgrades to achieve process analytical technology compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serine Protease Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trypsin, Chymotrypsin, Elastase, Thrombin Application: Biotechnology, Diagnostics, Therapeutics, Research End User: Pharmaceuticals, Biotechnology Firms, Research Institutes, Academic Institutions Source: Animal, Plant, Microbial, Recombinant |
| Companies Covered | Roche Holding AG, Amano Enzyme Inc., Novozymes A/S, DSM, AB Enzymes GmbH, BASF SE, Merck KGaA, Chr. Hansen Holding A/S, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serine Protease Market Evolving Landscape
Precision fermentation is collapsing the traditional boundaries between research-grade and therapeutic-grade serine protease supply tiers, enabling single-source manufacturers to serve multiple certification levels.
Microbial strain engineering is collapsing the yield gap between Pichia pastoris and mammalian cell culture systems for complex protease folding. Contract manufacturers in Germany and Japan are adopting CRISPR-optimized expression platforms to capture high-purity therapeutic contracts previously reserved for CHO cell production. The technology is collapsing the historical 18-month timeline for new protease variant commercialization.
REACH authorization requirements for industrial enzyme formulations are compelling European manufacturers to submit full substance dossiers for legacy protease blends previously exempt under intermediate use provisions. Chemical formulators serving detergent and textile sectors are consolidating supplier relationships to reduce registration cost exposure. The regulation is most acutely affecting mid-tier industrial blenders in Germany and the Netherlands.
Biopharmaceutical procurement teams are unbundling protease supply from bundled cell culture media contracts, conducting direct qualification of recombinant trypsin and collagenase alternatives. Large molecule CDMOs in the United States are establishing approved supplier lists with dedicated serine protease categories. The shift is most visible among gene therapy manufacturers requiring animal-origin-free documentation for regulatory submissions.
Serine Protease Market Segmentation
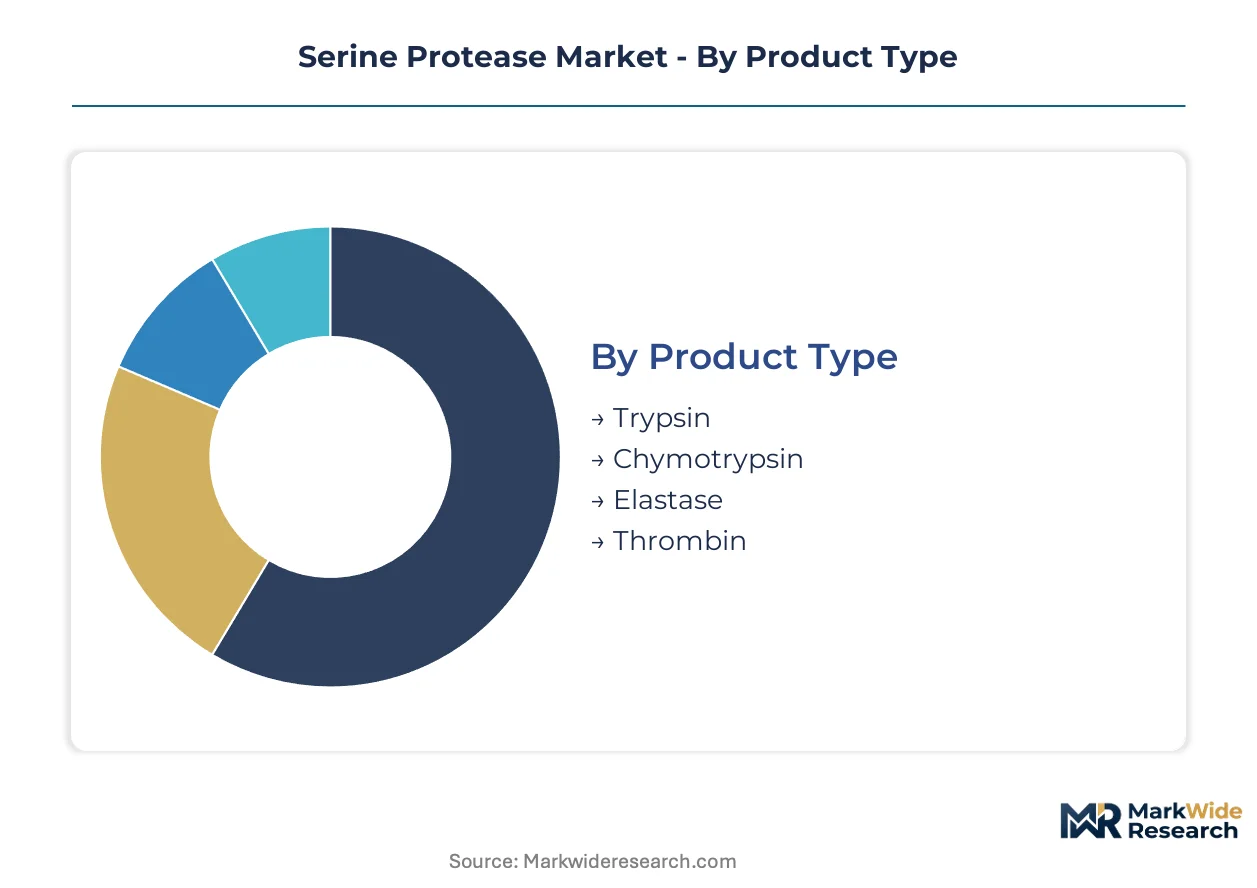
Serine protease procurement patterns diverge sharply across certification grades, with cGMP compliance requirements fragmenting supply tiers that fermentation technology is now beginning to bridge. Manufacturers optimize production platforms against end-use specifications rather than pursuing universal scale economies.
Product Type:
Trypsin and chymotrypsin anchor cell culture workflows, while thrombin concentrates in coagulation therapeutics and elastase serves specialized diagnostic applications.
- Trypsin:Pancreatic serine protease with specificity for lysine and arginine residues dominates cell dissociation protocols and protein digestion workflows. Demand concentrates in United States gene therapy manufacturing where FDA mandates animal-origin-free documentation for regulatory submissions.
- Thrombin:Coagulation factor IIa with dual procoagulant and anticoagulant regulatory functions commands therapeutic-grade margins. Hematology applications in Germany and Japan drive qualification of recombinant variants to satisfy EMA MDR and PMDA viral safety requirements.
- Chymotrypsin:Aromatic residue-specific protease serves peptide mapping and quality control analytics in biologics manufacturing.
- Elastase:Broad-substrate protease targets connective tissue matrices in specialized cell isolation protocols and pulmonary research.
Established volume favors trypsin; emerging adoption favors thrombin recombinant alternatives.
Application:
Margin structures stratify across certification burdens, with therapeutic applications requiring viral clearance validation that research segments bypass entirely.
- Therapeutics:cGMP-grade proteases for coagulation disorders and wound healing command premium pricing contingent on FDA process validation and EMA batch release testing. Blood coagulation cascade modulators advancing through Phase III trials in United States and European Union expand addressable patient populations.
- Biotechnology:Cell culture and bioprocessing applications require ISO 13485-compliant protease supply with documented absence of adventitious agents. Large molecule CDMOs in Germany unbundle protease procurement from bundled media contracts to establish direct supplier qualification.
- Diagnostics:Immunoassay and molecular testing applications utilize research-grade specifications with lower purity thresholds.
- Research:Proteomics and academic workflows consume commodity trypsin with minimal regulatory documentation requirements.
Therapeutic-grade certification captures margin concentration; biotechnology applications expand volume fastest.
End User:
Procurement sophistication varies with regulatory exposure, from validated supplier audits in pharmaceuticals to catalog purchasing in academic settings.
- Pharmaceuticals:Integrated biopharmaceutical manufacturers and contract development organizations enforce captive supply agreements or approved vendor lists with dedicated serine protease categories. FDA viral safety guidance compels migration toward recombinant sources for biologics manufacturing.
- Biotechnology Firms:Mid-scale cell therapy developers in United States and Japan prioritize animal-origin-free documentation to streamline IND submissions.
- Research Institutes:Government and nonprofit laboratories balance specification requirements against budget constraints in protease procurement.
- Academic Institutions:University core facilities purchase research-grade enzymes through distributor channels with minimal technical support requirements.
Pharmaceutical verticals dominate value capture; biotechnology firms drive specification evolution.
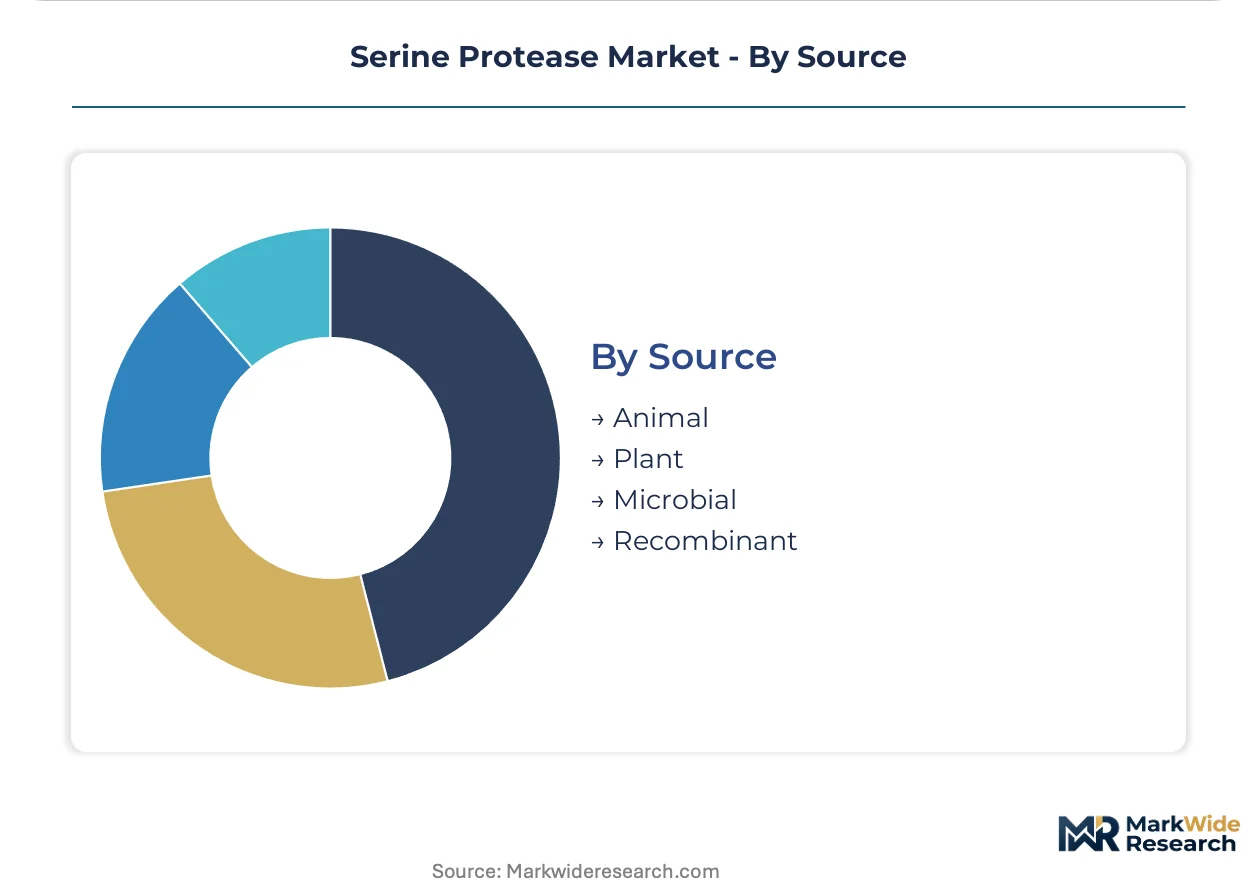
Source:
Production technology selection determines endotoxin profiles, glycosylation patterns, and regulatory pathway complexity across end-use applications.
- Recombinant:Microbial and mammalian expression systems eliminate animal-origin contamination risks while enabling defined glycosylation for therapeutic proteases. Pichia pastoris platforms with CRISPR-optimized strains are collapsing yield gaps with CHO cell culture in Germany and Japan.
- Microbial:Bacterial fermentation of Bacillus subtilis proteases serves industrial and diagnostic applications where endotoxin clearance is manageable.
- Plant:Moss and duckweed expression systems satisfy vegan certification requirements for cosmetic and nutraceutical formulations without endotoxin concerns.
- Animal:Pancreatic extraction from porcine and bovine sources retains cost advantage in research segments despite FDA restrictions on biologics manufacturing use.
Recombinant platforms claim specification leadership; microbial fermentation retains cost-sensitive volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA viral safety mandates anchor United States procurement patterns, while EMA MDR compliance and NMPA green biomanufacturing incentives reshape supply chain configurations across Germany, China, and Japan.
United States
Gene therapy manufacturers in Massachusetts and North Carolina drive demand for animal-origin-free trypsin documentation to satisfy FDA IND submission requirements. The agency's stringent viral clearance protocols compel migration toward recombinant production platforms. Greater Boston anchors high-purity therapeutic protease qualification as cell therapy developers establish captive supply agreements.
Germany
Diagnostic manufacturers across Baden-Württemberg and Bavaria accelerate ISO 13485-certified protease qualification under EMA MDR enforcement timelines. REACH authorization requirements for industrial enzyme formulations impose registration cost burdens on mid-tier blenders. The Rhine-Main biopharmaceutical cluster concentrates CRISPR-optimized Pichia pastoris capacity expansion for therapeutic-grade contracts.
China
NMPA incentives for green biomanufacturing redirect capital toward domestic fermentation capacity in Jiangsu and Shandong provinces. The regulator's accelerated biosimilar approval pathways incorporate serine protease components for local production substitution. Yangtze River Delta biopharmaceutical parks anchor fermentation infrastructure buildout to narrow API import dependency.
Japan
PMDA viral safety requirements for biologics manufacturing drive qualification of recombinant thrombin variants in Osaka and Tokyo prefectures. METI biotechnology funding supports precision fermentation technology adoption for high-purity therapeutic supply. The Kansai region concentrates mammalian cell culture expertise previously reserved for complex protease folding applications.
India
PLI scheme production-linked incentives attract contract development organizations to establish regional fill-finish capabilities in Maharashtra and Telangana. CDSCO regulatory convergence with ICH guidelines streamlines biosimilar component qualification for export-oriented manufacturers. Hyderabad's genome valley anchors microbial strain engineering capacity serving both domestic and European diagnostic markets.
Serine Protease Market Competitive Landscape
Capability concentration sits with precision fermentation specialists commanding therapeutic-grade margins; scale advantage sits with industrial enzyme producers serving commodity diagnostics and research segments. The market structures around three archetypes: captive biopharmaceutical infrastructure operators, precision fermentation technology licensors, and diversified industrial biotechnology conglomerates. Consolidation pressures favor backward integration into fermentation capacity and strategic partnerships for viral clearance protocol access.
Within the therapeutic-grade tier, Roche Holding AG and Novozymes A/S exemplify divergent competitive positions—Swiss pharmaceutical infrastructure versus Danish industrial biotechnology scale. Amano Enzyme Inc. occupies a specialized position in enzyme manufacturing. These three entities represent the spectrum from captive biologics supply to diversified fermentation platforms, with each archetype facing distinct qualification cost burdens and margin pool access constraints.
| Leading Market Players |
|---|
| Roche Holding AG |
| Amano Enzyme Inc. |
| Novozymes A/S |
| DSM |
| AB Enzymes GmbH |
| BASF SE |
| Merck KGaA |
| Chr. Hansen Holding A/S |
| DuPont de Nemours, Inc. |
| Others |
Value Network & Pricing Analysis
Jiangsu province's fermentation capacity expansion is compressing import premiums for active pharmaceutical ingredients while amplifying pricing leverage for domestic manufacturers serving therapeutic-grade protease contracts.
Pricing Analysis
United States-Germany price spreads for recombinant trypsin exceed those for microbial-source alternatives, with certification grade and volume scale serving as the primary price differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels captures margin concentration in cGMP-compliant therapeutic segments while research-grade commoditization intensifies cost competition. Pricing pressure stems from glucose and nitrogen source volatility in industrial fermentation. Academic institutions exhibit highest price sensitivity; integrated biopharmaceutical manufacturers demonstrate lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Contract manufacturers in Germany, Japan, and the United States hold concentrated capacity for therapeutic-grade serine protease production. Bacillus subtilis fermentation strains, CHO cell culture media, and plant-based expression vectors constitute critical input dependencies. Single-source vulnerability around CRISPR-optimized Pichia pastoris platforms poses structural risk. Distribution runs through validated supplier lists at large molecule CDMOs and direct procurement channels for gene therapy developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough as recombinant production technology maturation collapses cost premiums and redirects procurement toward microbial-source alternatives.
For Market Incumbents: Pre-empt margin erosion in research-grade segments by accelerating backward integration into precision fermentation capacity in the Yangtze River Delta. Invest in viral clearance protocol certification to defend therapeutic-grade positioning against emerging plant-source competitors. Captive biologics infrastructure at Roche Holding AG exemplifies the defensive moat required.
For New Entrants and Emerging Players: Pursue white-space opportunity in plant-source expression systems for cosmetic and nutraceutical formulations where vegan certification commands premium positioning. India's PLI scheme-supported contract development organizations represent the most penetrable entry point for regional fill-finish capabilities. Lead with animal-origin-free documentation as the primary go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a capability consolidation play because precision fermentation expertise is concentrating among specialists capable of spanning research-grade through cGMP certification tiers. Target precision fermentation technology licensors with demonstrated CRISPR strain optimization capabilities. Monitor FDA biosimilar guidance acceleration as the critical inflection signal for therapeutic-grade demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | CRISPR-optimized Pichia pastoris platforms collapse yield gaps with mammalian cell culture in Germany. |
| Viral Clearance Protocol Certification | FDA safety mandates exclude commodity suppliers from therapeutic-grade margin pools. |
| Plant-Source Expression System Development | Moss and duckweed platforms satisfy vegan certification requirements without endotoxin concerns. |
| Continuous Bioprocessing Technology Adoption | Perfusion fermentation enables real-time harvesting and reduces downstream purification bottlenecks. |
| Regional Fill-Finish Capability Establishment | India's PLI scheme attracts contract development organizations to Maharashtra and Telangana. |
Research Methodology
The analysis maps recombinant production platforms, therapeutic-grade certification tiers, and industrial enzyme applications, each validated through fermentation scientists, regulatory affairs specialists, and biopharmaceutical procurement managers. Primary interviews with CDMO supply chain directors and diagnostic manufacturer quality officers combined with secondary validation from FDA guidance documents, EMA MDR submissions, and NMPA biosimilar pathway announcements. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Assumptions held fixed include regulatory divergence patterns between FDA, EMA, and PMDA viral safety requirements; varied assumptions include fermentation feedstock cost trajectories and CRISPR strain optimization adoption rates. Segmentation dimensions span source technology, application certification grade, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from capacity buildout timelines and substitution elasticity between animal-derived and recombinant alternatives. Forecast inputs incorporate China's dual carbon goals policy intensity and EMA MDR enforcement timelines.
Macroeconomic conditions sit as an overlay; deviation in biopharmaceutical capital expenditure cycles or glucose commodity pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory convergence and technology adoption S-curves. Quarterly review of FDA biosimilar approval velocity and NMPA green biomanufacturing incentive disbursement is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Peptide and Oligonucleotide CDMO Market
Biotechnology Services
Molecular Methods Market
Biotechnology Services
Biologics CDMO Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
Prokaryotic Expression Systems Market
Biotechnology Services
Biobank Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
Global Protein Binding Assay Market
Biotechnology Services
Phospho-Specific Antibodies Market
Biotechnology Services
Global Western Blotting Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Plasma Feed Market