
 France Flow Cytometry Market | 2026-2036
France Flow Cytometry Market Size, Share, and Industry Trends Forecast 2026-2036
France Flow Cytometry Market Analysis
Aftermarket service revenue is narrowing as instrument manufacturers push bundled reagent contracts to capture lifetime value. Danaher leverages its consumables portfolio to lock in recurring revenue across installed bases. BD sustains competitive pressure through deep clinical validation in hematology diagnostics. Sysmex Corporation anchors its position with automated sample preparation workflows that reduce operator dependency.
Flow cytometry measures physical and chemical characteristics of cells or particles suspended in fluid by passing them through laser beams, detecting scattered light and fluorescence emissions at rates exceeding 10,000 events per second for multiplexed phenotyping. The technique enables quantitative cell sorting, immunophenotyping, and biomarker detection across research and diagnostic settings. Instruments and reagents together command the dominant share of product-type revenue, with analytical software emerging as the fastest-growing segment as laboratories demand AI-assisted gating algorithms. End-user demand concentrates in research institutions and pharmaceutical companies, where high-parameter panels for immuno-oncology trials drive instrument utilization and reagent pull-through.
ANSM governs in vitro diagnostic device registration under the EU Medical Device Regulation transition, while France's national health technology assessment body evaluates flow cytometry platforms for reimbursement eligibility in hospital laboratories. The country's adoption of MDR conformity requirements shapes product development timelines and clinical evidence standards for new instrument launches. Stakeholders must monitor how evolving CE marking obligations and reagent quality certifications reshape competitive access to French clinical and research procurement channels.
Market Dynamics
Instrument manufacturers in France are bundling reagent contracts to capture lifetime value from installed bases, compressing aftermarket service revenue while locking laboratories into recurring consumable purchases.
Growth Catalysts
- EU Medical Device Regulation:MDR transition at ANSM accelerates replacement of legacy platforms with CE-IVDR certified systems in Paris hospital laboratories.
- Immuno-oncology trials:Pharmaceutical companies in Lyon demand high-parameter panels for cell therapy development, pulling through instrument utilization and reagent volumes.
- Île-de-France research cluster:France's national biomedical research strategy prioritizes cell-based analysis platforms, directing public funding toward flow cytometry infrastructure.
Market Restraints
- Fluorophore supply concentration:Reagent production depends on specialized dye chemistries sourced from a narrow supplier base in Germany and the United States.
- MDR clinical evidence requirements:ANSM's expanded conformity obligations extend product development timelines by 18-24 months for new instrument launches.
- Mass cytometry substitution:Metal-tag detection systems offer higher multiplexing capacity for deep immunophenotyping in certain research applications.
Strategic Opportunities
- AI-assisted gating software:Machine learning algorithms for automated population identification represent the fastest-growing product segment as laboratories seek operator-independent analysis.
- Automated sample preparation:Integration of robotic liquid handling with analytical workflows reduces technician dependency in high-throughput clinical settings.
- CNIL data governance frameworks:France's health data privacy regulations create competitive differentiation for vendors offering compliant cloud-based data management.
Industry Challenges
- Specialized cytometrist shortage:Clinical laboratories in Marseille and Toulouse struggle to recruit trained operators capable of complex panel design and compensation.
- Legacy LIS integration:New instruments must interface with established laboratory information systems through HL7 or proprietary protocols, extending deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Flow Cytometry Market |
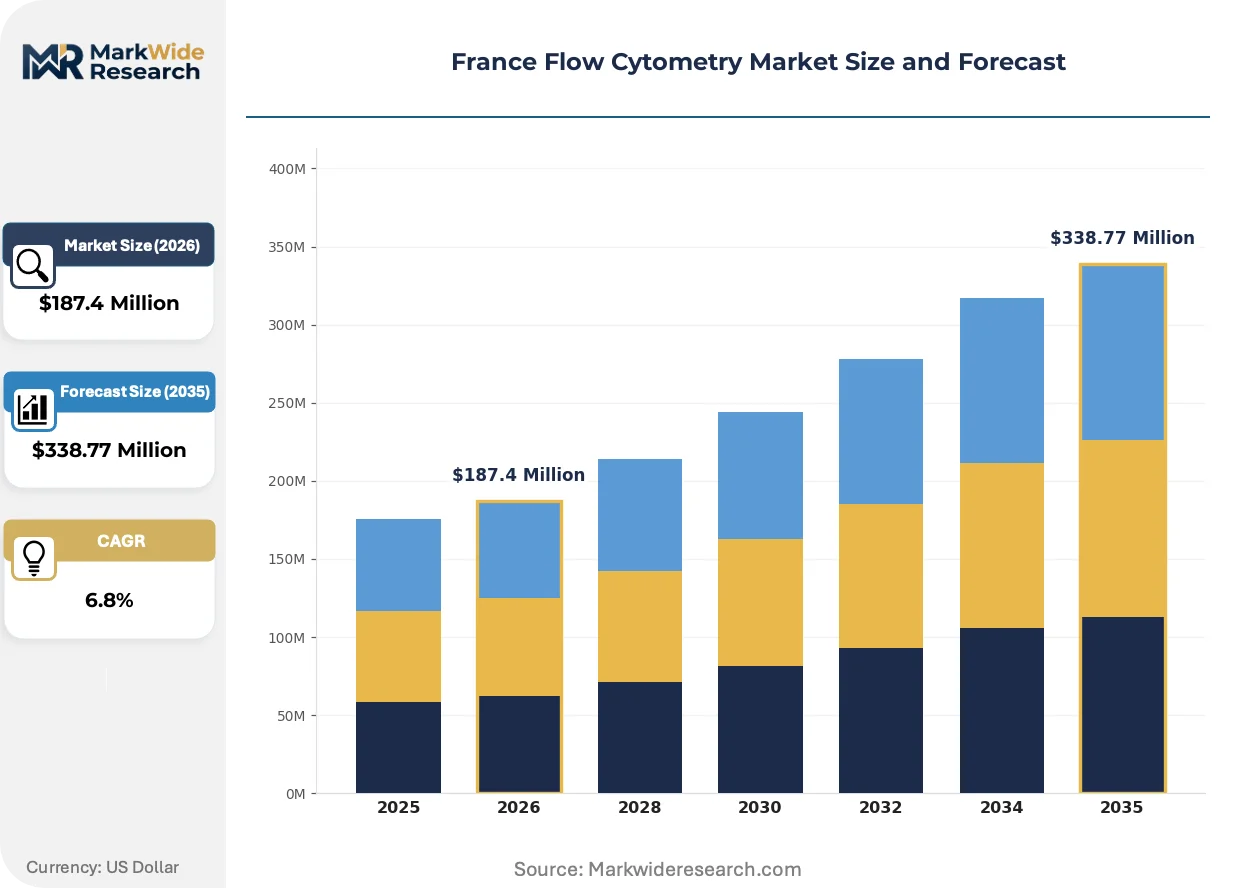
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytical, Reagents, Software, Instruments End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Biotechnology Firms Component: Flow Cell, Laser, Detectors, Fluidics System Application: Immunology, Oncology, Hematology, Drug Development |
| Companies Covered | Danaher, BD, Sysmex Corporation, Agilent Technologies, Thermo Fisher Scientific, Bio-Rad Laboratories, Beckman Coulter, Merck KGaA, Miltenyi Biotec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Flow Cytometry Market Emerging Trajectories
Spectral detection architectures are replacing traditional filter-based systems, enabling simultaneous measurement of 40+ fluorochromes without compensation matrices. This shift is compressing hardware differentiation while elevating software and reagent portfolios as primary competitive battlegrounds.
Full-spectrum flow cytometry is collapsing the distinction between research and clinical instrumentation by delivering research-grade parameter depth on platforms qualifying for diagnostic use. Academic medical centers in Strasbourg and Bordeaux are adopting these systems for translational programs, forcing vendors to unify their product architectures. The convergence is eroding the premium pricing historically commanded by research-dedicated instruments.
ANSM's implementation of MDR post-market surveillance requirements is mandating continuous performance monitoring for CE-IVDR certified devices. Manufacturers must maintain updated clinical evidence portfolios and report adverse events through the EUDAMED database. Hospital laboratories now prioritize vendors with established regulatory infrastructure over newer entrants lacking MDR transition experience.
Service unbundling is accelerating as independent third-party providers capture maintenance contracts from original equipment manufacturers. Regional service networks in Provence-Alpes-Côte d'Azur and Occitanie are offering faster response times and flexible pricing structures. This fragmentation is pressuring manufacturer margins on aftermarket revenue while creating channel conflict in multi-vendor installations.
France Flow Cytometry Market Segmentation
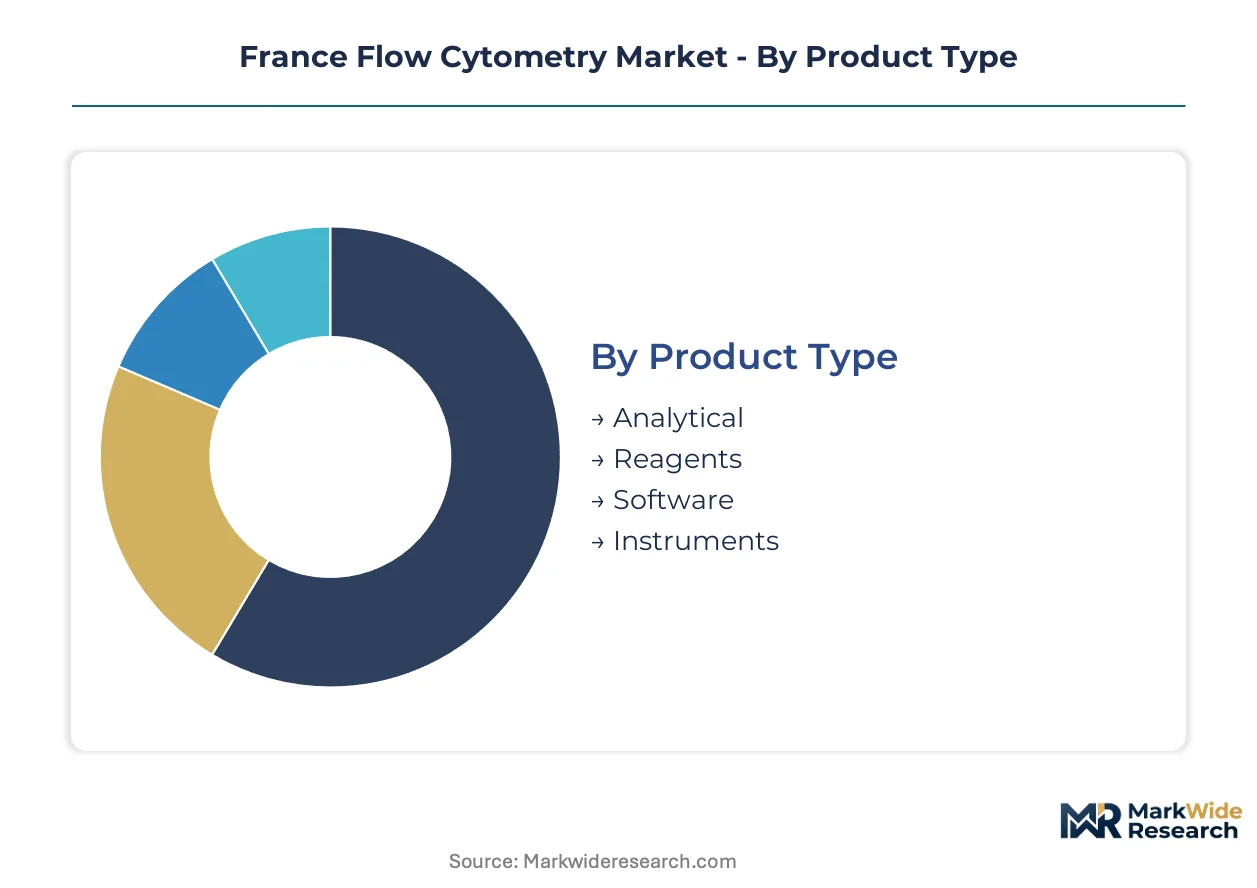
Flow cytometry segmentation in France reveals divergent replacement cycles across product layers. Instruments lock laboratories into multi-year depreciation schedules while consumables and software refresh annually, creating distinct revenue rhythms for vendors serving Paris hospital networks and Lyon pharmaceutical clusters.
Product Type:
Instruments turn over slowest at 7-10 year replacement cycles, while reagents deplete monthly and software licenses renew annually, fragmenting vendor cash flow profiles across the installed base.
- Instruments:Cell analyzers and sorters represent capital-intensive hardware requiring CE-IVDR certification under ANSM oversight. Academic medical centers in Strasbourg prioritize spectral detection platforms capable of 40-parameter panels for translational immuno-oncology programs.
- Reagents:Fluorochrome-conjugated antibodies and calibration beads constitute recurring consumable demand. Clinical laboratories in Marseille face supply vulnerability from concentrated dye chemistry sourcing in Germany and the United States.
- Software:AI-assisted gating algorithms and cloud-based data management tools are expanding most quickly as CNIL-compliant platforms gain preference for multi-site collaboration.
- Analytical:Population analysis and compensation calculation modules integrate with laboratory information systems through HL7 protocols, extending deployment timelines in legacy hospital environments.
Reagents anchor the volume base while software gains share at the steepest rate.
End User:
Customer archetypes diverge sharply in procurement authority and technical sophistication, with pharmaceutical buyers demanding research-grade parameter depth while clinical operators prioritize regulatory compliance and throughput.
- Clinical Laboratories:Hospital-based hematology and immunology departments drive diagnostic utilization under ANSM reimbursement frameworks. Operators in Toulouse struggle with specialized cytometrist recruitment for complex panel design.
- Pharmaceutical Companies:Lyon-based cell therapy developers pull high-parameter instruments and reagent volumes for immuno-oncology trial workflows. These buyers prioritize automated sample preparation to reduce technician dependency.
- Research Institutions:Academic centers within the Île-de-France cluster access public funding for cell-based analysis infrastructure under France's national biomedical research strategy.
- Biotechnology Firms:Emerging therapeutic developers in Bordeaux and Montpellier adopt full-spectrum platforms that collapse distinctions between research and clinical instrumentation.
Clinical laboratories dominate installed base value while pharmaceutical companies expand procurement fastest.
Component:
Hardware subsystems vary in failure rates and service contract attach rates, with lasers requiring precision alignment and fluidics demanding preventive maintenance protocols.
- Laser:Solid-state excitation sources at 488nm and 640nm wavelengths enable simultaneous fluorochrome excitation. Replacement cycles accelerate in high-throughput Paris hospital laboratories running extended daily operations.
- Detectors:Photomultiplier tubes and avalanche photodiodes capture scattered light and fluorescence emissions at event rates exceeding 10,000 per second.
- Flow Cell:Quartz cuvettes and microfluidic channels position cell streams at laser intersection points with hydrodynamic focusing precision.
- Fluidics System:Sheath fluid delivery and sample aspiration mechanisms require calibrated pressure regulation for consistent event rates across operator shifts.
Laser subsystems generate the highest service revenue intensity while detector technology evolves fastest.
Application:
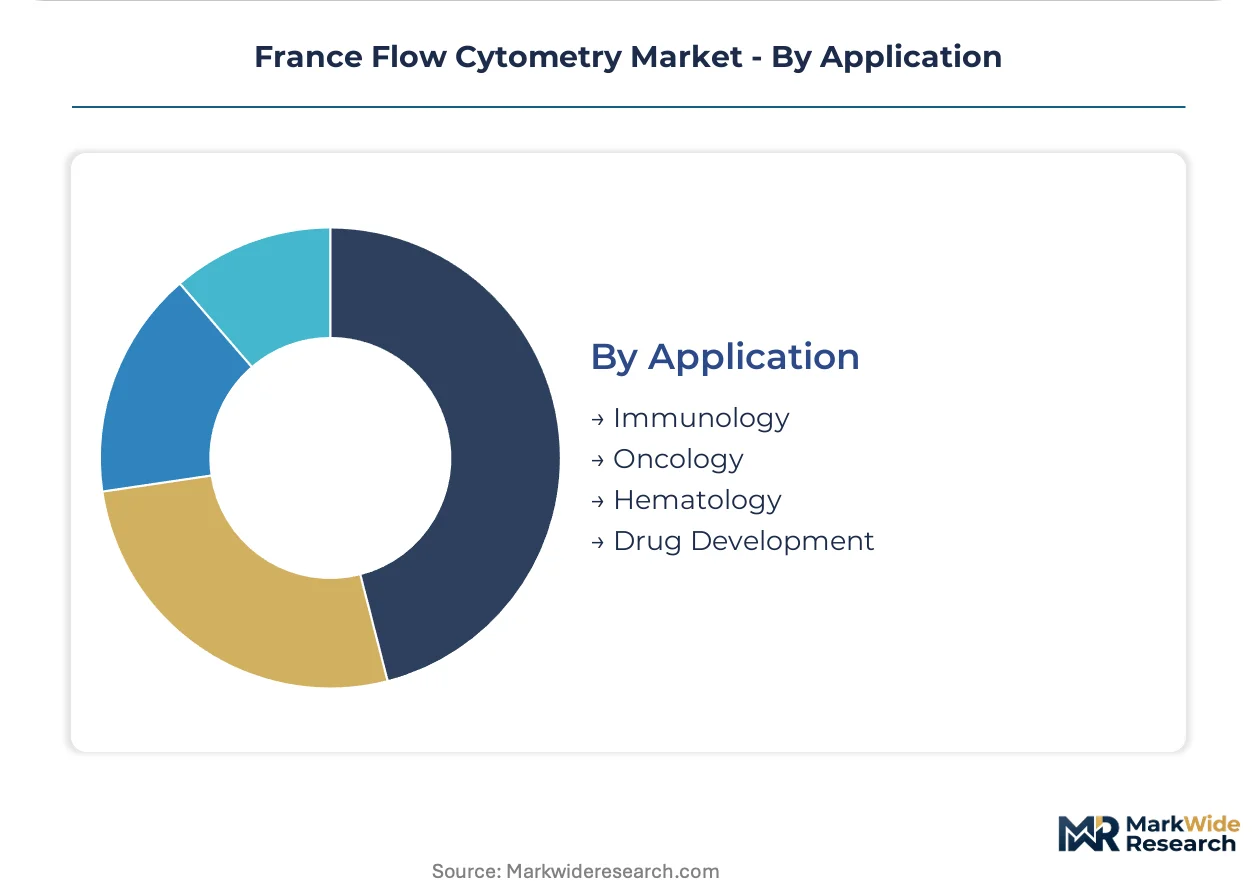
Disease-area concentration shapes reagent panel standardization, with leukemia diagnostics driving protocol harmonization while drug development demands customizable assay flexibility.
- Oncology:Leukemia and lymphoma immunophenotyping protocols dominate clinical utilization in Paris and Lyon hospital networks. BD's deep clinical validation in hematology diagnostics sustains competitive positioning.
- Immunology:T-cell subset enumeration and cytokine profiling support autoimmune disease monitoring and transplant rejection surveillance.
- Hematology:CD34+ stem cell quantification and reticulocyte analysis anchor routine diagnostic workflows in regional hospital laboratories.
- Drug Development:Cell therapy potency assays and biomarker detection panels pull instrument utilization in pharmaceutical company R&D facilities.
Oncology anchors the volume base while drug development climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's flow cytometry consumption concentrates in clinical diagnostics while research applications drive faster replacement cycles in the Île-de-France cluster. Regional procurement patterns diverge sharply between Paris hospital networks prioritizing regulatory compliance and Lyon pharmaceutical developers demanding research-grade parameter depth.
Île-de-France
Paris hospital laboratories anchor diagnostic instrument demand under ANSM reimbursement frameworks. The EU Medical Device Regulation transition accelerates platform replacement with CE-IVDR certified systems. Academic medical centers within the Paris-Saclay cluster deploy spectral detection architectures for translational immuno-oncology programs.
Auvergne-Rhône-Alpes
Lyon-based cell therapy developers pull high-parameter panels for pharmaceutical R&D workflows. France's national biomedical research strategy directs public funding toward cell-based analysis infrastructure in this cluster. Automated sample preparation systems reduce operator dependency in high-throughput clinical trial settings.
Provence-Alpes-Côte d'Azur
Regional hospital laboratories in Marseille face specialized cytometrist recruitment challenges for complex panel design. Independent third-party service providers capture maintenance contracts through faster response times than original equipment manufacturers. CNIL data governance frameworks shape vendor selection for multi-site collaboration platforms.
Nouvelle-Aquitaine
Bordeaux biotechnology firms adopt full-spectrum platforms collapsing distinctions between research and clinical instrumentation. Emerging therapeutic developers prioritize vendors with established MDR regulatory infrastructure. Local procurement channels favor systems qualifying for both diagnostic use and translational research applications.
Occitanie
Toulouse clinical laboratories struggle with legacy LIS integration extending deployment cycles for new instrument installations. Regional service networks offer flexible pricing structures pressuring manufacturer aftermarket margins. Public research institutions access national funding streams for flow cytometry infrastructure under cell-based analysis priorities.
France Flow Cytometry Market Vendor Landscape
Capability concentration sits with diversified life sciences conglomerates; scale advantage sits with specialized diagnostic instrument manufacturers. The vendor base organizes into three tiers: multinational conglomerates leveraging consumables portfolios, dedicated cytometry specialists, and emerging platform developers. Consolidation pressure intensifies as bundled reagent contracts displace standalone instrument sales. Strategic moves center on regulatory infrastructure investment and automated workflow integration.
Within the diversified conglomerate tier, Danaher and Thermo Fisher Scientific exemplify players capturing lifetime value through consumables lock-in. BD occupies a position as a clinical validation anchor in hematology diagnostics. Sysmex Corporation represents the automated workflow specialization archetype with reduced operator dependency positioning.
| Leading Market Players |
|---|
| Danaher |
| BD |
| Sysmex Corporation |
| Agilent Technologies |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Beckman Coulter |
| Merck KGaA |
| Miltenyi Biotec |
| Others |
Supply Flow & Price Mechanics
Single-source fluorophore dependency in Germany and the United States compresses pricing flexibility across reagent tiers while forcing French laboratories into long-term procurement commitments that reshape inventory strategies and vendor lock-in patterns.
Pricing Analysis
Long-term bundled reagent contracts dominate the French market as Danaher and BD lock hospital laboratories into multi-year consumable commitments. Pricing stratifies across CE-IVDR certified premium systems, validated clinical platforms, and research-grade instruments with variable after-sales support. Cost compression in the standard tier intensifies because independent third-party service providers undercut manufacturer maintenance rates. Pharmaceutical companies in Lyon show least price sensitivity due to cell therapy trial budgets, while regional hospital laboratories in Marseille and Toulouse face acute budget constraints.
Supply Chain Analysis
Contract manufacturing for flow cytometry instruments concentrates in Germany, the United States, and Japan where precision optical component foundries maintain capacity. Laser excitation modules and photomultiplier tubes draw from specialized semiconductor fabrication facilities in these jurisdictions. Single-source vulnerability runs through concentrated dye chemistry suppliers in Bavaria and Massachusetts. Distribution runs through authorized dealer networks serving Paris hospital procurement consortia and direct pharmaceutical accounts in Lyon.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France flow cytometry market is in a cyclical recovery phase as ANSM's MDR transition forces replacement of legacy platforms and unlocks capital expenditure cycles deferred during regulatory uncertainty.
For Market Incumbents: Entrench position by deepening reagent portfolio bundling to capture lifetime value from installed bases in Paris hospital networks. Accelerate AI-assisted gating software development to defend against emerging platform developers targeting the fastest-growing product segment. Prioritize MDR regulatory infrastructure investment to maintain competitive access against newer entrants lacking CE-IVDR certification experience.
For New Entrants and Emerging Players: Build out presence in automated sample preparation workflows where Sysmex Corporation has established proof points but market penetration remains incomplete. Target biotechnology firms in Bordeaux and Montpellier adopting full-spectrum platforms that collapse research-clinical distinctions. Pursue cloud-based data management partnerships with CNIL-compliant architectures as the primary go-to-market angle.
For Investors and Strategic Acquirers: ANSM's EUDAMED reporting requirements reshape the acquisition landscape by privileging vendors with established post-market surveillance infrastructure. The 5-10 year viability window favors platforms with diagnostic and research dual-use qualification. Target acquisition archetypes include spectral detection technology specialists and automated liquid handling integrators. Monitor CE-IVDR certification timelines as the critical inflection signal for platform replacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Certification Pathway | ANSM registration unlocks hospital laboratory reimbursement eligibility in Paris networks. |
| Reagent Portfolio Bundling | Consumables lock-in captures recurring revenue from installed bases across Île-de-France. |
| AI-Assisted Gating Development | Machine learning algorithms address specialized cytometrist shortages in Marseille and Toulouse. |
| Automated Sample Preparation Integration | Robotic liquid handling reduces technician dependency in Lyon pharmaceutical trial workflows. |
| CNIL-Compliant Cloud Architecture | Data governance frameworks differentiate vendors for multi-site collaboration in Provence-Alpes-Côte d'Azur. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital laboratory directors, biomedical engineers, pharmaceutical R&D heads, and cytometry specialists. Secondary validation drew from ANSM regulatory filings, EUDAMED device registrations, hospital procurement databases, and EU Medical Device Regulation transition guidance documents. Bottom-up instrument and reagent volume estimates triangulated against top-down market sizing from national health technology assessment records.
Calibration against historical replacement cycles and MDR implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-user archetype, application area, and regional cluster within France. CAGRs were derived from instrument installation trajectories and consumable pull-through rates. Forecast inputs incorporated spectral detection adoption curves and automated workflow penetration in pharmaceutical settings.
Sensitivities concentrate around ANSM enforcement timelines for legacy platform decommissioning and fluorophore supply disruptions from German and United States manufacturers. Forecasts reflect assumptions about MDR transition completion and public funding continuity for Île-de-France research infrastructure. Quarterly review of CE-IVDR certification backlogs and hospital capital expenditure approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Transfection Market
Biomedical Technology
Needle Based Biopsy Guns Market
Biomedical Technology
Cell Separation Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
Global Exosome Research Products Market
Biomedical Technology
Macrophage Marker Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Global Expression Vectors Market
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
Global Cell Signaling Market
Biomedical Technology
Vaccine Technology Market
Biomedical Technology
Biochips Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Latin America Flow Cytometry Market