
 Inhalable Biologics Market | 2026-2036
Inhalable Biologics Market Size, Share, and Industry Trends Forecast 2026-2036
Inhalable Biologics Market Analytics
Hospital procurement of inhalable biologics is narrowing around a smaller set of suppliers with validated cold-chain and aerosolization capabilities. AstraZeneca leverages its respiratory franchise to anchor pulmonary biologic development across multiple therapeutic areas. Boehringer Ingelheim sustains manufacturing scale in soft mist and dry powder platforms that accommodate complex protein structures. MannKind Corporation specializes in Technosphere-based dry powder formulation, a technology that differentiates its approach to peptide and protein stabilization.
Inhalable biologics comprise therapeutic proteins, peptides, monoclonal antibodies, and vaccines engineered for pulmonary deposition via nebulization, dry powder inhalers, metered-dose inhalers, or soft mist inhalers, with particle size distributions typically targeting one to five microns for optimal alveolar absorption and systemic bioavailability. Monoclonal antibodies dominate current development pipelines due to their therapeutic potency in respiratory disorders, while vaccines represent the fastest-expanding product category as developers pursue mucosal immunity advantages over parenteral administration. Dry powder inhalers capture the largest share of delivery mode investment, though nebulization retains critical utility in hospital settings where ventilator-compatible administration determines clinical adoption.
FDA oversight of inhaled protein immunogenicity, combined with EMA requirements for demonstrating comparable bioavailability to subcutaneous routes, shapes clinical trial design and market access timelines for new entrants. The EU MDR and FDA's evolving quality-by-design expectations for complex drug-device combinations are forcing developers to integrate human factors engineering earlier in product development. Stakeholders must monitor how regulator convergence on inhaled biologic standards affects portfolio prioritization and partnership strategies across the development cycle.
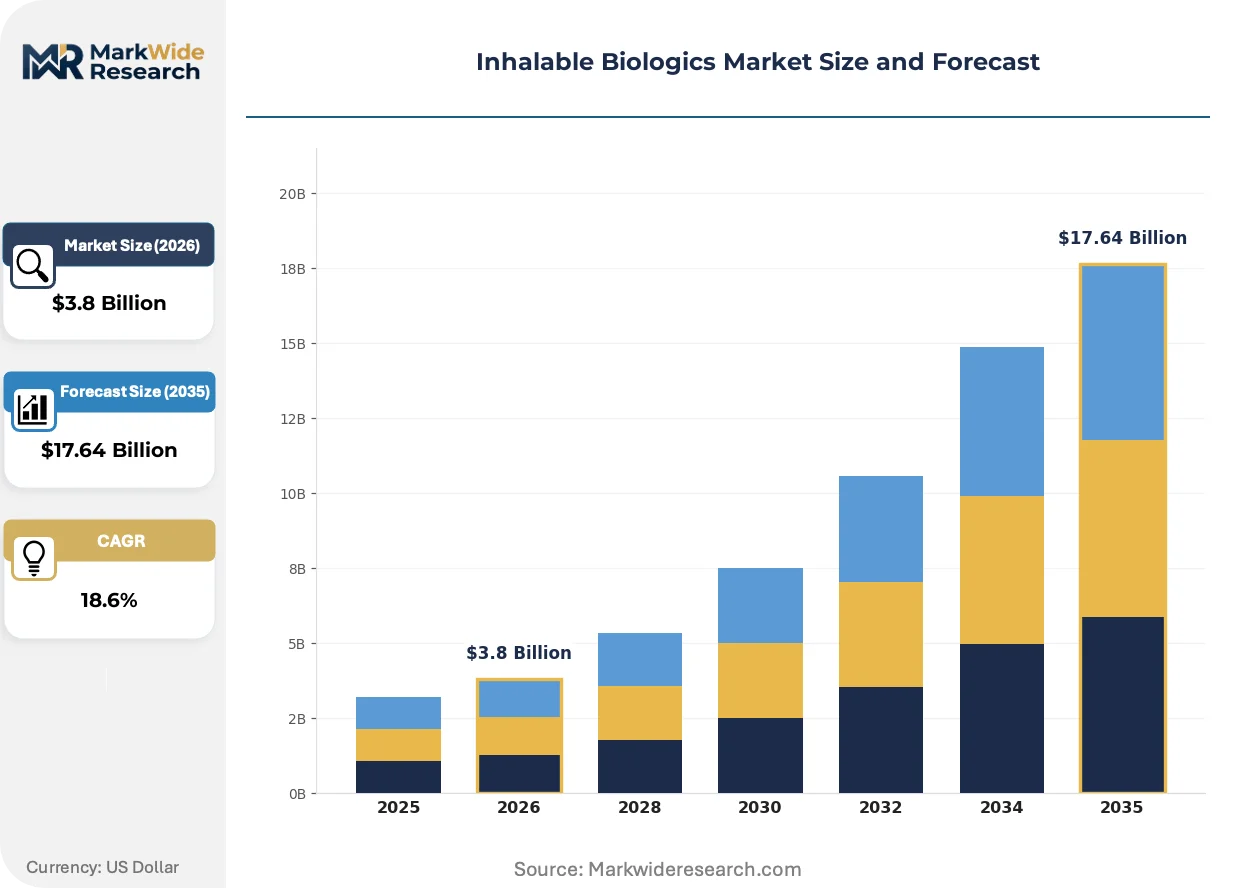
Market Dynamics
FDA's advancing guidance on inhaled protein stability is compressing development timelines while forcing developers to resolve immunogenicity questions earlier in clinical programs. This regulatory pressure is reshaping partnership strategies between biologic innovators and specialized aerosolization platform owners.
Growth Catalysts
- Home care migration:Patients managing chronic respiratory conditions seek self-administered alternatives to parenteral biologics, expanding addressable populations beyond hospital-dependent therapies.
- EMA bioequivalence pathways:The agency's framework for demonstrating comparable bioavailability to subcutaneous routes accelerates market access timelines for pulmonary delivery innovators.
- Dry powder engineering:Technosphere and lipid-based stabilization technologies enable peptide and protein preservation without cold-chain dependency, unlocking distribution to resource-limited settings.
Market Restraints
- Alveolar deposition physics:Achieving consistent one-to-five micron particle size distributions across manufacturing batches requires specialized spray-drying equipment with limited vendor base.
- Immunogenicity surveillance burden:FDA mandates for anti-drug antibody monitoring in pulmonary protein trials extend clinical program durations and inflate safety database requirements.
- Device-biologic interdependence:Complex drug-device combination regulations under EU MDR force redundant validation cycles when either component changes, locking formulations to specific inhaler platforms.
Strategic Opportunities
- Mucosal vaccine delivery:Developers exploit pulmonary immune induction advantages over intramuscular routes for respiratory pathogen vaccines, targeting stockpiling contracts from national health agencies.
- Soft mist nebulization:Ventilator-compatible aerosol generation captures intensive care unit demand for biologic delivery in mechanically ventilated patients with acute respiratory distress.
- Quality-by-design integration:Early human factors engineering incorporation reduces late-stage device failures, differentiating sponsors in FDA pre-submission negotiations.
Industry Challenges
- Aerosol engineering talent scarcity:Cross-disciplinary expertise spanning protein chemistry, fluid dynamics, and pulmonary physiology concentrates in limited academic and industrial clusters.
- Cold-chain infrastructure gaps:Validated temperature-controlled distribution for nebulized biologics requires capital deployment in secondary markets where hospital pharmacy capabilities remain underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inhalable Biologics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Peptides, Proteins, Vaccines Delivery Mode: Nebulization, Metered-Dose Inhalers, Dry Powder Inhalers, Soft Mist Inhalers End User: Hospitals, Home Care, Clinics, Research Laboratories Application: Respiratory Disorders, Infectious Diseases, Allergies, Cancer Therapy |
| Companies Covered | AstraZeneca, F. Hoffmann-La Roche Ltd, Boehringer Ingelheim, MannKind Corporation, Aridis Pharmaceuticals, Inc., Inhalon Biopharma, Inc., CanSino Biologics, Kamada Pharmaceuticals, GSK plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inhalable Biologics Market Evolving Landscape
Formulation science is converging with device engineering to overcome historical barriers to protein stability in pulmonary environments. Developers now prioritize platforms that eliminate the need for refrigerated storage throughout distribution.
Technosphere dry powder technology is hybridizing protein stabilization with patient-friendly inhalation profiles. MannKind's platform anchors this approach, enabling room-temperature storage of peptides previously requiring cold-chain handling. Hospital systems adopting these formulations reduce pharmacy infrastructure costs while expanding ambulatory care eligibility for biologic therapies.
EU MDR implementation is forcing earlier integration of human factors validation into combination product development. The regulation's emphasis on use-error reduction in critical drug delivery is extending design verification timelines by twelve to eighteen months for sponsors lacking established respiratory device portfolios. European notified bodies are prioritizing submissions with robust clinical handling studies, advantaging developers with prior inhaler platform approvals.
Hospital procurement is consolidating supplier relationships around vendors with validated end-to-end aerosolization capabilities. IDN pharmacy directors now require demonstration of particle size consistency across temperature excursions and shelf-life periods, displacing fragmented sourcing of nebulizers and biologics from separate vendors. This concentration is most visible in United States academic medical centers where formulary committees wield centralized contracting authority.
Inhalable Biologics Market Segmentation
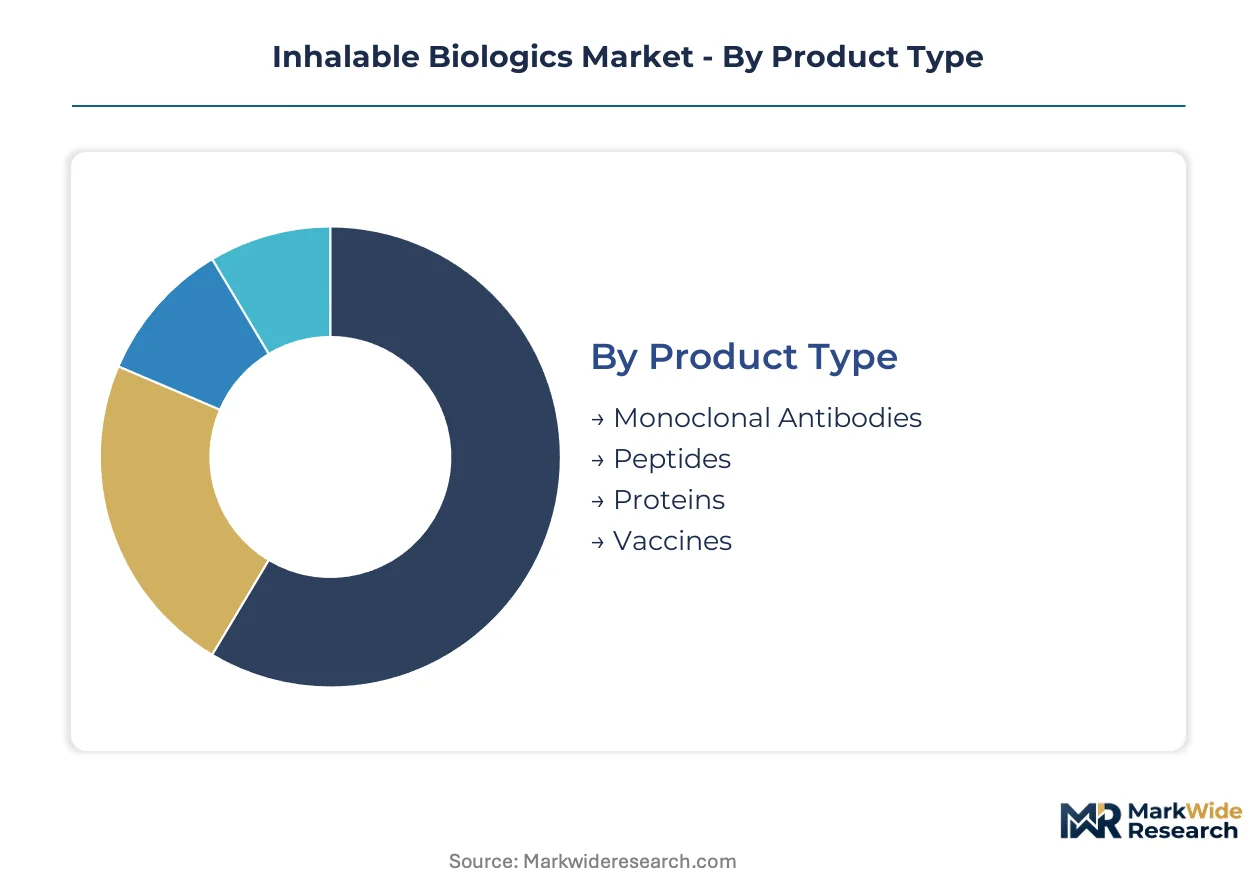
Segmentation in inhalable biologics reveals how formulation complexity, delivery physics, and care setting economics interact to determine commercial viability. Each dimension carries distinct regulatory burdens and capital requirements that reshape competitive entry points.
Product Type:
Monoclonal antibodies and vaccines occupy opposite ends of the development risk spectrum, with peptides and proteins filling intermediate positions based on molecular stability profiles.
- Monoclonal Antibodies:Large glycoprotein structures engineered for high-affinity target binding in respiratory and systemic indications. Hospital formulary committees in the United States concentrate procurement around validated cold-chain suppliers, with FDA immunogenicity surveillance requirements extending clinical program timelines.
- Vaccines:Antigen formulations exploiting pulmonary mucosal immunity induction for respiratory pathogens. National health agencies in France and Germany are stockpiling contracts for pandemic preparedness, with EMA bioequivalence pathways accelerating market access compared to novel therapeutic proteins.
- Peptides:Short-chain amino acid sequences requiring stabilization technologies to prevent degradation in humid pulmonary environments. Technosphere dry powder platforms enable room-temperature distribution, reducing pharmacy infrastructure costs.
- Proteins:Enzyme and cytokine formulations with intermediate molecular weights between peptides and antibodies. Spray-drying equipment constraints limit manufacturing scale for sub-five micron particle requirements.
Established volume favors monoclonal antibodies; emerging adoption favors vaccines.
Delivery Mode:
Device selection locks formulations to specific patient populations based on coordination requirements, care setting infrastructure, and ventilation compatibility.
- Dry Powder Inhalers:Breath-actuated systems eliminating propellant requirements and enabling compact portable designs. Home care adoption in the United States concentrates around patient-friendly inhalation profiles with reduced coordination demands.
- Nebulization:Continuous aerosol generation compatible with mechanical ventilation circuits in intensive care units. Hospital procurement in Germany requires validated particle size consistency across temperature excursions for ventilator-compatible administration.
- Metered-Dose Inhalers:Pressurized systems delivering fixed-dose aerosol plumes requiring hand-breath coordination. EU F-Gas Regulation phase-downs are forcing propellant reformulation investments.
- Soft Mist Inhalers:Mechanical spring systems generating slow-moving aerosol clouds with reduced oropharyngeal deposition. Boehringer Ingelheim's manufacturing scale accommodates complex protein structures in this platform.
Hospital dependence sustains nebulization; ambulatory expansion drives dry powder inhalers.
End User:
Care setting migration from institutional to self-administered delivery reconfigures reimbursement pathways and pharmacy infrastructure requirements.
- Hospitals:Centralized pharmacy operations with validated cold-chain and aerosolization capabilities. United States academic medical centers are consolidating supplier relationships around end-to-end platform vendors.
- Home Care:Self-administered alternatives to parenteral biologics expanding addressable populations beyond hospital-dependent therapies. Technosphere stabilization eliminates refrigeration requirements for room-temperature distribution.
- Clinics:Outpatient facilities with intermediate pharmacy capabilities between hospitals and home settings. Reimbursement pathways in France favor clinic-administered biologics for patient monitoring requirements.
- Research Laboratories:Early-phase clinical trial sites requiring flexible formulation batch sizes. EU MDR human factors engineering mandates extend design verification timelines for sponsors.
Institutional procurement dominates current revenue; home care settings are climbing the fastest.
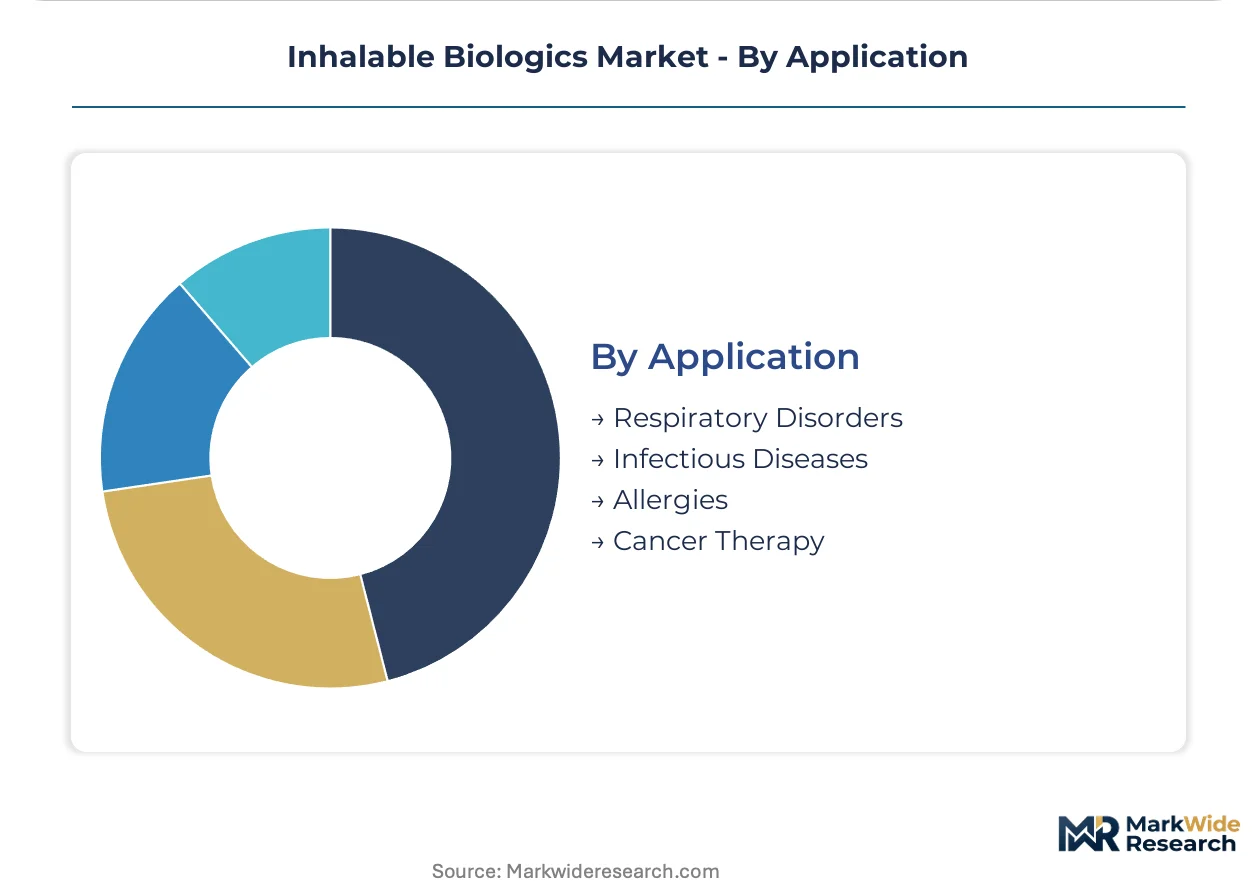
Application:
Therapeutic area selection determines regulatory precedent availability, biomarker validation requirements, and competitive intensity in clinical development.
- Respiratory Disorders:Asthma, COPD, and cystic fibrosis indications with established pulmonary delivery precedent. AstraZeneca leverages its respiratory franchise to anchor biologic development across multiple therapeutic areas.
- Infectious Diseases:Antiviral and antibacterial biologics targeting respiratory pathogens. Mucosal immunity advantages over intramuscular routes are attracting national stockpiling contracts.
- Allergies:Immunomodulatory proteins for allergic rhinitis and asthma prevention. EMA requirements for demonstrating comparable bioavailability to subcutaneous routes shape trial design.
- Cancer Therapy:Inhaled immunotherapy and targeted agents for lung and metastatic disease. FDA advancing guidance on inhaled protein stability is compressing development timelines for oncology applications.
Respiratory disorders anchor near-term revenue; infectious disease applications show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on inhaled protein stability accelerates United States development timelines, while EMA bioequivalence frameworks compress European market access. National stockpiling programs in France and Germany expand vaccine procurement. Cold-chain infrastructure gaps in secondary markets constrain distribution reach.
United States
Academic medical centers consolidate supplier relationships around end-to-end aerosolization platforms. FDA immunogenicity surveillance mandates extend clinical program durations and inflate safety database requirements. The Boston-Cambridge biotech corridor anchors pulmonary biologic development, with AstraZeneca leveraging its respiratory franchise across multiple therapeutic areas.
Germany
Hospital procurement requires validated particle size consistency across temperature excursions for ventilator-compatible administration. EMA bioequivalence pathways for demonstrating comparable bioavailability to subcutaneous routes accelerate market access timelines. The Rhine-Main industrial cluster concentrates soft mist inhaler manufacturing scale that accommodates complex protein structures.
France
Reimbursement pathways favor clinic-administered biologics for patient monitoring requirements. ANSM oversight of inhaled protein immunogenicity shapes clinical trial design for new entrants. The Paris-Saclay research cluster drives mucosal vaccine delivery development, with national health agencies stockpiling contracts for pandemic preparedness.
United Kingdom
Post-Brexit regulatory divergence from EMA frameworks creates parallel submission requirements for pulmonary delivery innovators. MHRA quality-by-design expectations for complex drug-device combinations force earlier human factors engineering integration. The Oxford-Cambridge-London golden triangle anchors respiratory biologic R&D, with GSK plc maintaining formulation expertise in the region.
China
NMPA advancing guidance on inhaled protein stability mirrors FDA compression of development timelines. Domestic manufacturers exploit Technosphere dry powder platforms for room-temperature distribution without cold-chain dependency. The Yangtze River Delta biopharma corridor concentrates peptide stabilization technology development, with CanSino Biologics anchoring mucosal vaccine innovation.
Inhalable Biologics Market Competitive Landscape
On the supply side, the industry is consolidating around respiratory-focused pharmaceutical conglomerates with validated aerosolization capabilities and specialized biotech platforms with proprietary stabilization technologies. The competitive terrain stratifies into three archetypes: large-cap respiratory franchise holders, mid-cap platform technology specialists, and emerging clinical-stage developers pursuing mucosal delivery. Dominant competitive moves include strategic partnerships between biologic innovators and specialized aerosolization platform owners, plus capacity expansion in spray-drying equipment for sub-five micron particle manufacturing.
Within the respiratory franchise tier, AstraZeneca and Boehringer Ingelheim exemplify supply-side consolidation, leveraging decades of pulmonary device expertise to anchor biologic development across therapeutic areas. MannKind Corporation occupies a distinct position as a platform technology specialist, with its Technosphere dry powder formulation representing an archetype of protein stabilization without cold-chain dependency. Among clinical-stage developers, Aridis Pharmaceuticals, Inc. and Inhalon Biopharma, Inc. sit within the emerging mucosal delivery vector, pursuing pulmonary immune induction advantages for respiratory pathogen vaccines.
| Leading Market Players |
|---|
| AstraZeneca |
| F. Hoffmann-La Roche Ltd |
| Boehringer Ingelheim |
| MannKind Corporation |
| Aridis Pharmaceuticals, Inc. |
| Inhalon Biopharma, Inc. |
| CanSino Biologics |
| Kamada Pharmaceuticals |
| GSK plc |
| Others |
Value Network & Pricing Analysis
Overcapacity in European spray-drying equipment installations is compressing contract manufacturing margins while concentrating pricing power among United States-based platform owners with validated Technosphere capabilities. This utilization asymmetry rewards suppliers with FDA-cleared stabilization technologies and penalizes commodity nebulization service providers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates validated cold-chain monoclonal antibody formulations from room-temperature peptide platforms and commodity nebulization services. Price differentiation rests on FDA immunogenicity clearance tier and manufacturing scale, with hospital procurement committees in Germany demanding volume discounts exceeding ambulatory clinic purchasers. Cost compression in the nebulization tier is intensifying because of EU MDR compliance investments. Academic medical centers exhibit lowest price sensitivity due to bundled device-biologic contracting authority.
Supply Chain Analysis
Contract manufacturing concentration sits with Boehringer Ingelheim's soft mist platform, MannKind's Technosphere facilities, and AstraZeneca's respiratory network across the United States, Germany, and United Kingdom. Raw material dependencies span pharmaceutical-grade lactose carriers, hydrofluoroalkane propellants, and recombinant protein feedstocks. Single-source vulnerability concentrates in specialized spray-drying equipment with limited qualified vendors. Distribution runs through validated cold-chain logistics for hospital-formulary biologics and ambient-temperature channels for Technosphere-enabled home care products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
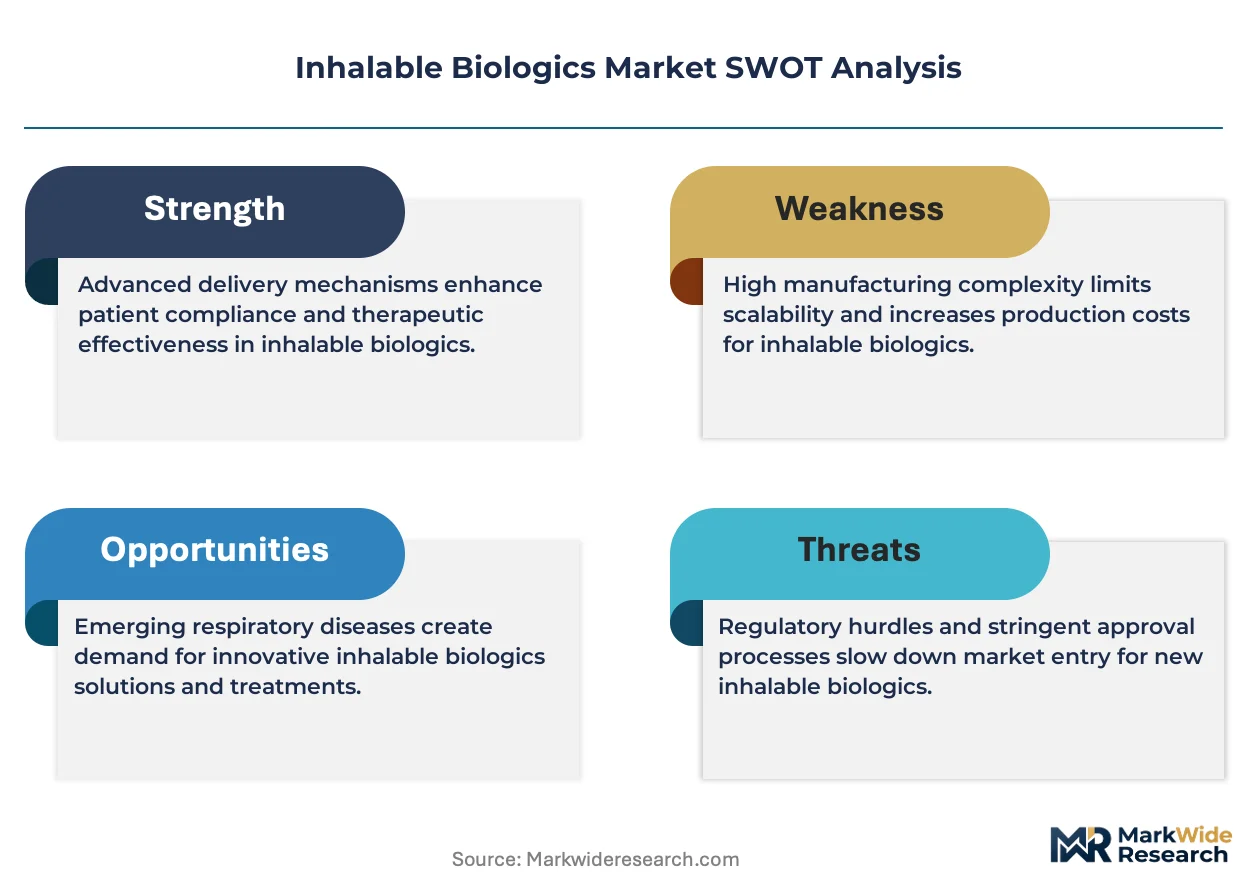
This market operates as a defensive-moat story anchored in regulatory entrenchment. FDA immunogenicity surveillance requirements and EU MDR device-biologic validation cycles create switching costs that protect incumbent platform positions.
For Market Incumbents: Harden regulatory entrenchment by deepening FDA quality-by-design submissions for combination products and expanding capacity in Technosphere dry powder manufacturing. The threat of NMPA-cleared Chinese competitors with cost-advantaged room-temperature platforms demands preemptive certification investment in secondary markets. Vertical integration into specialized spray-drying equipment ownership secures particle size consistency capabilities. For New Entrants and Emerging Players: Pursue mucosal vaccine delivery contracts from French and German national stockpiling programs as the most penetrable entry vector. Soft mist nebulization for ventilator-compatible intensive care administration represents underserved demand within hospital procurement. A go-to-market angle anchored in EMA bioequivalence pathway acceleration differentiates against incumbent timeline advantages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across dry powder inhaler platform development due to EU MDR human factors engineering mandates and specialized aerosolization talent scarcity. Long-term viability favors platform technology specialists with proprietary stabilization IP over single-product developers. The signal to watch is FDA pre-submission meeting outcomes for inhaled protein immunogenicity protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA pre-submission negotiations on inhaled protein stability compress development timelines for pulmonary biologics. |
| Manufacturing Scale-Up | Technosphere dry powder capacity expansion eliminates cold-chain dependency for peptide distribution to resource-limited settings. |
| Strategic Partnership | Biologic innovators partnering with specialized aerosolization platform owners share immunogenicity surveillance burdens. |
| Pipeline Diversification | Mucosal vaccine delivery development targets national health agency stockpiling contracts in France and Germany. |
| Hospital System Partnership | United States academic medical center formulary consolidation rewards end-to-end aerosolization capability demonstration. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions governing pulmonary biologic adoption trajectories. Primary interview findings triangulated against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue reconciliation validated segmentation outputs.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, delivery mode, end user, and application. CAGRs derived from epidemiological trend extrapolation, pricing trajectory analysis, and regulatory approval probability weighting. Forecast inputs incorporated EMA bioequivalence pathway evolution and NMPA guidance convergence on inhaled protein standards.
Sensitivities concentrate around FDA immunogenicity guidance revisions, EU MDR notified body capacity constraints, and cold-chain infrastructure deployment rates in secondary markets. Forecasts reflect assumptions on patient migration to home care settings and hospital procurement consolidation velocity. Quarterly review of regulatory pre-submission outcomes and GPO contract award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Liquid Biopsy Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Global Stem Cell Assay Market
Biomedical Technology
Global Biosimulation Market
Biomedical Technology
Vaccine Technology Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Latin America Flow Cytometry Market
Biomedical Technology
E2 Antibody Market
Biomedical Technology
Global Plant Stem Cell Market
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
US Liquid Biopsy Market
Biomedical Technology
Global Glycomics/Glycobiology Market
Biomedical Technology
Global Exosome Research Products Market
Biomedical Technology
Bacteriophage Market