
 Global Optogenetics Market | 2026-2036
Global Optogenetics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optogenetics Market Foresight
Academic neuroscience departments are gaining procurement share as pharmaceutical R&D budgets tighten, and the Global Optogenetics Market is bifurcating between basic research and translational therapeutic development. Thermo Fisher Scientific leverages its viral vector catalog to anchor reagent supply chains across North American and European institutions. Coherent Inc. specializes in solid-state laser architectures that dominate multiphoton excitation workflows. GenSight Biologics S.A. positions its gene therapy pipeline to navigate clinical translation from bench to ophthalmology trials.
Optogenetics denotes a biological technique employing light-sensitive proteins such as channelrhodopsin-2 to modulate targeted cell populations with millisecond temporal precision, primarily serving neuroscience investigation and emerging therapeutic intervention. Viral vectors lead product category volume due to established adeno-associated virus packaging protocols, while light delivery systems capture expanding share as implantable fiber-optic probes achieve chronic biocompatibility. Genetic constructs represent the fastest-growing segment as synthetic promoters enable cell-type-specific expression without transgenic breeding timelines.
FDA oversight of optogenetic gene therapies intensifies as Investigational New Drug applications incorporate phototoxicity risk assessments, while the EU MDR reclassifies active implantable optical devices under stricter conformity evaluation pathways. ISO 10993 biocompatibility standards now govern fiber-optic material selection for long-term neural interfaces. Stakeholders must monitor reimbursement policy evolution for optogenetic vision restoration procedures to anticipate commercial infrastructure investment timing.
Market Dynamics
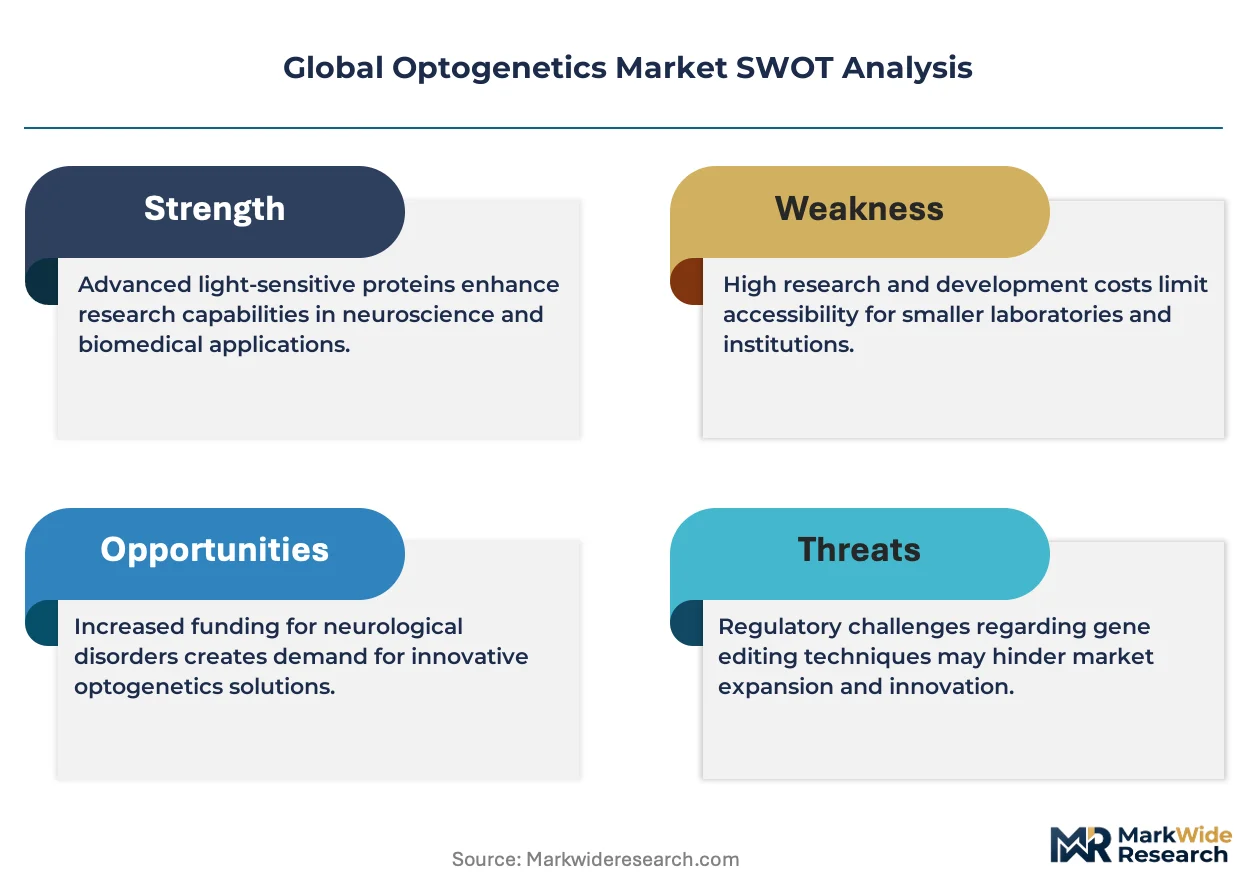
The optogenetics market pivots on the tension between viral vector supply scarcity and accelerating demand for cell-type-specific neural modulation tools across academic and clinical research institutions.
Growth Catalysts
- NIH BRAIN Initiative funding:Sustained federal appropriations for neural circuit mapping projects drive instrument procurement cycles at US academic medical centers, creating predictable replacement demand for laser systems and fiber-optic implants.
- EU MDR pathway clarification:The Medical Device Regulation's reclassification of active implantable optical devices provides conformity benchmarks that reduce regulatory uncertainty for light-delivery system manufacturers seeking CE marking.
- Channelrhodopsin variant engineering:Directed evolution of faster kinetics variants enables millisecond-precision inhibition protocols that expand addressable experimental questions beyond excitation-only workflows.
Market Restraints
- AAV packaging capacity limits:The 4.7 kilobase cargo constraint of adeno-associated virus serotypes restricts simultaneous delivery of multiple opsin constructs, forcing complex co-injection protocols that increase experimental variability.
- Phototoxicity risk accumulation:Chronic blue-light exposure in neural tissue generates reactive oxygen species that compromise cell viability, limiting longitudinal study designs and therapeutic application windows.
- Fiber-optic material biocompatibility:Silica-based implant materials trigger glial scarring responses that degrade optical transmission efficiency within months, necessitating repeated surgical interventions.
Strategic Opportunities
- Red-shifted opsin development:Longer-wavelength excitation spectra reduce phototoxicity and enable deeper tissue penetration, opening translational pathways for non-invasive cortical modulation that bypasses craniotomy requirements.
- Japan's regenerative medicine regulatory sandbox:The PMDA's conditional early approval framework for gene therapy products accelerates clinical validation timelines for optogenetic vision restoration candidates.
- Wireless power telemetry integration:Convergence of inductive charging microelectronics with sub-millimeter LEDs eliminates transcranial fiber tethering, enabling free-behavior neuroscience experiments previously constrained by cable artifacts.
Industry Challenges
- Cross-disciplinary talent scarcity:The intersection of neurobiology, optical physics, and viral vector engineering demands hybrid skill sets that remain underrepresented in both academic and commercial training pipelines.
- ISO 10993 certification timelines:Extended biocompatibility testing protocols for novel polymer cladding materials delay product launches by 18-24 months, compressing effective patent protection windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optogenetics Market |
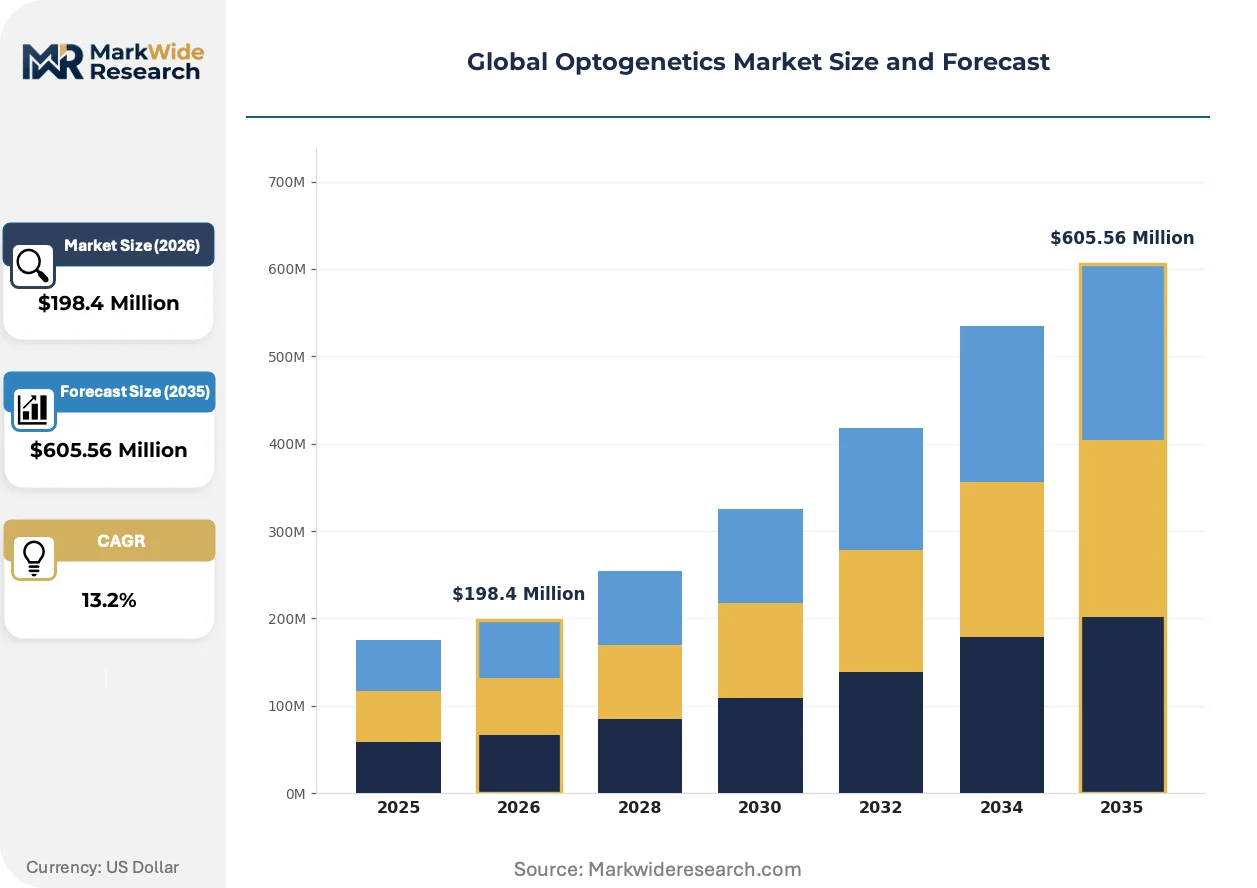
| Market Size in 2026 | $198.4 Million |
| Market Size in 2035 | $605.56 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optogenetic Tools, Light-Emitting Diodes, Fiber Optic Cables, Genetic Constructs Application: Neuroscience Research, Pain Management, Vision Restoration, Cardiac Arrhythmias End User: Research Laboratories, Academic Institutions, Pharmaceutical Companies, Clinical Research Organizations Technology: Viral Vectors, Transgenic Models, Light Delivery Systems, Microelectrode Arrays |
| Companies Covered | Thermo Fisher Scientific, Coherent Inc., Thorlabs Inc., NeuroNexus Technologies, GenSight Biologics S.A., Noldus Information Technology, Elliot Scientific Limited, Laserglow Technologies, Addgene, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optogenetics Market Shifts & Advancements
Optogenetics instrumentation converges toward minimally invasive form factors while regulatory frameworks mature to accommodate gene-therapy-device combination products. Three developments dominate the innovation landscape.
Red-shifted channelrhodopsin variants is supplanting blue-light excitation architectures in preclinical workflows. Stanford and MIT neurotechnology groups now standardize on Chrimson and bistable step-function opsins for dual-color independent modulation. The structural consequence is compression of multiphoton laser infrastructure requirements, as longer wavelengths permit lower-cost fiber-coupled diode systems to achieve comparable tissue penetration depths.
EU MDR Annex XVI expansion reclassifies software-controlled light-delivery systems as active implantable medical devices requiring notified body intervention. Manufacturers must now submit clinical evaluation reports demonstrating photothermal safety margins for chronic neural interfaces. German and French ophthalmology centers are consolidating procurement around vendors with established MDR technical documentation, marginalizing smaller laser system suppliers lacking regulatory affairs capacity.
Academic core facilities are consolidating reagent procurement through centralized viral vector production agreements rather than individual laboratory packaging contracts. This channel shift displaces small-batch AAV suppliers in favor of institutional-scale GMP manufacturing partnerships. The pattern is most visible at US Research I universities, where shared resource subsidies now cover 60-70 percent of per-investigator optogenetics reagent costs, flattening price sensitivity for premium serotype variants.
Global Optogenetics Market Segmentation
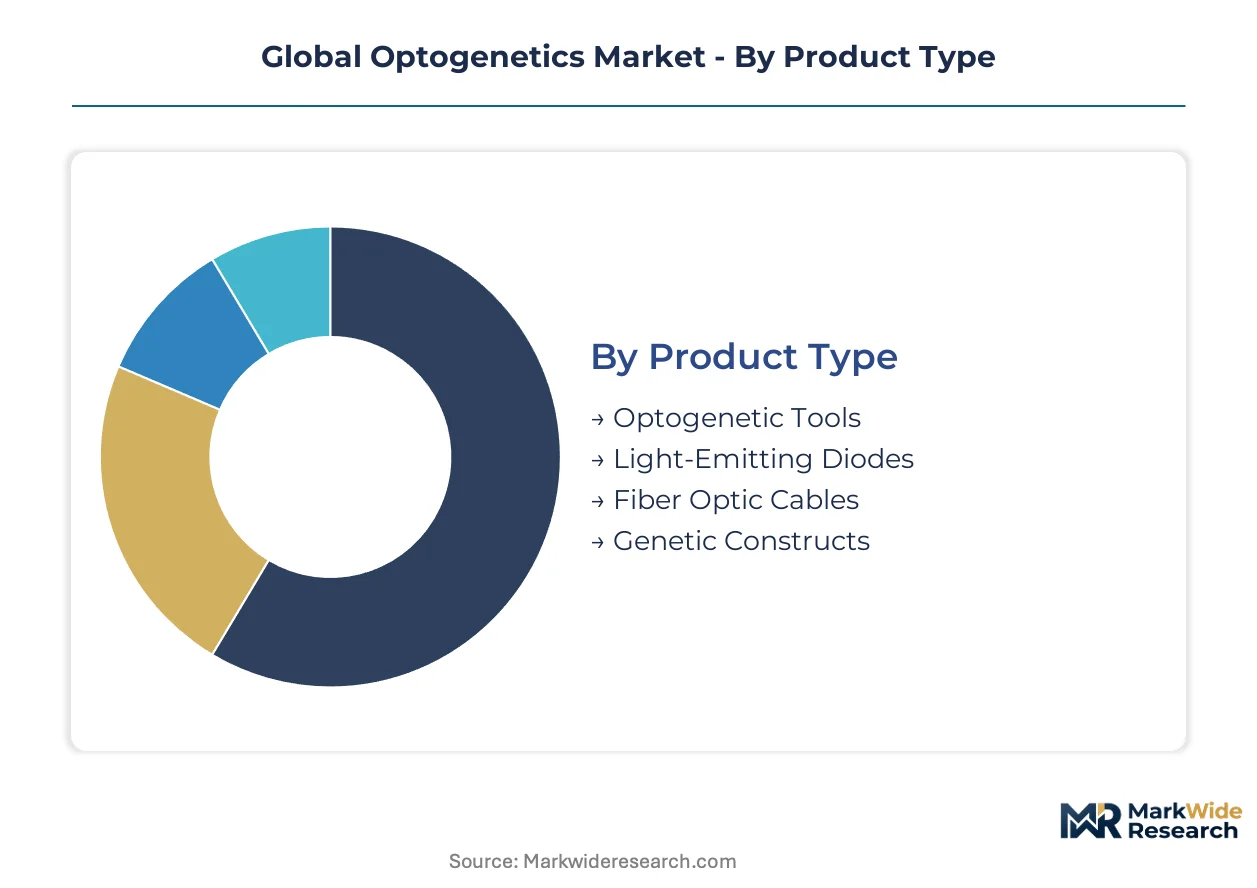
Optogenetics procurement flows through distinct channel architectures that reshape competitive positioning across reagent supply, instrumentation, and service delivery. Segmentation reveals where vendor consolidation concentrates versus where fragmentation persists.
Product Type:
Channel concentration varies sharply: viral vector tools flow through institutional core facilities, light-delivery hardware routes through capital equipment distributors, and genetic constructs increasingly source from centralized GMP manufacturing partnerships.
- Optogenetic Tools:Engineered opsin proteins and targeting vectors constitute the technical foundation of experimental workflows. Demand clusters at US Research I universities where NIH BRAIN Initiative subsidies cover 60-70 percent of per-investigator reagent costs, flattening price sensitivity for premium serotype variants.
- Light-Emitting Diodes:Solid-state illumination sources are displacing legacy laser architectures in budget-constrained laboratories. European academic medical centers favor fiber-coupled diode systems that achieve comparable tissue penetration at lower capital cost, compressing multiphoton infrastructure requirements.
- Fiber Optic Cables:Implantable silica probes with polymer cladding enable chronic neural interfaces. Glial scarring responses degrade optical transmission efficiency within months, necessitating repeated surgical interventions and recurring consumable demand.
- Genetic Constructs:Synthetic promoters and cell-type-specific expression cassettes eliminate transgenic breeding timelines. Expansion concentrates fastest here as CRISPR-assisted vector engineering shortens construct development cycles.
Optogenetic Tools dominate installed base. Genetic Constructs is where expansion concentrates.
Application:
Cost tier stratification separates exploratory neuroscience from regulated therapeutic development, with vision restoration commanding premium pricing due to clinical trial infrastructure requirements.
- Neuroscience Research:Circuit mapping and behavioral modulation studies constitute the volume foundation. Academic laboratories in Germany, France, and the United States drive instrument procurement cycles through sustained federal and EU framework program funding.
- Pain Management:Preclinical models target dorsal root ganglion modulation for chronic neuropathic conditions. Translation remains early-stage due to phototoxicity risk accumulation in peripheral nerve tissue.
- Vision Restoration:Retinal ganglion cell targeting for inherited retinal dystrophies represents the most advanced therapeutic pipeline. GenSight Biologics navigates PMDA's conditional early approval framework in Japan while pursuing EMA scientific advice for European market access.
- Cardiac Arrhythmias:Optogenetic pacing and defibrillation protocols address cardiac conduction disorders. Technical complexity of thoracic light delivery has limited commercial penetration relative to neural applications.
Neuroscience Research commands volume share. Vision Restoration captures margin expansion.
End User:
Customer type determines contract structure: academic institutions favor subsidized core facility access, pharmaceutical companies demand GMP-compliant viral vector supply, and clinical research organizations seek integrated device-gene therapy regulatory packages.
- Research Laboratories:Individual investigator groups maintain flexible procurement through small-batch AAV suppliers. Channel shift toward centralized institutional agreements is displacing this segment's traditional supply relationships.
- Academic Institutions:Shared resource subsidies now consolidate reagent procurement through GMP manufacturing partnerships. Stanford and MIT neurotechnology groups exemplify this pattern, standardizing on Chrimson and step-function opsin variants through core facility distribution.
- Pharmaceutical Companies:Tightened R&D budgets are compressing internal optogenetics capabilities, creating outsourcing demand for contract viral vector production and preclinical study execution.
- Clinical Research Organizations:EU MDR Annex XVI reclassification requires notified body intervention for active implantable optical device trials. CROs with established MDR technical documentation capacity are consolidating procurement relationships.
Academic Institutions anchor volume throughput. Clinical Research Organizations present the steepest expansion trajectory.
Technology:
Maturity gradients separate established viral vector protocols from emerging wireless and microelectrode integration platforms that remain precommercial.
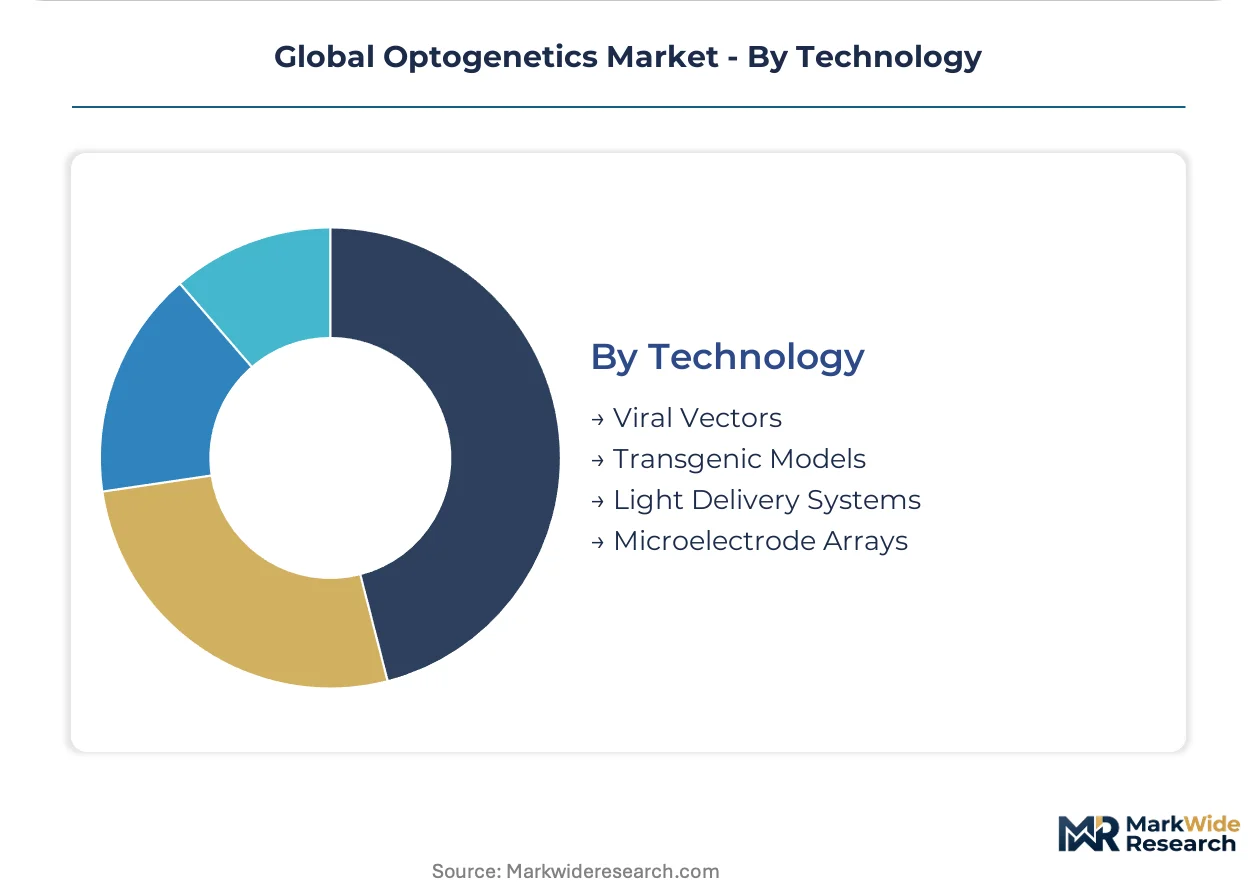
- Viral Vectors:Adeno-associated virus packaging protocols lead product category volume. The 4.7 kilobase cargo constraint restricts simultaneous delivery of multiple opsin constructs, forcing complex co-injection protocols.
- Transgenic Models:Germline modification approaches persist for stable cell-type-specific expression. Breeding timeline disadvantages are accelerating displacement by viral vector alternatives.
- Light Delivery Systems:Implantable fiber-optic probes and wireless LED microdevices achieve chronic biocompatibility. Inductive charging microelectronics with sub-millimeter LEDs eliminate transcranial fiber tethering.
- Microelectrode Arrays:Combined electrophysiological recording and optical stimulation platforms enable closed-loop modulation. Integration complexity limits deployment to specialized neurotechnology laboratories.
Viral Vectors dominate technical deployment. Light Delivery Systems is where innovation investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Viral vector manufacturing clusters and NIH-funded neurotechnology centers concentrate optogenetics supply and demand in discrete geographic nodes. Academic procurement subsidies and regulatory pathway maturity determine where commercial infrastructure investment flows.
United States
Stanford and MIT neurotechnology groups drive opsin variant standardization through core facility distribution networks. The FDA intensifies Investigational New Drug oversight for optogenetic gene therapies with mandatory phototoxicity risk assessments. Greater Boston anchors viral vector GMP manufacturing partnerships that supply institutional-scale reagent agreements.
Germany
Heidelberg and Munich academic medical centers consolidate procurement around vendors with established EU MDR technical documentation capacity. The EU Medical Device Regulation reclassifies active implantable optical devices under stricter conformity evaluation pathways requiring notified body intervention. Baden-Württemberg laser system manufacturers face margin pressure from fiber-coupled diode alternatives.
Japan
The PMDA's conditional early approval framework for gene therapy products accelerates clinical validation timelines for vision restoration candidates. METI-funded neurotechnology programs sustain instrument procurement at University of Tokyo and RIKEN Brain Science Institute. Kansai region ophthalmology centers pioneer non-invasive cortical modulation protocols using red-shifted opsin architectures.
United Kingdom
Cambridge and Oxford neuroscience departments expand optogenetics budgets as channelrhodopsin engineering improves targeting precision. The Medicines and Healthcare products Regulatory Agency aligns with EMA scientific advice pathways for combination device-gene therapy products. London-based contract research organizations build MDR technical documentation capacity for EU clinical trial expansion.
France
Paris-Saclay neurotechnology clusters standardize on Chrimson and step-function opsin variants for dual-color modulation workflows. ANSM enforces photothermal safety margin requirements for chronic neural interface trials. Lyon ophthalmology centers participate in GenSight Biologics' European market access strategy through EMA scientific advice engagement.
Global Optogenetics Market Competitive Landscape
Concentration sits with diversified life science conglomerates and specialized photonics manufacturers. The vendor base stratifies between institutional-scale reagent suppliers and precision instrumentation fabricators. Three archetypes dominate: viral vector catalog providers, solid-state laser architects, and gene therapy-device combination developers. Competitive moves center on GMP manufacturing partnerships and regulatory affairs capacity building.
Among diversified reagent suppliers, Thermo Fisher Scientific anchors institutional procurement relationships through viral vector catalog breadth. Coherent Inc. and Thorlabs Inc. occupy positions in the photonics tier, with the former representing solid-state laser specialization and the latter exemplifying fiber-optic component integration. GenSight Biologics S.A. sits within the clinical translation archetype, navigating combination product pathways.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Coherent Inc. |
| Thorlabs Inc. |
| NeuroNexus Technologies |
| GenSight Biologics S.A. |
| Noldus Information Technology |
| Elliot Scientific Limited |
| Laserglow Technologies |
| Addgene |
| Others |
Supply & Pricing Matrix
AAV packaging facility utilization rates above 85 percent at Greater Boston GMP sites create scale economies that compress per-dose viral vector costs while establishing price floors for boutique serotype variants. This concentration dynamic simultaneously elevates procurement leverage for institutional-scale buyers and marginalizes small-batch academic suppliers.
Pricing Analysis
Volume-discount tiering structures separate institutional core facility agreements from individual laboratory spot purchases. Pricing stratifies across GMP-certified, research-grade, and custom-engineered vector tiers, with FDA master file status commanding substantial premiums. Cost compression in fiber-coupled diode systems is intensifying because European academic medical centers favor lower-capital alternatives to multiphoton lasers. Pharmaceutical companies exhibit lowest price sensitivity due to therapeutic development timelines, while individual research laboratories face flattening NIH subsidy coverage.
Supply Chain Analysis
The United States and Germany anchor viral vector GMP manufacturing, while Japan and Taiwan concentrate optoelectronic component fabrication for wireless LED microdevices. Raw material dependencies center on recombinant plasmid DNA, high-purity silica fiber preforms, and indium gallium nitride epitaxial wafers. Single-source vulnerability in AAV serotype-specific packaging cell lines creates supply interruption risk for specialized constructs. Distribution runs through institutional procurement consortia rather than traditional laboratory supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optogenetics market sits in early-cycle expansion as red-shifted opsin variants unlock non-invasive therapeutic modalities previously blocked by craniotomy requirements and phototoxicity constraints.
For Market Incumbents: Fortify GMP manufacturing partnerships against emerging contract viral vector specialists by securing exclusive access to novel packaging cell line IP. Deepen backward integration into synthetic promoter libraries to differentiate construct offerings beyond commodity AAV serotypes. The EU MDR Annex XVI reclassification timeline pressures smaller laser system suppliers lacking notified body relationships. For New Entrants and Emerging Players: Japan's PMDA conditional early approval framework offers the fastest regulatory pathway for optogenetic vision restoration candidates. Target wireless power telemetry integration for free-behavior neuroscience applications where cable artifacts constrain incumbent fiber-tethered architectures. White-space penetration concentrates at academic core facilities seeking consolidated reagent procurement alternatives to Thermo Fisher's catalog dominance. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among viral vector GMP manufacturers with institutional-scale agreements covering 60-70 percent of per-investigator reagent costs. Acquisition targets should display established ISO 10993 biocompatibility documentation capacity and MDR technical affairs expertise. The signal to watch is reimbursement policy evolution for optogenetic vision restoration procedures.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Annex XVI Compliance Pathway | Notified body intervention enables CE marking for active implantable optical devices in German and French ophthalmology centers. |
| Red-Shifted Opsin Pipeline Expansion | Chrimson and step-function variant development reduces phototoxicity risk for longitudinal therapeutic applications. |
| Wireless LED Microdevice Integration | Inductive charging microelectronics eliminate transcranial fiber tethering for behavioral neuroscience workflows. |
| Institutional Core Facility Partnership | Stanford and MIT consolidation patterns demonstrate 60-70 percent subsidy coverage flattening price sensitivity. |
| PMDA Conditional Early Approval Engagement | Japan's regenerative medicine sandbox accelerates clinical validation timelines for GenSight Biologics' vision restoration candidates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with viral vector manufacturing executives, academic core facility directors, regulatory affairs specialists at ophthalmology CROs, and biomedical engineers at NIH-funded neurotechnology centers; and secondary validation against FDA Investigational New Drug filings, EMA scientific advice pathways, PMDA gene therapy approval registers, and institutional procurement database disclosures. Bottom-up reagent volume estimates triangulated against top-down NIH BRAIN Initiative appropriation flows.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, application, end user, and technology maturity tier. CAGRs derived from instrument replacement cycle analysis, viral vector demand elasticity, and regulatory pathway probability-weighted therapeutic approval timelines. Forecast inputs incorporated opsin variant engineering velocity, EU MDR implementation pace, and wireless power telemetry commercialization readiness.
Underlying assumptions cover sustained federal neuroscience funding, AAV packaging capacity expansion, and MDR notified body capacity scaling, with deviation risk concentrated in phototoxicity safety signal emergence and reimbursement policy stagnation for vision restoration. Recalibration cycles align with material shifts in NIH appropriation patterns, EU MDR guidance document releases, and PMDA conditional approval precedent establishment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Europe Biobanks Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
Fluorescent in Situ Hybridization Market
Biomedical Technology
Europe Transfection Technologies Market
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market
Biomedical Technology
Protein Expression Technology Market
Biomedical Technology
Global Laser Capture Microdissection Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
Global Biomarker Technologies Market
Biomedical Technology
Glycomics Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Global Protein Characterization and Quantification Market
Biomedical Technology
Cell Cryopreservation Market
Biomedical Technology
Cell Separation Market