
 Plant-Based Vaccines Market | 2026-2036
Plant-Based Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Vaccines Market Analytics
Contract biomanufacturing channels for transient expression systems is reshaping how pharmaceutical developers access plant-based production capacity. Medicago Inc. leverages vertical integration from Nicotiana benthamiana cultivation to fill-finish operations. Kentucky BioProcessing anchors large-scale tobacco-derived bioreactor capacity for pandemic response stockpiling. iBio Inc. differentiates through its FastPharming system and automated hydroponic facility design.
Plant-based vaccines are biologics produced through recombinant protein expression in whole plants or plant cell cultures, typically using viral vector infiltration or stable transgenic lines with protein purification yields reaching grams per kilogram of leaf biomass. Their primary purpose is to generate immunogenic antigens for prophylactic or therapeutic vaccination at lower capital cost than mammalian cell culture. Recombinant antigens command the dominant share of current development pipelines due to proven transient expression timelines under eight weeks. Virus-like particles represent the fastest-growing product category, driven by self-assembling capsid structures that elicit strong neutralizing antibody responses without infectious genetic material. Infectious disease applications sustain the largest therapy area allocation, though cancer vaccines are gaining trial volume as neoantigen personalization converges with plant expression speed.
FDA plant-made pharmaceutical guidance, EMA adaptive pathway frameworks, and WHO prequalification standards collectively determine clinical trial design, GMP compliance, and procurement eligibility for plant-derived biologics. These frameworks shape demand by defining comparability thresholds that transient expression platforms must meet for interchangeable use against CHO-cell benchmarks. Stakeholders must monitor how national biodefense stockpiling mandates and pandemic treaty negotiations redistribute manufacturing investment between distributed plant systems and centralized mammalian facilities.
Market Dynamics
Transient expression platforms are compressing biomanufacturing timelines from months to weeks, forcing contract manufacturers to reconfigure capacity allocation and pricing models around speed rather than scale alone.
Growth Catalysts
- Pandemic Preparedness Mandates:BARDA and DARPA funding streams prioritize domestic biomanufacturing resilience, directing procurement toward distributed plant-based systems that bypass mammalian cell culture bottlenecks during surge demand.
- EMA Adaptive Pathways:The framework accelerates conditional approval for plant-derived recombinant antigens, reducing clinical trial duration and enabling earlier revenue recognition for developers targeting infectious disease immunization programs.
- Virus-Like Particle Engineering:Self-assembling capsid technologies elicit robust neutralizing antibody responses without infectious genetic material, expanding addressable indications beyond traditional subunit vaccines.
Market Restraints
- Downstream Purification Costs:Leaf biomass processing requires chromatography and filtration infrastructure comparable to mammalian systems, eroding the capital cost advantage at commercial scale.
- Regulatory Comparability Burden:FDA plant-made pharmaceutical guidance demands extensive immunogenicity bridging studies against CHO-cell benchmarks, extending development timelines for interchangeable use claims.
- Specialized Cultivation Expertise:Nicotiana benthamiana agronomy and viral vector optimization depend on limited talent pools concentrated in specific research clusters.
Strategic Opportunities
- Neoantigen Personalization Convergence:Plant expression speed aligns with patient-specific cancer vaccine manufacturing windows, enabling just-in-time production that mammalian platforms cannot match.
- Automated Hydroponic Integration:Robotics and environmental control systems reduce contamination risk while standardizing biomass yields, opening contract manufacturing to developers without captive cultivation.
- WHO Prequalification Pathway:Emerging market procurement eligibility hinges on prequalification standards that plant-based platforms can pursue through abbreviated clinical data packages.
Industry Challenges
- Fill-Finish Capacity Coordination:Aseptic processing and vialing operations remain concentrated among legacy biologics contractors, creating integration friction for plant-derived drug substance.
- GMP Compliance Timeline:Facility qualification and process validation for transient expression systems lack precedent, forcing sponsors to negotiate case-by-case with national regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Vaccines Market |
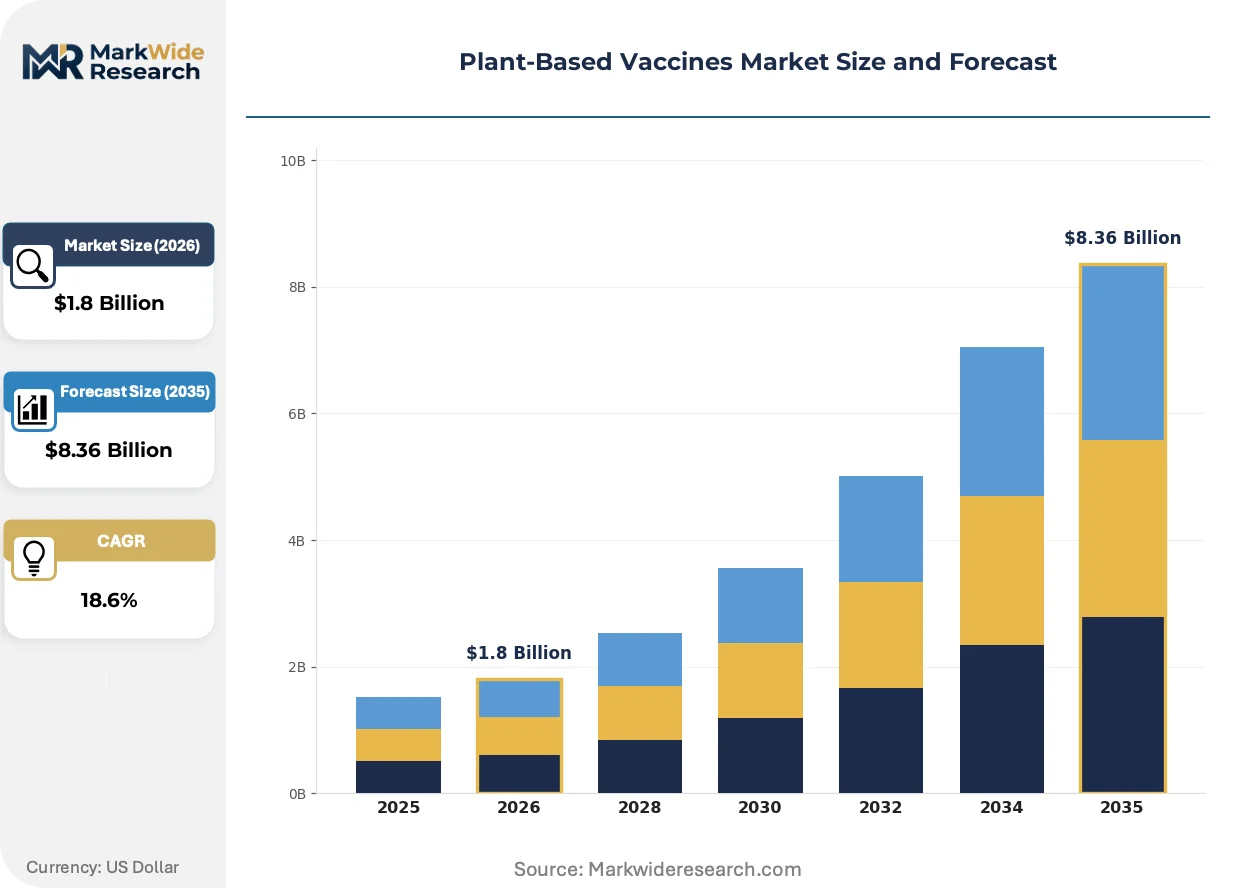
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Antigens, Live Attenuated Vaccines, Inactivated Vaccines, Virus-Like Particles Therapy Area: Infectious Diseases, Cancer Vaccines, Autoimmune Disorders, Allergies Delivery Method: Intramuscular, Oral, Intranasal, Transdermal Target Population: Adults, Pediatrics, Elderly, Immunocompromised Individuals |
| Companies Covered | Medicago Inc., iBio Inc., Creative Biolabs, ICON Genetics GmbH, Kentucky BioProcessing, PlantForm Corporation, Baiya Phytopharm, Lumen Bioscience Inc., Leaf Expression Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Vaccines Market Evolving Landscape
Speed-to-clinic imperatives are reshaping competitive advantage around expression platform selection, with transient systems capturing development-stage contracts previously reserved for stable cell lines.
MagnICON viral vector systems are collapsing the upstream production timeline for complex multimeric antigens. Vaccine developers targeting seasonal influenza and emerging variants now specify transient Nicotiana platforms in request-for-proposal documents. The compression from gene synthesis to purified drug substance is eliminating traditional CMC bottlenecks that delayed first-in-human studies.
EMA's adaptive licensing framework is creating regulatory runway for plant-made pharmaceuticals through iterative evidence generation. Developers submit initial safety and immunogenicity data for conditional approval, then expand indication scope via post-authorization studies. Oncology applications are responding fastest, leveraging the framework's flexibility for personalized neoantigen vaccines where traditional Phase III designs prove infeasible.
National biodefense stockpiling programs are consolidating procurement around surge-capable manufacturing networks. United States federal agencies now evaluate contract manufacturers on dual-use flexibility—routine production plus pandemic response scaling—rather than unit cost alone. This behavioral shift favors plant-based platforms with modular bioreactor configurations over centralized mammalian facilities with fixed output constraints.
Plant-Based Vaccines Market Segmentation
Plant-based vaccine developers must align platform selection with product architecture and patient population. Segmentation reveals where transient expression systems compete against mammalian cell culture on speed, cost, or immunogenicity profile.
Product Type:
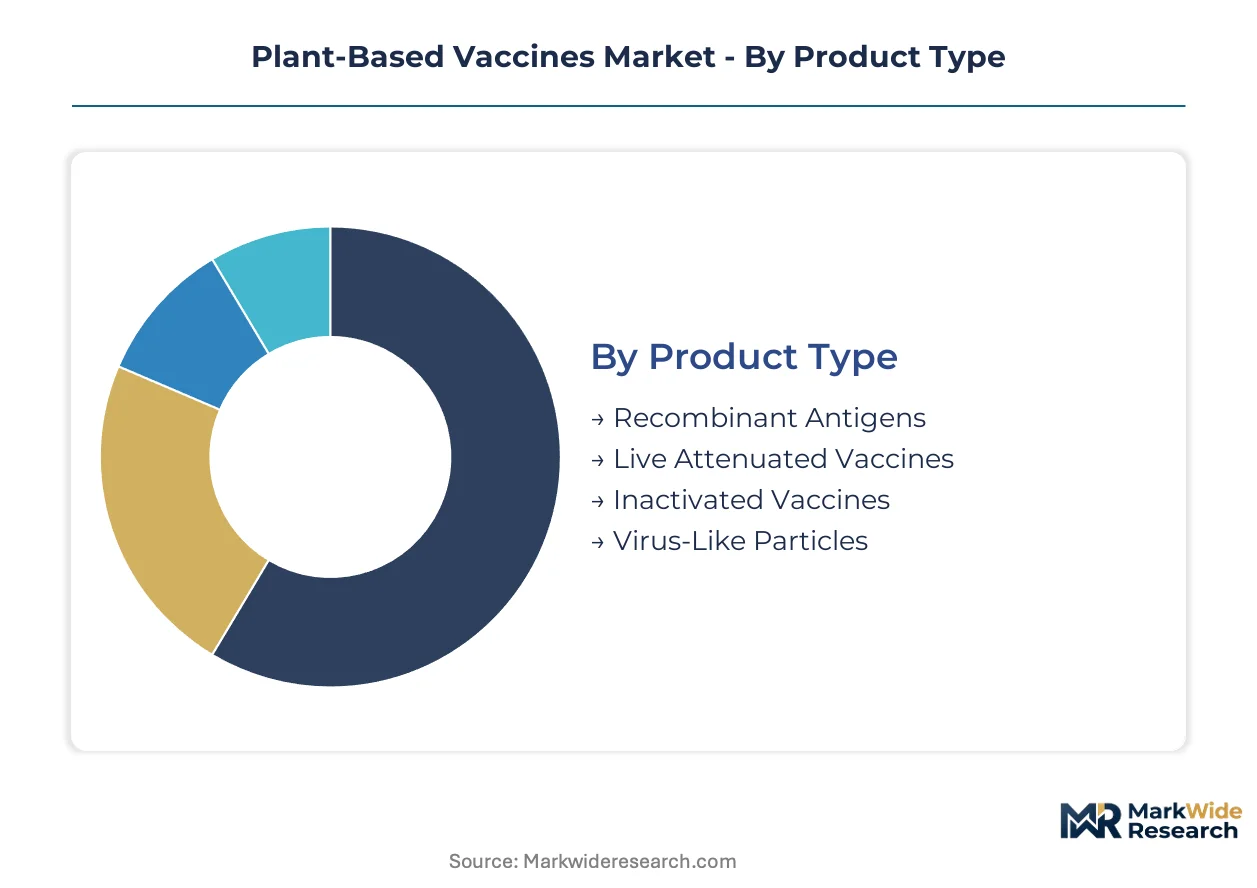
Mature subunit formats dominate current manufacturing throughput while self-assembling particle technologies accelerate fastest.
- Recombinant Antigens:Purified protein subunits expressed through viral vector infiltration of Nicotiana benthamiana leaves. BARDA-funded procurement programs in the United States concentrate demand for influenza and COVID-19 candidates where speed-to-dose outweighs adjuvant complexity.
- Virus-Like Particles:Self-assembling capsid structures lacking infectious genetic material elicit neutralizing antibody responses through repetitive epitope display. EMA adaptive pathway approvals for Medicago's COVID-19 VLP validate commercial scalability.
- Live Attenuated Vaccines:Weakened pathogen strains propagated in plant tissue culture systems.
- Inactivated Vaccines:Chemically treated whole pathogens processed from transgenic plant biomass.
Recombinant antigens handle the majority of throughput; virus-like particles are expanding most quickly on share.
Therapy Area:
Volume concentrates in infectious disease stockpiling while oncology applications exploit platform speed for personalized manufacturing.
- Infectious Diseases:Pandemic preparedness mandates from United States federal agencies sustain procurement for influenza, COVID-19, and emerging pathogen candidates. DARPA investments prioritize surge-capable domestic biomanufacturing over unit cost optimization.
- Cancer Vaccines:Patient-specific neoantigen targets require expression timelines incompatible with mammalian cell culture. Plant-based transient systems compress manufacturing windows to match clinical administration schedules.
- Autoimmune Disorders:Tolerance-inducing biologics delivered through oral plant tissue consumption.
- Allergies:Hypoallergenic protein variants expressed in plant systems to reduce IgE cross-reactivity.
Infectious diseases command the largest revenue pool; cancer vaccines are gaining share fastest.
Delivery Method:
Route selection determines formulation complexity and cold chain requirements across distribution networks.
- Intramuscular:Standard injection delivery for purified protein antigens requiring adjuvant suspension. United States military vaccination programs specify intramuscular formats for stockpile compatibility with existing immunization infrastructure.
- Oral:Edible plant tissue or lyophilized powder formulations bypassing needle requirements. WHO prequalification pathways for thermostable oral vaccines target emerging market distribution gaps.
- Intranasal:Mucosal spray delivery inducing IgA responses at respiratory entry points.
- Transdermal:Microneedle patch applications of plant-derived antigens.
Intramuscular formats carry the highest production volumes; oral delivery is climbing the fastest on development priority.
Target Population:
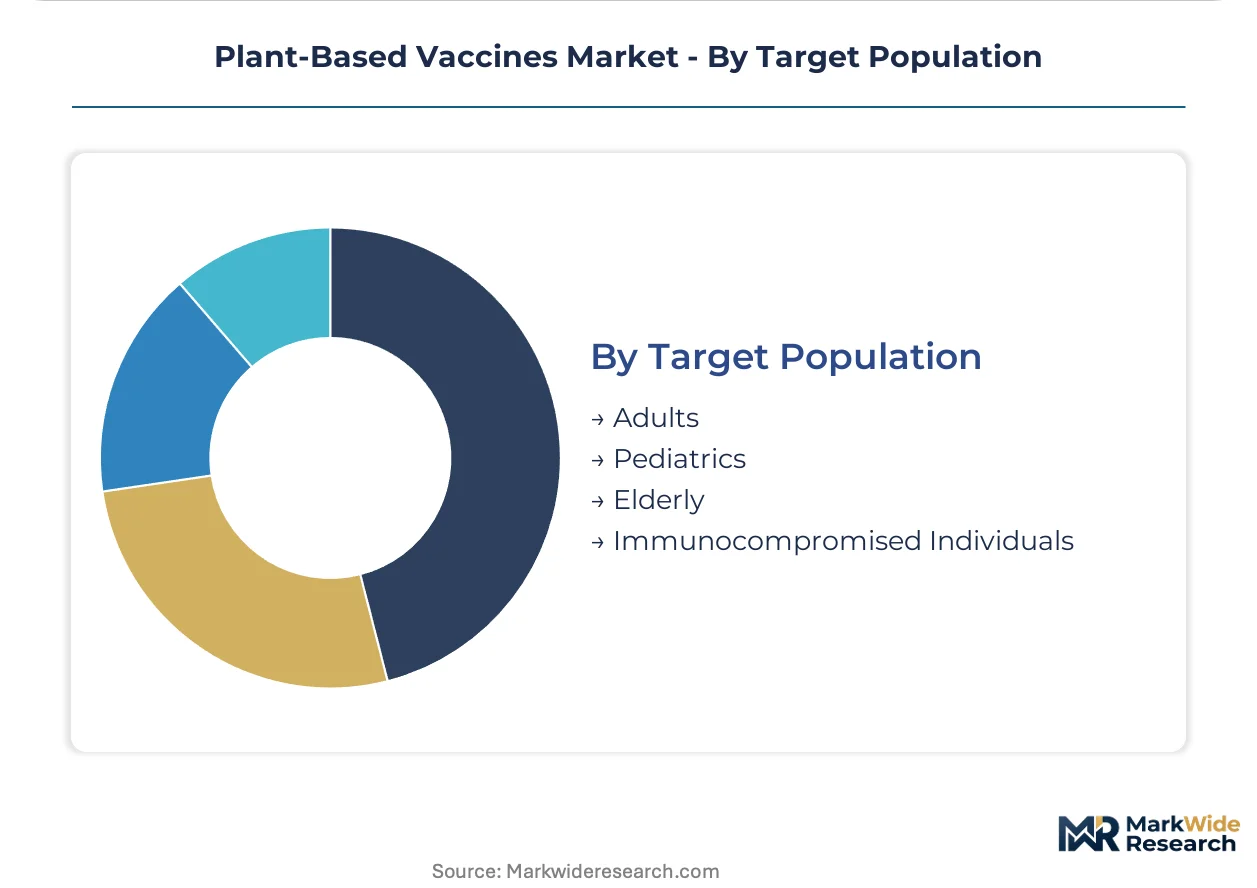
Immunogenicity bridging studies vary by age-related immune competence and underlying health status.
- Adults:Standard immunization schedules for healthy working-age populations. FDA plant-made pharmaceutical guidance requires adult safety data as the foundation for pediatric indication expansion.
- Pediatrics:Smaller dose volumes and enhanced purity specifications for developing immune systems. EMA pediatric investigation plans mandate age-appropriate formulation development.
- Elderly:Immunosenescence-targeted adjuvant combinations with plant-derived antigens.
- Immunocompromised Individuals:Non-replicating VLP and subunit formats preferred over live attenuated approaches.
Adult populations absorb the bulk of commercial supply; pediatric indications are advancing fastest through regulatory pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal biodefense procurement mandates in the United States are redistributing manufacturing investment toward distributed plant-based production systems that bypass mammalian cell culture bottlenecks during pandemic surge scenarios.
United States
BARDA and DARPA funding streams prioritize domestic biomanufacturing resilience, directing contract awards toward transient expression platforms with surge-capable modular configurations. FDA plant-made pharmaceutical guidance establishes comparability thresholds against CHO-cell benchmarks for interchangeable use claims. The Research Triangle Park cluster in North Carolina anchors Medicago's vertical integration from Nicotiana benthamiana cultivation through fill-finish operations.
Germany
EMA adaptive pathway frameworks accelerate conditional approval timelines for plant-derived recombinant antigens, reducing clinical trial duration for infectious disease candidates. The country's national pharmaceutical regulator enforces GMP compliance standards that transient expression platforms must negotiate case-by-case. Halle-based ICON Genetics GmbH maintains viral vector optimization expertise concentrated in Saxony-Anhalt research clusters.
Canada
Health Canada aligns with FDA guidance on immunogenicity bridging studies, facilitating cross-border regulatory convergence for plant-made pharmaceuticals. Federal pandemic preparedness stockpiling programs evaluate contract manufacturers on dual-use flexibility metrics. Quebec's Medicago facilities demonstrate commercial-scale Nicotiana benthamiana processing from gene synthesis through purified drug substance.
United Kingdom
Leaf Expression Systems Ltd. in Norwich anchors transient expression capabilities serving European vaccine developers seeking compressed manufacturing timelines. The Medicines and Healthcare products Regulatory Agency processes plant-derived biologics applications under accelerated assessment pathways for pandemic countermeasures. East Anglia's agritech corridor concentrates specialized cultivation expertise for viral vector infiltration protocols.
Thailand
Baiya Phytopharm leverages tropical growing conditions for year-round Nicotiana benthamiana biomass production serving Asian immunization programs. The country's national pharmaceutical regulator pursues WHO prequalification alignment for emerging market procurement eligibility. Bangkok-centered biomanufacturing infrastructure integrates automated hydroponic systems with regional fill-finish partnerships.
Plant-Based Vaccines Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated specialists with captive cultivation capacity and contract manufacturers offering speed-to-clinic services through transient expression platforms. Three strategic archetypes dominate: tobacco-bioreactor operators with pandemic surge capabilities, automated hydroponic facility designers, and viral vector technology licensors. Capacity expansion and strategic partnerships represent the dominant competitive moves as developers seek guaranteed drug substance supply for clinical programs.
Among North American operators, Medicago Inc. and Kentucky BioProcessing occupy positions at the scale-driven end of contract manufacturing, while iBio Inc. exemplifies the technology-licensing archetype through its FastPharming system deployment. These three anchors demonstrate how geographic clustering around federal funding sources—BARDA in the United States and Canadian pandemic preparedness programs—shapes competitive positioning without requiring identical business model construction.
| Leading Market Players |
|---|
| Medicago Inc. |
| iBio Inc. |
| Creative Biolabs |
| ICON Genetics GmbH |
| Kentucky BioProcessing |
| PlantForm Corporation |
| Baiya Phytopharm |
| Lumen Bioscience Inc. |
| Leaf Expression Systems Ltd. |
| Others |
Value Network & Pricing Analysis
Nicotiana benthamiana seed stock and viral vector supplies concentrate among specialized agronomy providers in the United States and Canada, directing margin capture toward downstream drug substance manufacturers with captive cultivation and automated hydroponic infrastructure. Contract manufacturers command pricing premiums for speed-to-clinic services while commodity leaf biomass processors compete on unit cost for stockpiled pandemic countermeasures.
Pricing Analysis
Volume-discount tiering separates surge-capable pandemic response contracts from routine clinical manufacturing engagements. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification status, fill-finish integration depth, and BARDA contract eligibility. Pricing pressure stems from downstream purification infrastructure costs that erode transient expression capital advantages at commercial scale. Government procurement programs demonstrate lowest price sensitivity; emerging market developers without captive cultivation face highest cost pressure.
Supply Chain Analysis
Upstream feedstock production centers on Kentucky, North Carolina, and Quebec for temperate-climate greenhouse operations, with Thailand anchoring tropical biomass cultivation. Viral vector stocks, specialized growth media, and chromatography resins draw from concentrated life sciences suppliers in Germany and the United States. Single-source vulnerability runs through fill-finish contractors with legacy biologics expertise. Distribution runs through cold-chain logistics networks serving federal stockpile depots and hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based vaccines occupy an early-cycle expansion phase as EMA adaptive pathways and BARDA procurement mandates accelerate platform validation beyond proof-of-concept. Transient expression speed is displacing mammalian cell culture for development-stage contracts previously reserved for stable CHO lines.
For Market Incumbents: Pre-empt margin compression in commoditized leaf biomass processing by deepening captive supply of viral vector stocks and automated hydroponic systems. Kentucky BioProcessing and Medicago demonstrate how backward integration into seed genetics and environmental control hardware defends pricing power against emerging contract manufacturers. Regulatory comparability burdens for FDA interchangeable use claims threaten developers without immunogenicity bridging study experience.
For New Entrants and Emerging Players: Southeast Asian markets with WHO prequalification alignment and limited domestic biomanufacturing infrastructure present the most penetrable white-space. Baiya Phytopharm's Thailand-based model proves tropical cultivation can serve regional immunization programs without temperate-climate capital intensity. Target oral delivery formulation partnerships with emerging market distributors lacking cold-chain infrastructure.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with demonstrated GMP compliance for transient expression systems and established relationships with BARDA or equivalent biodefense procurement agencies. Long-term viability hinges on successful navigation of FDA plant-made pharmaceutical guidance comparability thresholds. The signal to watch is conditional EMA approval volume for personalized neoantigen cancer vaccines, where plant platform speed creates defensible positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Hydroponic Scale-Up | Reduces contamination risk while standardizing biomass yields for contract manufacturing access. |
| Viral Vector Optimization Partnership | MagnICON system licensing accelerates multimeric antigen production timelines for seasonal programs. |
| EMA Adaptive Pathway Submission | Conditional approval frameworks reduce clinical trial duration for infectious disease candidates. |
| Fill-Finish Capacity Integration | Aseptic processing partnerships eliminate downstream bottlenecks for purified drug substance. |
| WHO Prequalification Pursuit | Abbreviated clinical data packages unlock emerging market procurement eligibility for oral formulations. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads at plant-based vaccine sponsors, contract manufacturing procurement managers, and hospital formulary directors anchored the qualitative base. These primary inputs combined with FDA plant-made pharmaceutical guidance documents, EMA adaptive pathway submission records, ClinicalTrials.gov protocol registries, and BARDA contract award disclosures. Bottom-up capacity assessments across Nicotiana benthamiana cultivation facilities triangulated against top-down procurement forecasts from federal biodefense programs.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling across product architecture, therapy area, delivery method, and target population dimensions. CAGRs derived from facility capacity expansion announcements, viral vector yield improvements, and regulatory approval velocity patterns. Forecast inputs incorporated transient expression timeline compression rates and comparability study burden estimates for CHO-cell benchmark requirements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by tobacco-bioreactor operators or breakthroughs in downstream purification cost structures would shift outcomes. Cross-checking against BARDA contract award velocity and EMA conditional approval volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biotechnology
GMO Crops and Seeds Market
Agricultural Biotechnology
Transgenic Seeds Market
Agricultural Biotechnology
Animal Brucella Antibody ELISA Kits Market
Agricultural Biotechnology
Agricultural Biotechnology Market
Agricultural Biotechnology
Stigmasterol-Rich Plant Sterols Market
Agricultural Biotechnology
South America Feed Phytogenics Market
Agricultural Biotechnology
Global Animal Biotechnology Market
Agricultural Biotechnology
Agroscience Market
Agricultural Biotechnology
Europe Agriculture Biotech Market
Agricultural Biotechnology
Duckweed Protein Market
Agricultural Biotechnology
Global Poultry Vaccines Market
Agricultural Biotechnology
Africa Algae Protein Market
Agricultural Biotechnology
Global Plant Hormones Market
Agricultural Biotechnology
Europe Plant Growth Regulators Market
Agricultural Biotechnology
Asia-Pacific Agriculture Biotech Market
Agricultural Biotechnology
Asia Pacific Feed Phytogenics Market