
 Global Immunohistochemistry (IHC) Market | 2026-2036
Global Immunohistochemistry (IHC) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Immunohistochemistry (IHC) Market Foresight
Modular reagent-and-instrument bundling is realigning procurement patterns across hospital pathology departments. F. Hoffmann-La Roche leverages integrated slide staining systems to anchor its presence in high-throughput diagnostic networks. Thermo Fisher Scientific competes through antibody specialization spanning oncology and neuroscience research channels. Danaher Corporation controls consumables distribution density in North American reference laboratories.
Immunohistochemistry denotes a laboratory technique using antibody-antigen binding to visualize specific protein targets in tissue sections, typically employing chromogenic or fluorescent detection with DAB or Alexa Fluor reporters at 4-40x microscopy resolution. The method enables diagnostic classification of tumor origin, biomarker expression profiling, and immune cell infiltration mapping in formalin-fixed paraffin-embedded specimens. Antibodies command sustained margin concentration due to clone specificity requirements and validation-intensive development cycles. Cancer diagnostics occupies the largest application share while biomarker discovery demonstrates the fastest expansion trajectory driven by companion diagnostic mandates. Diagnostic laboratories represent the most concentrated end-user channel for recurring consumables volume.
FDA quality system regulations and EMA in-vitro diagnostic device standards shape product validation requirements and market access pathways for IHC assay manufacturers. CLIA laboratory certification in the United States and ISO 15189 accreditation frameworks in European jurisdictions enforce analytical performance thresholds that filter vendor eligibility. Stakeholders must monitor evolving premarket notification pathways for automated staining platforms and software-aided scoring algorithms as regulatory scope broadens beyond traditional reagent controls.
Market Dynamics
Automated slide staining platforms are compressing manual workflow capacity in diagnostic laboratories, forcing capital allocation decisions that favor integrated reagent-instrument bundles over standalone antibody procurement.
Growth Catalysts
- Companion diagnostic mandates:FDA and EMA pathways now require biomarker validation for targeted oncology therapies, expanding IHC testing volumes in reference laboratories.
- Multiplex staining platforms:Academic medical centers in Germany and the United States are deploying 7-12 color panels for immune profiling, driving consumables density per specimen.
- CLIA laboratory certification:United States quality enforcement creates vendor eligibility filters that concentrate procurement among validated suppliers.
Market Restraints
- Antibody clone specificity requirements:Validation-intensive development cycles extend time-to-market for novel biomarker targets.
- Reagent supply concentration:North American reference laboratories depend on limited qualified sources for DAB chromogen and detection polymers.
- Substitution pressure from RNAscope:In situ hybridization methods encroach on protein detection applications in neuroscience research channels.
Strategic Opportunities
- Underpenetrated digital pathology integration:Image analysis algorithms for automated IHC scoring remain nascent in European community hospital networks.
- EMA in-vitro diagnostic device standards expansion:Software-aided scoring algorithms face broadening regulatory scope beyond traditional reagent controls.
- Spatial biology convergence:Integration of IHC with spatial transcriptomics creates new service revenue in precision oncology research.
Industry Challenges
- Pathologist workforce constraints:Specialized expertise in complex biomarker interpretation creates bottlenecks in high-throughput diagnostic networks.
- Legacy LIS integration friction:Automated staining platforms require middleware development for connectivity with existing laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Immunohistochemistry (IHC) Market |
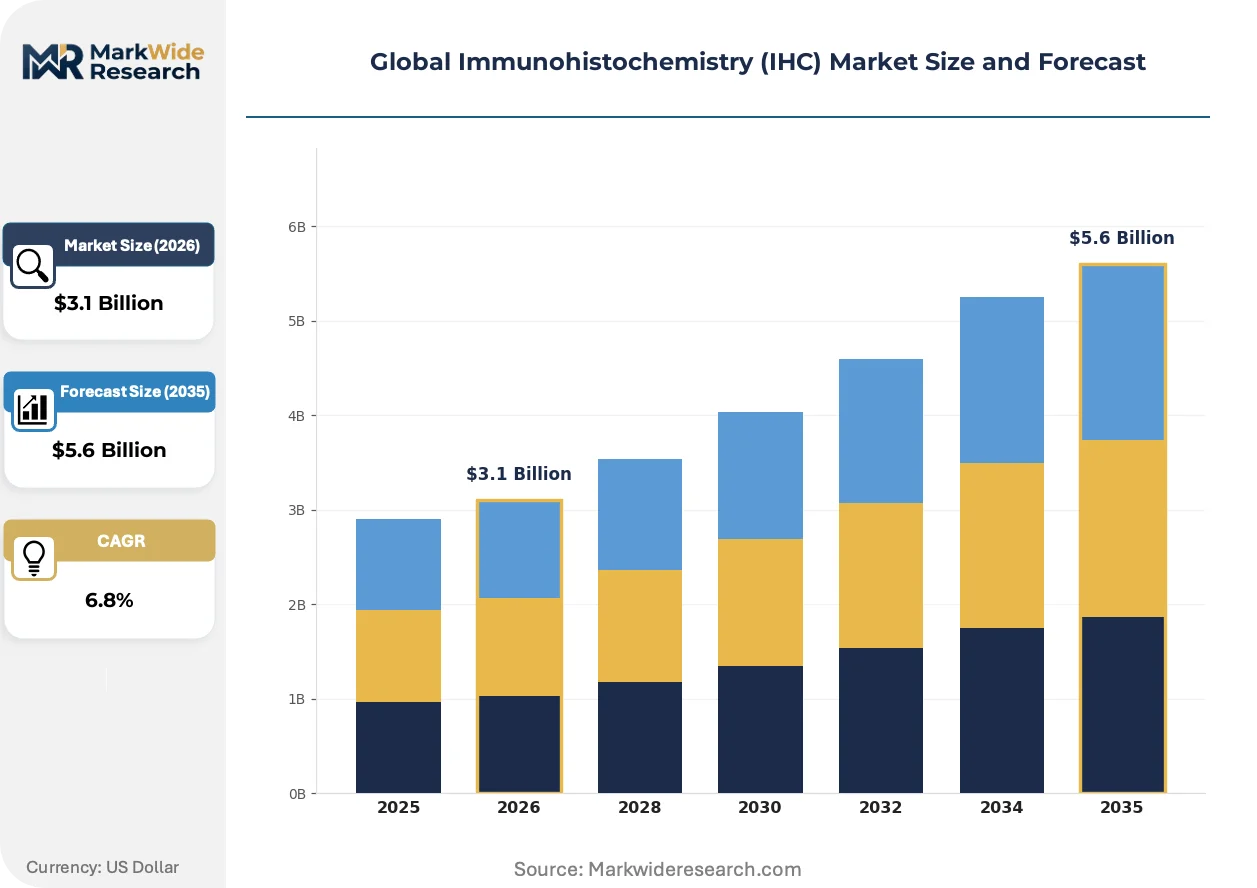
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibodies, Detection Reagents, Instruments, Software Solutions Application: Cancer Diagnostics, Infectious Disease Research, Neurological Disorder Studies, Biomarker Discovery End User: Academic Research Institutes, Pharmaceutical Companies, Diagnostic Laboratories, Biotechnology Firms Deployment: On-Premises, Cloud-Based, Hybrid Models, Managed Services |
| Companies Covered | F. Hoffmann-La Roche, Thermo Fisher Scientific, Danaher Corporation, Agilent Technologies, Merck KGaA, PerkinElmer, Bio-Rad Laboratories, Abcam, Cell Signaling Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Immunohistochemistry (IHC) Market Shifts & Advancements
Fluorescent detection methods are displacing chromogenic workflows in research applications, while regulatory frameworks accelerate validation requirements for clinical deployment. Three forces are compressing competitive positioning.
Multiplex immunofluorescence panels are expanding into immune-oncology biomarker discovery, enabling simultaneous visualization of PD-L1, CD8, and FOXP3 in tumor microenvironments. Academic medical centers in the United States and Germany are adopting 40x whole-slide imaging for quantitative spatial analysis. This technology is expanding into companion diagnostic development pipelines, compressing timelines for biomarker validation.
EMA MDR implementation is tightening quality management system requirements for IHC assay manufacturers, mandating post-market surveillance and clinical evidence documentation. Manufacturers must recertify legacy products under stricter performance thresholds. European reference laboratories are consolidating procurement around MDR-compliant suppliers, filtering vendor eligibility.
Consolidated purchasing agreements are reshaping antibody procurement in North American health systems, replacing individual laboratory autonomy with centralized supply contracts. Group purchasing organizations now negotiate multi-year reagent bundles with instrument placement incentives. This concentration is most visible in United States academic medical center networks, where standardization across satellite campuses reduces validation redundancy.
Global Immunohistochemistry (IHC) Market Segmentation
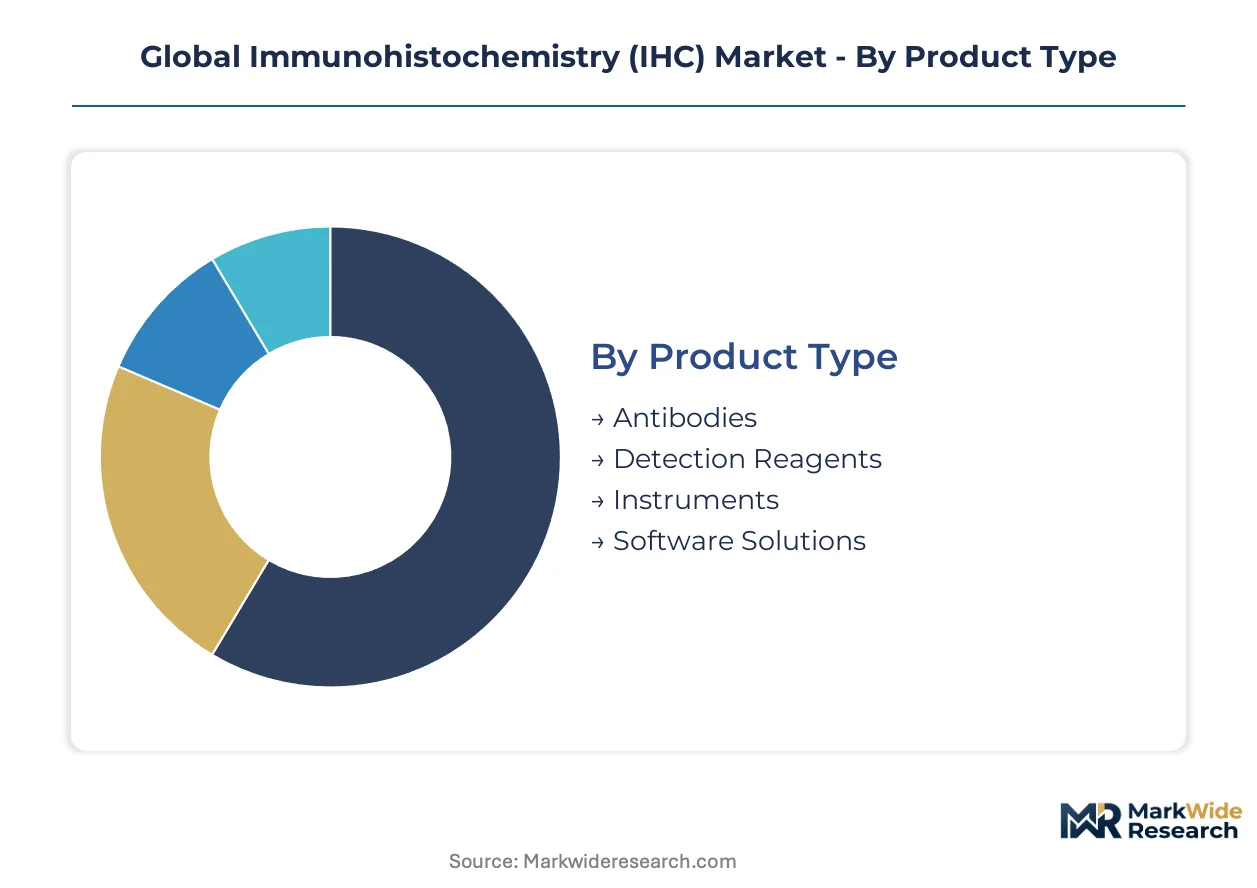
Segmentation in immunohistochemistry reveals distinct procurement patterns across reagent-intensive versus capital-intensive categories. Each dimension exposes different margin structures, validation burdens, and vendor control points that shape competitive strategy.
Product Type:
The customization-to-standardization spectrum stretches from clone-specific antibody development to commoditized detection chemistries.
- Antibodies:Monoclonal and polyclonal preparations targeting specific protein epitopes in FFPE tissue sections. Diagnostic laboratories in the United States concentrate procurement around FDA-cleared clones for PD-L1 and HER2 testing under CLIA enforcement. Clone specificity requirements extend validation cycles and sustain premium pricing for validated suppliers.
- Detection Reagents:Chromogenic substrates including DAB and polymer-based signal amplification systems. German cancer diagnostics laboratories are expanding automated workflow capacity, driving bundled reagent consumption per slide. EMA quality frameworks filter vendor eligibility toward MDR-compliant manufacturers.
- Instruments:Automated slide staining platforms with robotic liquid handling and temperature-controlled incubation chambers.
- Software Solutions:Image analysis algorithms for quantitative scoring of biomarker expression and immune cell infiltration mapping.
Leading the category by volume: Detection Reagents. Expanding most quickly: Software Solutions.
Application:
Volume concentration aligns with regulatory-mandated testing pathways versus exploratory research budgets.
- Cancer Diagnostics:Tumor origin classification and biomarker expression profiling for therapy selection. Academic medical centers in Germany and the United States deploy 7-12 color multiplex panels for immune-oncology profiling, compressing per-specimen analysis timelines. Companion diagnostic mandates from FDA and EMA expand required testing volumes in reference laboratories.
- Biomarker Discovery:Exploratory protein target identification for companion diagnostic development. Pharmaceutical companies in Switzerland and the United Kingdom are integrating IHC with spatial transcriptomics for precision oncology pipelines. This convergence creates service revenue in contract research organizations.
- Infectious Disease Research:Pathogen detection and tissue tropism studies in viral and bacterial infection models.
- Neurological Disorder Studies:Protein aggregation analysis in neurodegenerative disease tissue specimens.
Commanding the largest revenue share: Cancer Diagnostics. Gaining share fastest: Biomarker Discovery.
End User:
Procurement autonomy varies from centralized health system contracts to principal-investigator-driven laboratory budgets.
- Diagnostic Laboratories:High-throughput clinical testing facilities with recurring consumables demand. North American reference laboratories are consolidating procurement through group purchasing organization agreements with multi-year reagent bundles. CLIA certification requirements concentrate vendor selection among validated suppliers.
- Academic Research Institutes:Principal-investigator-driven procurement with flexibility for novel antibody validation. Research institutes in Germany and the United States are adopting 40x whole-slide imaging systems for quantitative spatial analysis. Grant-funded budgets prioritize publication-ready multiplex staining capabilities.
- Pharmaceutical Companies:Companion diagnostic development and clinical trial biomarker analysis.
- Biotechnology Firms:Target validation and therapeutic antibody development support.
Highest consumables density: Diagnostic Laboratories. Steepest instrumentation investment: Academic Research Institutes.
Deployment:
Data sovereignty requirements and legacy infrastructure compatibility shape cloud migration willingness.
- On-Premises:Local server installation with institutional control over patient data and algorithm parameters. European hospital networks prioritize on-premises image analysis to satisfy GDPR data localization requirements. Germany's academic medical centers maintain this architecture for sensitive pathology datasets.
- Hybrid Models:Split processing with local image capture and cloud-based algorithm execution. United States health systems are adopting hybrid architectures to balance computational scalability with HIPAA compliance. This approach accommodates legacy LIS integration constraints.
- Cloud-Based:Fully remote processing with vendor-managed infrastructure and subscription pricing.
- Managed Services:Outsourced staining and analysis with results delivery.
Dominant architecture: On-Premises. Climbing the fastest: Hybrid Models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of IHC instruments and reagents concentrates in Germany, Switzerland, and the United States, while diagnostic consumption clusters in reference laboratories across these same markets. Consumption growth outpaces production expansion in India and China as hospital networks build pathology capacity.
United States
Academic medical centers in Boston and Houston deploy 7-12 color multiplex panels for immune-oncology profiling, driving consumables density per specimen. FDA quality system regulations and CLIA laboratory certification enforce analytical performance thresholds that filter vendor eligibility toward validated suppliers. The Greater Boston biotech corridor anchors companion diagnostic development pipelines, compressing biomarker validation timelines through integrated pharmaceutical partnerships.
Germany
Cancer diagnostics laboratories in Munich and Heidelberg expand automated IHC workflows under EMA in-vitro diagnostic device standards and MDR implementation. EMA quality frameworks mandate post-market surveillance and clinical evidence documentation, recertifying legacy products under stricter performance thresholds. The Rhine-Main cluster concentrates procurement consolidation among MDR-compliant suppliers as university hospitals standardize across satellite campuses.
Switzerland
Pharmaceutical companies in Basel integrate IHC with spatial transcriptomics for precision oncology pipelines, creating contract research service revenue. Swissmedic regulates in-vitro diagnostic devices with alignment to EMA frameworks, ensuring market access continuity with EU neighbors. The Basel-Lake Geneva corridor anchors biomarker discovery investment as Roche and Novartis affiliate networks drive companion diagnostic co-development.
China
Hospital pathology departments in Shanghai and Beijing adopt automated staining platforms as domestic manufacturers expand instrument assembly capacity. NMPA regulates in-vitro diagnostic devices with accelerating premarket notification pathways for software-aided scoring algorithms. The Yangtze River Delta concentrates reagent manufacturing investment as local suppliers build antibody validation capabilities for oncology biomarker testing.
India
Diagnostic laboratory chains in Mumbai and Bangalore expand IHC testing menus for cancer classification as private hospital networks build pathology infrastructure. CDSCO regulates in-vitro diagnostics with phased implementation of quality management system requirements for imported and domestic assays. The Maharashtra-Gujarat pharmaceutical corridor attracts contract research organizations establishing biomarker discovery services for export markets.
Global Immunohistochemistry (IHC) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across reagent-intensive and capital-intensive segments. The market structure tilts toward consolidation in automated instrumentation while antibody supply fragments across hundreds of clone-specific developers. Three archetypes dominate: integrated diagnostics conglomerates bundling reagent-instrument systems, antibody specialists commanding clone specificity premiums, and contract research service providers capturing biomarker discovery outsourcing. Competitive moves concentrate on multi-year reagent bundle negotiations with instrument placement incentives and M&A targeting novel antibody validation capabilities.
Among diversified life science conglomerates, F. Hoffmann-La Roche and Thermo Fisher Scientific exemplify the integrated systems archetype, anchoring procurement relationships through bundled staining platforms and detection chemistries. Danaher Corporation occupies a position within the consumables distribution tier, controlling reagent supply density in North American reference laboratories through consolidated logistics networks.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Agilent Technologies |
| Merck KGaA |
| PerkinElmer |
| Bio-Rad Laboratories |
| Abcam |
| Cell Signaling Technology |
| Others |
Supply & Pricing Matrix
Captive antibody production by integrated diagnostics conglomerates anchors supply positions and sustains premium pricing power for validated clones in CLIA-certified reference laboratories. Bundled reagent-instrument procurement contracts concentrate volume commitments, compressing standalone antibody suppliers into price-competitive niches.
Pricing Analysis
Margin tightening in consumables tiers reflects group purchasing organization consolidation across United States academic medical center networks. Three-tier pricing structure across premium validated clones, standard research-grade antibodies, and economy bulk detection reagents stratifies procurement by certification level and volume scale. Cost-down pressure on chromogenic substrates accelerates because domestic manufacturers in China expand DAB production capacity. Diagnostic laboratories exhibit highest price sensitivity due to fixed reimbursement schedules, while pharmaceutical companion diagnostic development teams absorb premium pricing for regulatory-grade validation.
Supply Chain Analysis
Freight cost volatility from cold-chain antibody shipments between Germany, Switzerland, and the United States compresses margin structures for temperature-sensitive reagents. Manufacturing concentration in Germany, the United States, and China for automated staining platforms creates single-source vulnerability for proprietary instrument consumables. Raw material dependencies span purified immunoglobulin fractions, chromogenic substrates, and polymer detection chemistries. Distribution runs through consolidated logistics networks serving North American reference laboratories and European university hospital clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into antibody validation capabilities and automated staining platform development defines competitive survival, as unbundled reagent suppliers face procurement exclusion from integrated health system contracts.
For Market Incumbents: Hedge against RNAscope substitution in neuroscience research channels by acquiring spatial transcriptomics compatibility layers. Deepen backward integration into recombinant antibody production to secure clone specificity pipelines. Defensive consolidation around EMA MDR-compliant quality systems filters vendor eligibility toward recertified legacy portfolios. For New Entrants and Emerging Players: The price-point gap between premium Roche-automated workflows and economy manual staining kits opens penetration pathways in Indian and Chinese hospital pathology departments. Target digital pathology integration services for European community hospitals lacking computational pathology infrastructure. Pursue white-label antibody development for pharmaceutical companion diagnostic partnerships as the fastest-validated entry channel. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified life science conglomerates seeking antibody specialization capabilities. Long-term viability hinges on regulatory-grade validation infrastructure rather than research-grade reagent volume. Acquisition target archetype: mid-cap antibody developers with FDA-cleared PD-L1 or HER2 clones. Monitor FDA premarket notification pathway expansion for software-aided scoring algorithms as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Antibody Clone Validation Investment | FDA-cleared PD-L1 and HER2 clones anchor procurement relationships in CLIA-certified reference laboratories. |
| Automated Staining Platform Integration | Bundled reagent-instrument contracts exclude standalone suppliers from high-throughput diagnostic networks. |
| EMA MDR Quality System Recertification | Post-market surveillance mandates filter vendor eligibility toward compliant manufacturers in European markets. |
| Spatial Transcriptomics Convergence | Integration with IHC creates service revenue in pharmaceutical precision oncology pipelines. |
| Digital Pathology Algorithm Development | Software-aided scoring capabilities address pathologist workforce constraints in high-volume networks. |
Research Methodology
Independent corroboration across primary interviews with pathology department directors, IHC platform engineers, GPO contracts managers, and pharmaceutical biomarker development leads underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and CLIA laboratory certification records. Bottom-up reagent volume estimates triangulate against top-down instrument placement data.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled span product type, application, end user, and deployment architecture, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derive from instrument placement trajectories, consumables pull-through coefficients, and multiplex panel adoption curves in academic medical centers.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time instrument utilization metrics introduce uncertainty bands around consumables forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Exosome Research Products Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market
Biomedical Technology
Macrophage Marker Market
Biomedical Technology
US Liquid Biopsy Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Human Biobanking Ownership Market
Biomedical Technology
Ontogenetic Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
Asia-Pacific Proteomics Market
Biomedical Technology
Global Cell Sorting Market
Biomedical Technology
Global Biomarker Technologies Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Europe Biobanks Market
Biomedical Technology
Orthobiological Products Market
Biomedical Technology
Global Autologous Conditioned Plasma Market
Biomedical Technology
Global Cell Counting Market