
 Global Ligation Market | 2026-2036
Global Ligation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ligation Market Foresight
The EU Green Deal is repositioning material sourcing standards for single-use medical devices, compelling manufacturers to evaluate biodegradable polymers and reduced-plastic packaging formats. Ethicon leverages its Johnson & Johnson parent network to sustain integrated supply chains across European sterilization facilities. Medtronic anchors its competitive stance through concentrated R&D spending on next-generation clip appliers. B. Braun Melsungen AG dominates Central European hospital procurement channels with localized production footprints.
Ligation refers to the mechanical occlusion or binding of biological structures—ducts, vessels, or tissues—using sutures, clips, bands, or wire constructs, typically manufactured from stainless steel, titanium, silicone, or absorbable synthetic polymers through extrusion, molding, or braiding processes. Its primary purpose is to achieve hemostasis, tissue approximation, or orthodontic force application in surgical and dental interventions. Elastic bands within orthodontic treatments occupy mature volume positions with stable replacement cycles, while barbed ligatures in soft tissue repair represent the fastest-expanding margin pool as laparoscopic procedures proliferate. Wire ligatures in vascular surgery retain premium pricing power due to fatigue-resistance specifications and regulatory certification burdens.
The FDA enforces Class II medical device controls for surgical ligatures, mandating biocompatibility testing under ISO 10993 and quality systems aligned with 21 CFR Part 820, which elevates barriers for non-domestic entrants. EMA's Medical Device Regulation requires notified body intervention for implantable ligation devices, extending approval timelines and consolidating vendor relationships with established European registrants. China's NMPA implements dual carbon goals that pressure manufacturers to document supply chain emissions for polymer-based elastic bands. Stakeholders must monitor divergent sterilization validation requirements across FDA, EMA, and NMPA jurisdictions when rationalizing global product platforms.
Market Dynamics
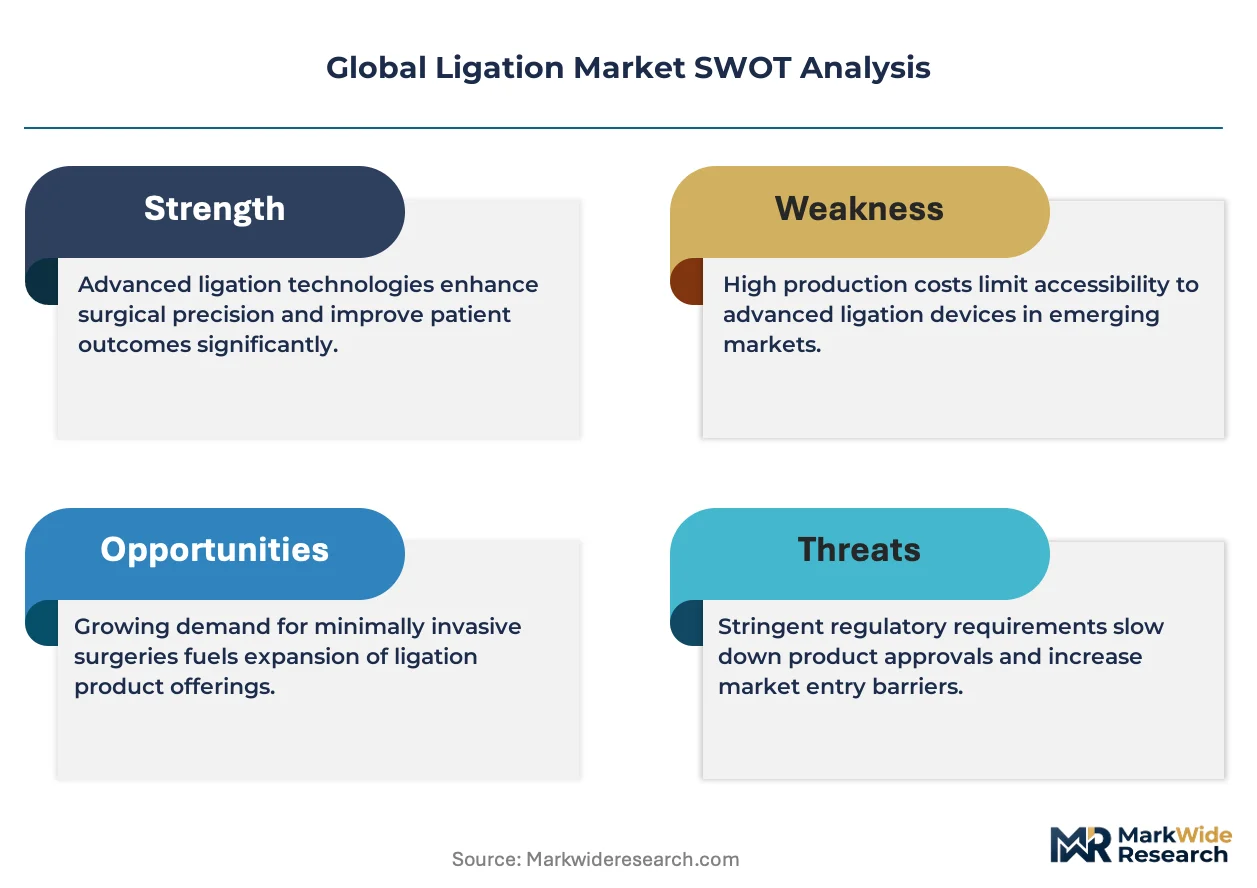
The Global Ligation Market is being fundamentally restructured by the convergence of laparoscopic procedure proliferation and tightening biocompatibility mandates, which together compress product lifecycles while elevating certification burdens for manufacturers across all material categories.
Growth Catalysts
- Minimally Invasive Surgery Expansion:Hospital systems in the United States are converting open procedures to laparoscopic approaches, creating sustained pull for barbed and clip-based ligature systems that enable faster closure times.
- EMA MDR Implementation:The EU Medical Device Regulation's sterility requirements for implantable devices are consolidating vendor relationships, rewarding manufacturers with established notified body partnerships and sterilization infrastructure.
- Orthodontic Elastic Band Replacement Cycles:Dental practices worldwide maintain predictable consumption patterns for silicone-based elastic ligatures, generating stable recurring revenue streams independent of surgical volume fluctuations.
Market Restraints
- Titanium Raw Material Volatility:Surgical clip manufacturers face input cost pressure from titanium sponge supply concentration in Chinese and Russian smelting operations, compressing margin buffers on premium vascular applications.
- Regulatory Approval Timeline Extension:EMA's notified body intervention requirements for implantable ligation devices have extended market entry timelines by 12-18 months for non-European registrants, entrenching incumbent positions.
- Absorbable Polymer Performance Limitations:Synthetic polymer ligatures in high-tension orthopedic applications exhibit inconsistent degradation profiles, restricting their displacement of stainless steel wire in load-bearing scenarios.
Strategic Opportunities
- Biodegradable Polymer Development:EU Green Deal material sourcing standards are creating first-mover advantage for manufacturers evaluating polylactic acid and polyglycolic acid alternatives to petroleum-based elastic bands.
- Central European Production Localization:Germany's orthopedic and dental clusters present concentrated procurement channels where domestic sterilization capabilities and logistics proximity command premium positioning.
- China NMPA Carbon Documentation:The dual carbon goals mandate creates competitive differentiation for manufacturers with supply chain emissions transparency for polymer-based products entering Chinese distribution.
Industry Challenges
- Sterilization Validation Complexity:Divergent FDA 21 CFR Part 820, EMA MDR, and NMPA requirements for ethylene oxide and gamma sterilization protocols force manufacturers to maintain multiple validation dossiers, inflating quality assurance headcount.
- Barbed Suture Manufacturing Scale-Up:The precision molding and cutting equipment required for unidirectional barb formation demands seven-figure capital commitments, constraining mid-tier entrants from matching laparoscopic product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ligation Market |
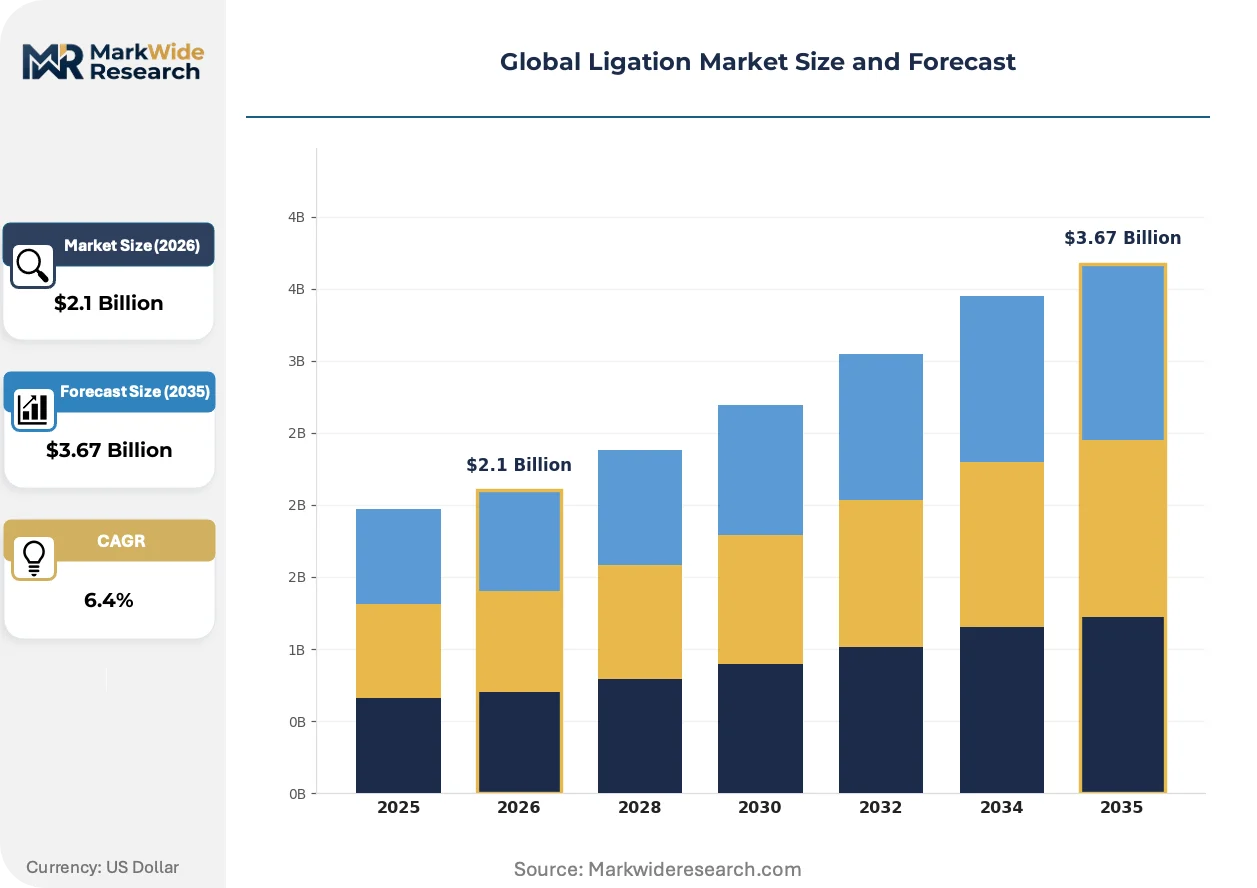
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barbed Ligatures, Elastic Bands, Wire Ligatures, Power Chains, Rubber Ligatures Application: Orthodontic Treatments, Periodontal Therapy, Soft Tissue Repair, Vascular Surgery, Tissue Approximation End User: Orthodontic Clinics, Dental Laboratories, Research Institutes, Medical Universities, Private Practitioners Distribution Channel: Direct Sales, Online Platforms, Distributors, Dental Supply Stores, Medical Equipment Dealers |
| Companies Covered | Ethicon (Johnson & Johnson), Medtronic, Teleflex Incorporated, Olympus Corporation, Applied Medical Resources, CONMED Corporation, The Cooper Companies, B. Braun Melsungen AG, Grena Think Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ligation Market Shifts & Advancements
Electrosurgical integration and smart material formulation are compressing the functional gap between mechanical and energy-based vessel sealing, while regulatory carbon accounting rewrites sourcing criteria for single-use consumables across all major jurisdictions.
Barbed suture technology is electrifying soft tissue repair workflows by eliminating the need for knot-tying in confined laparoscopic spaces. Ambulatory surgical centers in the United States are adopting these systems at accelerated rates compared to traditional teaching hospitals. The technology is electrifying competitive positioning by enabling procedure time reductions that translate directly to throughput economics in high-volume settings.
EMA's Medical Device Regulation is tightening biocompatibility testing protocols for implantable ligation devices, specifically elevating ISO 10993 cytotoxicity and sensitization requirements. Manufacturers must now submit comprehensive chemical characterization data that was previously accepted through predicate equivalence. Vascular surgery applications face the steepest compliance burden, driving consolidation toward vendors with in-house toxicology testing capabilities.
Hospital procurement departments are unbundling after-sales service from device contracts, demanding itemized pricing for sterilization validation support and clinical training. This pattern is displacing bundled premium pricing models that historically obscured true service costs. The shift is most visible in German hospital procurement, where centralized purchasing cooperatives now mandate transparent cost breakdowns for all implantable ligation systems.
Global Ligation Market Segmentation
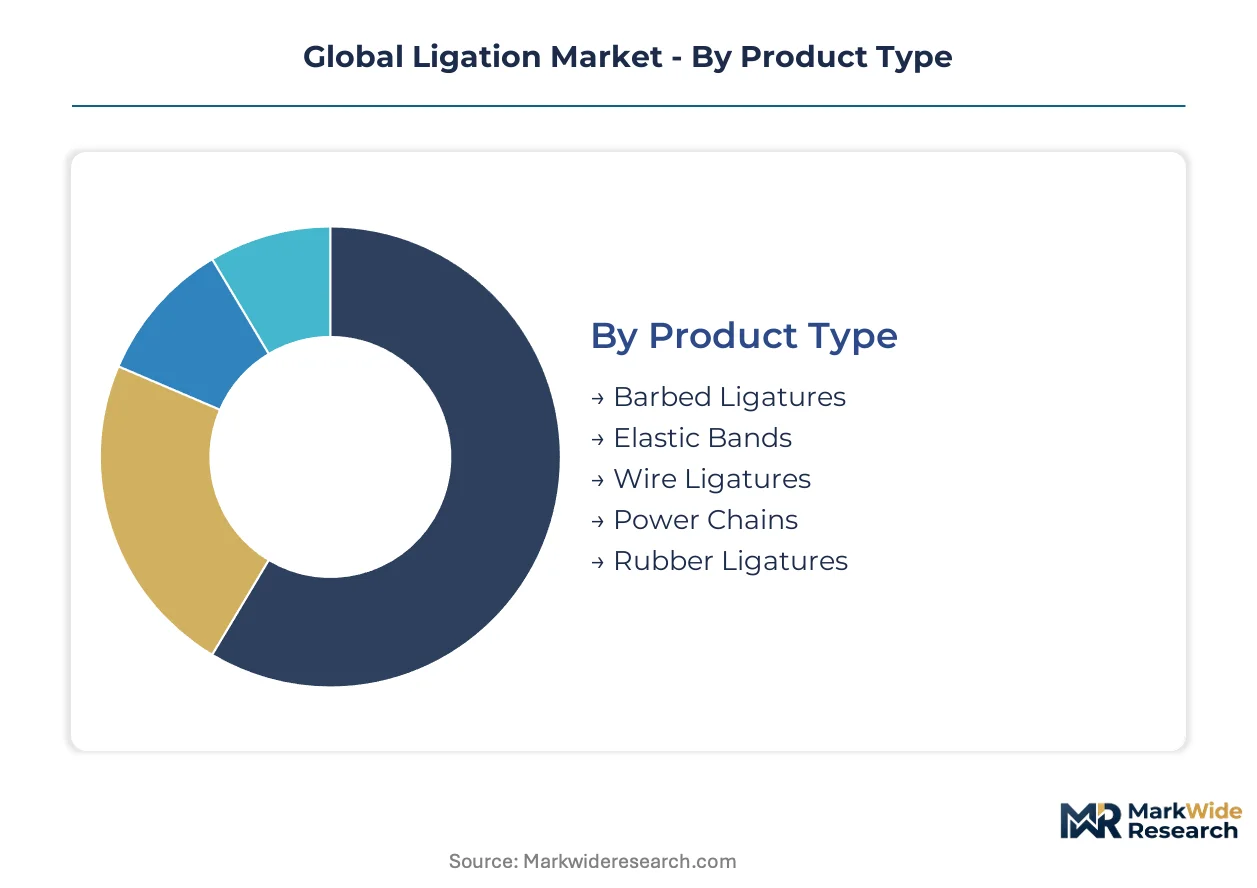
Material composition and procedural setting determine procurement patterns across ligation product categories. Surgeons and orthodontists evaluate tensile strength, degradation profiles, and sterilization compatibility when selecting ligature systems for specific anatomical applications.
Product Type:
Cost tier separates commodity elastic consumables from precision-engineered surgical implants with fatigue-resistance specifications.
- Barbed Ligatures:Unidirectional barbs machined from polydioxanone or polyglycolic acid eliminate knot-tying in laparoscopic closures. United States ambulatory surgical centers are converting open procedures to adopt these systems for throughput gains in high-volume settings.
- Elastic Bands:Silicone or latex-based orthodontic ligatures maintain predictable replacement cycles across dental practices worldwide. Germany's orthodontic clusters sustain concentrated procurement volumes through centralized purchasing cooperatives.
- Wire Ligatures:Stainless steel or titanium constructs for vascular surgery retain premium positioning due to ISO 10993 certification burdens and fatigue-resistance testing requirements.
- Power Chains:Continuous elastic chains manufactured from medical-grade polymers deliver controlled orthodontic force application.
- Rubber Ligatures:Natural latex alternatives serve price-sensitive dental markets with shorter replacement intervals.
Elastic Bands lead on scale; Barbed Ligatures lead on momentum.
Application:
Volume concentration follows procedure migration from inpatient settings to outpatient facilities.
- Orthodontic Treatments:Fixed appliance therapy generates recurring silicone ligature consumption through scheduled adjustment appointments. Dental practices in Germany and the United States maintain stable inventory turnover independent of surgical caseload fluctuations.
- Soft Tissue Repair:Laparoscopic hernia and gynecological procedures are accelerating barbed suture adoption. Hospital systems in the United States prioritize closure time reductions that translate to operating room throughput economics.
- Vascular Surgery:Titanium clip applications face EMA MDR biocompatibility testing escalation for implantable devices.
- Periodontal Therapy:Elastic and wire ligatures support splinting procedures for mobile teeth.
- Tissue Approximation:General surgical closure applications span absorbable and non-absorbable material categories.
Orthodontic Treatments anchor volume stability; Soft Tissue Repair commands the steepest expansion trajectory.
End User:
Customer type dictates purchasing authority structure and service bundling expectations.
- Orthodontic Clinics:Specialized practices maintain direct relationships with manufacturers for elastic band replenishment. German dental purchasing cooperatives now mandate itemized pricing transparency for all consumable categories.
- Private Practitioners:Solo and group dental practices route procurement through distributors for consolidated supply management.
- Dental Laboratories:Fabrication facilities source ligature systems as component inputs for appliance construction.
- Medical Universities:Teaching hospitals balance training requirements against cost pressures in surgical ligature selection.
- Research Institutes:Academic centers evaluate novel biodegradable polymer formulations for regulatory submission pathways.
Orthodontic Clinics concentrate procurement volume; Research Institutes drive material innovation pipelines.
Distribution Channel:
Supply chain configuration determines sterilization validation support access and logistics proximity advantages.
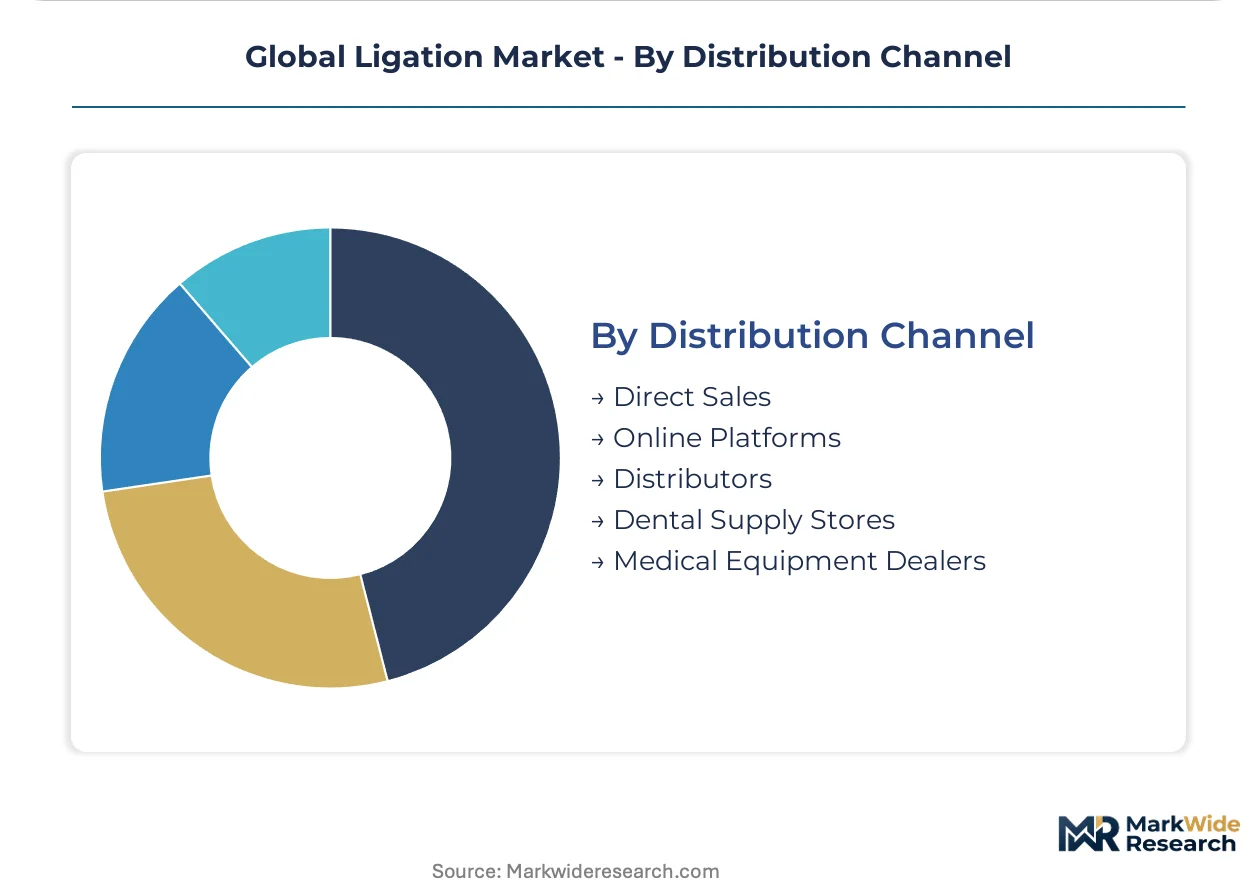
- Distributors:Regional medical supply networks dominate Central European hospital procurement through localized sterilization capabilities. B. Braun Melsungen AG leverages German production footprints to command premium positioning in these channels.
- Direct Sales:Manufacturers with in-house toxicology testing capabilities bypass intermediaries for vascular surgery accounts facing EMA MDR chemical characterization requirements.
- Online Platforms:E-commerce penetration accelerates for standardized orthodontic consumables with established specification clarity.
- Dental Supply Stores:Brick-and-mortar retailers serve emergency replenishment needs for private practitioners.
- Medical Equipment Dealers:Capital equipment vendors bundle ligature systems with clip applier and stapler placements.
Distributors retain volume concentration; Direct Sales gains share fastest among implantable device categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ligation device manufacturing traces its industrial lineage to German precision engineering traditions and post-war American surgical innovation, with contemporary production clustering reflecting these historical foundations alongside emergent Asian supply capabilities.
United States
Ambulatory surgical centers in the United States are converting open procedures to laparoscopic approaches at accelerated rates, creating sustained procurement pull for barbed suture systems. The FDA enforces Class II medical device controls under 21 CFR Part 820, mandating biocompatibility testing that elevates market entry barriers. Hospital systems in Texas and Florida prioritize operating room throughput economics, driving clip applier adoption for closure time reductions.
Germany
Orthopedic and dental clusters in Germany sustain concentrated procurement volumes for advanced ligature systems through centralized purchasing cooperatives. The EU Medical Device Regulation tightens sterility and biocompatibility requirements for implantable devices, rewarding manufacturers with established notified body partnerships. B. Braun Melsungen AG leverages localized production footprints in Melsungen to command premium positioning in Central European hospital channels.
China
Domestic manufacturers in China face procurement pressure from hospital systems seeking cost-competitive alternatives to imported titanium clips. The NMPA implements dual carbon goals that pressure manufacturers to document supply chain emissions for polymer-based elastic bands. Production gravity concentrates in Jiangsu and Zhejiang provinces, where medical device industrial parks offer integrated sterilization infrastructure.
Japan
Aging demographics in Japan are expanding volumes for vascular ligation procedures in tertiary care centers, sustaining demand for fatigue-resistant wire constructs. The PMDA maintains stringent quality system requirements aligned with international standards, extending approval timelines for foreign registrants. Tokyo and Osaka medical device clusters concentrate procurement authority for high-specification surgical ligatures.
India
Private hospital chains in India are expanding laparoscopic surgery capacity, creating import dependency for barbed suture systems where domestic manufacturing remains limited. The CDSCO regulates medical devices under the Drugs and Cosmetics Act, with notified body alignment to international standards accelerating for implantable categories. Mumbai and Delhi-NCR clusters concentrate dental orthodontic practices driving elastic ligature consumption.
Global Ligation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification burden and sterilization infrastructure dimensions, with vascular surgery applications commanding the steepest tier separation. The vendor base organizes into three strategic archetypes: diversified medical technology conglomerates with integrated supply chains, specialized surgical device manufacturers with concentrated R&D portfolios, and regional fabricators serving price-sensitive orthodontic consumables. Dominant competitive moves include backward integration into polymer compounding operations and geographic expansion through sterilization facility partnerships.
Within the diversified conglomerate tier, Ethicon and Medtronic exemplify positioning anchored to parent-network supply chain scale and multi-jurisdictional regulatory dossiers. B. Braun Melsungen AG occupies a position representing European-centric production localization and Central European procurement channel dominance. These three entities collectively illustrate how sterilization infrastructure ownership and notified body relationship depth stratify competitive access across implantable device categories.
| Leading Market Players |
|---|
| Ethicon (Johnson & Johnson) |
| Medtronic |
| Teleflex Incorporated |
| Olympus Corporation |
| Applied Medical Resources |
| CONMED Corporation |
| The Cooper Companies |
| B. Braun Melsungen AG |
| Grena Think Medical |
| Others |
Supply & Pricing Matrix
Centralized purchasing cooperatives in German hospital systems anchor contract-based long-term procurement for implantable ligation devices, entrenching volume-tiered pricing that rewards sterilization infrastructure ownership and notified body certification depth.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates vascular surgery titanium clips from laparoscopic barbed sutures and commodity orthodontic elastic bands. Price differentiation hinges on ISO 10993 certification grade and after-sales sterilization validation bundling. Cost compression in the elastic band tier is intensifying because of polymer raw material volatility and distributor margin stacking. Dental clinics in price-sensitive emerging markets exhibit the highest price sensitivity, while United States ambulatory surgical centers prioritize throughput economics over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China operate hub-and-spoke patterns that position sterilization-validated inventory within 48-hour reach of major hospital clusters. Manufacturing concentration rests on German precision engineering for wire constructs, Chinese polymer compounding for elastic bands, and United States medical device assembly for clip appliers. Titanium sponge feedstock draws from Russian and Chinese smelting operations, creating single-source vulnerability for vascular clip manufacturers. Distribution runs through specialized medical device distributors with captive ethylene oxide sterilization capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Ligation Market represents a late-cycle quality story where EMA MDR biocompatibility escalation and FDA Class II enforcement are filtering demand toward premium-certified manufacturers with in-house toxicology capabilities.
For Market Incumbents: Lock in notified body relationships and sterilization facility partnerships before EMA MDR implementation tightens vendor qualification windows. Deepen backward integration into polymer compounding to defend margin buffers against titanium raw material volatility and absorbable polymer performance limitations that threaten substitution. For New Entrants and Emerging Players: EU Green Deal material sourcing standards in Europe open a window for biodegradable polymer specialists to capture procurement share from petroleum-based elastic band incumbents. Target India's private hospital chains expanding laparoscopic capacity, where import dependency for barbed sutures creates white-space for domestic manufacturing partnerships with sterilization infrastructure providers. For Investors and Strategic Acquirers: Diversified medical technology conglomerates are the most active acquirer in this space, seeking sterilization infrastructure and notified body dossiers to extend vascular surgery positioning. Over a multi-year horizon, acquisition value concentrates in mid-tier surgical device manufacturers with concentrated R&D portfolios and European regulatory registrations. Monitor NMPA carbon documentation compliance as the inflection signal for Chinese market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Expansion | EMA MDR implementation rewards manufacturers with pre-qualified sterilization validation pathways. |
| Biodegradable Polymer Scale-Up | EU Green Deal sourcing standards create first-mover positioning for polylactic acid alternatives. |
| Sterilization Infrastructure Acquisition | Hospital procurement unbundling elevates captive ethylene oxide capacity to competitive differentiator. |
| Central European Production Localization | German orthopedic clusters command premium positioning through logistics proximity and GPO channel access. |
| Carbon Documentation Compliance Program | NMPA dual carbon goals mandate supply chain emissions transparency for polymer-based products. |
Research Methodology
Multiple input streams — hospital procurement database analysis, regulatory filing review, and clinician workflow observation — were reconciled across primary interviews with biomedical engineers, GPO contracts managers, hospital purchasing committee members, and sterilization facility operators, validated against FDA 510(k) clearances, EMA MDR technical documentation, hospital supply chain expenditure records, and ISO 10993 biocompatibility test reports through bottom-up product-category sizing and top-down market consolidation triangulation.
Historical shipment data was cross-referenced against expert panel assessments of laparoscopic procedure conversion rates and orthodontic elastic band replacement cycle stability across the analysis window. Segmentation modeling incorporated material composition tiers, procedural setting categories, end-user purchasing authority structures, and regional regulatory cluster variations. CAGRs were derived from procedure volume elasticity analysis and pricing trajectory synthesis, with specific inputs including ambulatory surgical center capacity expansion schedules and dental practice inventory turnover benchmarks.
Revisions become necessary when EMA notified body capacity constraints extend approval timelines beyond modeled assumptions or when titanium sponge supply disruptions alter input cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Glycomics/Glycobiology Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
North America Proteomics Market
Biomedical Technology
Europe Proteomics Market
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Global RNA Analysis Market
Biomedical Technology
Polymerase Chain Reaction Technologies Market
Biomedical Technology
Structural Biology and Molecular Modeling Techniques Market
Biomedical Technology
Global Expression Vectors Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Global Cell Harvesting Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Biomarker Detection Systems Market