
 Fluorescent in Situ Hybridization Market | 2026-2036
Fluorescent in Situ Hybridization Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorescent in Situ Hybridization Market Foresight
Buyer concentration among large reference laboratories and hospital networks is pivoting procurement toward long-term supply agreements with integrated reagent vendors. Thermo Fisher Scientific leverages its channel breadth to anchor clinical lab contracts across North America. Abbott competes through specialized oncology assay portfolios tied to companion diagnostic pathways. Bio-Rad Laboratories sustains R&D intensity in probe chemistry, differentiating its position in research-grade applications.
Fluorescent in situ hybridization employs fluorescently labeled DNA or RNA probes that hybridize to complementary target sequences within fixed cells or tissue sections, enabling chromosomal localization and gene copy number assessment with spatial resolution down to single-cell level. The technique serves primarily as a diagnostic and research tool for detecting genetic aberrations associated with cancer, congenital disorders, and infectious pathogens. Probes and reagent kits command the largest share of product-type revenue, reflecting recurring consumable demand tied to test volume. Oncology applications generate the fastest expansion within the application dimension, driven by HER2, ALK, and EGFR testing protocols. Diagnostic laboratories represent the most concentrated end-user margin pool, though biotechnology firms are expanding in-house FISH capabilities for target validation.
The US FDA and EMA jointly shape market access through companion diagnostic co-development requirements and quality system regulations governing in vitro diagnostic manufacture. ISO 15189 accreditation standards and CLIA laboratory certification in the United States enforce analytical performance benchmarks that filter probe kit suppliers. Stakeholders must monitor evolving payer coverage policies for FISH-based tests, as reimbursement determinations increasingly influence laboratory menu decisions and manufacturer pricing authority.
Market Dynamics
Companion diagnostic co-development requirements from the US FDA and EMA are compressing probe kit validation timelines while elevating analytical performance benchmarks that filter supplier qualification.
Growth Catalysts
- Companion diagnostic mandates:The FDA's expanding guidance on nucleic acid-based companion diagnostics accelerates assay standardization for oncology applications. Clinical diagnostic laboratories expand FISH-based testing menus to capture HER2, ALK, and EGFR testing protocols.
- Spatial resolution demands:Single-cell genomics research is overtaking bulk sequencing approaches in academic medical centers. Biotechnology firms build in-house FISH capabilities for target validation workflows.
- ISO 15189 enforcement:Laboratory accreditation standards in the United States and European Union enforce analytical performance benchmarks. Probe kit suppliers must maintain quality system documentation to retain contract eligibility.
Market Restraints
- Fluorophore supply concentration:Specialized dye chemistries for probe labeling concentrate among a limited set of chemical suppliers. Price volatility in rhodamine and cyanine derivatives squeezes reagent kit margins.
- Technical throughput ceilings:Manual slide preparation and hybridization protocols limit batch processing capacity. Automated platforms require substantial capital outlay that mid-sized laboratories defer.
- Reimbursement compression:Payer coverage policies for FISH-based tests tighten prior authorization requirements. Medicare Administrative Contractors in the United States impose documentation burdens that slow test adoption.
Strategic Opportunities
- India diagnostic expansion:CDSCO regulatory pathways for in vitro diagnostics are streamlining. Private hospital networks in Mumbai and Delhi build molecular pathology capabilities that absorb research-grade probe systems.
- Digital pathology convergence:Whole-slide imaging platforms integrate fluorescence capture modules. Pathology departments consolidate brightfield and FISH workflows on unified scanners.
- China NMPA harmonization:The National Medical Products Administration aligns technical review standards with IMDRF guidelines. Domestic manufacturers gain accelerated approval for oncology companion diagnostic kits.
Industry Challenges
- Cytogenetic technologist shortage:Specialized training programs for fluorescence microscopy and probe interpretation have contracted. Reference laboratories compete for ASCP-certified personnel who can validate complex assays.
- CLIA certification timelines:Laboratory certification requirements for high-complexity testing extend implementation schedules. New test menu additions require protracted proficiency testing documentation.
- Legacy LIS integration:Laboratory information systems in established cancer centers lack native support for fluorescence image metadata. Custom interface development adds cost and delay to platform deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorescent in Situ Hybridization Market |
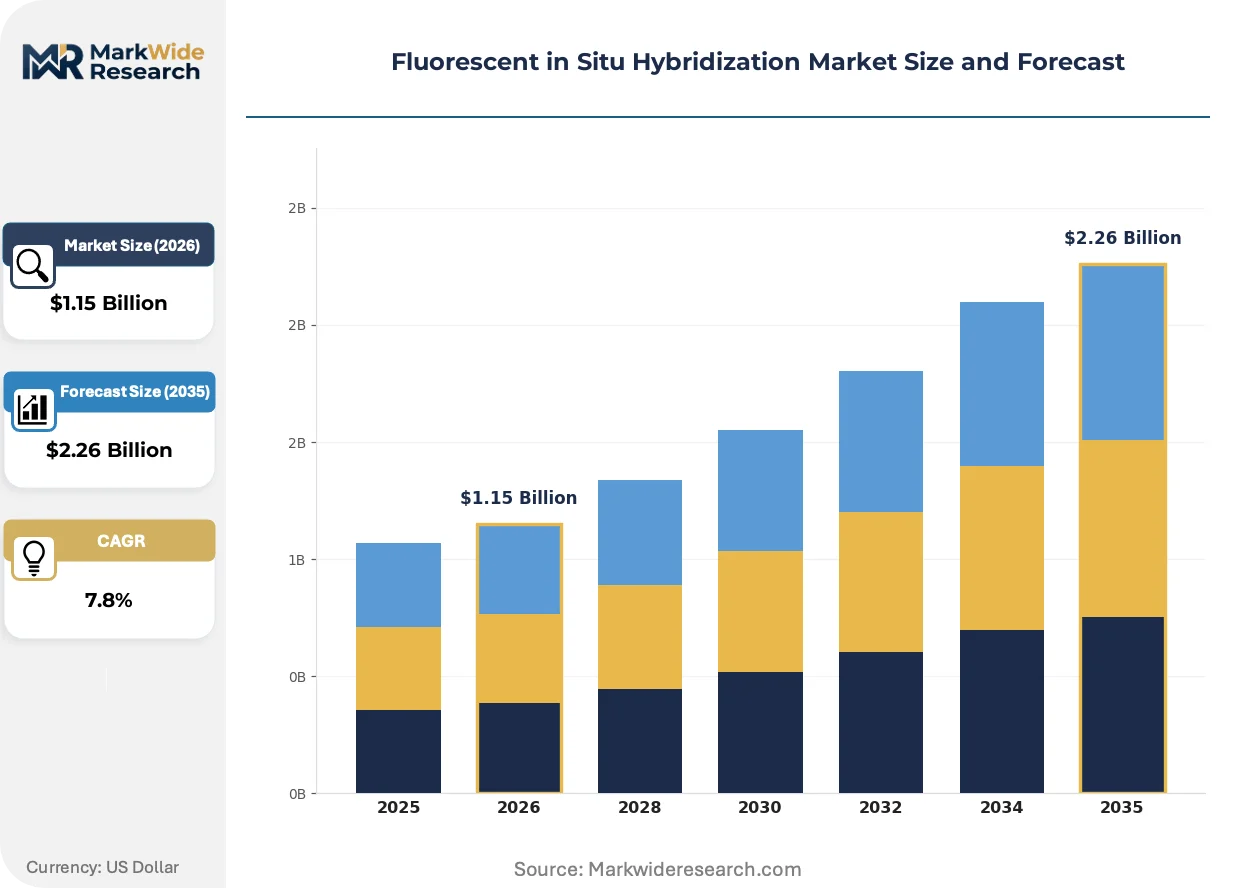
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.26 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probes, Reagents, Kits, Instruments, Software Application: Genetic Disorder Diagnosis, Oncology, Infectious Disease Detection, Prenatal Screening, Research & Development End User: Diagnostic Laboratories, Academic Research Centers, Pharmaceutical Companies, Biotechnology Firms, Forensic Laboratories Technology: Direct Labeling, Indirect Labeling, Peptide Nucleic Acid, Multiplex FISH |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, Abbott, F. Hoffmann-La Roche Ltd, PerkinElmer, Merck KGaA, Bio-Rad Laboratories, Leica Biosystems Nussloch GmbH, Genemed Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorescent in Situ Hybridization Market Shifts & Advancements
Multiplex probe architectures and automated scoring algorithms are compressing turnaround times while expanding the genetic aberration panel density per tissue section.
Chromogenic in situ hybridization is overtaking standard fluorescence protocols in anatomic pathology departments. CISH eliminates the need for specialized fluorescence microscopes while preserving chromogenic visualization compatible with routine hematoxylin and eosin stains. Community hospital laboratories in the United States adopt CISH for HER2 testing to avoid capital investment in darkroom-equipped microscopy suites.
The EU In Vitro Diagnostic Regulation (IVDR) reclassifies most FISH-based companion diagnostic kits as Class C devices. Manufacturers must submit technical documentation and performance evaluation reports to notified bodies for CE marking renewal. European reference laboratories are consolidating supplier relationships to reduce the qualification burden associated with multiple vendor IVDR certifications.
Consolidated procurement through integrated delivery networks is displacing decentralized laboratory purchasing. Large health systems in the United States negotiate enterprise-wide reagent contracts that bundle FISH probe kits with histology consumables. Hospital network supply chain directors extract volume-based pricing concessions that independent oncology practices cannot match.
Fluorescent in Situ Hybridization Market Segmentation
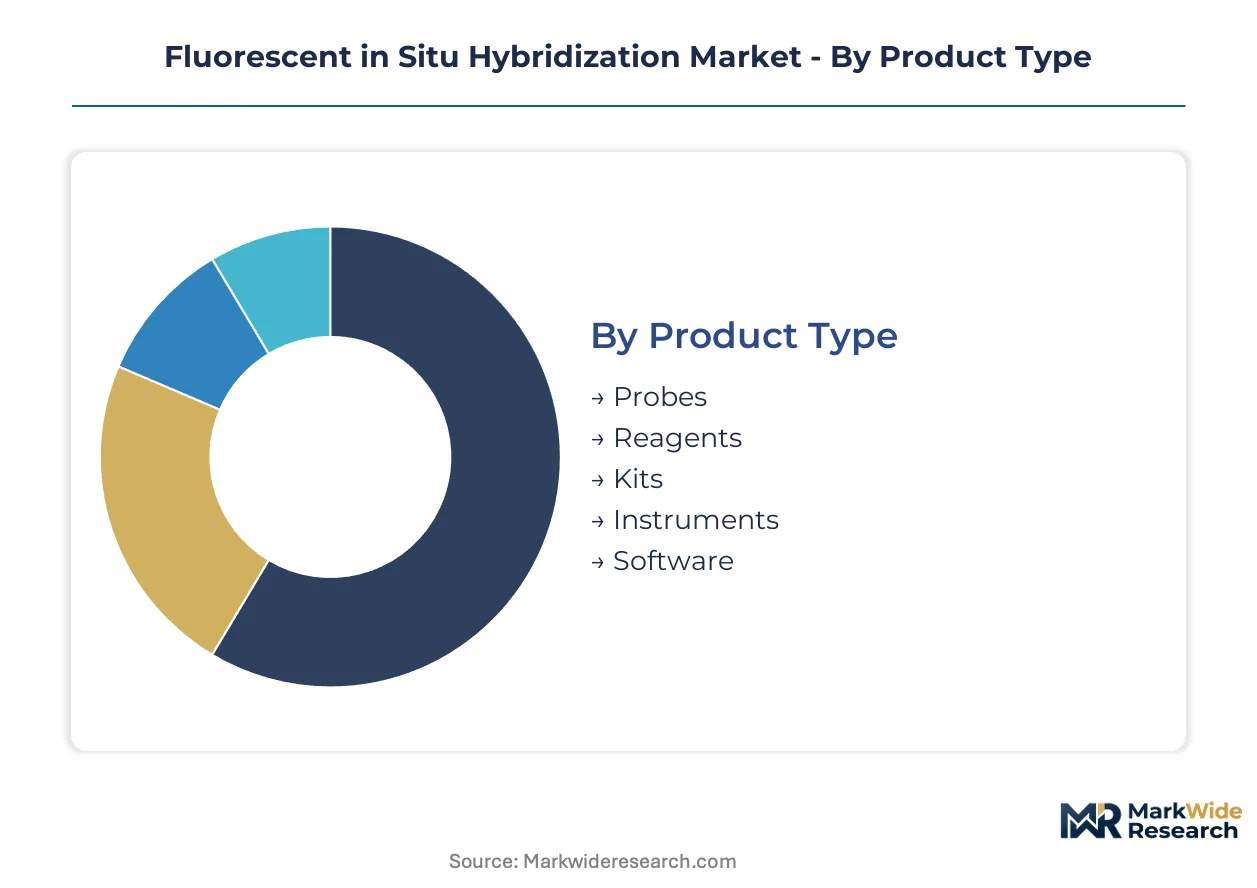
Segmentation in the FISH market reveals distinct margin structures across consumables versus capital equipment, with probe chemistry and reagent kits commanding recurring revenue streams that anchor supplier profitability. Understanding these divisions clarifies where procurement leverage concentrates and which technology platforms drive replacement cycles.
Product Type:
Supply concentration in fluorophore chemistries and probe manufacturing infrastructure shapes competitive positioning across consumable and instrument categories.
- Probes:Fluorescently labeled DNA or RNA sequences designed for chromosomal localization and gene copy number assessment. Academic medical centers in the United States absorb the bulk of research-grade probe demand as single-cell genomics workflows expand.
- Reagents:Specialized buffers, hybridization solutions, and counterstains optimized for tissue permeabilization and signal amplification. Price volatility in rhodamine and cyanine derivatives squeezes kit margins for diagnostic laboratories running high-volume oncology protocols.
- Kits:Pre-configured assay systems bundling probes, reagents, and protocols for standardized testing menus. CDSCO regulatory streamlining in India is accelerating kit adoption among private hospital networks building molecular pathology capabilities.
- Instruments:Fluorescence microscopes, automated hybridization platforms, and imaging systems enabling spatial resolution down to single-cell level. Capital outlay requirements limit batch processing capacity expansion at mid-sized laboratories.
- Software:Image analysis algorithms and laboratory information system interfaces supporting probe interpretation and fluorescence metadata management. Legacy LIS integration challenges delay platform deployments at established cancer centers.
Probes and reagent kits absorb the bulk of installed capacity; automated instruments and scoring software are expanding most quickly as laboratories pursue throughput gains.
Application:
Cost tier differentiation separates high-complexity companion diagnostic protocols from standardized screening applications, with reimbursement policies filtering test menu decisions.
- Oncology:HER2, ALK, and EGFR testing protocols for companion diagnostic pathways and targeted therapy selection. Medicare Administrative Contractors in the United States impose prior authorization documentation burdens that slow test adoption.
- Genetic Disorder Diagnosis:Chromosomal aberration detection for congenital conditions including microdeletion syndromes and aneuploidies. Reference laboratories compete for ASCP-certified cytogenetic technologists who can validate complex assays.
- Infectious Disease Detection:Pathogen identification through ribosomal RNA targeting in fixed tissue sections. Clinical diagnostic laboratories expand testing menus as FDA guidance on nucleic acid-based diagnostics accelerates assay standardization.
- Prenatal Screening:Fetal chromosomal analysis via amniotic fluid or chorionic villus sampling. Reimbursement compression limits menu expansion at independent obstetric practices.
- Research & Development:Target validation workflows and spatial transcriptomics applications in drug discovery. Biotechnology firms build in-house FISH capabilities to reduce reliance on contract research organizations.
Oncology applications absorb the bulk of installed capacity; research and development workflows are climbing the fastest as pharmaceutical companies internalize target validation.
End User:
Customer type determines procurement modality, with consolidated health systems extracting volume concessions unavailable to decentralized purchasers.
- Diagnostic Laboratories:High-complexity testing facilities running standardized oncology and genetic screening protocols. Integrated delivery networks in the United States negotiate enterprise-wide reagent contracts bundling FISH probe kits with histology consumables.
- Biotechnology Firms:Drug developers building internal spatial genomics capabilities for target validation and biomarker discovery. Single-cell genomics research is overtaking bulk sequencing approaches in this segment.
- Academic Research Centers:Institutions pursuing fundamental chromosomal biology and technology development. EU IVDR reclassification of companion diagnostic kits is consolidating supplier relationships to reduce qualification burdens.
- Pharmaceutical Companies:Organizations co-developing companion diagnostics alongside therapeutic pipelines. FDA and EMA joint requirements compress probe kit validation timelines while elevating analytical performance benchmarks.
- Forensic Laboratories:Facilities applying FISH to DNA mixture interpretation and kinship analysis. Specialized training program contraction limits technologist availability for fluorescence microscopy protocols.
Diagnostic laboratories absorb the bulk of installed capacity; biotechnology firms are gaining share fastest as in-house FISH capabilities displace outsourced workflows.
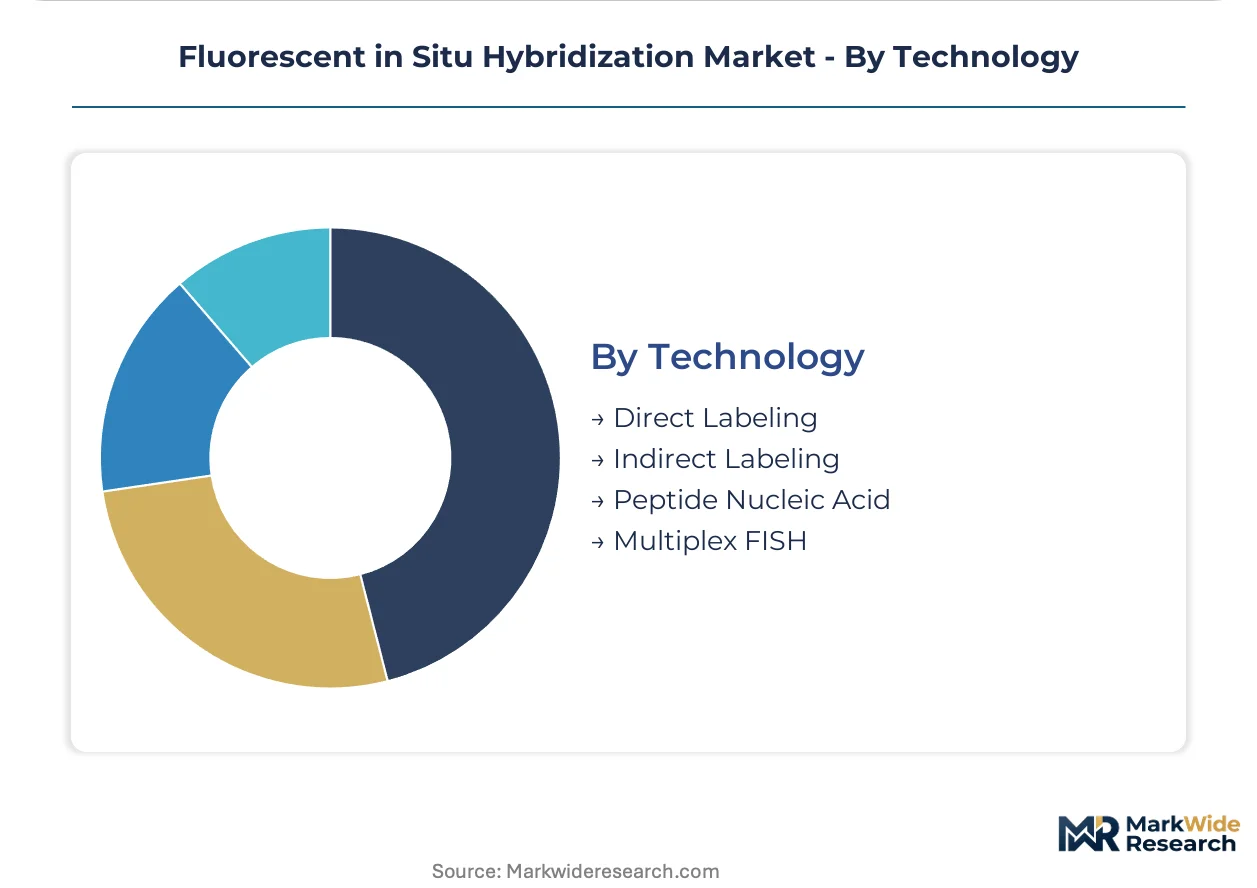
Technology:
Maturity gradients separate established labeling chemistries from emerging multiplex architectures, with automation readiness determining platform selection criteria.
- Direct Labeling:Fluorophore conjugation directly to probe nucleic acid sequences without antibody amplification. Chromogenic in situ hybridization variants eliminate specialized fluorescence microscope requirements for community hospital laboratories.
- Multiplex FISH:Simultaneous detection of multiple genetic targets using spectrally distinct fluorophores per tissue section. Whole-slide imaging platforms integrate fluorescence capture modules as pathology departments consolidate brightfield and FISH workflows.
- Indirect Labeling:Hapten incorporation followed by fluorophore-conjugated antibody detection for signal amplification. Batch processing limitations from manual slide preparation constrain throughput at high-volume facilities.
- Peptide Nucleic Acid:Synthetic nucleic acid analogs with neutral peptide backbones enabling enhanced hybridization specificity. Research-grade applications dominate as clinical validation timelines extend under CLIA certification requirements.
Direct labeling absorbs the bulk of installed capacity; multiplex FISH architectures are expanding most quickly as probe density per section drives efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic laboratories in the United States consume the largest probe kit volumes, while biotechnology clusters in Germany and India are accelerating in-house FISH capability builds. Regulatory harmonization across FDA, EMA, and NMPA jurisdictions is compressing validation timelines for companion diagnostic co-developments.
United States
Reference laboratories and cancer centers in Boston and Houston drive probe kit consumption for HER2, ALK, and EGFR testing protocols. FDA guidance on nucleic acid-based companion diagnostics accelerates assay standardization across CLIA-certified high-complexity facilities. The Southeast corridor from Atlanta to Nashville attracts cytogenetic technologists as academic medical centers expand single-cell genomics workflows.
Germany
EU IVDR reclassification of FISH-based companion diagnostic kits as Class C devices is consolidating supplier relationships among European reference laboratories. EMA quality system regulations enforce analytical performance benchmarks that filter probe kit vendors. The Rhine-Ruhr and Munich clusters host pathology departments integrating whole-slide imaging platforms with fluorescence capture modules.
China
NMPA alignment with IMDRF technical review standards accelerates domestic manufacturer approvals for oncology companion diagnostic kits. Private hospital networks in Shanghai and Beijing build molecular pathology capabilities that absorb research-grade probe systems. The Yangtze River Delta concentrates fluorescence microscope distribution channels serving biotechnology firms internalizing target validation.
India
CDSCO regulatory streamlining for in vitro diagnostics enables private hospital networks in Mumbai and Delhi to expand FISH-based testing menus. BIS laboratory accreditation standards enforce analytical performance benchmarks for diagnostic facilities. The Bangalore-Hyderabad corridor attracts biotechnology firms building in-house spatial genomics capabilities for drug discovery workflows.
Japan
PMDA quality system regulations govern in vitro diagnostic manufacture alongside METI industrial policy supporting precision medicine infrastructure. Academic medical centers in Tokyo and Osaka adopt multiplex FISH architectures for spatial transcriptomics research. The Kansai region concentrates peptide nucleic acid probe development for enhanced hybridization specificity applications.
Fluorescent in Situ Hybridization Market Competitive Landscape
United States producers anchor one tier; European specialists hold quality-system certifications that filter Asian entrants. The vendor base separates into three tiers: integrated life science conglomerates with channel breadth, specialized diagnostics firms with companion diagnostic portfolios, and regional reagent suppliers serving research-grade demand. Two dominant competitive moves are emerging: long-term supply agreements with integrated delivery networks and IVDR certification consolidation to reduce European qualification burdens.
Among integrated life science conglomerates, Thermo Fisher Scientific and Agilent Technologies exemplify the channel-anchored archetype. Abbott and F. Hoffmann-La Roche Ltd occupy positions within the companion diagnostic co-development tier. Bio-Rad Laboratories and Merck KGaA sit within the research-grade reagent specialization segment. Leica Biosystems Nussloch GmbH represents the European microscopy-instrumentation archetype. PerkinElmer and Genemed Technologies anchor mid-scale diagnostic reagent supply positions.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| Abbott |
| F. Hoffmann-La Roche Ltd |
| PerkinElmer |
| Merck KGaA |
| Bio-Rad Laboratories |
| Leica Biosystems Nussloch GmbH |
| Genemed Technologies |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between IVDR Class C companion diagnostic kits and research-grade probe systems manifests in divergent pricing architectures and sourcing configurations. Premium-tier suppliers anchor long-term contracts with integrated delivery networks through bundled reagent agreements, while commodity probe vendors compete on spot pricing for academic procurement.
Pricing Analysis
Volume-versus-margin splits separate high-throughput diagnostic laboratories from boutique research facilities. A three-tier pricing structure across premium, standard, and economy levels reflects differentiation by FDA/EMA co-development certification, ISO 15189 accreditation status, and after-sales technical support depth. Cost compression in economy-tier research probes intensifies as fluorophore supply concentration in rhodamine and cyanine derivatives squeezes kit margins. Mid-sized reference laboratories exhibit highest price sensitivity, while pharmaceutical companion diagnostic co-developers prioritize analytical performance over unit cost.
Supply Chain Analysis
Domestic-content mandates from China's NMPA and India's CDSCO are reshaping sourcing patterns for probe manufacturing and fluorescence microscope assembly. Specialty dye chemistries concentrate supply in Germany, Switzerland, and Japan, while optical component fabrication centers on China and South Korea. Raw material dependencies span high-purity rhodamine derivatives, cyanine fluorophores, and precision optical glass. Single-source vulnerability in specialized hybridization buffer formulations threatens continuity. Distribution runs through integrated life science distributors serving hospital networks and direct procurement channels for pharmaceutical developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over fluorophore chemistry and automated scoring algorithms determines contract eligibility. Players are pursuing backward integration into probe synthesis to escape dye supply volatility.
For Market Incumbents: Lock in multi-year supply agreements with integrated delivery networks before IVDR certification consolidation reduces vendor pools. Invest in captive fluorophore production capacity to neutralize rhodamine and cyanine price volatility. Defend against chromogenic in situ hybridization substitution by bundling darkroom-free imaging platforms with traditional FISH workflows.
For New Entrants and Emerging Players: Community hospital laboratories in the United States represent the most penetrable buyer archetype, underserved by automated platform vendors targeting high-complexity cancer centers. Target CISH-compatible probe systems that eliminate fluorescence microscope capital requirements. Pursue CDSCO fast-track pathways for private hospital networks in Mumbai and Delhi building first-time molecular pathology capabilities.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated life science conglomerates seeking companion diagnostic assay portfolios. Long-term viability hinges on FDA/EMA dual-approval track records and installed base conversion to automated scoring software. Monitor NMPA harmonization progress as the inflection signal for Chinese domestic manufacturer consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Certification Consolidation | Reduces European supplier qualification burden for reference laboratories. |
| Automated Scoring Algorithm Development | Compresses turnaround times for HER2 and ALK testing protocols. |
| Fluorophore Backward Integration | Neutralizes rhodamine and cyanine derivative price volatility. |
| CDSCO Regulatory Fast-Track | Accelerates kit adoption in Mumbai and Delhi hospital networks. |
| CISH Platform Launch | Eliminates darkroom investment for community hospital laboratories. |
Research Methodology
Independent corroboration across laboratory directors, regulatory affairs specialists, and procurement officers at integrated delivery networks underwrites the qualitative findings. Primary interviews with cytogenetic technologists, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA companion diagnostic submissions, and CMS Medicare reimbursement databases. Bottom-up probe kit volume estimates triangulate against top-down diagnostic laboratory capacity assessments.
Rate-of-change decomposition separates volume growth from mix shift and pricing dynamics across the analysis window. Segmentation dimensions encompass product type, application pathway, end-user procurement modality, and technology maturity tier. CAGRs derive from installed base expansion rates, test menu additions, and replacement cycle timing for automated hybridization platforms. Forecast inputs incorporate CLIA certification timeline trajectories and payer prior authorization policy evolution.
Revisions become necessary when fluorophore supply disruptions, IVDR implementation delays, or Medicare reimbursement compression materialize beyond modeled scenarios. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
France Flow Cytometry Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
Europe Transfection Technologies Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
Macrophage Marker Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Drug Discovery Enzymes Market
Biomedical Technology
Global Drug Discovery Technologies Market
Biomedical Technology
PD L1 Biomarker Testing Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Global Oncology Based in-Vivo CRO Market
Biomedical Technology
Southern Blotting Market