
 Coated Solar Control Glass Market | 2026-2036
Coated Solar Control Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Solar Control Glass Market Analysis
Chinese flat-glass producers is pivoting toward solar-control coating capacity to serve domestic green-building mandates. AGC Inc. leverages its sputter-coating expertise to anchor premium facade contracts across East Asia. SAINT-GOBAIN sustains technology leadership through integrated low-emissivity R&D pipelines. PPG Industries competes on specialized reflective coatings for high-solar-gain climates.
Coated solar control glass consists of flat glass substrates bearing thin-film metallic or metal-oxide layers, typically applied via magnetron sputtering or pyrolytic deposition, engineered to transmit visible light while reflecting infrared solar radiation to reduce cooling loads. The primary commercial purpose is to cut HVAC energy consumption in buildings and improve cabin thermal comfort in vehicles. Low-E glass dominates value capture due to stringent thermal insulation codes, while sputter coating leads technology investment because of its precision in layer thickness control and spectral selectivity. Vacuum coating occupies a smaller but defensible niche in aerospace glazing where weight and optical clarity constraints are acute.
Building regulators in the European Union enforce the Energy Performance of Buildings Directive and CE marking for construction products, compelling specifiers to source certified solar-control glazing. The US EPA and state-level stretch codes such as California's Title 24 shape demand by mandating envelope thermal performance thresholds that coated glass satisfies. China's GB standards for building energy efficiency and its dual carbon goals are tightening permissible heat-gain coefficients, directly expanding addressable volume for coated products. Stakeholders must monitor how tightening national building codes and carbon-border adjustments reshape procurement criteria and supplier qualification requirements.
Market Dynamics
Building envelope thermal performance mandates are compressing specification windows for glazing contractors. The EU Green Deal and China's dual carbon goals are forcing rapid substitution of conventional float glass with spectrally selective coated alternatives.
Growth Catalysts
- EU Energy Performance of Buildings Directive:The directive tightens permissible U-values for commercial facades, compelling developers in Germany and France to specify triple-silver low-E coatings.
- Automotive cabin thermal management:Electric vehicle manufacturers are integrating solar-control windscreens to reduce HVAC drain on battery range.
- Magnetron sputtering precision:Advances in layer thickness control enable custom spectral selectivity for high-latitude versus tropical climates.
Market Restraints
- Silver price volatility:Sputter coatings rely on silver layers; London Metal Exchange price swings compress coating margins unpredictably.
- Float glass supply concentration:Five Chinese producers control over sixty percent of substrate availability, creating bottleneck risk for coaters elsewhere.
- Pyrolytic coating performance ceiling:Online chemical vapor deposition achieves lower optical precision than offline sputtering, limiting its suitability for premium commercial projects.
Strategic Opportunities
- India green building acceleration:GRIHA certification adoption in Mumbai and Bangalore commercial towers is opening volume for imported low-E glass.
- Building-integrated photovoltaics convergence:Coatings that combine solar control with semi-transparent PV generation are capturing pilot contracts in Singapore and Dubai.
- Retrofit channel development:Secondary glazing specialists are developing cut-to-size coated panel programs for 1970s office stock in London and New York.
Industry Challenges
- Magnetron sputter technician scarcity:Vacuum coating expertise concentrates in Japan and Germany, constraining capacity expansion elsewhere.
- CE marking timeline compression:Construction product regulation compliance now requires extended fire-performance testing, delaying project bids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Solar Control Glass Market |
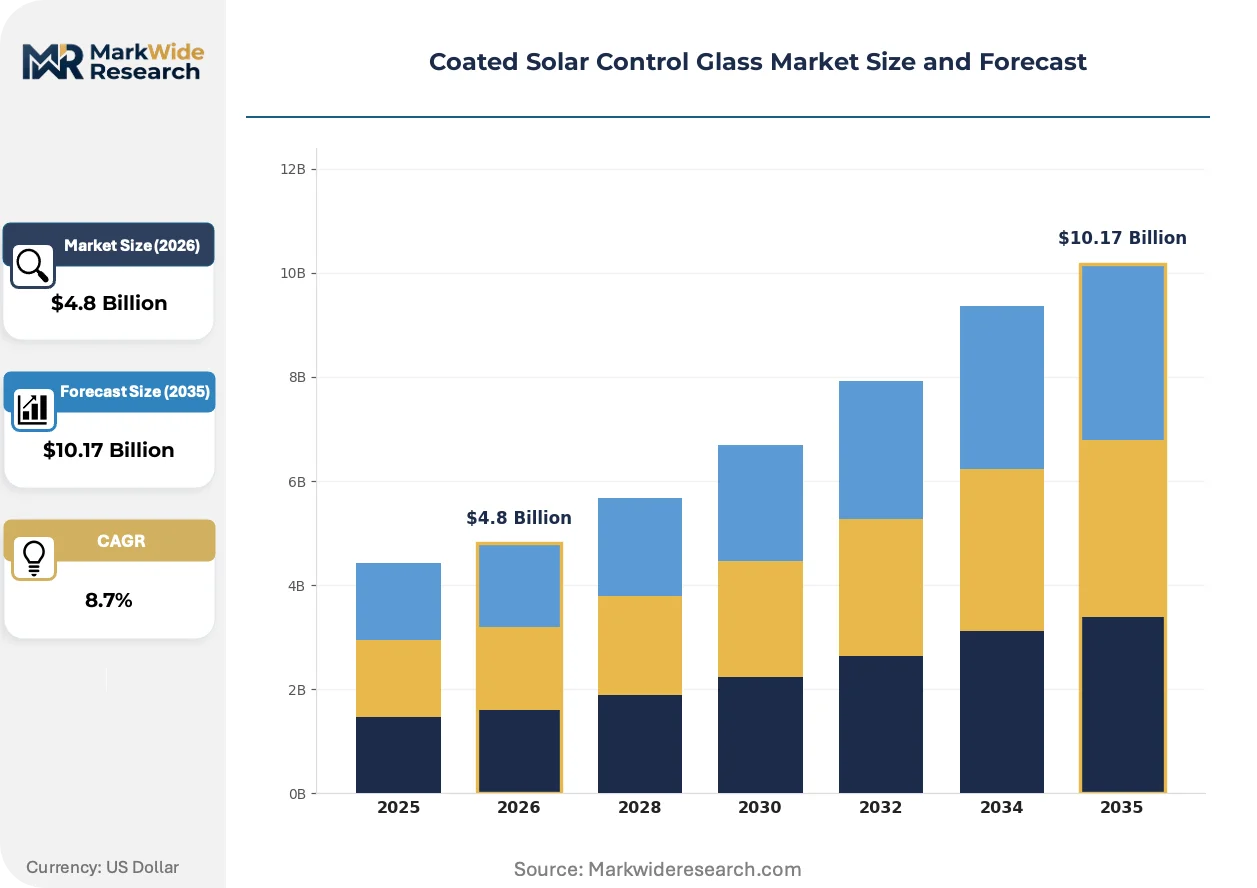
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Glass, Tinted Glass, Reflective Glass, Low-E Glass Technology: Thin Film Coating, Vacuum Coating, Sputter Coating, Chemically Strengthened End User: Commercial Buildings, Residential Properties, Automotive Industry, Aerospace Sector Application: Facade Glazing, Skylights, Windows, Sunrooms |
| Companies Covered | PPG Industries, EUROGLAS, AGC Inc., Nippon Sheet Glass Co., Ltd., CSG Holding Co., Ltd., Guardian Industries, Central Glass Co., Ltd., Sisecam, SAINT-GOBAIN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Solar Control Glass Market Emerging Trajectories
Coating stack architectures are evolving from single-function solar rejection toward multifunctional layers that manage thermal, optical, and electrical properties simultaneously. This convergence is redrawing competitive boundaries between glass coaters and thin-film electronics specialists.
Electrochromic glazing is expanding into high-end commercial facades where dynamic tint adjustment replaces static solar-control coatings. AECOM and Foster + Partners are specifying these systems for Middle Eastern headquarters towers. The technology is expanding into markets previously dominated by fixed low-E glass, compressing premium pricing power for conventional sputtered products.
China's GB standards for building energy efficiency are tightening permissible solar heat gain coefficients on a province-by-province basis. The MIIT enforcement timeline is accelerating retrofit demand in Shanghai and Shenzhen commercial stock. Northern European suppliers are responding by pre-certifying coating stacks to accelerated Chinese test protocols.
Façade engineers are bundling glazing specification with performance guarantees that cover installed U-value and g-value outcomes. This shifts risk from building owners to coating suppliers and integrators. The model is most visible in German and Austrian commercial developments where energy-plus building standards dominate procurement criteria.
Coated Solar Control Glass Market Segmentation
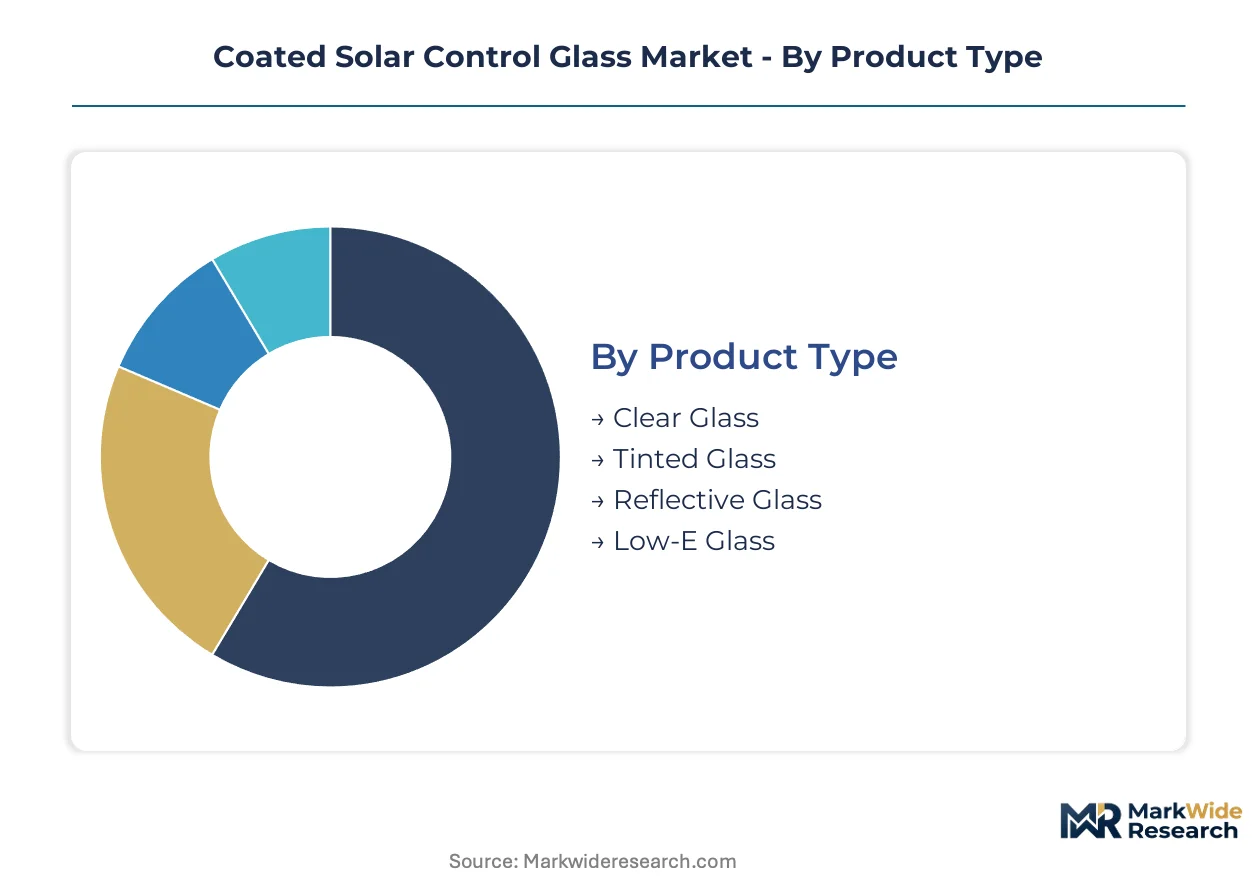
Segmentation in coated solar control glass reveals how substrate choices, deposition methods, and end-use specifications fragment procurement requirements. Specification engineers must match thermal performance targets against coating durability, optical clarity, and installation geometry constraints.
Product Type:
Supply concentration in float glass manufacturing has concentrated premium substrate availability among integrated producers, forcing coaters to align product portfolios with captive glass sourcing.
- Low-E Glass:Multi-layer silver or metal-oxide stacks engineered for thermal insulation with high visible light transmission. German and French commercial facade developers specify triple-silver configurations to meet EU Energy Performance of Buildings Directive U-value ceilings.
- Reflective Glass:Single or double-layer metallic coatings that reject solar gain through high exterior reflectance. Demand clusters in Dubai and Singapore high-rise towers where cooling load reduction dominates over daylight harvesting priorities.
- Tinted Glass:Body-colored substrates with absorptive solar control properties, typically iron or cobalt doped. Mumbai commercial developers specify grey and bronze tints for GRIHA-certified projects requiring cost-effective heat gain reduction.
- Clear Glass:Uncoated or minimally treated soda-lime substrates serving as base material for secondary coating operations or budget-conscious residential applications in price-sensitive markets.
Today's leader: Low-E Glass. Tomorrow's challenger: Reflective Glass.
Technology:
Cost tier differentiation separates precision deposition methods from commodity chemical treatments, with capital intensity determining regional technology adoption patterns.
- Sputter Coating:Magnetron sputtering deposits nanometer-precise metal and metal-oxide layers in vacuum chambers, enabling custom spectral selectivity. Japanese and German equipment suppliers dominate turnkey line installation, constraining capacity expansion in emerging markets.
- Thin Film Coating:Liquid-applied or spray-deposited organic-inorganic hybrids for moderate-performance applications. Automotive OEMs in Stuttgart and Detroit specify thin-film windscreen treatments to manage cabin thermal load without electromagnetic interference.
- Vacuum Coating:Specialized electron-beam or thermal evaporation for aerospace glazing where weight minimization and optical clarity constraints exclude atmospheric deposition methods.
- Chemically Strengthened:Ion-exchange surface hardening combined with solar-control functionality for impact-resistant architectural and transportation glazing. Shenzhen metro system specifications require chemically strengthened low-E panels for platform screen doors.
Sputter Coating commands premium pricing power. Thin Film Coating is climbing the fastest as automotive volumes scale.
End User:
Application-specific performance certification requirements fragment demand across building codes, automotive safety standards, and aerospace material qualifications.
- Commercial Buildings:Curtain wall and storefront systems requiring documented U-values and g-values for energy code compliance. London and New York retrofit specialists are developing cut-to-size coated panel programs for 1970s office stock.
- Automotive Industry:Laminated windscreens and sidelites with integrated solar-control and defogging functionality. Electric vehicle manufacturers in California integrate solar-control glazing to reduce HVAC battery drain.
- Residential Properties:Window replacement and new construction markets driven by state-level stretch codes and utility rebate programs. California Title 24 thermal performance thresholds shape specification patterns.
- Aerospace Sector:Cockpit transparencies and cabin windows requiring simultaneous solar rejection, de-icing capability, and bird-strike resistance. Montreal and Toulouse airframe integrators qualify coating suppliers to AS9100 standards.
Commercial Buildings anchor current volume. Automotive Industry shows steepest expansion trajectory as electrification accelerates.
Application:
Installation geometry and exposure conditions determine coating durability requirements, with vertical facades, overhead glazing, and angled surfaces each demanding distinct stack architectures.
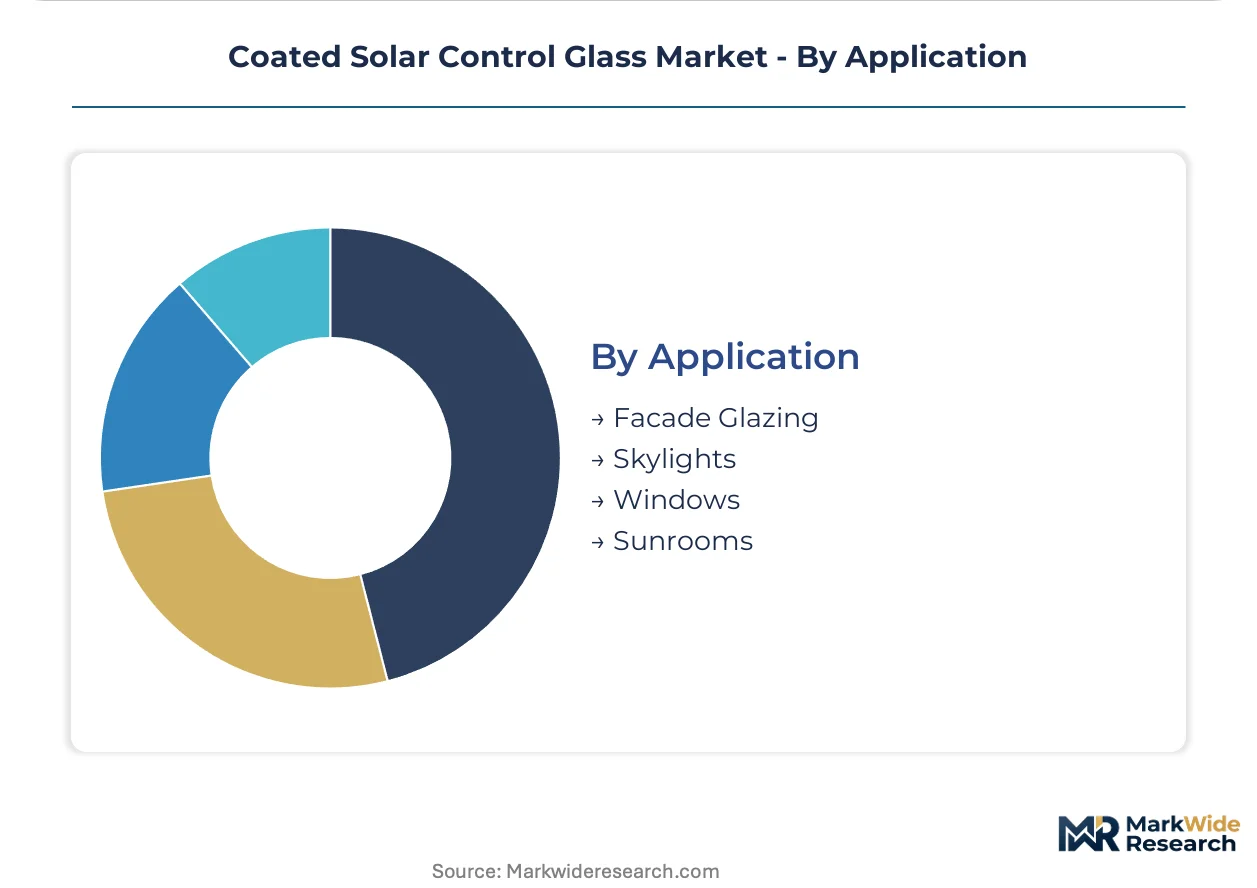
- Facade Glazing:Large-format insulated glass units for curtain walls and rainscreen systems. Foster + Partners specifications in Middle Eastern headquarters towers are integrating electrochromic alternatives to static coatings.
- Windows:Operable and fixed fenestration in commercial and residential construction. Shanghai and Shenzhen GB standard enforcement is accelerating replacement of single-pane float with low-E retrofits.
- Skylights:Overhead glazing requiring enhanced UV resistance and thermal performance to manage solar gain from direct overhead exposure. Singapore pilot projects are testing semi-transparent PV-integrated solar-control coatings.
- Sunrooms:Residential conservatory and greenhouse structures prioritizing visible light transmission with moderated solar gain. Bangalore residential developers specify selective coatings for year-round usability.
Facade Glazing dominates specification value. Skylights are gaining share fastest as daylighting mandates spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coating capacity migrates toward jurisdictions where energy-code enforcement creates premium demand but substrate availability constrains local supply. This arbitrage pulls investment toward China and India while European coaters defend position through certification complexity.
China
Shanghai and Shenzhen commercial towers drive coated glass volumes under tightening GB energy efficiency standards. MIIT enforcement timelines compress retrofit windows for 1970s office stock. Yangtze River Delta fabricators expand sputter-coating lines to serve domestic green-building mandates.
Germany
Triple-silver low-E specifications dominate Frankfurt and Munich facade contracts under EU Energy Performance of Buildings Directive U-value ceilings. CE marking and fire-performance testing extend project qualification timelines. Bavarian coating specialists anchor premium contracts across Alpine climate zones.
United States
California Title 24 thermal performance thresholds shape specification patterns from Los Angeles to San Francisco. EPA and state-level stretch codes mandate envelope performance that coated glass satisfies. Pacific Northwest developers specify high-transmission variants for daylighting-optimized commercial cores.
India
Mumbai and Bangalore commercial towers adopt GRIHA certification, opening volume for imported low-E glass. BIS standards for building envelope materials tighten procurement criteria. Maharashtra fabricators develop cut-to-size coated panel programs for retrofit channels.
United Arab Emirates
Dubai and Abu Dhabi high-rise towers prioritize cooling-load reduction over daylight harvesting in glazing specifications. MOHAP and local building codes enforce thermal performance thresholds for new commercial stock. Sharjah-based integrators qualify coating suppliers for Middle Eastern headquarters projects.
Coated Solar Control Glass Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue automotive and retrofit specializations. The vendor base clusters around integrated glass manufacturers with captive float substrate supply and independent coaters dependent on merchant sourcing. Three archetypes dominate: integrated multinationals with full-stack coating capability, regional fabricators serving protected domestic markets, and automotive-focused specialists leveraging thin-film expertise. Competitive moves concentrate on backward integration into float glass production and pre-certification of coating stacks to accelerated test protocols.
Among integrated multinationals, AGC Inc., SAINT-GOBAIN, and PPG Industries exemplify the premium-tier vector. AGC Inc. represents Japanese sputter-coating expertise anchored in East Asian facade contracts. SAINT-GOBAIN occupies a position within European technology leadership through integrated low-emissivity development pipelines. PPG Industries exemplifies specialized reflective coating capability for high-solar-gain climate applications.
| Leading Market Players |
|---|
| PPG Industries |
| EUROGLAS |
| AGC Inc. |
| Nippon Sheet Glass Co., Ltd. |
| CSG Holding Co., Ltd. |
| Guardian Industries |
| Central Glass Co., Ltd. |
| Sisecam |
| SAINT-GOBAIN |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed Chinese float-glass producers anchor substrate supply, compressing margin capture for independent coaters while enforcing pricing discipline across premium and standard tiers. Their captive energy costs and state-supported capacity expansions reshape how coating specialists in Germany and Japan defend pricing power.
Pricing Analysis
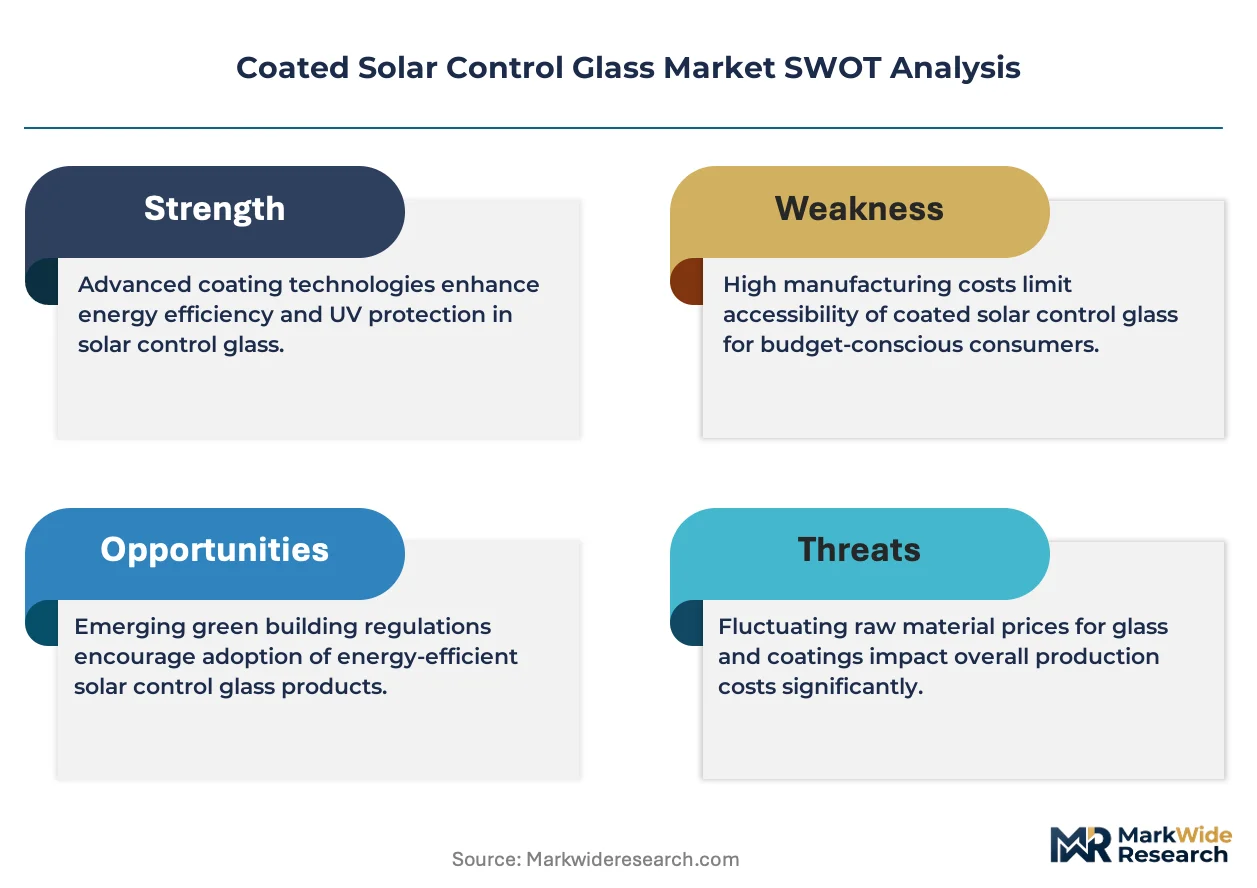
Distributor margins absorb 12-18 points on standard low-E glass moving through European facade contractors, while direct-to-OEM automotive contracts command volume discounts that strip 8-12 points from list pricing. Three-tier pricing structure across premium, standard, and economy levels separates triple-silver sputtered products from pyrolytic coatings and commodity tinted glass. Cost compression in the standard tier intensifies because Yangtze River Delta fabricators flood export markets with excess capacity. Commercial building developers show lowest price sensitivity where energy-code compliance is mandatory; residential replacement contractors exhibit highest sensitivity, squeezing aftermarket channel returns.
Supply Chain Analysis
Container freight rates from Shanghai to Rotterdam and Los Angeles directly determine landed cost competitiveness for Chinese coating exports versus European domestic production. Raw material sourcing concentrates in China for float glass substrates, Japan and Germany for magnetron sputtering equipment, and Peru and Mexico for silver bullion feedstock. Silver price volatility on the London Metal Exchange creates margin unpredictability that coaters hedge through long-term offtake contracts or pass through via indexed pricing clauses. Distribution runs through integrated glass manufacturers with captive float supply, independent merchant coaters, and regional fabricators serving protected domestic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in coated solar control glass rests on silver-input cost management and premium-tier specification capture as building codes tighten thermal performance thresholds. Coatings that combine solar control with semi-transparent PV generation command pricing premiums that offset commodity pressure in standard architectural glazing.
For Market Incumbents: To counter electrochromic glazing displacement in Middle Eastern headquarters towers, SAINT-GOBAIN and AGC Inc. should accelerate pre-certification of dynamic coating stacks to accelerated Chinese test protocols and deepen backward integration into float glass production in the Yangtze River Delta. Certification investment in GB standards compliance anchors premium positioning as MIIT enforcement timelines compress retrofit windows. For New Entrants and Emerging Players: Enter via automotive thin-film specialization targeting California electric vehicle manufacturers seeking HVAC load reduction without electromagnetic interference, or via cut-to-size retrofit panels for 1970s London and New York office stock. White-space concentration sits in Indian GRIHA-certified commercial towers where imported low-E glass faces limited domestic coating capacity. Go-to-market leverage rests on technical service partnerships with secondary glazing specialists. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators serving protected domestic markets with established CE marking or BIS certification pathways. Long-term viability favors coaters with captive float supply or automotive thin-film technology transferable to building-integrated photovoltaics convergence. The signal to watch is province-by-province GB standard enforcement accelerating replacement demand in Shanghai and Shenzhen commercial stock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Float Glass Production | Captive substrate supply insulates coaters from Chinese producer concentration and freight cost volatility. |
| Pre-certification to Accelerated Chinese Test Protocols | MIIT enforcement timelines reward early compliance with premium specification access in Shanghai and Shenzhen. |
| Automotive Thin-film Technology Licensing | Electric vehicle OEMs in Stuttgart and Detroit prioritize cabin thermal management without electromagnetic interference. |
| Building-integrated Photovoltaics Convergence | Singapore and Dubai pilot contracts validate coatings combining solar control with semi-transparent power generation. |
| Retrofit Channel Partnership Development | London and New York 1970s office stock creates cut-to-size coated panel demand through secondary glazing specialists. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facade engineers, coating plant managers, automotive OEM procurement leads, and green building certification consultants with secondary validation. Primary sources included magnetron sputtering equipment suppliers in Japan and Germany, float glass producers in China and India, and architectural specification teams at Foster + Partners and AECOM. Secondary data drew from SEC 10-K filings of listed glass manufacturers, EU Energy Performance of Buildings Directive implementation reports, Chinese MIIT GB standard enforcement notices, and GRIHA certification databases. Bottom-up volume estimates triangulated against top-down construction spend allocations across commercial, automotive, and residential end uses.
Segment-weighting approaches applied differential growth assumptions across sputter coating versus pyrolytic deposition, triple-silver low-E versus standard double-silver configurations, and commercial facade versus automotive windscreen applications. Coated glass demand was modeled as a function of building envelope thermal performance mandate adoption curves, electric vehicle production ramp rates, and retrofit replacement cycles for 1970s commercial stock. CAGRs were derived from regression analysis of historical price-volume relationships and forward projection of regulatory enforcement timelines. Industry-specific inputs included silver price volatility bands from London Metal Exchange futures curves and province-level GB standard implementation schedules from MIIT notices.
Inputs from equipment suppliers and certification bodies were available through the study window; gaps in real-time project pipeline visibility for Middle Eastern headquarters towers and Indian GRIHA-certified developments introduce uncertainty bands around volume forecasts. Forecasts reflect assumptions about regulatory enforcement continuity, silver price mean reversion, and electrochromic glazing cost-down trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Antiglare Glass Market
Glass
Glass Insulator Market
Glass
Crystalware and Glassware Market
Glass
Glass Vials Market
Glass
Asia-Pacific Flat Glass Market
Glass
Paper Glass Maker Market
Glass
Laboratory Glassware Market
Glass
Glass Prepreg Market
Glass
Insulating Glass Market
Glass
Screen-Printing Glass Market
Glass
Spherical Silica Market
Glass
Global Scratch Resistant Glass Market
Glass
Optical Materials Market
Glass
North America Flat Glass Market
Glass
Antibacterial Glass Market
Glass
Foam Glass Granulate Market