
 Polycrystalline Alumina Fiber Market | 2026-2036
Polycrystalline Alumina Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Polycrystalline Alumina Fiber Market Analytics
ISO 9001 quality management certification is unwinding competitive access for new entrants lacking audited manufacturing traceability. BASF SE leverages its integrated alumina precursor supply chain to control raw material consistency across fiber lots. Denka Company Limited anchors Japanese domestic demand through specialized high-purity formulations for semiconductor furnace applications. Unifrax I LLC competes on North American aftermarket service density, embedding technical support teams directly at customer melt shops.
Polycrystalline alumina fiber consists of alpha-alumina crystallites bonded in a polycrystalline matrix, typically manufactured via sol-gel spinning or melt-extrusion processes with service temperatures exceeding 1600°C in oxidizing environments. Its primary commercial purpose is high-temperature thermal insulation in furnaces, kilns, and combustion chambers where refractory ceramic fiber alternatives degrade structurally. Mats and textiles command the largest volume share due to standardized furnace lining geometries, while chopped fiber forms exhibit the fastest growth trajectory as spray-applied insulation gains favor in petrochemical turnaround maintenance. Aerospace application segments concentrate margin pools where AS9100-certified product commands price premiums over commodity building insulation grades.
EPA emissions standards for industrial kilns and OSHA permissible exposure limits for respirable crystalline silica directly shape fiber product specifications and installation protocol documentation requirements in the United States. REACH registration obligations under ECHA jurisdiction compel European suppliers to submit full toxicological dossiers for fiber chemistries, creating compliance cost barriers that favor incumbent producers with established substance portfolios. Stakeholders must monitor evolving furnace efficiency mandates across multiple jurisdictions, as regulatory tightening on thermal energy intensity typically accelerates retrofit demand for advanced insulation materials ahead of equipment replacement cycles.
Market Dynamics
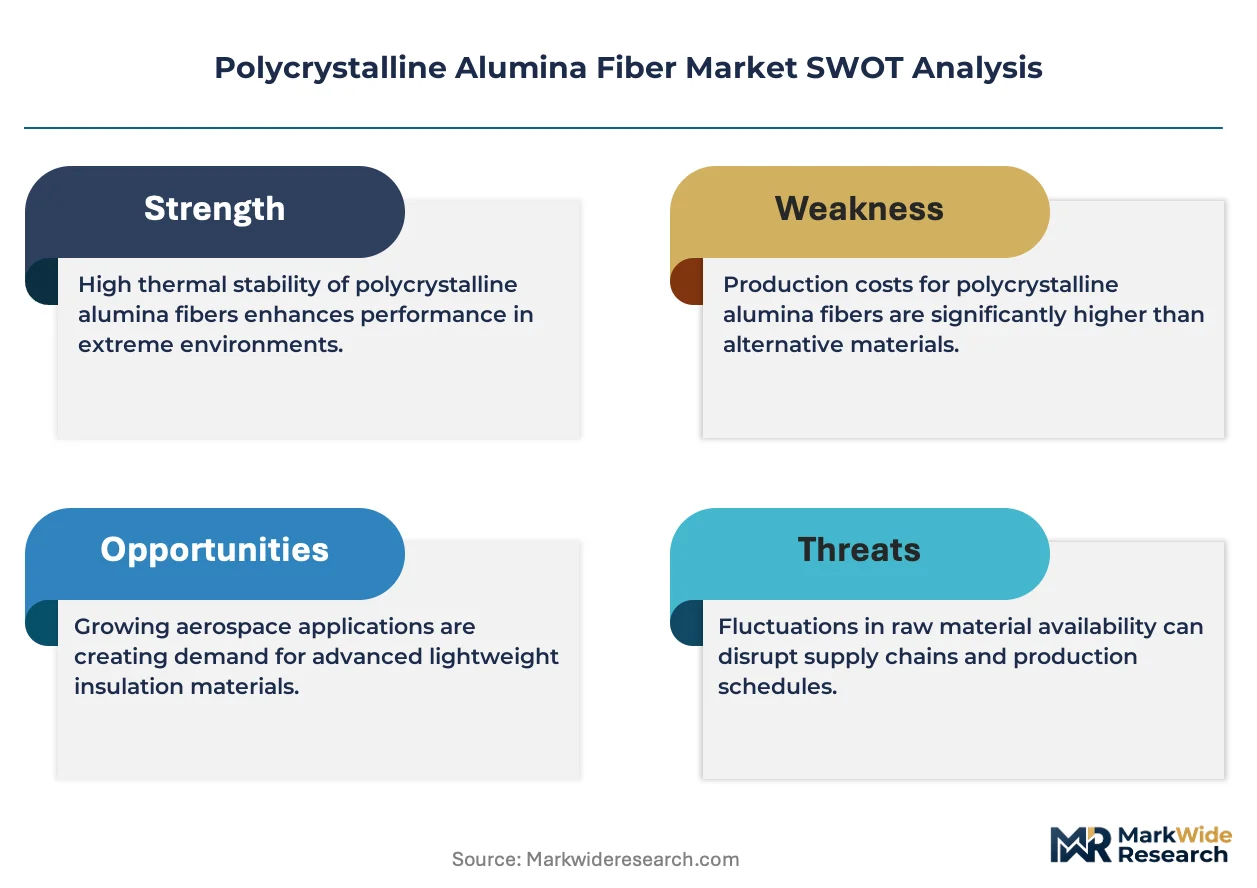
REACH registration obligations under ECHA jurisdiction are redirecting formulation strategies across European supply chains, tightening permissible fiber classifications and forcing producers to submit full toxicological dossiers that favor incumbents with established substance portfolios.
Growth Catalysts
- Petrochemical retrofit cycles in China:Domestic high-temperature insulation replacement demand outpaces other manufacturing geographies as state-owned refineries accelerate furnace efficiency upgrades.
- AS9100 certification premiums:Aerospace furnace lining specifications command price advantages over commodity building insulation grades, concentrating margin pools in engine OEM supply chains.
- Spray-applied insulation adoption:Chopped fiber forms gain favor in turnaround maintenance protocols, displacing traditional mat installations with faster application methods.
Market Restraints
- Alumina precursor cost volatility:Sol-gel spinning processes depend on high-purity aluminum alkoxide feedstocks subject to energy-intensive refining economics.
- Respirable crystalline silica exposure limits:OSHA permissible exposure thresholds in the United States mandate costly installation protocol documentation and worker protection systems.
- Refractory ceramic fiber substitution:Lower-cost aluminosilicate alternatives persist in non-critical furnace zones where service temperatures remain below 1400°C.
Strategic Opportunities
- Semiconductor diffusion furnace segments in Japan:METI-supported domestic manufacturing reshoring creates demand for ultra-high-purity fiber formulations with sub-ppm contaminant specifications.
- EU Green Deal thermal efficiency mandates:Industrial kiln emissions standards accelerate retrofit demand for advanced insulation materials ahead of equipment replacement cycles.
- Digital twin integration:Predictive thermal modeling converges with fiber specification databases to enable outcome-based lining performance contracts.
Industry Challenges
- ISO 9001 audit traceability gaps:New entrants lacking certified manufacturing documentation face competitive access barriers in aerospace and medical device supply chains.
- AS9100 certification timelines:Aerospace quality management accreditation requires 18-24 month implementation cycles that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycrystalline Alumina Fiber Market |
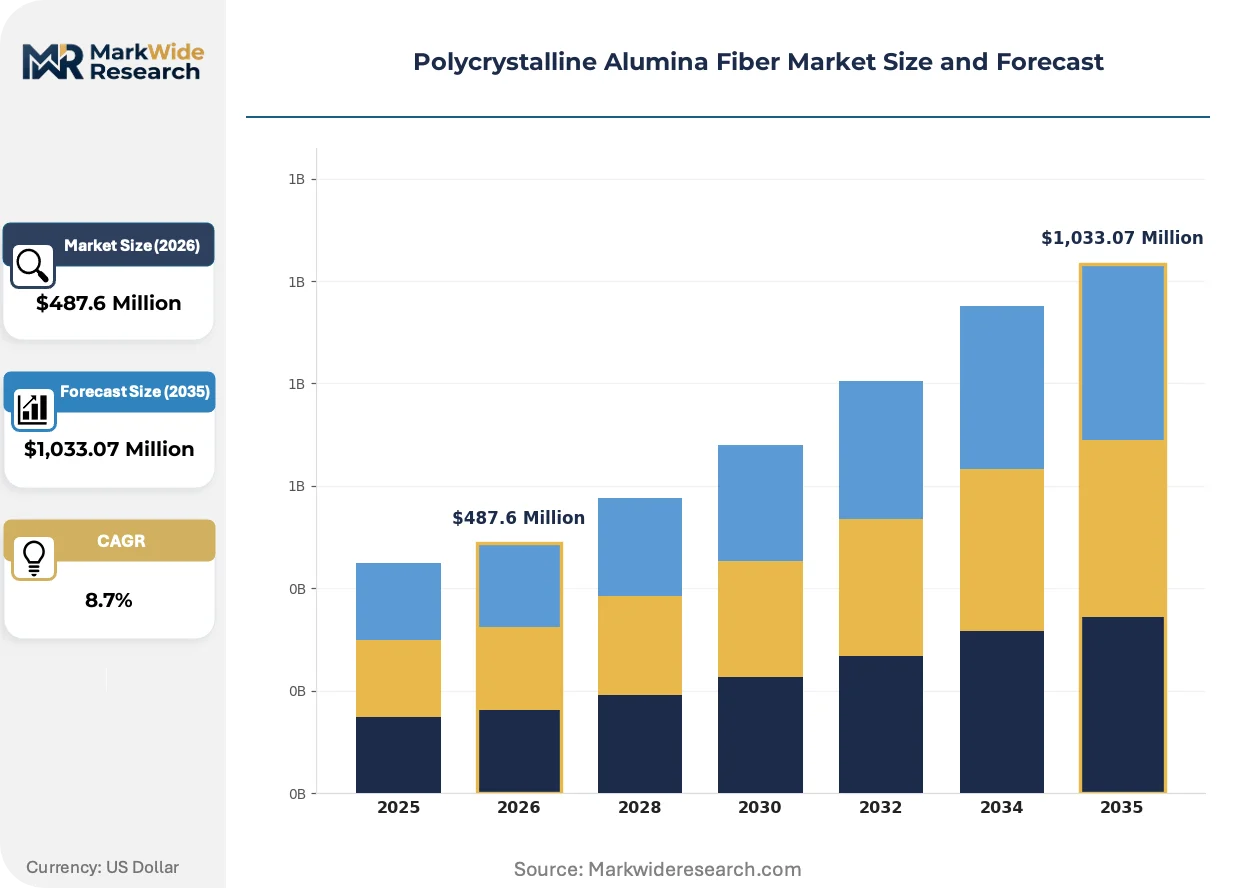
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
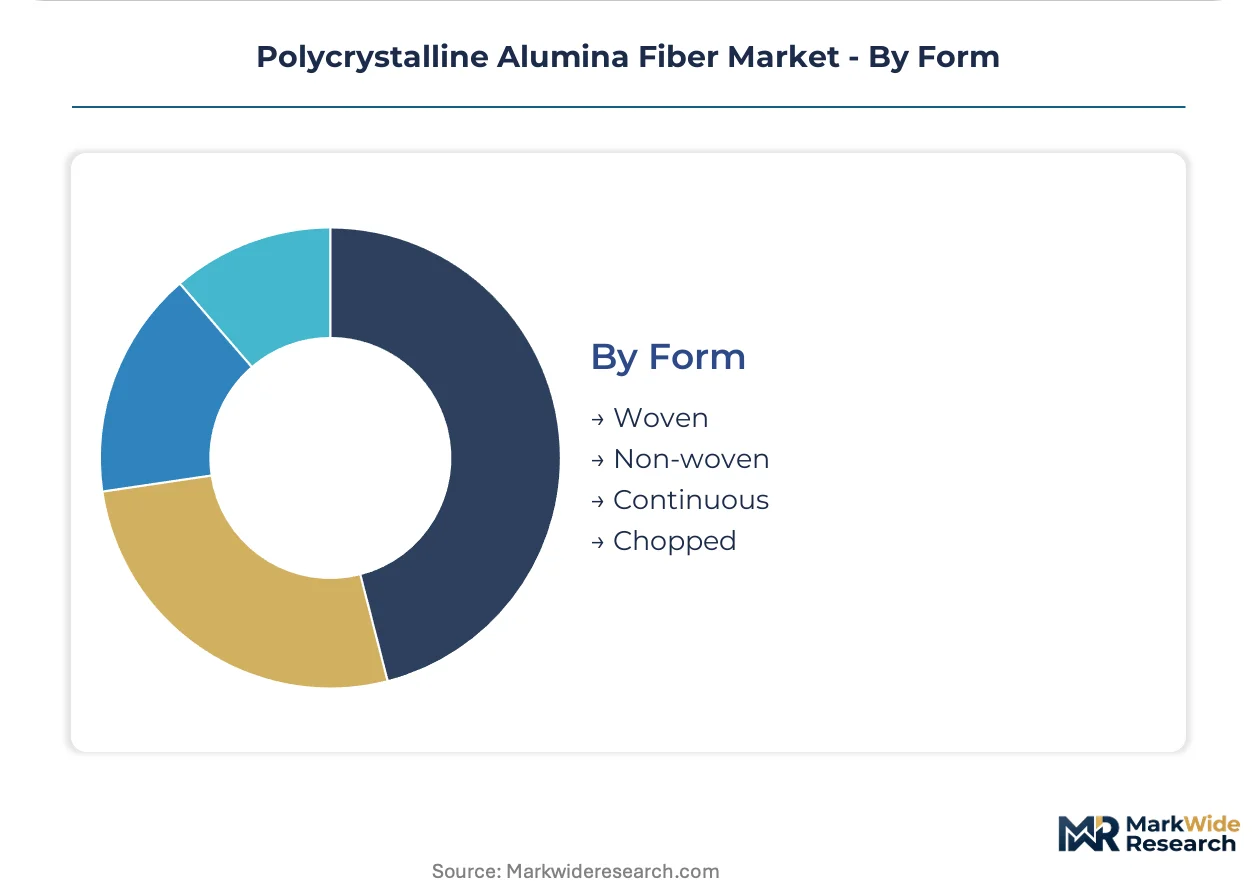
| Segmentation | Product Type: Textiles, Ropes, Mats, Fabrics Application: Aerospace, Automotive, Building, Insulation End User: Manufacturers, Contractors, OEMs, Research Institutions Form: Woven, Non-woven, Continuous, Chopped |
| Companies Covered | BASF SE, Denka Company Limited, 3M Company, Unifrax I LLC, Morgan Advanced Materials plc, Almatis GmbH, CeramTec GmbH, ZIRCAR Ceramics, Inc., AluChem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycrystalline Alumina Fiber Market Evolving Landscape
Sol-gel spinning advancements are compressing fiber diameter distributions while elevating alpha-alumina crystallite purity, reshaping competitive positioning around thermal shock resistance metrics rather than bulk density alone.
Nanostructured fiber architectures with engineered grain boundaries are supplanting conventional melt-extruded products in aerospace thermal barrier applications. Engine OEMs at GE Aerospace and Rolls-Royce facilities are qualifying these formulations for next-generation turbine blade shroud insulation. The technology is compressing acceptable thermal conductivity thresholds by 15-20 percent in the 1200-1600°C service range.
ECHA enforcement of updated REACH Annex XVII restrictions on synthetic mineral fibers is forcing reformulation of alumina-silica blends previously classified as exonerated. European insulation contractors now demand full substance composition disclosure for installation liability coverage. German furnace engineering firms are accelerating qualification of pure polycrystalline alumina alternatives to preempt regulatory reclassification risks.
Integrated service contracts bundling fiber supply with thermal performance guarantees are displacing transactional material procurement in petrochemical maintenance channels. Reliance Industries and Sinopec facilities are piloting decade-long lining lifecycle agreements with penalty clauses for unplanned downtime. This shift is most visible in China's coastal refining corridor where state-backed energy groups consolidate vendor relationships.
Polycrystalline Alumina Fiber Market Segmentation
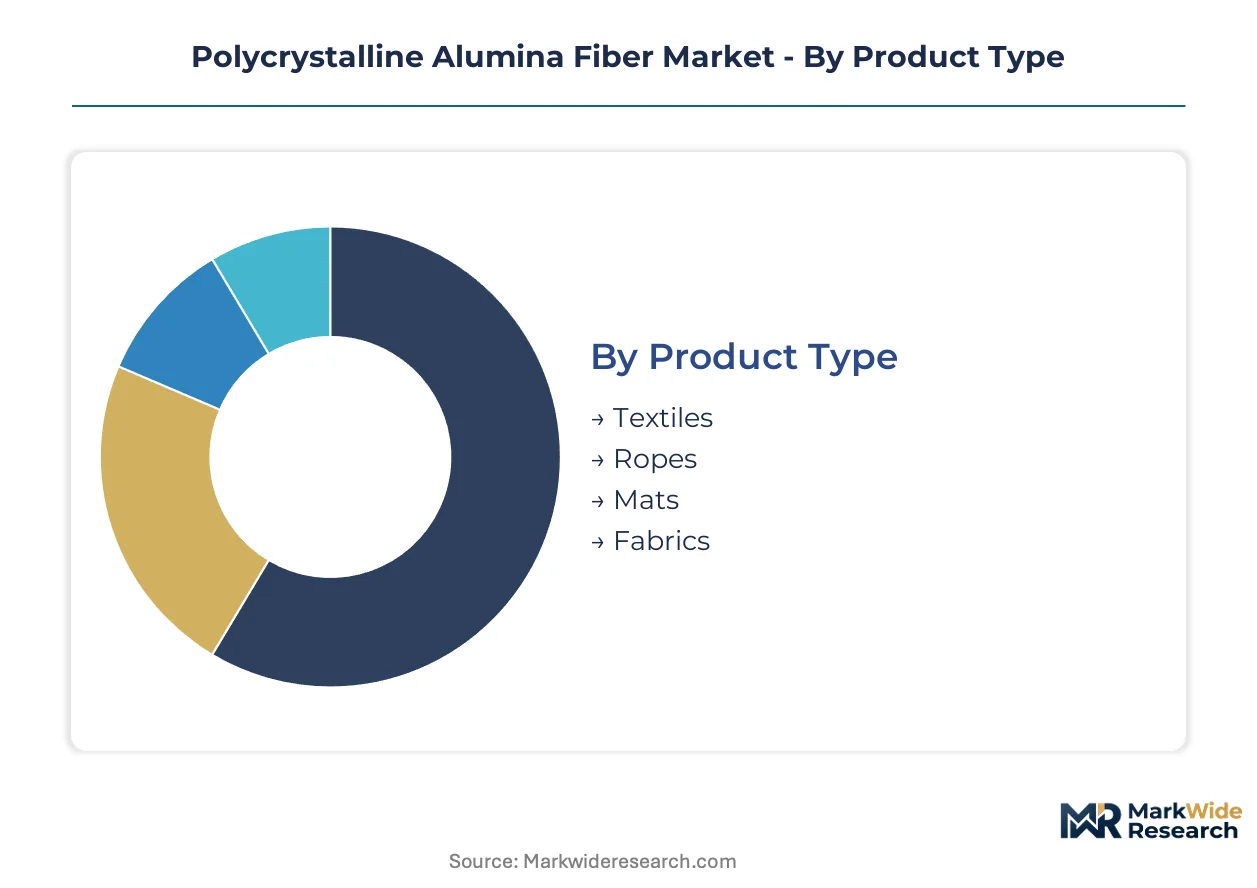
Polycrystalline alumina fiber segmentation reveals divergent competitive dynamics across product architectures and installation methods. Substitution pressure from refractory ceramic fibers intensifies in lower-temperature tiers while premium specifications defend position in aerospace-qualified grades.
Product Type:
Textiles and mats face the strongest refractory ceramic fiber substitution threat in commodity furnace lining applications where service temperatures fall below 1400°C.
- Mats:Rigidized fiber boards and flexible blanket formats dominate standardized furnace lining geometries across petrochemical and steel heat treatment installations. Demand concentrates in China's coastal refining corridor where state-owned energy groups consolidate vendor relationships for turnaround maintenance cycles.
- Textiles:Woven tapes, sleevings, and braided constructions serve complex thermal barrier geometries in turbine engine applications. AS9100-certified textile specifications command price premiums over commodity building insulation grades as GE Aerospace and Rolls-Royce facilities qualify next-generation formulations.
- Ropes:Round and square braided packings seal expansion joints and door seals in kiln car systems.
- Fabrics:Woven cloth substrates support composite preform manufacturing and removable insulation covers.
Mats anchor the volume base while chopped fiber derivatives gain share at the steepest rate in spray-applied retrofit protocols.
Application:
Margin concentration follows certification tier rather than raw volume, with aerospace specifications capturing disproportionate value pools against construction-grade alternatives.
- Insulation:Furnace linings, kiln car systems, and combustion chamber barriers constitute the foundational demand driver across industrial heat processing. EPA emissions standards for industrial kilns and OSHA permissible exposure limits for respirable crystalline silica directly shape product specifications and installation protocol documentation requirements in the United States.
- Aerospace:Thermal barrier systems for turbine blade shrouds, exhaust nozzles, and re-entry vehicle heat shields demand sub-ppm contaminant specifications. Nanostructured fiber architectures with engineered grain boundaries are supplanting conventional melt-extruded products as engine OEMs push thermal conductivity thresholds lower.
- Automotive:Catalytic converter mounting mats and exhaust system insulation utilize lower-purity grades subject to cost pressure from aluminosilicate alternatives.
- Building:Fire-rated penetration seals and high-temperature duct insulation compete against lower-cost glass and rock wool solutions in commercial construction specifications.
Insulation commands the installed base while aerospace climbs the fastest on qualification-driven replacement cycles.
End User:
Procurement authority is shifting from maintenance contractors to integrated service contracts bundling fiber supply with thermal performance guarantees.
- Contractors:Installation specialists executing furnace turnaround maintenance and greenfield construction projects drive spot market demand for standardized mat and textile formats. REACH registration obligations under ECHA jurisdiction compel European contractors to demand full substance composition disclosure for installation liability coverage.
- OEMs:Original equipment manufacturers in furnace engineering and aerospace systems specify qualified fiber grades through approved vendor lists with 18-24 month AS9100 certification timelines. ISO 9001 quality management certification is unwinding competitive access for new entrants lacking audited manufacturing traceability.
- Manufacturers:In-house refractory shops at steel mills and petrochemical complexes maintain captive inventories for emergency repairs.
- Research Institutions:National laboratories and university materials science programs procure small-lot specialty formulations for experimental thermal protection systems.
Contractors dominate transaction volume while OEMs tighten specification control through lifecycle performance agreements.
Form:
Manufacturing process economics separate continuous filament grades requiring sol-gel spinning investment from chopped fiber commoditization.
- Chopped:Short-cut fiber segments enable spray-applied insulation and vacuum-formed shapes with faster installation protocols displacing traditional mat installations. Reliance Industries and Sinopec facilities are piloting decade-long lining lifecycle agreements with penalty clauses for unplanned downtime.
- Continuous:Spun filament tows support textile manufacturing and unidirectional composite preforms requiring tensile strength retention at extreme temperatures. Sol-gel spinning advancements are compressing fiber diameter distributions while elevating alpha-alumina crystallite purity.
- Woven:Interlaced yarn constructions provide dimensional stability in removable insulation pads and expansion joint fabrics.
- Non-woven:Needle-punched felts and vacuum-formed boards offer isotropic thermal properties at lower manufacturing cost.
Continuous filament retains specification authority in aerospace while chopped fiber expands most quickly in maintenance channel conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal thermal efficiency mandates are accelerating retrofit demand for advanced insulation materials across industrial kiln installations. State-backed energy consolidation in China's coastal refining corridor is redirecting procurement toward integrated service contracts with performance guarantees. Japanese semiconductor reshoring programs under METI are creating specialized demand for ultra-high-purity fiber formulations.
China
State-owned refineries along the Bohai Rim and Yangtze Delta are accelerating furnace efficiency upgrades ahead of dual carbon goals deadlines. MEE emissions enforcement is tightening permissible thermal intensity thresholds for petrochemical complexes. Sinopec facilities in Zhenhai and Shanghai are piloting decade-long lining lifecycle agreements with penalty clauses for unplanned downtime.
United States
EPA emissions standards for industrial kilns are mandating documentation-heavy installation protocols across steel heat treatment and petrochemical maintenance channels. OSHA permissible exposure limits for respirable crystalline silica are reshaping worker protection system requirements. Gulf Coast refining clusters in Texas and Louisiana are consolidating vendor relationships around aftermarket service density.
Germany
ECHA enforcement of updated REACH Annex XVII restrictions is forcing reformulation of alumina-silica blends previously classified as exonerated. German furnace engineering firms in North Rhine-Westphalia are accelerating qualification of pure polycrystalline alumina alternatives. The Ruhr industrial corridor is witnessing preemptive regulatory reclassification risk mitigation among insulation contractors.
Japan
METI-supported domestic manufacturing reshoring is creating demand for ultra-high-purity fiber formulations with sub-ppm contaminant specifications. Semiconductor diffusion furnace segments in Kyushu and the Kanto region are driving specialized high-purity formulation requirements. Denka Company Limited anchors domestic supply chains through AS9100-certified product lines for aerospace thermal barrier applications.
Saudi Arabia
SABIC and other state-backed petrochemical groups are expanding high-temperature insulation capacity across Jubail and Yanbu industrial cities. The country's national industrial development program is prioritizing furnace efficiency upgrades in downstream chemical processing. Eastern Province refining complexes are importing advanced mat and textile formats for turnaround maintenance cycles.
Polycrystalline Alumina Fiber Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive alumina precursor supply chains. Tiered competitive structure separates AS9100-certified aerospace specialists from commodity building insulation suppliers. Two strategic archetypes dominate: integrated chemical producers controlling raw material consistency, and regional service-embedded fabricators competing on technical support density. Dominant competitive moves include backward integration into high-purity aluminum alkoxide feedstocks and geographic expansion through integrated service contract bundling.
Among Germany-based chemical conglomerates, BASF SE exemplifies the integrated precursor supply chain archetype with audited manufacturing traceability spanning fiber lot consistency. Japanese specialists Denka Company Limited occupy a position within the high-purity formulation tier, serving semiconductor furnace applications through domestic supply chain anchoring. Unifrax I LLC represents the North American service-embedded model, competing through technical support team placement at customer melt shops rather than commodity pricing.
| Leading Market Players |
|---|
| BASF SE |
| Denka Company Limited |
| 3M Company |
| Unifrax I LLC |
| Morgan Advanced Materials plc |
| Almatis GmbH |
| CeramTec GmbH |
| ZIRCAR Ceramics, Inc. |
| AluChem Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with alumina precursor suppliers lock in both fiber production capacity and feedstock price visibility, insulating Chinese petrochemical buyers from aluminum alkoxide volatility while compressing margin flexibility for European producers facing REACH compliance cost escalation.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate raw material procurement, transferring aluminum price volatility directly to fiber pricing. Three-tier pricing structure across AS9100-certified aerospace grades, ISO 9001 industrial specifications, and commodity building insulation separates margin pools by certification burden. Pricing pressure stems from refractory ceramic fiber substitution in sub-1400°C furnace zones. Spot market contractors exhibit highest price sensitivity, while aerospace OEMs accept premiums for qualified supply security.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and Red Sea container diversion are elevating landed costs for European insulation contractors sourcing Chinese-manufactured mats. Production concentrates in China, Germany, and Japan, drawing from high-purity aluminum alkoxide feedstocks, sol-gel chemical precursors, and specialized spinning equipment. Single-source vulnerability sits with German furnace engineering firms dependent on BASF precursor supply. Distribution runs through technical service-embedded fabricators rather than commodity distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated service contracts bundling fiber supply with thermal performance guarantees represent a platform-economics inflection, as digital twin interoperability enables outcome-based lining lifecycle agreements between suppliers and state-backed energy groups.
For Market Incumbents: Secure backward integration into high-purity aluminum alkoxide production to defend against precursor cost volatility and Denka's semiconductor-grade formulation advantages. Deepen AS9100 certification moats to delay new entrant aerospace qualification timelines. Lock in decade-long performance contracts with Sinopec and Reliance Industries before digital twin standardization commoditizes thermal modeling expertise.
For New Entrants and Emerging Players: Anchor in spray-applied chopped fiber retrofit protocols where installation speed displaces incumbent mat relationships and certification barriers are lowest. Target Chinese coastal refining corridor maintenance contractors underserved by Unifrax's North American service density. Lead with predictive thermal modeling software bundled with commodity fiber supply to bypass AS9100 accreditation requirements.
For Investors and Strategic Acquirers: Regional service-embedded fabricators with captive technical support teams at customer melt shops offer acquisition targets with sticky contractor relationships and recurring maintenance revenue visibility. Long-term viability hinges on EU Green Deal thermal efficiency mandate acceleration as retrofit demand inflection. Watch ECHA REACH Annex XVII enforcement intensity as regulatory reclassification catalyst for pure polycrystalline alumina alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | BASF's captive aluminum alkoxide production secures fiber lot consistency against feedstock volatility. |
| AS9100 Certification Investment | Eighteen-month accreditation timelines lock aerospace supply chains against unqualified competitors. |
| Digital Twin Platform Development | Predictive thermal modeling enables outcome-based lining performance contracts with penalty clauses. |
| Long-term Service Contract Bundling | Decade-long lifecycle agreements with Sinopec consolidate vendor relationships beyond transactional procurement. |
| Nanostructured Fiber R&D | Engineered grain boundaries at GE Aerospace qualification compress thermal conductivity thresholds. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with furnace engineering procurement leads, petrochemical maintenance directors, aerospace OEM thermal barrier specialists, and refractory contractor operations managers; and secondary validation through ECHA REACH registration databases, EPA emissions compliance filings, customs trade flow records, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up fiber volume estimates by product form and application were triangulated against top-down petrochemical capacity expansion and aerospace engine production forecasts.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product architecture, installation method, certification tier, end-use industry, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, efficiency mandate compliance deadlines, and qualification-driven aerospace adoption curves. Sol-gel spinning capacity expansion timelines and REACH substance portfolio registration status served as industry-specific forecast inputs.
Underlying assumptions cover furnace efficiency upgrade compliance schedules, REACH Annex XVII enforcement continuity, and aluminum precursor refining economics, with deviation risk concentrated in ECHA regulatory reclassification timing and Chinese state-owned enterprise procurement consolidation pace. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Drug Integrated Polymer Fibers Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market
Fibers
Global R-Glass Fiber Market
Fibers
Fiberglass Cloth Market
Fibers
Carbon Fiber Wrap Market
Fibers
Microfibrillated Cellulose (MFC) Market
Fibers
Natural Fiber Reinforcement Materials Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
Precision Fiber Molding Market
Fibers
High Temperature Superconducting Fibers Market
Fibers
North America Nanofiber Market
Fibers
North America Glass Fiber Reinforced Gypsum Market
Fibers
Global Fiberglass Mold Market
Fibers
High Performance Fibers for Defense Market
Fibers
Keratin Market