
 North America Glass Insulators Market | 2026-2036
North America Glass Insulators Market Size, Share, and Industry Trends Forecast 2026-2036
North America Glass Insulators Market Insights
Composite-core hybrid designs is tilting traditional porcelain-and-glass supply chains toward higher-performance configurations. Hubbell Incorporated leverages its vertical integration into hardware fittings to capture margin across the full assembly stack. ABB Ltd. anchors its North American position through dedicated manufacturing for utility-scale suspension strings. Victor Insulators specializes in custom pin-type formulations for rural cooperative networks.
Glass insulators are electrically insulating devices manufactured from tempered soda-lime or borosilicate glass, engineered to withstand mechanical loads exceeding 15 tons while maintaining dielectric strength above 140 kV per unit in contaminated environments. Their primary purpose is to support and electrically isolate energized conductors from grounded structures across overhead transmission and distribution networks. Suspension insulators carry the bulk of replacement volume as utilities rebuild 345 kV and 500 kV corridors, while renewable energy applications represent the fastest-expanding demand pool driven by wind farm collector systems. Pin insulators retain stable demand within 15-69 kV distribution feeders where cost sensitivity favors mature designs.
FERC Order 1920 and NERC reliability standards are tightening mechanical and electrical performance requirements for new transmission investments across the United States. EPA regional haze rules and state-level renewable portfolio standards in California, Texas, and New York are directing capital toward cleaner generation that requires expanded interconnection infrastructure. Stakeholders must monitor interconnection queue clearance rates and state regulatory commission rulings on cost recovery mechanisms to time procurement cycles effectively.
Market Dynamics
FERC Order 1920 is compressing transmission infrastructure replacement cycles across the United States while renewable interconnection queues in Texas and California strain existing overhead line capacity. Utilities now face simultaneous pressure to harden aging corridors and expand collector systems for utility-scale solar and wind deployments.
Growth Catalysts
- FERC Order 1920:The Federal Energy Regulatory Commission's transmission planning mandate requires utilities to identify cost-effective regional solutions, accelerating procurement of suspension-type glass insulators for 345 kV and 500 kV corridor rebuilds.
- Wind farm collector systems:Utility-scale renewable deployments across the Great Plains and Southwest are expanding demand for multi-element suspension strings capable of handling mechanical loads in high-vibration environments.
- Grid hardening mandates:NERC reliability standards following extreme weather events are forcing accelerated replacement of porcelain insulators with tempered glass units offering superior contamination performance in coastal and industrial zones.
Market Restraints
- Soda-lime glass feedstock volatility:Energy-intensive glass melting operations face input cost pressure from natural gas price swings and carbon emission compliance costs under EPA regional haze rules.
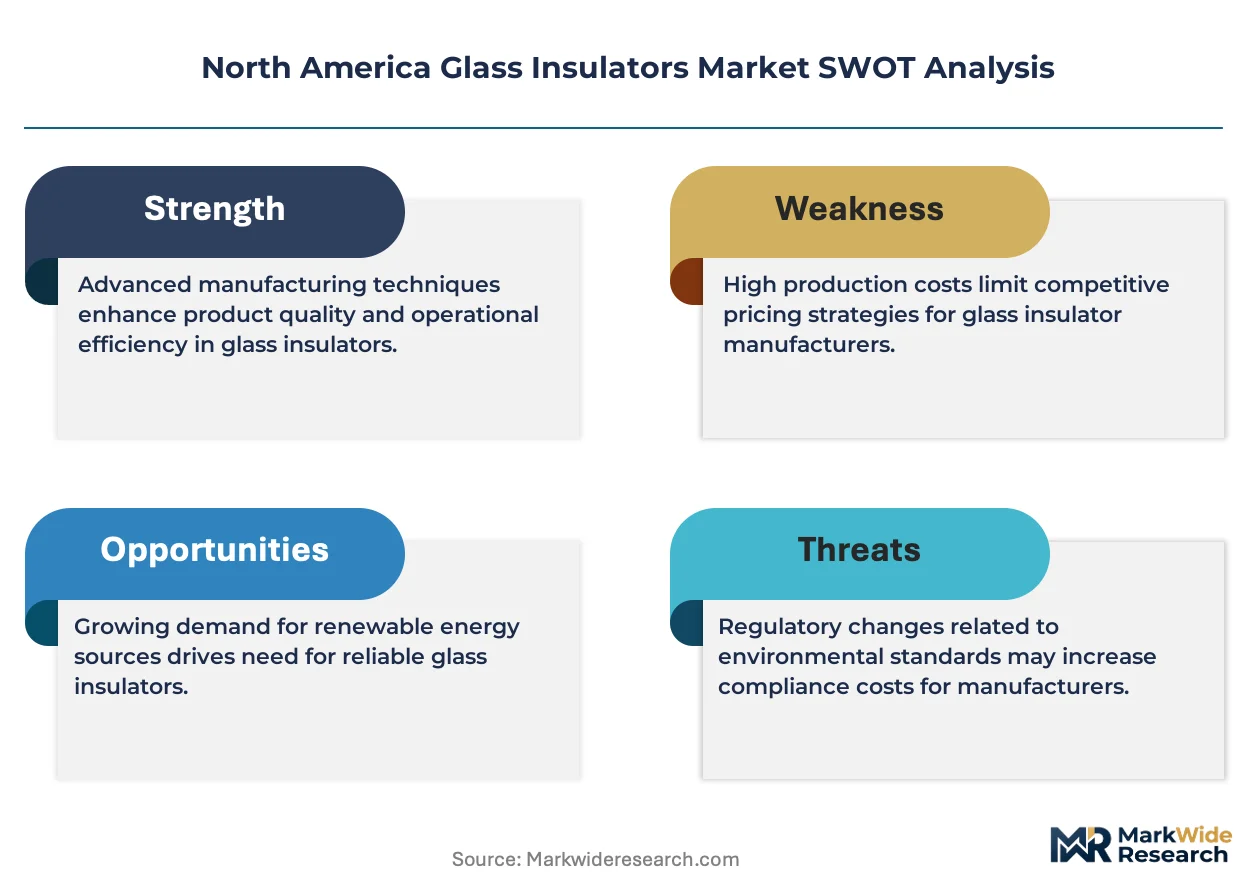
- Composite insulator substitution:Silicone rubber composite designs are capturing share in 69-230 kV applications where weight reduction and vandalism resistance outweigh glass dielectric advantages.
- Domestic manufacturing concentration:Production of high-voltage suspension units concentrates in a limited number of specialized foundries, creating supply bottleneck risk during surge procurement cycles.
Strategic Opportunities
- Rural cooperative networks:Electric cooperatives in the Mountain West and Pacific Northwest remain underpenetrated for premium pin-type formulations, offering volume expansion for specialized manufacturers.
- Hybrid composite-core designs:Convergence of glass dielectric housings with composite load-bearing cores creates performance tier differentiation against pure porcelain and pure composite alternatives.
- State renewable portfolio standards:California's accelerated clean energy targets and Texas interconnection reforms are directing capital toward transmission expansion requiring expanded insulator procurement.
Industry Challenges
- Specialized glass tempering expertise:The workforce capable of controlling thermal treatment parameters for 15-ton mechanical load ratings remains scarce, constraining quality-assured capacity expansion.
- Multi-standard certification timelines:Simultaneous compliance with ANSI C29, IEC 60383, and utility-specific material specifications extends product qualification cycles for new entrants.
- Legacy infrastructure compatibility:Integration of modern glass insulator strings with aged hardware fittings requires custom engineering, complicating standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Glass Insulators Market |
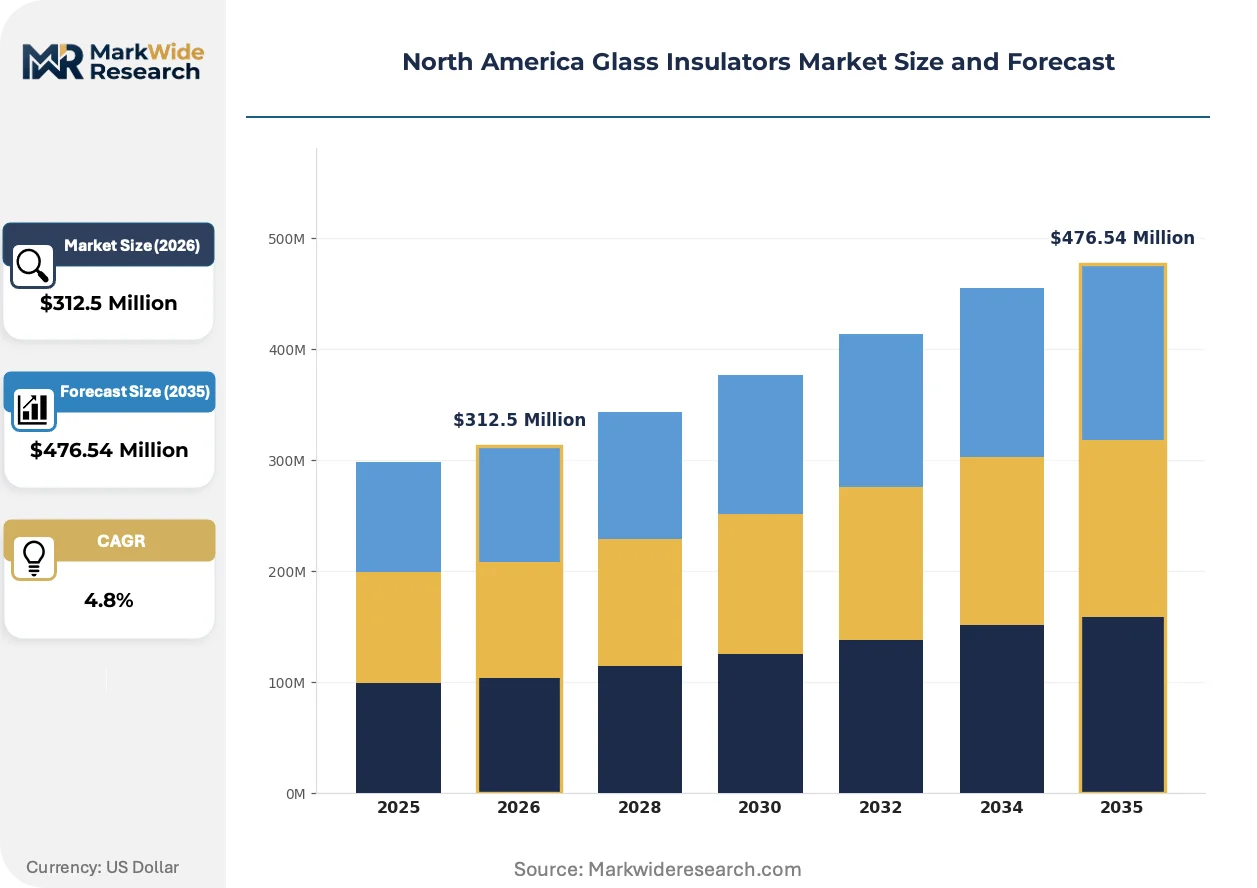
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pin Insulators, Suspension Insulators, Line Post Insulators, Shackle Insulators Application: Power Transmission, Distribution Networks, Renewable Energy, Telecommunications Installation Type: Overhead Lines, Underground Cabling, Substations, Wind Farms End User: Utility Companies, Renewable Developers, Industrial Plants, Commercial Infrastructure |
| Companies Covered | General Electric Company, Hubbell Incorporated, ABB Ltd., TE Connectivity, Siemens AG, Schneider Electric SE, Victor Insulators, PG&E Corporation, MacLean Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Glass Insulators Market Trends and Innovations
Material science advances and procurement model evolution are reconfiguring competitive positioning in North American glass insulator supply. Manufacturers now compete on dielectric performance optimization and supply chain responsiveness rather than commodity volume alone.
Composite-core hybrid suspension strings is hybridizing traditional glass insulator architecture by combining tempered dielectric housings with fiber-reinforced polymer load-bearing cores. Utilities rebuilding 230-500 kV corridors are specifying these configurations for weight-critical applications including long-span river crossings and seismic zones. The technology is hybridizing procurement specifications, forcing pure-glass and pure-composite suppliers toward intermediate performance tiers.
FERC Order 1920 and companion NERC CIP-014 physical security standards are tightening mechanical performance verification requirements for transmission infrastructure investments. The regulations mandate documented load-testing protocols and traceable manufacturing records, elevating compliance costs for smaller foundries. High-voltage suspension applications in California and Texas are responding with consolidated supplier qualification lists favoring vertically integrated manufacturers.
Consolidated procurement through transmission owner joint ventures is compressing supplier negotiation cycles and unbundling hardware-insulator assembly sourcing. Investor-owned utilities in the PJM and ERCOT interconnections are shifting toward multi-year framework agreements with penalty clauses for delivery failure. The behavioral shift is most visible in Texas, where interconnection queue delays have created surge-demand volatility that favors suppliers with captive glass melting capacity.
North America Glass Insulators Market Segmentation
Glass insulator procurement patterns diverge sharply across voltage classes and installation environments. Product specifications, mechanical load ratings, and contamination resistance requirements create distinct demand pools that manufacturers must address through differentiated production configurations.
Product Type:
Cost tier stratification separates mature commodity formats from specialized high-voltage assemblies requiring certified tempering protocols.
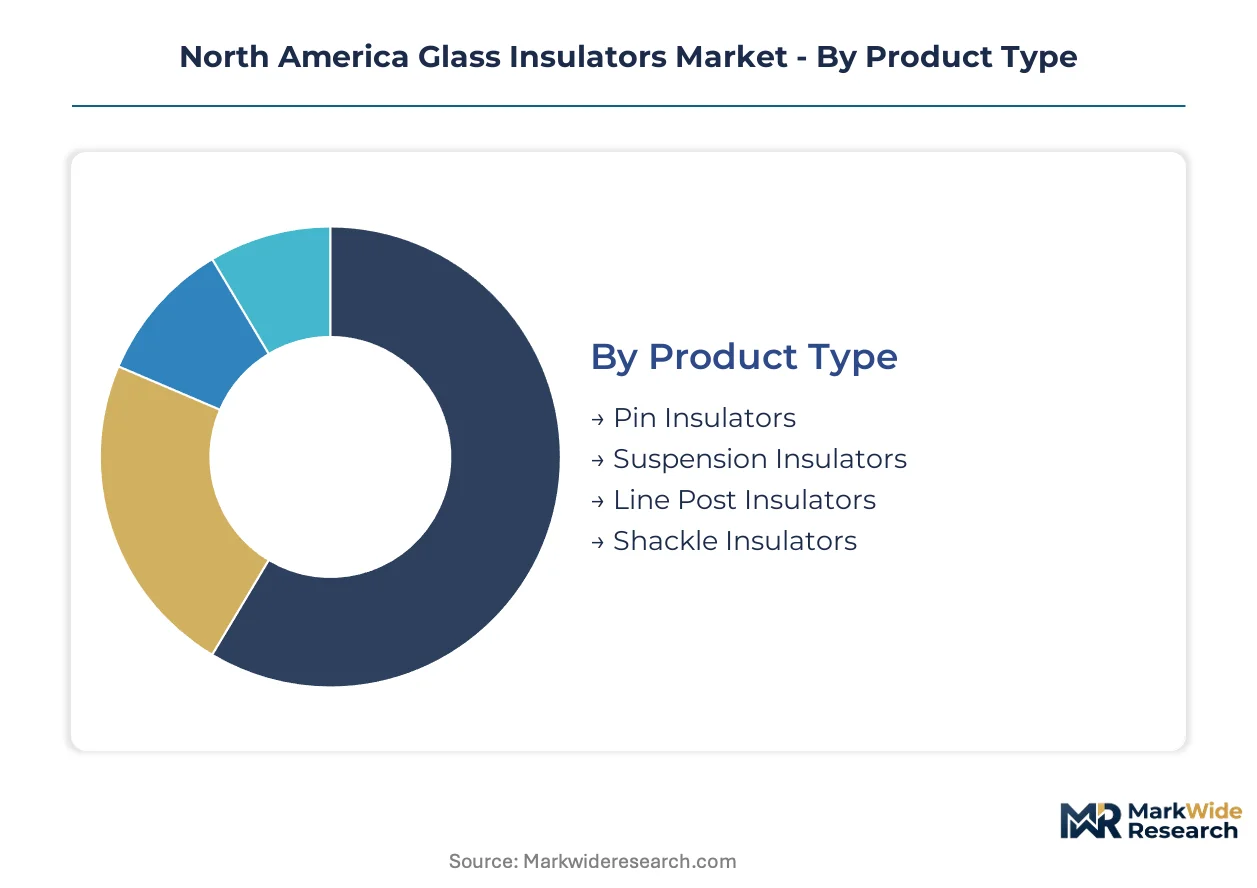
- Pin Insulators:Single-piece tempered glass units support 15-69 kV distribution feeders through direct conductor mounting on crossarms. Rural cooperatives in the Mountain West favor these units for cost-sensitive replacement cycles where porcelain alternatives have failed.
- Suspension Insulators:Multi-element disc strings handle mechanical loads exceeding 15 tons across 345 kV and 500 kV transmission corridors. ERCOT and CAISO interconnection queues are expanding procurement of these strings for renewable collector systems and corridor rebuilds under FERC Order 1920.
- Line Post Insulators:Vertical mounting configurations integrate conductor support with structural bracing for compact substation layouts.
- Shackle Insulators:Compact curved designs serve low-voltage distribution tie points and secondary service drops.
Pin insulators hold installed capacity. Suspension insulators are rotating up the share rankings.
Application:
Application scope determines dielectric performance thresholds and environmental certification requirements for glass formulations.
- Power Transmission:Bulk energy movement across 230-765 kV corridors demands suspension strings with dielectric strength above 140 kV per unit in contaminated environments. PJM and ERCOT transmission owners are specifying these for long-span river crossings and seismic zones.
- Renewable Energy:Wind farm collector systems in Texas and the Great Plains require multi-element strings capable of withstanding high-vibration mechanical loads. This segment is climbing the fastest as interconnection queue backlogs force parallel infrastructure expansion.
- Distribution Networks:15-69 kV feeder reinforcement maintains steady replacement volume across aging urban infrastructure.
- Telecommunications:Antenna support and guy-wire isolation applications use compact glass units with lower mechanical ratings.
Power transmission holds installed capacity. Renewable energy is rotating up the share rankings.
Installation Type:
Installation environment dictates hardware compatibility and environmental exposure specifications for glass tempering protocols.
- Overhead Lines:Exposed conductor support across open terrain subjects insulators to contamination, UV degradation, and mechanical wind loading. Texas and California utilities are prioritizing these installations for grid hardening mandates following extreme weather events.
- Wind Farms:Turbine-specific collector circuits require lightweight suspension configurations for nacelle-to-tower transitions and inter-turbine cabling. The segment is expanding most quickly as Great Plains renewable deployment accelerates.
- Substations:Controlled-environment installations emphasize compact post designs for busbar support and equipment isolation.
- Underground Cabling:Limited glass penetration due to cable insulation replacing overhead conductor support requirements.
Overhead lines hold installed capacity. Wind farms are rotating up the share rankings.
End User:
Customer type determines procurement scale, qualification requirements, and framework agreement structures for supplier relationships.
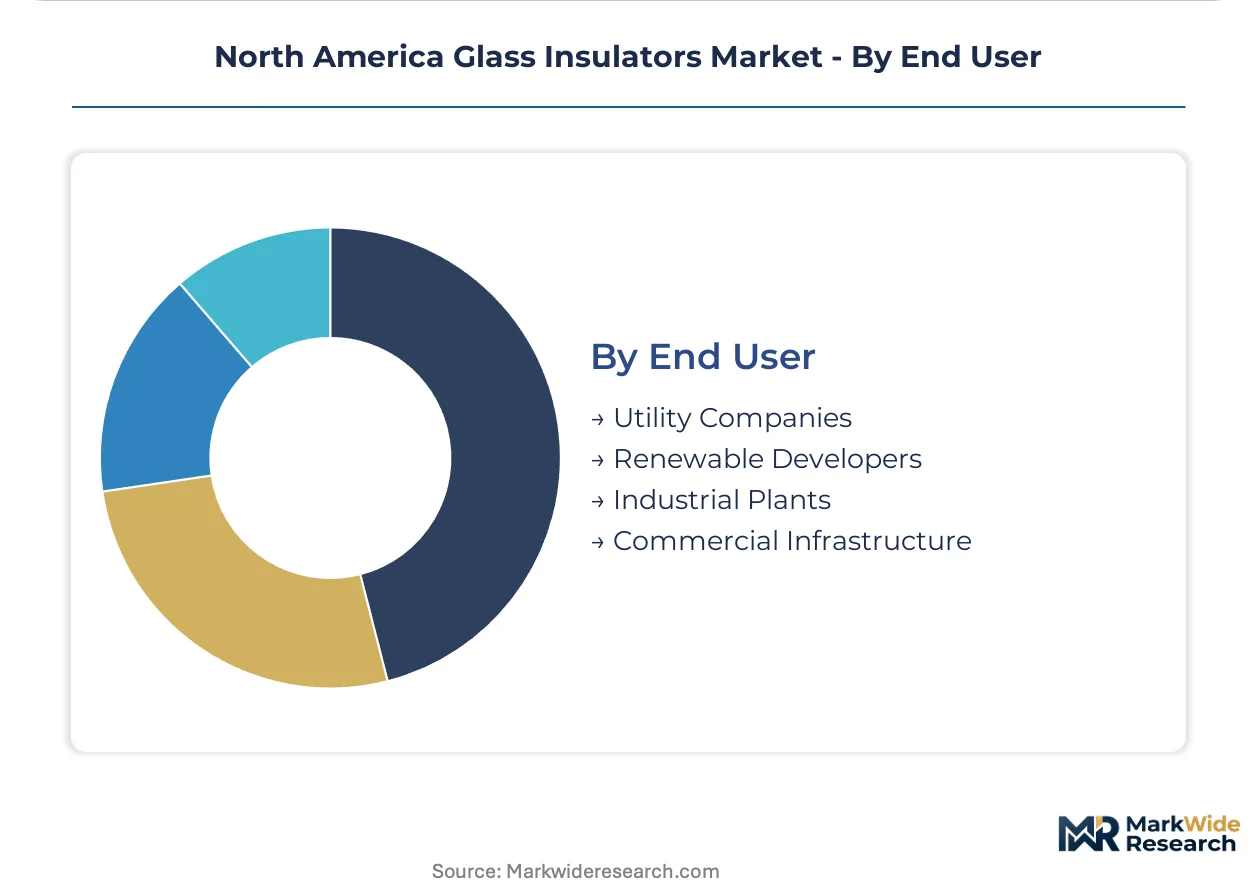
- Utility Companies:Investor-owned transmission owners in PJM and ERCOT dominate volume through multi-year framework agreements with penalty clauses for delivery failure. FERC Order 1920 compliance documentation and NERC CIP-014 physical security standards elevate supplier qualification barriers.
- Renewable Developers:Wind and solar project sponsors face compressed procurement timelines tied to interconnection queue clearance schedules. The segment is gaining share fastest as Texas interconnection reforms and California clean energy targets redirect capital toward transmission expansion.
- Industrial Plants:Cogeneration and heavy manufacturing facilities maintain captive distribution infrastructure with specialized contamination resistance needs.
- Commercial Infrastructure:Data centers and large retail distribution facilities require dedicated substation-grade insulation for private service entrances.
Utility companies hold installed capacity. Renewable developers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transmission owners and renewable developers concentrate procurement across three national markets with distinct regulatory drivers and infrastructure replacement cycles.
United States
ERCOT and CAISO interconnection queues are straining existing overhead line capacity across Texas and California. FERC Order 1920 mandates regional transmission planning that accelerates suspension-type glass insulator procurement for 345 kV and 500 kV corridor rebuilds. PJM transmission owners in the Mid-Atlantic are consolidating supplier qualification lists under NERC CIP-014 physical security standards.
Canada
Hydro-Québec and provincial transmission operators are rebuilding aging 735 kV corridors connecting remote hydroelectric generation to load centers. Environment Canada regulations on greenhouse gas emissions from energy-intensive glass manufacturing are elevating compliance costs for imported units. Ontario's manufacturing heartland around Hamilton hosts specialized foundries serving cross-border utility procurement.
Mexico
Comisión Federal de Electricidad is expanding 400 kV transmission infrastructure to connect renewable zones in Oaxaca and the Baja California peninsula. The country's national energy regulator has streamlined interconnection permitting for wind and solar projects, compressing procurement timelines for suspension strings. Monterrey's industrial cluster supplies hardware fittings for integrated assembly sourcing.
North America Glass Insulators Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a moderately consolidated structure where three to five manufacturers capture the majority of high-voltage suspension volume. Vertically integrated electrical equipment conglomerates dominate framework agreements with investor-owned utilities, while mid-cap specialists retain positions in rural cooperative and industrial segments. Two strategic archetypes define competitive positioning: full-stack hardware-assembly suppliers and pure-play glass formulation specialists. Capacity expansion in captive glass melting and backward integration into soda-lime feedstock sourcing represent the dominant competitive moves.
Among diversified electrical equipment manufacturers, General Electric Company and Siemens AG exemplify the channel-controlling archetype through integrated transmission infrastructure portfolios. Hubbell Incorporated occupies a specialist position with concentrated exposure to North American utility procurement. ABB Ltd. anchors the premium-tier segment for utility-scale suspension strings with dedicated regional manufacturing capabilities.
| Leading Market Players |
|---|
| General Electric Company |
| Hubbell Incorporated |
| ABB Ltd. |
| TE Connectivity |
| Siemens AG |
| Schneider Electric SE |
| Victor Insulators |
| PG&E Corporation |
| MacLean Power Systems |
| Others |
Pricing and Supply Chain Analysis
Specialized glass tempering foundries in Ohio and Ontario concentrate upstream capacity for high-voltage suspension units, anchoring margin capture at the formulation and thermal treatment tier rather than raw material sourcing. This geographic concentration of certified tempering expertise creates pricing power asymmetries that favor incumbent manufacturers with captive melting operations.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate procurement agreements between transmission owners and suspension string suppliers. Three-tier pricing structure across premium, standard, and economy levels separates ANSI C29-certified units from utility-specific specifications and unbranded commodity replacements. Pricing pressure stems from composite insulator substitution in 69-230 kV applications where silicone rubber designs undercut glass on installed weight. Rural electric cooperatives exhibit highest price sensitivity, while investor-owned utilities in ERCOT and PJM prioritize delivery reliability over unit cost.
Supply Chain Analysis
Soda-lime silica sand deposits in Wisconsin and Pennsylvania feed domestic glass melting operations, with borosilicate formulations drawing from specialty chemical suppliers in Germany and Japan. The supply chain rests on high-purity silica, natural gas for melting furnaces, and manganese-doped glass for UV resistance. Single-source vulnerability concentrates in specialized tempering equipment manufacturers serving the 15-ton mechanical load rating segment. Distribution runs through transmission owner joint ventures and EPC contractor assembly sourcing rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as FERC Order 1920 splinters procurement authority across regional transmission organizations and state regulatory commissions. Renewable interconnection queue backlogs generate demand volatility that rewards agile suppliers over volume-committed incumbents.
For Market Incumbents: Entrench position through backward integration into captive soda-lime feedstock sourcing and certified tempering capacity expansion in Texas. Composite insulator substitution threatens 69-230 kV glass volumes; defend share via hybrid composite-core suspension strings for weight-critical applications. Prioritize NERC CIP-014 compliance documentation investments to maintain qualification on consolidated supplier lists. For New Entrants and Emerging Players: Rural cooperative networks in the Mountain West and Pacific Northwest present underpenetrated demand for premium pin-type formulations. Target electric cooperatives with shorter qualification cycles and lower volume thresholds than investor-owned utilities. Pursue custom engineering partnerships for legacy hardware compatibility as a differentiated service layer. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with captive glass melting and hardware fitting assembly capabilities. Long-term viability hinges on exposure to 345 kV and 500 kV corridor rebuilds under FERC Order 1920 mandates. Monitor interconnection queue clearance rates in ERCOT and CAISO as inflection indicators for suspension string demand surges.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soda-Lime Feedstock | Captive silica sourcing insulates margin from natural gas price volatility and EPA regional haze compliance costs. |
| Hybrid Composite-Core Suspension String Development | Convergence of glass dielectric housings with fiber-reinforced polymer cores captures share from pure composite competitors in 230-500 kV applications. |
| NERC CIP-014 Certification Investment | Documented load-testing protocols and traceable manufacturing records secure placement on consolidated utility qualification lists. |
| Rural Cooperative Network Penetration | Shorter sales cycles and lower competitive intensity in Mountain West electric cooperatives offset lower per-unit margins. |
| Multi-Year Framework Agreement Negotiation | Penalty-clause contracts with ERCOT and PJM transmission owners reduce demand volatility exposure through volume commitments. |
Research Methodology
A spread of perspectives from transmission planning officers at investor-owned utilities, procurement leads at renewable developers, EPC contractor project managers, and glass foundry operations directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FERC filings, EIA transmission infrastructure data, NERC reliability standard documentation, and state regulatory commission rulings on cost recovery mechanisms. Bottom-up demand modeling triangulated against top-down transmission capital expenditure forecasts.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include voltage class, installation environment, end-user archetype, and regional regulatory framework. CAGRs were derived from utility capital expenditure trajectories, interconnection queue clearance rates, and replacement cycle acceleration under grid hardening mandates. Forecast inputs incorporated FERC Order 1920 implementation timelines and renewable portfolio standard compliance deadlines in California, Texas, and New York.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by composite insulator manufacturers would shift outcomes toward faster substitution in mid-voltage applications. Cross-checking against EIA transmission line mileage additions and ERCOT interconnection queue withdrawal rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Silica Market
Glass
Middle East and Africa Glassware Market
Glass
Silica Sand Market
Glass
North America Industrial Silica Sand Market
Glass
Metallic Glass Market
Glass
Glass Insulator Market
Glass
Global Vacuum Insulated Glass Market
Glass
Insulated Glass Market
Glass
Solar Control Glass Market
Glass
Screen-Printing Glass Market
Glass
Glass Mat Thermoplastic Market
Glass
North America Flat Glass Market
Glass
Mirrored Glass Market
Glass
Glass Forming Machine Market
Glass
Global Vitrification Market
Glass
Glass Block Market