
 Glass Forming Machine Market | 2026-2036
Glass Forming Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Forming Machine Market Foresight
Aftermarket service revenue is tilting toward predictive maintenance contracts and remote diagnostics as original equipment margins compress. Bucher Emhart Glass leverages its installed base across Europe and the Americas to sustain recurring service income. Bottero anchors its position through deep specialization in architectural and automotive glass forming systems. Heye International competes on precision engineering for narrow-neck pharmaceutical and cosmetic container segments.
A glass forming machine is capital equipment that shapes molten glass into containers, flat glass, or specialty products using blow, press, or combination processes operating at temperatures exceeding 1,000 degrees Celsius and cycle speeds up to 600 containers per minute. Its primary purpose is to mass-produce dimensionally consistent glass packaging and technical glassware for downstream industrial and consumer markets. Blow and blow equipment dominates installed capacity for standard beverage bottles, while electric servo technology is capturing the fastest growth as converters seek energy savings and tighter process control. Pharmaceutical bottle applications command premium pricing due to validation requirements and contamination prevention standards.
The EPA enforces emissions standards that push glass manufacturers toward cleaner combustion and electric forming technologies. REACH and the EU Green Deal restrict hazardous substances in machine coatings and mandate carbon footprint disclosures across equipment supply chains. OSHA and ISO 45001 shape workplace safety protocols for high-temperature forming operations. Stakeholders must monitor how evolving energy-efficiency regulations in the European Union and North America will reshape equipment replacement cycles and retrofit investment priorities.
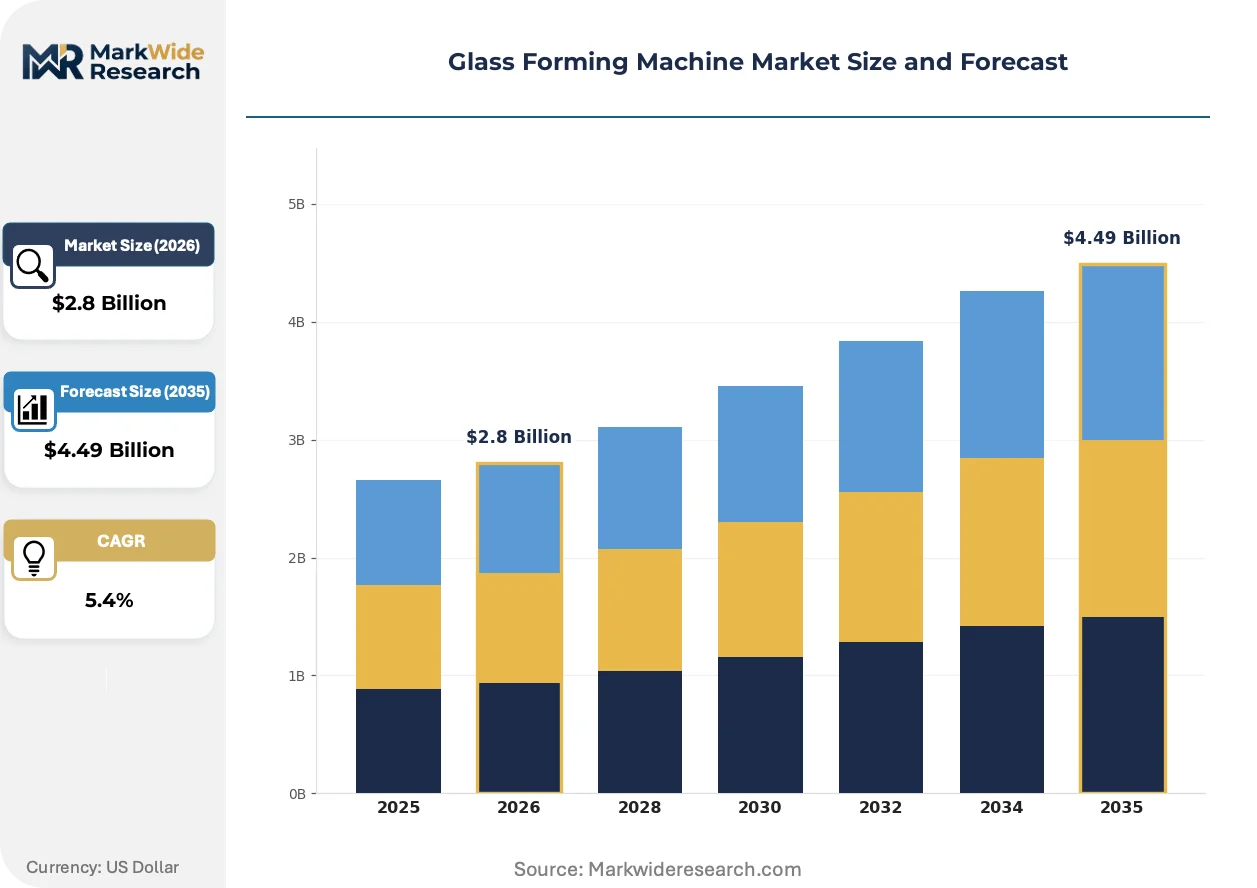
Market Dynamics
Electric servo technology is collapsing energy consumption benchmarks across glass forming operations while EU F-Gas Regulation and EPA emissions mandates accelerate capital replacement cycles among container manufacturers.
Growth Catalysts
- EU Green Deal mandates:Binding carbon footprint disclosure requirements for equipment supply chains are forcing beverage packagers to upgrade forming machinery ahead of scheduled replacement timelines.
- Lightweight bottle engineering:Thin-wall container designs for wine and spirits are demanding precision blow-and-blow equipment capable of maintaining dimensional tolerance at reduced glass weights.
- China:Domestic glass packaging capacity expansion is driving new machine installations and aftermarket retrofit demand across Shandong and Jiangsu manufacturing clusters.
Market Restraints
- Refractory material cost volatility:Zirconia and alumina-silicate prices fluctuate with mining output constraints, compressing margins on furnace rebuild contracts and spare parts.
- German equipment concentration:Precision forming component supply concentrates among Mittelstand specialists, creating single-source vulnerability for servo drive assemblies and mold tooling.
- REACH substance restrictions:ECHA classification of certain ceramic coatings as substances of very high concern is forcing reformulation of mold surface treatments and extending validation timelines.
Strategic Opportunities
- India:FSSAI packaging safety mandates and PLI scheme incentives for domestic manufacturing are opening procurement windows for pharmaceutical-grade forming systems in Gujarat and Maharashtra.
- Predictive maintenance convergence:Integration of thermal imaging sensors with machine learning analytics is collapsing unplanned downtime intervals for high-speed beverage lines.
- Refillable bottle infrastructure:Deposit-return schemes in Germany and Denmark are creating aftermarket demand for heavy-duty forming equipment optimized for 50+ reuse cycles.
Industry Challenges
- Servo technician scarcity:Electric drive calibration and PLC programming expertise lags equipment deployment, extending commissioning timelines and inflating service contract premiums.
- Pharmaceutical validation protocols:FDA and EMA contamination prevention standards require extensive IQ/OQ/PQ documentation, stretching order-to-acceptance cycles for narrow-neck container systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Forming Machine Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Blow & Blow, Press & Blow, Narrow Neck Press & Blow, Gob & Blow Technology: Hydraulic, Mechanical, Pneumatic, Electric Servo Application: Beverage Packaging, Food Containers, Pharmaceutical Bottles, Cosmetic Packaging End User Industry: Glass Bottle Manufacturers, Container Producers, Packaging Suppliers, Specialty Packaging Firms |
| Companies Covered | Bottero, LiSEC GmbH, Bucher Emhart Glass, Heye International, Torgauer Maschinenbau GmbH, Fives Group, Jetter AG, Ishizuka Glass Group, BDF Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Forming Machine Market Shifts & Advancements
Forming equipment architecture is undergoing fundamental redesign as electrification, regulatory compliance automation, and service model unbundling converge to reshape buyer-supplier relationships across container glass manufacturing.
All-electric servo forming systems are collapsing pneumatic and hydraulic drive architectures in high-speed beverage applications. Major converters in Germany and the United States are specifying servo-electric IS machines for new greenfield installations, eliminating compressed air infrastructure and enabling closed-loop pressure control. The technology is collapsing energy intensity benchmarks by removing combustion-heated compressed air systems from the forming process entirely.
REACH and the EU F-Gas Regulation are mandating comprehensive carbon footprint documentation across equipment supply chains. Machine builders must now certify coating chemistries, document embodied carbon in steel castings, and disclose refrigerant content in cooling subsystems. Pharmaceutical and premium cosmetic container segments face the steepest compliance burden as ECHA substance restrictions intersect with EMA validation requirements.
Aftermarket service unbundling is fragmenting traditional maintenance contracts into discrete diagnostic, spare parts, and remote monitoring subscriptions. Beverage packagers in China and Mexico are purchasing machine-health dashboards separately from technician dispatch services, compressing supplier pricing power. The shift is most visible among mid-cap converters seeking to internalize preventive maintenance while outsourcing only catastrophic failure response.
Glass Forming Machine Market Segmentation
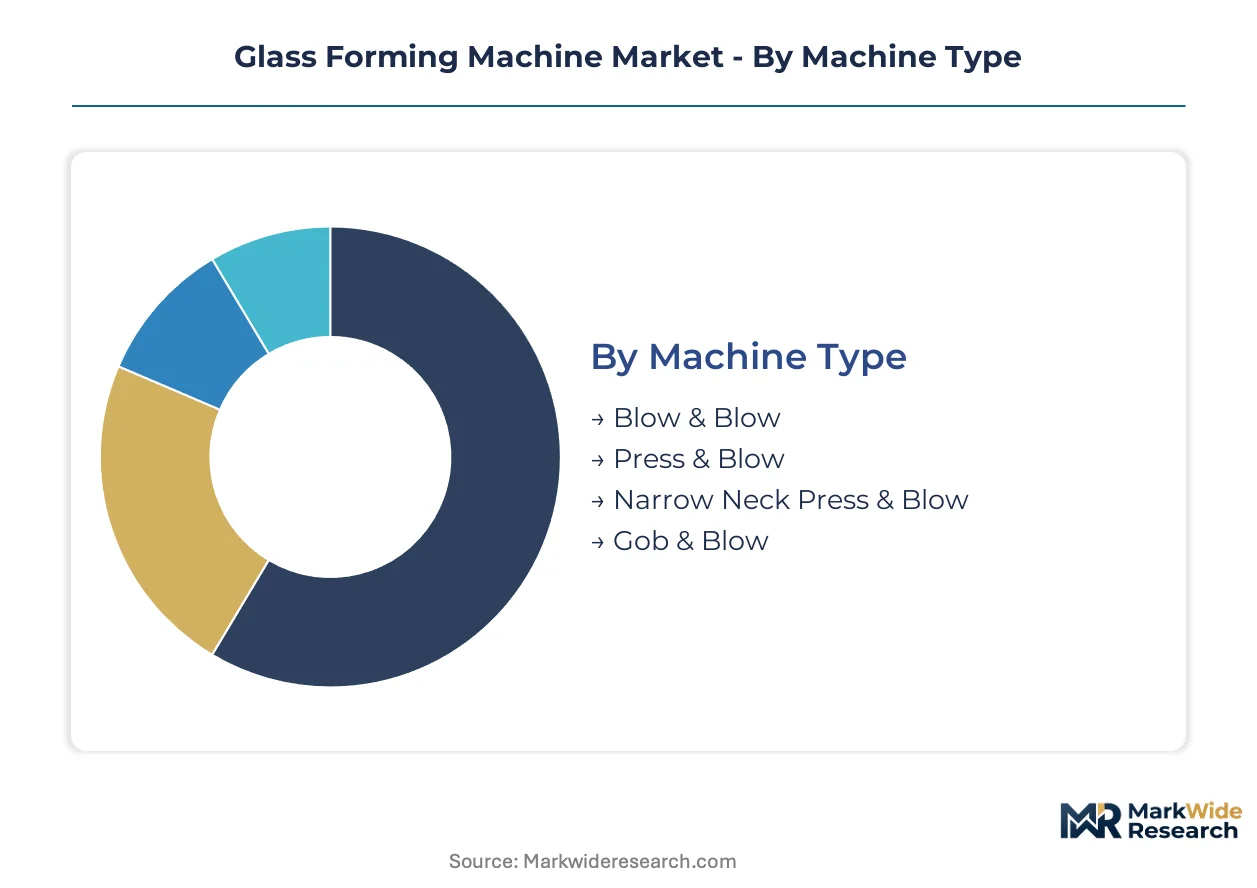
Glass forming machine procurement patterns diverge sharply across forming methods, drive architectures, and end-use compliance requirements. Equipment specification cascades from container geometry constraints through energy efficiency mandates to validation protocols.
Machine Type:
Mature blow-and-blow architectures dominate beverage volume while emerging narrow-neck precision systems capture pharmaceutical premiumization.
- Blow & Blow:Dual-stage compressed air forming produces hollow glass containers with uniform wall distribution. Demand concentrates among high-volume beverage packagers in Germany and the United States seeking lightweight wine and spirits bottles.
- Narrow Neck Press & Blow:Mechanical plunger preforms the neck finish before final blow molding, delivering dimensional precision for pharmaceutical vials and cosmetic droppers. FDA and EMA validation requirements sustain premium pricing.
- Press & Blow:Single-stage mechanical pressing suits wide-mouth food jars and cosmetic pots where neck precision matters less than throughput.
- Gob & Blow:Gravity-fed gob delivery remains entrenched in specialty tableware and technical glassware with lower volume requirements.
Blow & Blow retains volume leadership; Narrow Neck Press & Blow holds the steepest expansion curve.
Technology:
Cost tier stratification separates legacy pneumatic infrastructure from electric servo investments reshaping energy benchmarks.
- Electric Servo:Closed-loop motor control eliminates compressed air dependency, collapsing energy intensity metrics. German greenfield installations specify all-electric IS machines to meet EU Green Deal carbon disclosure mandates.
- Mechanical:Cam-driven timing systems persist in established beverage lines where capital replacement cycles lag regulatory pressure.
- Hydraulic:Oil-circuit power transmission survives in heavy-gauge specialty glass with intermittent production schedules.
- Pneumatic:Compressed air networks face accelerated displacement as EPA emissions enforcement tightens combustion-heated compressor infrastructure.
Mechanical systems retain installed base dominance; Electric Servo commands the fastest capacity expansion.
Application:
Customer type differentiation separates commodity beverage procurement from validated pharmaceutical equipment specifications.
- Beverage Packaging:High-speed lines for carbonated soft drinks, beer, and wine drive blow-and-blow equipment procurement. Shandong and Jiangsu manufacturing clusters in China anchor new installation demand.
- Pharmaceutical Bottles:Contamination prevention standards and IQ/OQ/PQ documentation requirements stretch order cycles. EMA and FDA validation protocols sustain premium equipment margins.
- Food Containers:Wide-mouth jars for preserves and sauces favor press-and-blow economics with shorter specification timelines.
- Cosmetic Packaging:Premium fragrance and skincare brands demand narrow-neck precision with aesthetic surface finish requirements.
Beverage Packaging sustains volume concentration; Pharmaceutical Bottles generate the highest margin capture.
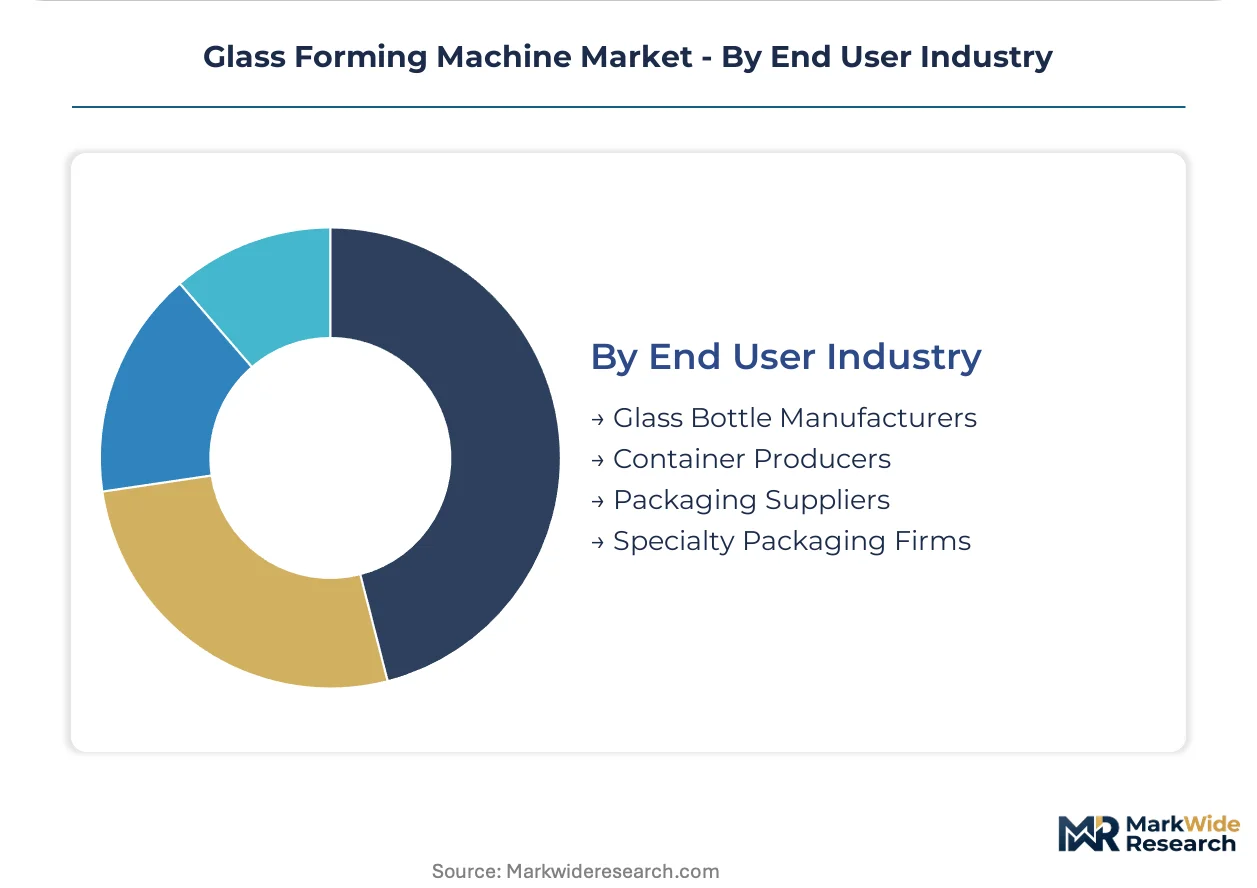
End User Industry:
Supply concentration among integrated container producers shapes procurement consolidation versus specialty packaging fragmentation.
- Glass Bottle Manufacturers:Captive forming operations at scale beverage suppliers drive multi-line IS machine purchases with integrated aftermarket service contracts.
- Container Producers:Independent converters serving regional food and beverage brands favor flexible equipment configurations with rapid changeover capability.
- Packaging Suppliers:Diversified material handlers expanding glass capabilities require turnkey forming solutions with training and validation support.
- Specialty Packaging Firms:Niche cosmetic and pharmaceutical contract packagers specify narrow-neck precision systems with documentation packages.
Glass Bottle Manufacturers retain procurement volume leadership; Specialty Packaging Firms show the steepest technology upgrade intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters prioritize precision narrow-neck systems for pharmaceutical validation, while Chinese beverage packagers favor high-throughput blow-and-blow architectures for lightweight bottle scale.
Germany
Bavarian and North Rhine-Westphalian glassworks drive electric servo IS machine procurement under EU Green Deal carbon disclosure mandates. The F-Gas Regulation accelerates furnace rebuild cycles. Mittelstand component specialists in Baden-Württemberg concentrate precision drive assembly supply for servo retrofits.
China
Shandong and Jiangsu manufacturing clusters anchor new blow-and-blow installations for domestic beverage packaging expansion. MEE dual carbon goals tighten emissions benchmarks for glass production equipment. Qingdao-based converters are retrofitting legacy pneumatic lines with energy-efficient servo architectures.
United States
Midwest container producers and Southeast beverage packagers specify all-electric forming systems to meet EPA emissions enforcement. OSHA workplace safety protocols shape high-temperature operation standards. Pennsylvania and Ohio glassworks concentrate aftermarket service contract demand for predictive maintenance integration.
India
FSSAI packaging safety mandates and PLI scheme incentives open procurement windows for pharmaceutical-grade narrow-neck systems in Gujarat and Maharashtra. CDSCO validation requirements stretch equipment qualification timelines. Mumbai-Pune industrial corridor converters are upgrading from mechanical to servo-electric architectures.
Italy
Emilia-Romagna and Lombardy specialty glassworks demand precision press-and-blow equipment for premium cosmetic container segments. REACH substance restrictions force mold coating reformulation. Venetian tableware manufacturers sustain gob-and-blow system demand for lower-volume artisanal production.
Glass Forming Machine Market Competitive Landscape
Capability concentration sits with German precision engineering specialists; scale advantage sits with diversified industrial conglomerates serving global beverage supply chains. The vendor base separates into three tiers: integrated IS machine builders with full-service portfolios, component specialists dominating servo drive and mold tooling niches, and regional fabricators capturing aftermarket retrofit demand. Consolidation pressure is mounting as energy-efficiency mandates accelerate replacement cycles and squeeze mid-tier mechanical system suppliers. Dominant competitive moves include technology licensing partnerships for electric servo architectures and geographic expansion into Indian and Southeast Asian pharmaceutical packaging corridors.
Within the integrated equipment tier, Bucher Emhart Glass and Bottero exemplify contrasting strategic positions. Bucher Emhart Glass occupies a position anchored across European and Americas installed bases, leveraging recurring service income from predictive maintenance contract unbundling. Bottero represents deep specialization in architectural and automotive glass forming systems distinct from container packaging. Heye International sits within the precision-engineering archetype, serving narrow-neck pharmaceutical and cosmetic container validation requirements. These three names illustrate how competitive positioning fragments across end-use specialization rather than consolidating around undifferentiated scale.
| Leading Market Players |
|---|
| Bottero |
| LiSEC GmbH |
| Bucher Emhart Glass |
| Heye International |
| Torgauer Maschinenbau GmbH |
| Fives Group |
| Jetter AG |
| Ishizuka Glass Group |
| BDF Industries |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's concentration of Mittelstand servo drive specialists concentrates pricing power for precision forming components, allowing German equipment builders to sustain premium positioning even as Chinese manufacturers compress entry-level mechanical system margins.
Pricing Analysis
Long-term offtake contracts with integrated beverage packagers dominate equipment procurement, though pharmaceutical-grade narrow-neck systems command project-based premiums tied to FDA and EMA validation documentation. Price differentiation separates electric servo architectures from legacy pneumatic tiers based on energy-efficiency certification and after-sales service bundling. Pricing pressure stems from refractory material cost volatility in furnace rebuild contracts. Mid-cap container producers in Mexico and Southeast Asia exhibit the highest price sensitivity, while pharmaceutical contract packagers absorb premiums for contamination prevention compliance.
Supply Chain Analysis
Zirconia and alumina-silicate feedstock extraction concentrates in Australia, South Africa, and China, exposing mold tooling and furnace component suppliers to mining output constraints. German and Japanese specialists anchor precision servo drive and ceramic coating production. Single-source vulnerability persists for high-tolerance mold assemblies sourced from Baden-Württemberg fabricators. Distribution runs through direct OEM channels for greenfield installations and regional service partners for aftermarket retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated glass bottle manufacturers in China and the United States, fragmenting pricing leverage among mid-tier equipment suppliers.
For Market Incumbents: Entrench position through backward integration into servo drive component production and predictive maintenance software development. Electric servo technician scarcity threatens service contract profitability; internalize training academies in Germany and the United States. Capacity expansion in Gujarat and Maharashtra captures Indian pharmaceutical packaging growth under FSSAI and PLI scheme incentives. For New Entrants and Emerging Players: Mid-market beverage converters in Southeast Asia seeking energy-efficient retrofits without full servo replacement represent the most penetrable entry point. Refurbished mechanical-to-servo hybrid systems for Shandong and Jiangsu manufacturing clusters offer a second white-space target. Lead with remote diagnostics subscriptions to bypass entrenched service relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EU Green Deal and EPA emissions mandates accelerate replacement cycles regardless of macroeconomic conditions. Target acquisition archetype: precision narrow-neck specialists with validated EMA documentation libraries. Watch for F-Gas Regulation enforcement intensity in Germany as the inflection signal for European retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Architecture Transition | Eliminates compressed air dependency, collapsing energy intensity metrics for EU Green Deal compliance. |
| Predictive Maintenance Platform Launch | Thermal imaging and machine learning integration reduces unplanned downtime for high-speed beverage lines. |
| Pharmaceutical Validation Documentation Investment | IQ/OQ/PQ packages sustain premium pricing for narrow-neck systems under FDA and EMA protocols. |
| Regional Service Hub Expansion | Proximity to Shandong and Jiangsu clusters captures Chinese aftermarket retrofit demand. |
| Refractory Material Supply Agreement | Long-term zirconia and alumina-silicate contracts insulate margins from mining output volatility. |
Research Methodology
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and refractory material suppliers anchors the qualitative findings. Secondary sources include SEC filings from diversified industrial conglomerates, ECHA substance restriction databases, customs trade data for glass forming equipment imports, and EU F-Gas Regulation compliance disclosures. Bottom-up capacity modeling triangulates against top-down spending estimates from beverage packaging capital expenditure surveys.
Calibration against historical replacement cycle patterns and regulatory enforcement timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include forming method, drive architecture, end-use compliance requirements, and regional manufacturing cluster adoption patterns. CAGRs derive from equipment shipment volumes, retrofit intensity ratios, and service contract pricing trajectories. Energy-efficiency mandate timelines and pharmaceutical validation protocol evolution serve as industry-specific forecast inputs.
Stress conditions across refractory material price bands, servo technician availability, and EU carbon disclosure enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and capital replacement cycle elasticity. Cross-checking against EPC contractor order backlogs and glass packaging capacity utilization data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Middle East and Africa Glassware Market
Glass
France Silica Sand Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Asia-Pacific Glassware Market
Glass
Coated Solar Control Glass Market
Glass
Glass Reactors Market
Glass
Insulated Glass Market
Glass
Pharmaceutical Glass Tubing Market
Glass
Glass Lined Equipment Market
Glass
Asia-Pacific Fiberglass Window Market
Glass
Silica Sand for Glass Making Market
Glass
Glass Substrate Market
Glass
Global Energy Efficient Glass Market
Glass
Asia Pacific Flexible Glass Market
Glass
Tempered Glass Market
Glass
Soda Feldspar Market