
 Advanced Glass Market | 2026-2036
Advanced Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Glass Market Analysis
The EU Green Deal's building performance standards is restructuring procurement patterns across European construction supply chains. Saint-Gobain leverages its float glass infrastructure to dominate premium coated glass output for commercial facades. Corning sustains technology leadership through chemically strengthened substrates serving electronics and automotive display markets. Xinyi Glass anchors cost-competitive tempered glass production for Asia-Pacific residential and industrial end users.
Advanced glass encompasses engineered silica-based materials modified through thermal, chemical, or coating processes to achieve specified mechanical strength, optical clarity, thermal insulation, or electromagnetic shielding properties, serving primarily as critical structural or functional elements in buildings, vehicles, and electronic devices. Tempered glass occupies the largest volume share due to mandatory safety codes in automotive and architectural applications, while coated glass captures disproportionate margin pools from solar panel and high-performance building projects. Laminated glass competes aggressively in transportation and security segments where interlayer bonding technology differentiates supplier capabilities.
EPA energy efficiency mandates and REACH chemical compliance frameworks in Europe shape product formulation and market access requirements for imported glass substrates. China's GB standards and MIIT industrial guidelines enforce domestic performance benchmarks that foreign suppliers must satisfy. FDA and NHTSA regulations in the United States govern automotive glazing safety and biocompatibility for medical device applications. Stakeholders must monitor evolving building retrofit mandates and automotive electrification trends to align R&D investments with regulatory trajectories.
Market Dynamics
Automotive electrification is compressing the laminated glass specification cycle as OEMs integrate larger display surfaces and structural battery enclosures into vehicle architectures, forcing substrate suppliers to recalibrate thermal management and electromagnetic shielding capabilities simultaneously.
Growth Catalysts
- EU Green Deal building renovation mandates:The directive targets deep energy retrofits across Germany, France, and Italy, creating pull for triple-glazed and vacuum-insulated units in commercial facades.
- Automotive laminated glass penetration:OEMs are expanding bonded windshield applications for occupant retention and acoustic dampening in premium vehicle segments.
- China's eastern coastal megacity construction codes:Energy-efficiency glazing mandates in Shanghai, Shenzhen, and Guangzhou concentrate demand for low-emissivity coated substrates.
Market Restraints
- High-purity silica supply concentration:Foundry-grade sand deposits in select regions create input cost volatility and geographic dependency for float glass manufacturers.
- REACH chemical compliance friction:ECHA restrictions on certain coating precursors and interlayer plasticizers complicate formulation continuity for European imports.
- Polycarbonate glazing substitution:Lightweight polymer alternatives threaten side-window and sunroof applications where weight reduction outweighs scratch-resistance requirements.
Strategic Opportunities
- India's commercial real estate expansion:LEED-certified office construction in Bangalore and Hyderabad creates specification pull for solar-control coated glass.
- Smart glass-electronics convergence:Electrochromic and suspended particle device technologies integrate with building management systems for dynamic daylight harvesting.
- US Inflation Reduction Act efficiency incentives:Tax credits for high-performance building envelopes accelerate retrofits in legacy commercial stock across Texas and Florida.
Industry Challenges
- Thin-film coating technician scarcity:Magnetron sputtering expertise concentrates in legacy industrial regions, constraining capacity expansion for precision optical layers.
- Automotive display glass certification timelines:NHTSA optical distortion standards and OEM validation cycles extend product qualification to 18-24 months.
- Legacy float line reconfiguration costs:Converting soda-lime capacity to borosilicate or aluminosilicate chemistries requires furnace rebuilds exceeding standard maintenance cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Glass Market |
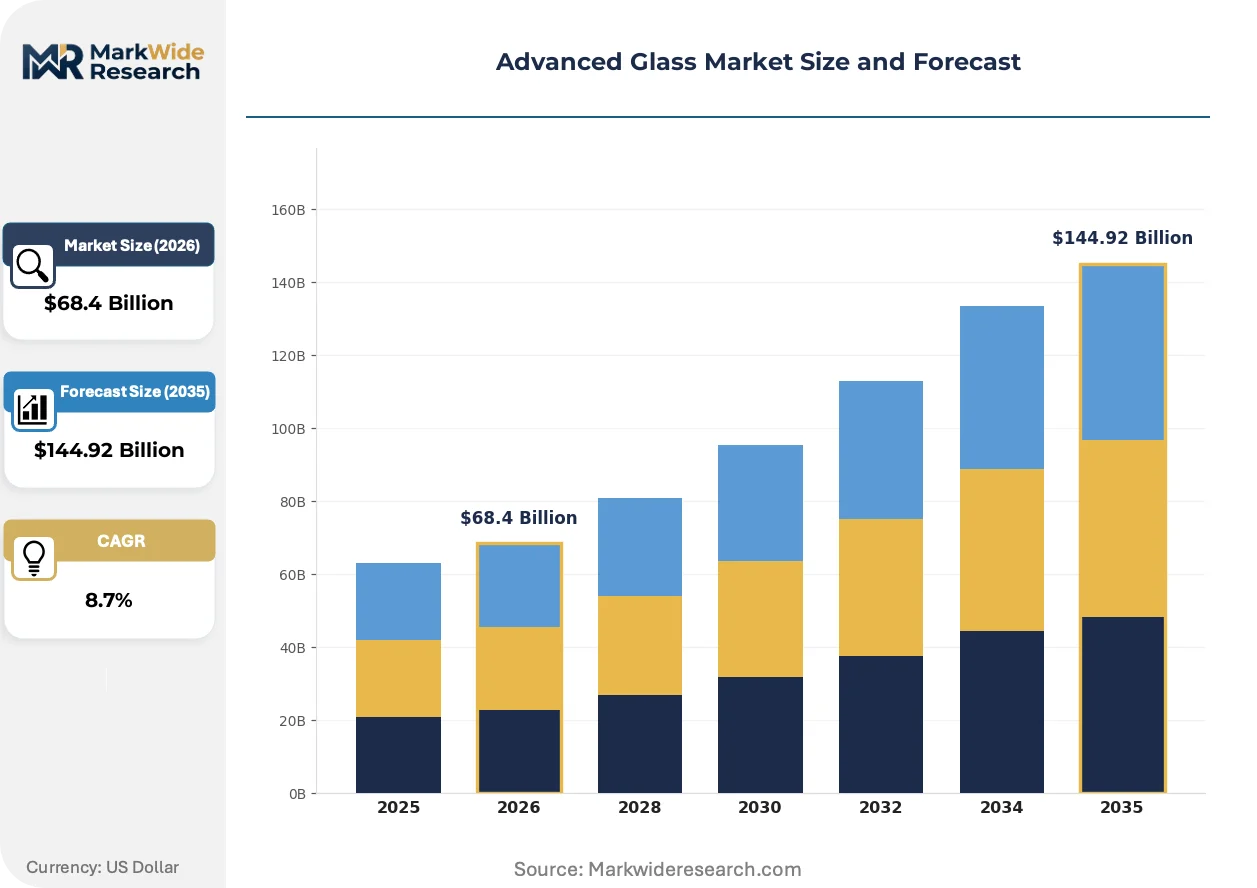
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Coated Glass, Insulated Glass Application: Automotive, Construction, Solar Panels, Electronics End User: Residential, Commercial, Industrial, Transportation Technology: Float Process, Chemical Strengthening, Ceramic Printing, Glass Blowing |
| Companies Covered | Saint-Gobain, AGC Inc., Corning Incorporated, Nippon Sheet Glass Co., Ltd., Guardian Industries, Schott AG, PPG Industries, Inc., Xinyi Glass Holdings Limited, Asahi Glass Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Glass Market Emerging Trajectories
Active materials integration is dissolving the boundary between structural glazing and functional electronics, with substrates now serving as thermal, optical, and electromagnetic management layers simultaneously rather than passive barriers.
Electrochromic thin-film deposition is electrifying facade specification as building operators seek dynamic solar heat gain coefficients without external shading hardware. Commercial developers in California and New York are specifying switchable glazing for net-zero certifications. The technology is compressing traditional static low-E coating margins by enabling premium pricing for tunable performance.
REACH F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing reformulation of plasma-enhanced chemical vapor deposition processes for barrier coatings. European glass coaters are migrating to atomic layer deposition alternatives with lower global warming potential precursors. The transition is most acute in solar panel cover glass manufacturing, where moisture ingress protection cannot degrade.
Direct-to-fabricator digital procurement platforms are fragmenting traditional distributor hierarchies in architectural glass supply chains. Large glazing contractors in Germany and the Netherlands are sourcing coated substrates through B2B marketplaces that bypass regional stockholding intermediaries. The disintermediation is most visible in standardized tempered products where specification compliance is verifiable through uploaded test certificates.
Advanced Glass Market Segmentation
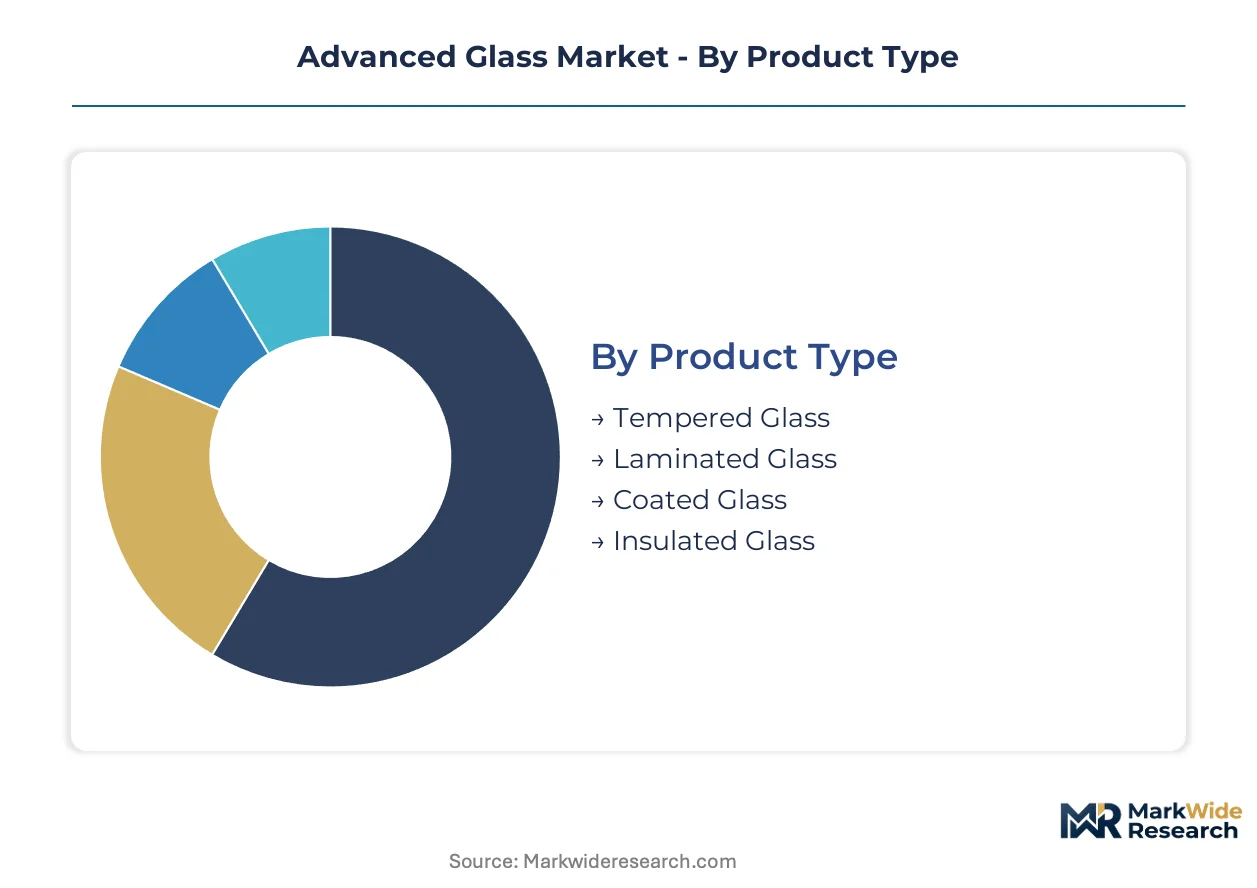
Segmentation in advanced glass reveals how manufacturing scale, regulatory mandates, and end-use performance requirements fragment supply capabilities across distinct technical tiers. Procurement patterns diverge sharply between specification-driven automotive and construction verticals versus cost-sensitive residential applications.
Product Type:
Tempered glass dominates standalone architectural safety applications where thermal shock resistance suffices, while laminated and coated variants embed into integrated systems demanding multi-functional performance.
- Tempered Glass:Heat-treated soda-lime silica engineered to shatter into granular fragments rather than sharp shards. Demand concentrates in China's eastern coastal megacity construction codes mandating safety glazing for high-rise residential towers, with volume pulled by mandatory tempering standards in Shanghai and Shenzhen building permits.
- Laminated Glass:Polyvinyl butyral or ionomer interlayers bond multiple glass plies for post-breakage retention and acoustic dampening. Automotive OEMs in Germany and Japan are expanding bonded windshield specifications for occupant retention in electric vehicle architectures, compressing specification cycles for interlayer clarity and electromagnetic shielding compatibility.
- Coated Glass:Magnetron-sputtered metal oxide layers manipulate solar heat gain and visible light transmission. Solar panel manufacturers and LEED-certified commercial developers in California specify anti-reflective and transparent conductive oxide coatings.
- Insulated Glass:Hermetically sealed dual or triple-pane units with inert gas fills and warm-edge spacers. EU Green Deal renovation mandates across Germany, France, and Italy accelerate triple-glazed unit retrofits in legacy commercial facades.
Volume placements concentrate in Tempered Glass; the faster expansion belongs to Laminated Glass.
Application:
Application segments stratify by certification burden and replacement frequency, with automotive and electronics demanding longest validation timelines versus construction's project-based procurement cycles.
- Automotive:Structural glazing for windshields, side windows, and emerging battery enclosure applications. NHTSA optical distortion standards and OEM validation cycles extend product qualification to 18-24 months, favoring incumbent suppliers with existing type approvals.
- Construction:Curtain walls, skylights, and interior partitions balancing thermal performance with aesthetic specification. Commercial real estate expansion in India's Bangalore and Hyderabad technology corridors creates pull for solar-control coated glass in LEED-certified office stock.
- Solar Panels:Tempered cover glass with anti-reflective coatings and moisture barrier properties. REACH F-Gas Regulation restrictions are forcing European manufacturers toward atomic layer deposition alternatives with lower global warming potential precursors.
- Electronics:Chemically strengthened aluminosilicate substrates for display covers and semiconductor packaging. Corning's fusion draw process dominates this margin-rich segment where scratch resistance and optical clarity command premium positioning.
Construction captures the largest absolute volume; Electronics climbs the fastest on display surface area expansion in vehicles and handheld devices.
End User:
End user categories diverge by procurement sophistication, with commercial and transportation buyers leveraging specification engineering versus residential reliance on distributor recommendations.
- Residential:Single-family and multi-family housing applications where cost sensitivity dominates. Direct-to-fabricator digital procurement platforms in Germany and the Netherlands are fragmenting traditional distributor hierarchies for standardized tempered products.
- Commercial:Office, retail, and hospitality construction with performance-based specifications. US Inflation Reduction Act efficiency incentives accelerate high-performance building envelope retrofits across Texas and Florida legacy commercial stock.
- Industrial:Manufacturing facilities and warehouses requiring impact resistance and thermal insulation. Food processing and pharmaceutical cleanroom applications in Switzerland and Singapore specify borosilicate glass for chemical resistance.
- Transportation:Rail, aviation, and maritime glazing with fire safety and ballistic requirements. Aviation regulators in the US and EU mandate specific interlayer formulations for windshield bird-strike resistance.
Commercial placements lead in value terms; Transportation gains share fastest on aerospace fleet renewal and high-speed rail expansion.
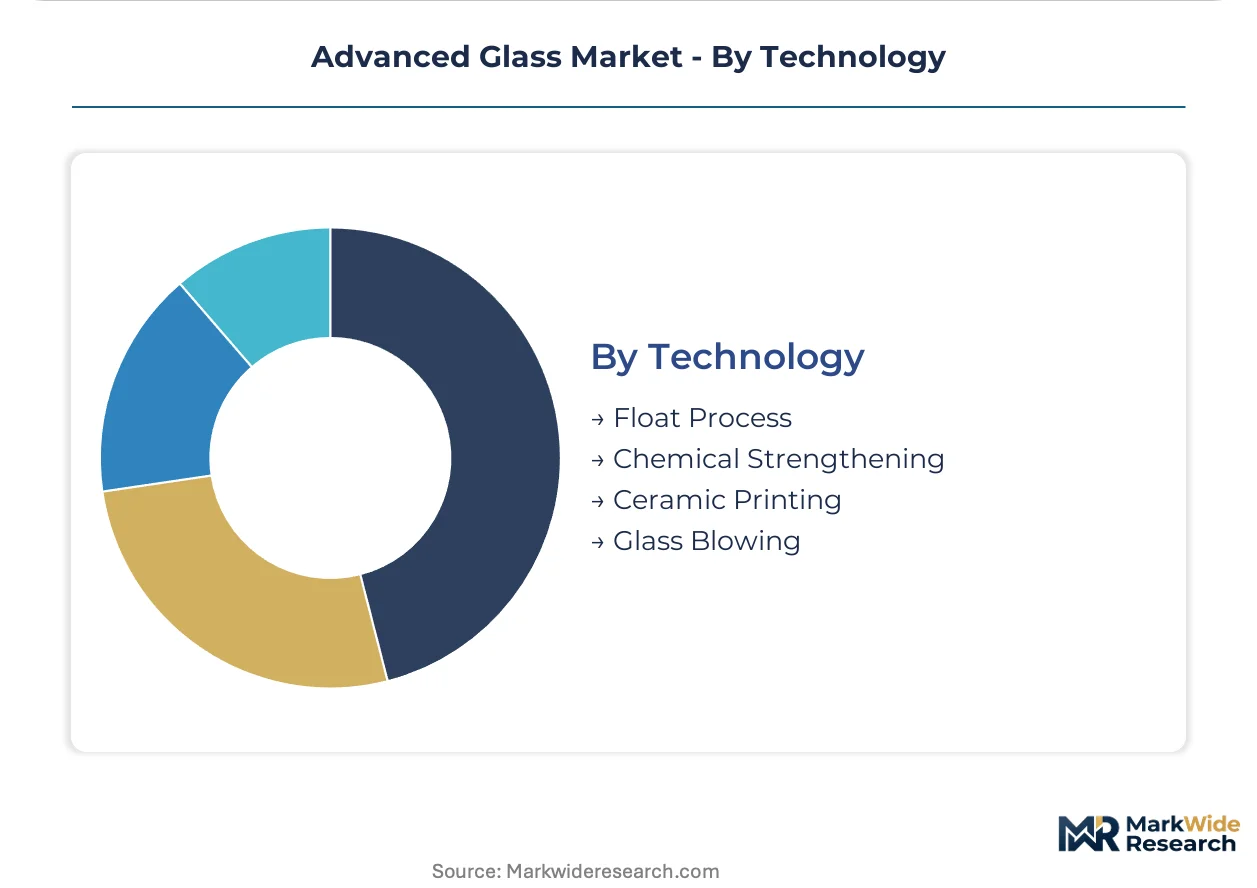
Technology:
Technology segments map to capital intensity and technical workforce availability, with float process capacity concentrated in legacy industrial regions versus chemical strengthening's proximity to electronics manufacturing clusters.
- Float Process:Molten glass ribbon formation on molten tin baths producing pristine flat substrates. Saint-Gobain leverages its integrated float infrastructure across France and Germany to dominate premium coated glass output for commercial facades.
- Chemical Strengthening:Ion exchange in molten potassium salt baths creating compressive surface layers. Electronics manufacturers in South Korea and Taiwan source ultra-thin strengthened substrates for foldable display applications.
- Ceramic Printing:Frit-based decorative and functional patterning fused during tempering. Automotive OEMs specify printed defrosting grids and antenna integration in rear windows.
- Glass Blowing:Artisan and precision scientific glassware production. Laboratory equipment manufacturers in Germany and Switzerland maintain captive blowing capabilities for complex borosilicate apparatus.
Float Process anchors the volume base; Chemical Strengthening shows the steepest expansion trajectory on display technology proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the most concentrated advanced glass demand cluster globally, with megacity construction codes mandating energy-efficient glazing across high-rise residential and commercial towers.
China
GB standards enforced by MIIT mandate low-emissivity coated substrates in Shenzhen and Guangzhou developments. Eastern coastal provinces concentrate tempered glass fabrication for domestic construction and export markets. Yangtze River Delta manufacturers supply solar panel cover glass to photovoltaic installers across Asia-Pacific.
Germany
EU Green Deal renovation targets accelerate triple-glazed unit retrofits in legacy commercial facades across Berlin and Munich. REACH chemical compliance frameworks restrict certain coating precursors, forcing reformulation of interlayer plasticizers. North Rhine-Westphalia hosts integrated float glass infrastructure serving premium coated output for European facades.
United States
Inflation Reduction Act efficiency incentives accelerate high-performance building envelope retrofits across Texas and Florida commercial stock. NHTSA optical distortion standards govern automotive glazing safety for Detroit and Tennessee OEM supply bases. EPA energy efficiency mandates shape product formulation for imported substrates.
India
LEED-certified office construction in Bangalore and Hyderabad technology corridors creates specification pull for solar-control coated glass. BIS performance benchmarks enforce domestic quality standards that foreign suppliers must satisfy. Maharashtra and Gujarat industrial corridors attract tempered glass capacity for residential and infrastructure end uses.
Japan
METI industrial guidelines promote high-performance glazing in Tokyo and Osaka commercial redevelopment projects. Automotive OEMs in Nagoya and Hiroshima specify laminated windshields for electric vehicle architectures. JIS standards govern interlayer clarity and electromagnetic shielding compatibility for transportation applications.
Advanced Glass Market Vendor Landscape
The competitive structure tilts toward integrated material conglomerates with captive float glass infrastructure. Tiered specialization separates premium coated substrate suppliers from volume-driven tempered glass fabricators. Three archetypes dominate: integrated chemical-material conglomerates controlling raw material-to-glass value chains; precision optical specialists serving electronics and display markets; and regional scale players optimizing cost-position in construction-grade safety glass. Capacity expansion and coating technology licensing represent the dominant competitive vectors as players recalibrate for electrification and energy-efficiency demand.
Within the integrated conglomerate tier, Saint-Gobain and AGC Inc. exemplify archetypes leveraging float process infrastructure across multiple continents. Corning Incorporated occupies a position representing precision optical specialization, anchoring the chemically strengthened substrate segment where display technology requirements command premium positioning. Xinyi Glass Holdings Limited sits within the scale-driven regional fabricator archetype, optimizing cost-competitive tempered production for Asia-Pacific residential and industrial procurement patterns.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc. |
| Corning Incorporated |
| Nippon Sheet Glass Co., Ltd. |
| Guardian Industries |
| Schott AG |
| PPG Industries, Inc. |
| Xinyi Glass Holdings Limited |
| Asahi Glass Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Silica sand benchmark volatility from Australian and Chinese foundry-grade deposits cascades through float glass manufacturing into three distinct pricing tiers: premium coated substrates for commercial facades, standard tempered safety glass for residential construction, and economy-grade architectural units where cost compression dominates procurement decisions.
Pricing Analysis
Energy-performance outcomes anchor value-based pricing for high-performance glazing, with solar heat gain coefficient ratings commanding premiums in LEED-certified developments. Price differentiation separates vacuum-insulated units from standard double-glazing through thermal bridging coefficients and gas-fill warranties. Cost compression in economy tempered glass is intensifying because Chinese eastern coastal capacity expansion outpaces Western demand growth. Residential contractors in India and Southeast Asia exhibit highest price sensitivity, while European commercial developers prioritize certification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany's North Rhine-Westphalia and China's Yangtze River Delta operate hub-and-spoke patterns serving fabrication networks across Western Europe and Asia-Pacific. Manufacturing concentrates in China, Germany, and the United States, with float process capacity anchored in legacy industrial corridors. Raw material flows draw from high-purity silica deposits in Australia, soda ash from the United States, and tin for float baths from Indonesia. Single-source vulnerability in specialized interlayer polymers from select European chemical producers threatens laminated glass continuity. Distribution runs through direct-to-fabricator digital platforms fragmenting traditional stockholding intermediaries in standardized tempered products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced glass has become a vertical-integration race where captive float infrastructure and coating technology licensing determine margin capture. Players are pursuing upstream control over high-purity silica deposits to secure input cost stability.
For Market Incumbents: Anchor market position through captive borosilicate conversion capacity and exclusive interlayer formulation partnerships. Polycarbonate glazing substitution in automotive side-windows threatens traditional laminated specifications. Defend against this displacement by accelerating electromagnetic shielding certification for electric vehicle battery enclosures. Prioritize furnace rebuild cycles toward aluminosilicate chemistries serving display substrate demand. For New Entrants and Emerging Players: Begin with electrochromic thin-film deposition capabilities targeting California and New York net-zero commercial certifications. India's Bangalore and Hyderabad LEED office construction offers the most penetrable geography for solar-control coated glass specification. Pursue technology licensing from established magnetron sputtering equipment manufacturers rather than greenfield process development. For Investors and Strategic Acquirers: The window for entry favors precision optical specialists with atomic layer deposition expertise over commodity tempered fabricators. Long-term viability hinges on display technology proliferation and automotive electrification glazing demand. Target mid-cap coating technology firms with established OEM validation timelines. Watch NHTSA optical distortion standard revisions as inflection indicators for automotive qualification barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Float Line Reconfiguration | Converting soda-lime capacity to borosilicate chemistries serves semiconductor packaging demand from South Korean electronics manufacturers. |
| Atomic Layer Deposition Transition | Migrating from plasma-enhanced chemical vapor deposition satisfies REACH F-Gas Regulation restrictions on fluorinated greenhouse gas precursors. |
| Direct-to-Fabricator Digital Platform | Bypassing regional distributor hierarchies captures margin compression in standardized tempered glass for German and Dutch glazing contractors. |
| Interlayer Formulation Partnership | Securing exclusive ionomer supply agreements differentiates laminated glass offerings for acoustic dampening in premium electric vehicles. |
| High-Purity Silica Backward Integration | Captive Australian and Chinese foundry-grade sand deposits insulates against input cost volatility threatening float glass margins. |
Methodological Framework
Multi-period observation of construction permit data, automotive production schedules, and solar panel installation rates anchored the trend analysis, supplemented by interviews with float plant managers, commercial glazing procurement leads, coating technology R&D directors, and building code enforcement officials. Secondary validation drew from customs and trade databases, EU Green Deal implementation reports, SEC 10-K filings from listed glass manufacturers, and MIIT industrial guideline publications. Bottom-up project pipeline enumeration triangulated against top-down macroeconomic scenario weighting.
Segment-weighting approaches distributed value and volume across product type, application, end user, and technology dimensions throughout the forecast period. CAGRs derived from regression analysis against construction spending indices, vehicle production forecasts, and solar capacity deployment trajectories. Industry-specific inputs included tempered glass safety code adoption timelines, electrochromic glazing penetration assumptions in commercial real estate, and REACH chemical compliance cost pass-through estimates.
Underlying measurement precision varies by segment; electronics display substrates and automotive laminated glass carry tighter precision than commodity tempered construction products due to longer validation cycles and consolidated supplier bases. Forecasts reflect assumptions about regulatory trajectory continuity, electrification adoption curves, and energy-efficiency code enforcement intensity. Periodic stress-testing of base assumptions against building retrofit mandate acceleration and automotive platform architecture shifts is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Global Glass Tempering System Market
Glass
Glass Polishing Powder Market
Glass
Solar Control Glass Market
Glass
Global Laminated Glass Market
Glass
Foam Glass Market
Glass
Optical Glass Market
Glass
Global Glass Flake Coatings Market
Glass
Flexible Glass Market
Glass
Laboratory Glassware Market
Glass
Glass Mat Market
Glass
Birefringent Crystals Market
Glass
Tempered Glass Market
Glass
Fiberglass Window Market
Glass
Laboratory Glass Container Market
Glass
Glass Alternative Materials Market
Glass
Europe Sapphire Glass Market