
 Alumina Slurry Market | 2026-2036
Alumina Slurry Market Size, Share, and Industry Trends Forecast 2026-2036
Alumina Slurry Market Insights
REACH chemical registration protocols in Europe are recalibrating the cost-of-entry calculus for alumina slurry suppliers seeking access to EU electronics manufacturing customers. Saint-Gobain leverages its integrated ceramic materials platform to sustain supply security across multiple purity grades. Fujimi Corporation anchors its position through specialized polishing compound formulations for silicon carbide substrates. Entegris competes on advanced contamination control protocols that meet semiconductor fab qualification thresholds.
Alumina slurry denotes a colloidal suspension of aluminum oxide particles, typically ranging from 0.05 to 3.0 microns in median particle size, dispersed in aqueous or solvent-based carriers for precision surface finishing applications. The suspension enables controlled material removal rates in chemical mechanical planarization processes essential to semiconductor wafer fabrication. Wet slurry formulations dominate volume consumption due to their established integration with existing CMP tool infrastructure and predictable rheological behavior. Electronics end users represent the fastest-expanding demand pool as advanced node chip production escalates substrate polishing intensity. Ceramic slurry variants command premium positioning where thermal stability and minimal trace metal contamination prove critical to yield performance.
EPA industrial chemical reporting requirements in the United States mandate disclosure of aluminum oxide nanoparticle content in commercial slurry formulations, shaping product registration strategies for domestic suppliers. ECHA substance evaluation procedures under REACH directly influence import certification timelines and testing expenditure for non-European manufacturers. China's GB standards for electronic-grade chemicals, administered by SAMR, establish parallel compliance pathways that suppliers must navigate for access to mainland semiconductor fabs. Stakeholders must monitor evolving purity specifications from foundry customers rather than regulatory bodies alone to anticipate formulation upgrade cycles.
Market Dynamics
Semiconductor node shrinkage below 7nm is intensifying polishing precision requirements, forcing slurry suppliers to recalibrate particle size distributions and contamination thresholds faster than equipment upgrade cycles.
Growth Catalysts
- Advanced Packaging Proliferation:Chiplet architectures and 3D stacking in logic devices multiply planarization steps per wafer, expanding volume consumption per finished substrate.
- Silicon Carbide Substrate Expansion:Electric vehicle power electronics manufacturing is consuming specialized alumina formulations optimized for wide-bandgap material polishing.
- South Korea Memory Fab Buildout:Pyeongtaek and Yongin corridors are adding capacity that concentrates demand for electronic-grade slurry procurement.
Market Restraints
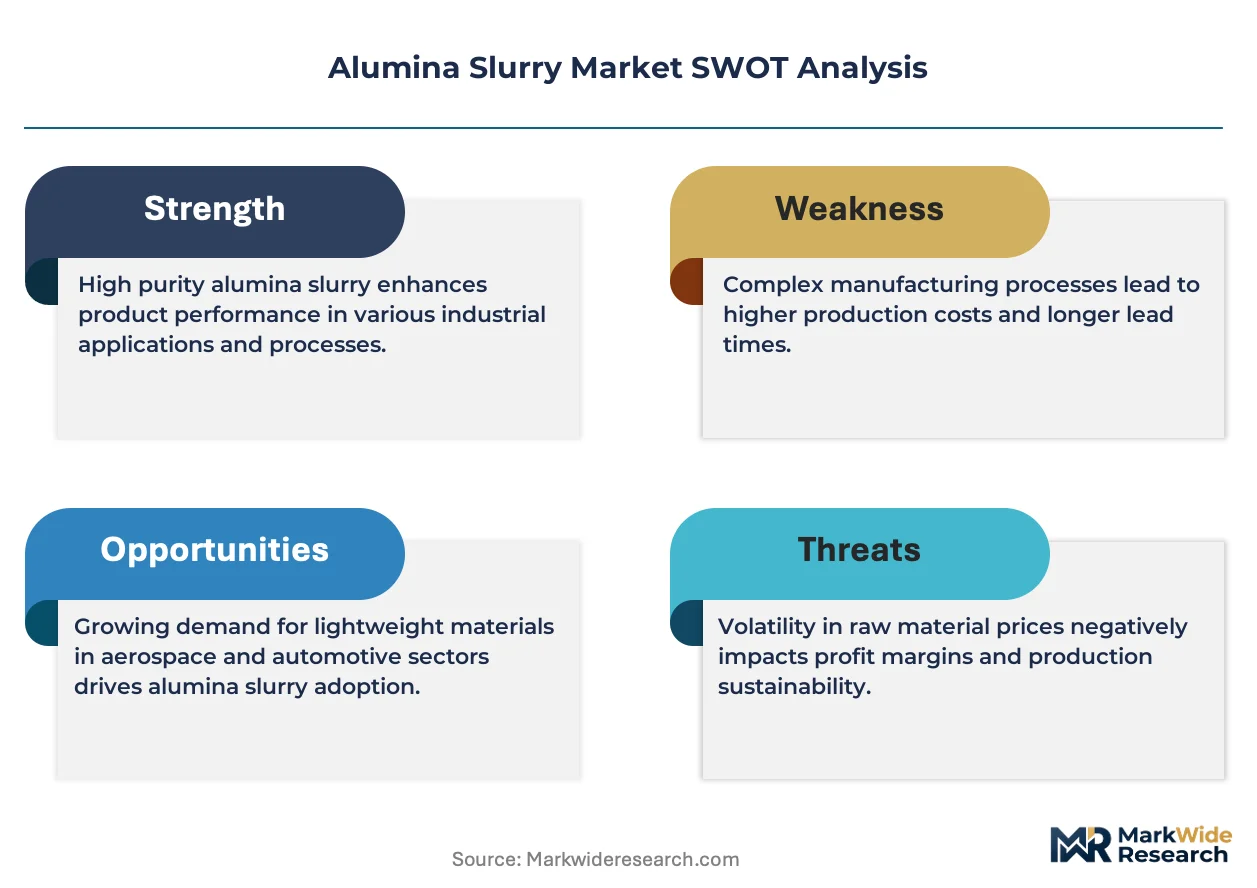
- High-Purity Alumina Feedstock Concentration:Four Japanese chemical houses control over 70% of 4N+ purity alumina powder supply, creating single-source vulnerability for formulated slurry producers.
- REACH Registration Cost Burden:ECHA substance evaluation procedures impose testing expenditures exceeding €200,000 per formulation variant, compressing margin structures for smaller import suppliers.
- Ceria Slurry Substitution in Oxide CMP:Cerium oxide formulations achieve higher oxide removal rates in shallow trench isolation applications, displacing alumina in select process nodes.
Strategic Opportunities
- India Semiconductor Mission Incentives:PLI scheme disbursements and Dholera fab zone development are creating first-mover positioning for slurry suppliers establishing local blending operations.
- Recyclable Slurry Systems:Closed-loop filtration and particle recovery technologies enable service-based revenue models displacing single-use product sales.
- GB Standard Alignment:SAMR electronic-grade chemical certifications for mainland China fabs allow qualified foreign suppliers to bypass joint venture requirements in select process categories.
Industry Challenges
- Contamination Control Expertise Gap:Semiconductor fab qualification protocols demand personnel capable of managing parts-per-trillion trace metal specifications, a skill set concentrated among veteran formulation chemists nearing retirement.
- Dual-Regulatory Certification Timelines:Simultaneous EPA nanoparticle reporting and ECHA REACH dossier preparation extends product launch windows by 18-24 months for multi-region suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alumina Slurry Market |
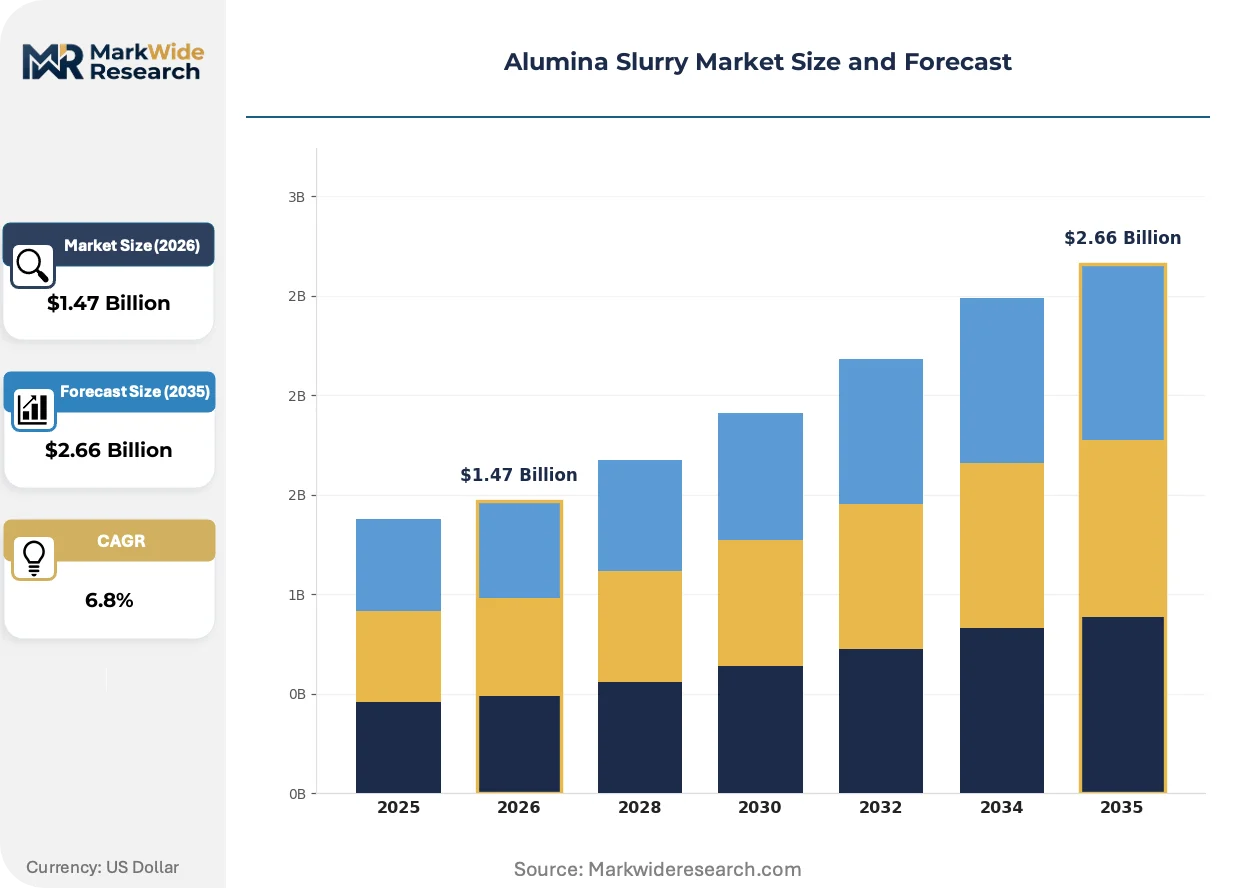
| Market Size in 2026 | $1.47 Billion |
| Market Size in 2035 | $2.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Slurry, Dry Slurry, Degassed Slurry, Ceramic Slurry Application: Polishing, Coating, Abrasive, Adhesive End User: Ceramics, Electronics, Aerospace, Automotive Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | AGSCO Corporation, Aritech Chemazone Private Limited, Saint-Gobain, Fujimi Corporation, Baikowski, CMC Materials, Entegris, Ferro Corporation, Almatis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alumina Slurry Market Trends and Innovations
Particle engineering and regulatory compliance automation are converging to redefine how slurry suppliers compete on specification adherence rather than commodity chemistry.
Colloidal silica-alumina hybrid abrasives are rewriting removal rate predictability in advanced node copper CMP. Memory manufacturers in South Korea's Hynix and Samsung corridors are qualifying these formulations for sub-5nm layer planarization. The technology is compressing the performance gap between established slurry families and enabling single-supplier consolidation for multi-layer stacks.
EPA industrial chemical reporting requirements for aluminum oxide nanoparticles are mandating real-time particle characterization data submission. Domestic suppliers are embedding inline metrology systems to automate batch-level disclosure. Electronics-grade slurry categories face the steepest compliance cost escalation as particle size thresholds trigger enhanced toxicity testing protocols.
Consolidated procurement through foundry-level master service agreements is displacing tool-specific supplier fragmentation. Taiwan Semiconductor Manufacturing and GlobalFoundries are centralizing slurry selection authority at corporate technical committees rather than individual fab engineering teams. This pattern concentrates contract volumes with fewer qualified suppliers and compresses qualification timelines for second-source alternatives.
Alumina Slurry Market Segmentation
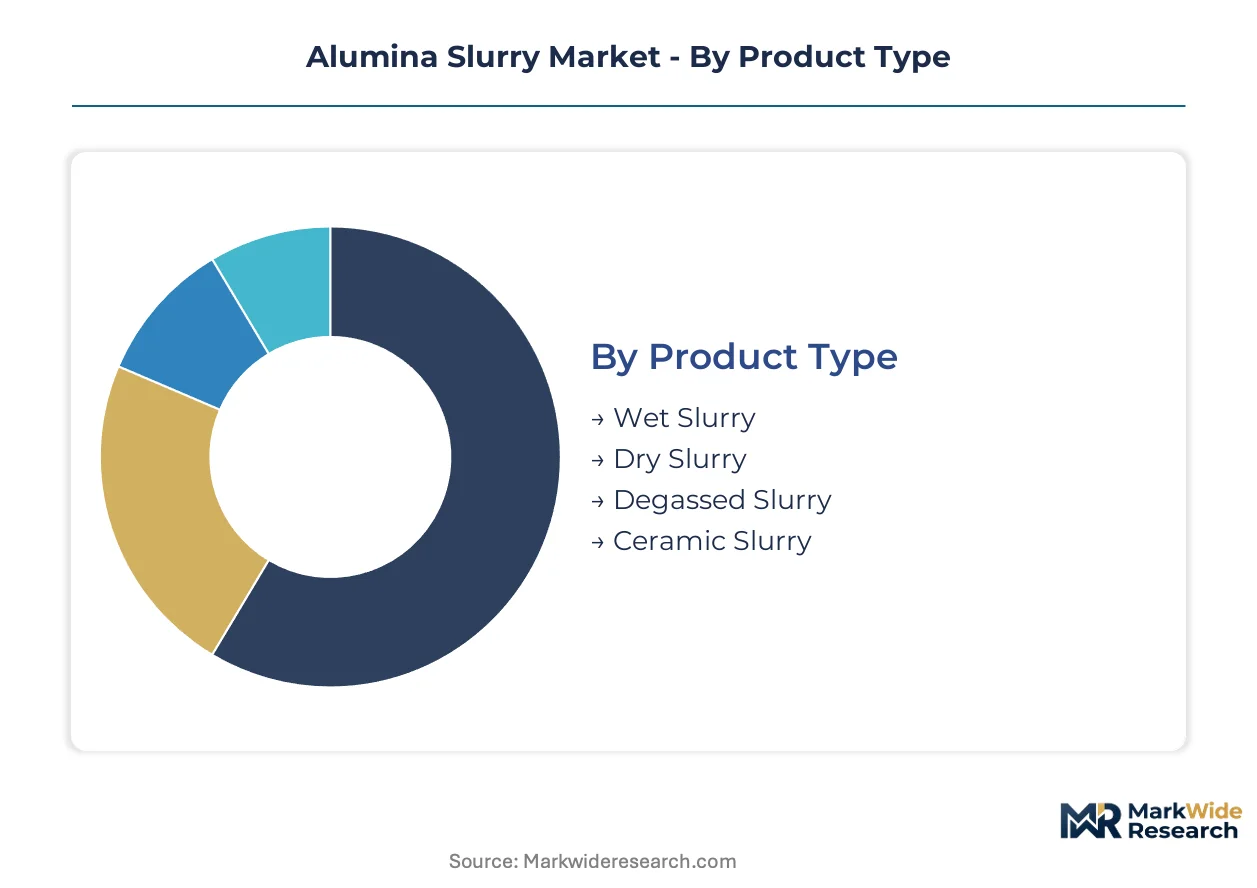
Alumina slurry formulations diverge sharply across purity grades and carrier systems, with semiconductor-grade specifications commanding multiples over industrial abrasives. Segmentation discipline separates volume commodity plays from premium qualification-dependent positions.
Product Type:
Wet slurry dominates tonnage while ceramic variants extract margin premiums through contamination control.
- Wet Slurry:Aqueous suspensions of aluminum oxide particles in the 0.05-3.0 micron range, formulated for predictable rheological behavior in chemical mechanical planarization tools. Samsung and SK Hynix fabs in South Korea's Pyeongtaek corridor consume the largest qualified volumes for memory wafer polishing. The segment faces pressure from closed-loop filtration systems that extend useful life and compress replacement frequency.
- Ceramic Slurry:Specialized formulations engineered for thermal stability and parts-per-trillion trace metal control, essential to yield performance in advanced node production. Taiwan Semiconductor Manufacturing and GlobalFoundries specify these grades for sub-7nm layer stacks where particle contamination thresholds tighten with each node shrink. ECHA REACH registration costs exceeding €200,000 per formulation variant restrict supplier participation to integrated materials platforms.
- Dry Slurry:Powder concentrates requiring on-site reconstitution, favored by cost-sensitive industrial polishers in automotive component finishing.
- Degassed Slurry:Vacuum-processed formulations eliminating dissolved gases that generate microbubbles during high-speed CMP operations, qualified for critical layer planarization.
Today's leader: Wet Slurry. Tomorrow's challenger: Ceramic Slurry.
Application:
Semiconductor polishing intensity separates premium formulation demand from industrial abrasive consumption.
- Polishing:Chemical mechanical planarization for silicon, silicon carbide, and oxide substrates, with process steps multiplying under chiplet architectures. South Korea's memory fab buildout concentrates demand for electronic-grade slurry procurement.
- Abrasive:Precision grinding and surface preparation across industrial manufacturing, with volume consumption tied to automotive and aerospace component output.
- Coating:Thin-film deposition preparation and surface modification applications in ceramic substrate manufacturing.
- Adhesive:Specialized binding applications where alumina particles provide thermal conductivity and mechanical reinforcement.
Polishing applications expand most quickly as advanced packaging multiplies planarization steps per finished wafer.
End User:
Electronics manufacturing concentrates premium demand while ceramics and automotive absorb commodity grades.
- Electronics:Semiconductor wafer fabrication and advanced packaging operations, with qualification protocols demanding parts-per-trillion trace metal specifications. EPA nanoparticle reporting requirements and ECHA REACH dossiers impose 18-24 month certification timelines for multi-region suppliers.
- Ceramics:Structural ceramic manufacturing and refractory applications, consuming standard purity grades with less stringent contamination thresholds.
- Aerospace:Precision component finishing and thermal barrier coating preparation, requiring specialized formulations for nickel-based superalloys.
- Automotive:Power electronics substrate polishing for electric vehicle inverters, with silicon carbide wafer consumption expanding specialized alumina formulation demand.
Electronics end users gain share fastest as node shrinkage below 7nm intensifies polishing precision requirements.
Distribution Channel:
Direct relationships dominate semiconductor-grade supply while distributors handle industrial volumes.
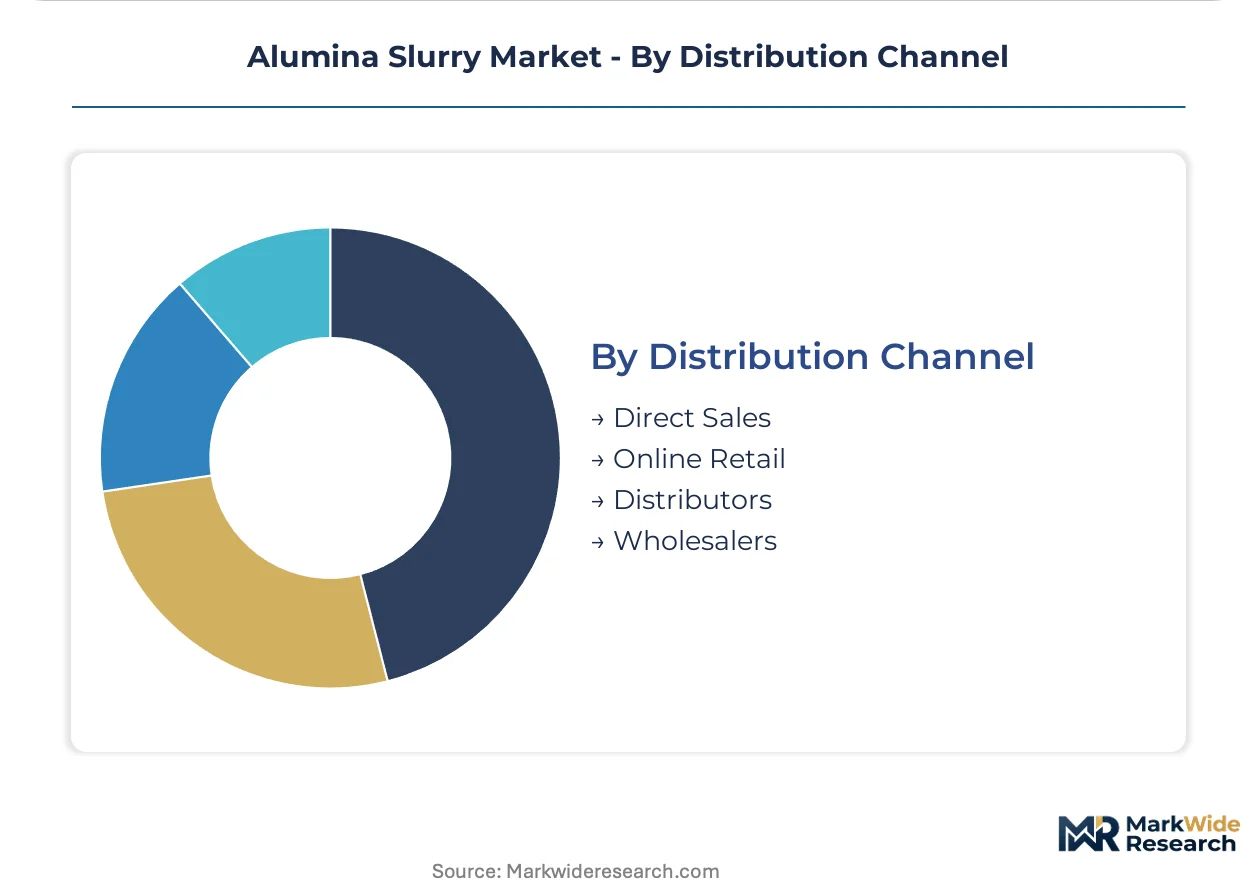
- Direct Sales:Master service agreements with foundry-level technical committees at Taiwan Semiconductor Manufacturing and GlobalFoundries, centralizing slurry selection authority and compressing qualification timelines for second-source alternatives.
- Distributors:Regional chemical distributors serving fragmented industrial abrasive demand across automotive and ceramics end users.
- Online Retail:E-commerce platforms for small-volume laboratory and research applications, with limited penetration in production-scale procurement.
- Wholesalers:Bulk commodity channels for standard purity grades in cost-sensitive industrial polishing operations.
Direct Sales channels capture margin premiums through technical service integration, while Distributors retain volume leverage in industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists with parts-per-trillion contamination control expertise concentrate in East Asian semiconductor corridors and European industrial chemical centers, anchoring regional supply capabilities.
United States
EPA industrial chemical reporting requirements for aluminum oxide nanoparticles mandate real-time particle characterization data submission from domestic suppliers. Austin and Phoenix semiconductor fab clusters drive demand for electronic-grade slurry procurement. Inline metrology systems embedded in production lines automate batch-level disclosure compliance.
South Korea
Samsung and SK Hynix memory operations in Pyeongtaek and Yongin corridors consume the largest qualified volumes for wafer polishing. MFDS chemical safety protocols align with semiconductor fab qualification standards. Government-backed K-Semiconductor Belt initiatives accelerate capacity additions requiring specialized alumina formulation supply.
Japan
METI industrial standards for electronic-grade chemicals establish purity benchmarks that propagate across Asian supply chains. Four Japanese chemical houses control over 70% of 4N+ purity alumina powder feedstock. Nagoya and Kyushu industrial zones maintain integrated ceramic materials platforms serving formulated slurry producers.
Taiwan
TSMC and GlobalFoundries centralize slurry selection authority at corporate technical committees rather than individual fab engineering teams. Hsinchu Science Park concentration creates consolidated procurement through master service agreements. Sub-7nm layer stack production tightens particle contamination thresholds with each node shrink.
China
SAMR GB standards for electronic-grade chemicals establish parallel compliance pathways for mainland semiconductor fabs. Yangtze River Delta and Pearl River Delta clusters expand silicon carbide substrate manufacturing for electric vehicle power electronics. Dual carbon goals pressure suppliers toward closed-loop filtration and particle recovery technologies.
Alumina Slurry Market Competitive Landscape
The competitive structure tilts toward integrated materials platforms with captive high-purity feedstock access and specialized polishing compound formulators with deep fab qualification relationships. Three archetypes dominate: diversified industrial materials conglomerates with ceramic expertise, precision abrasives specialists serving semiconductor customers, and regional chemical distributors handling industrial-grade volumes. Capacity expansion in East Asian semiconductor corridors and strategic partnerships for contamination control technology licensing represent the dominant competitive moves.
Among diversified materials platforms, Saint-Gobain exemplifies the integrated archetype with European ceramic heritage, while Fujimi Corporation occupies a position as a precision abrasives specialist with Japanese industrial roots. Entegris represents the contamination control-focused tier with North American semiconductor service lineage. These three anchors illustrate how feedstock security, formulation specialization, and fab qualification depth stratify competitive positioning.
| Leading Market Players |
|---|
| AGSCO Corporation |
| Aritech Chemazone Private Limited |
| Saint-Gobain |
| Fujimi Corporation |
| Baikowski |
| CMC Materials |
| Entegris |
| Ferro Corporation |
| Almatis |
| Others |
Pricing and Supply Chain Analysis
Closed-loop filtration technology adoption simultaneously compresses per-wafer slurry consumption and concentrates procurement power among fabs with captive particle recovery systems. This operational shift recalibrates supplier pricing power toward service-integrated contracts and away from pure product transactions.
Pricing Analysis
Bundled service contracts incorporating on-site technical support and contamination monitoring command 15-30% premiums over unbundled product-only supply. Three-tier pricing structure across electronic-grade, industrial-grade, and research-grade formulations reflects certification burden differentials. Cost compression in standard purity tiers intensifies because REACH registration expenses exceed €200,000 per variant. Memory fabs in South Korea's Pyeongtaek corridor exhibit lowest price sensitivity due to yield-critical contamination thresholds.
Supply Chain Analysis
Reverse-logistics flows for spent slurry recovery remain underdeveloped, creating stranded value in single-use disposal models. High-purity alumina feedstock concentrates in Japan, with four chemical houses controlling 70% of 4N+ powder supply. Formulated slurry production draws from specialty chemical capabilities in South Korea, Taiwan, and the United States. Single-source vulnerability in Japanese feedstock creates structural risk for non-integrated formulators. Distribution runs through direct master service agreements with foundry technical committees rather than fragmented tool-level procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a margin-expansion story as closed-loop service models displace commodity product sales and premium ceramic grades capture value from sub-7nm node qualification requirements.
For Market Incumbents: Cement feedstock security through backward integration into high-purity alumina powder production or long-term offtake agreements with Japanese suppliers. Deepen contamination control expertise pipelines to replace retiring formulation chemists. Ceria slurry substitution in oxide CMP applications threatens volume in legacy process nodes. For New Entrants and Emerging Players: Capture first-mover positioning in India's Dholera fab corridor before incumbent qualification timelines lock out alternatives. The automotive silicon carbide substrate polishing segment offers most penetrable entry point due to less stringent purity thresholds than logic fabs. Lead with recyclable slurry system pilots that convert capital expenditure into operational savings narratives. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors lacking direct foundry relationships and contamination control IP. Long-term viability favors integrated materials platforms with captive feedstock and formulation capabilities. Watch for SAMR GB standard alignment announcements as inflection signal for China market access liberalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Alumina | Secures feedstock autonomy against Japanese supplier concentration risk. |
| Closed-Loop Filtration Technology Licensing | Enables service-based revenue models at Samsung and SK Hynix fabs. |
| India Local Blending Operations | Captures PLI scheme benefits and Dholera corridor demand concentration. |
| ECHA REACH Dossier Automation | Compresses 18-24 month certification timelines for multi-region suppliers. |
| Colloidal Silica-Alumina Hybrid Development | Qualifies sub-5nm planarization formulations for TSMC layer stacks. |
Research Methodology
Bottom-up semiconductor fab consumption modeling reconciled against top-down specialty chemical production tracking forms the analytical core. Primary interviews with CMP process engineers, foundry procurement directors, slurry formulation chemists, and contamination control specialists combined with secondary validation from SEC filings, customs trade data, and ECHA registration databases. Triangulation across supply-side capacity announcements and demand-side tool installation records ensures coherence.
Input-output matrices map alumina powder production through formulation blending to end-use consumption across purity grades and application segments. Segmentation dimensions include product type, end-use industry, regional production hub, and certification tier. CAGRs derive from regression analysis of historical consumption intensity against semiconductor node transition timelines and packaging architecture shifts. Forecast inputs incorporate electric vehicle power electronics buildout rates and memory fab capacity expansion schedules.
Underlying measurement precision varies by segment; electronic-grade slurry volumes carry tighter precision than industrial abrasive categories due to consolidated procurement transparency. Forecasts reflect assumptions regarding node shrinkage cadence and regulatory certification timeline stability. Practitioners should monitor REACH substance evaluation backlog developments and SAMR GB standard implementation pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Asia-Pacific Kaolin Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
Activated Alumina Market
Ceramics
Mullite Market
Ceramics
Southeast Asia Melamine Market
Ceramics
Calcined Kaolin Market
Ceramics
Ball Clay Market
Ceramics
Thailand Ceramic Tiles Market
Ceramics
Ceramic Frit Market
Ceramics
Ceramics Packaging Market
Ceramics
Thermal Spray Powder Market
Ceramics
Aluminium Nitride Market
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
Global Alumina Market
Ceramics
Medical Ceramics Market
Ceramics
Graphite Crucibles Market