
 Silica Sand Market | 2026-2036
Silica Sand Market Size, Share, and Industry Trends Forecast 2026-2036
Silica Sand Market Analysis
High-purity grade silica is rotating toward premium pricing as solar glass and semiconductor foundry buyers tighten chemical tolerance thresholds. U.S. Silica leverages its Appalachian basin logistics network to sustain frac sand dominance while diversifying into industrial specialties. Sibelco anchors European supply through its Quarzwerke GmbH subsidiary, which dominates Central European high-iron glass sand deposits. Badger Mining Corporation specializes in western Wisconsin deposits that compete on grain roundness and crush resistance for oilfield proppant applications.
Silica sand consists primarily of silicon dioxide in granular form, typically exceeding 95% SiO₂ content with controlled gradation between 0.063 mm and 2.00 mm for industrial use; producers wash, classify, and acid-leach raw ore to achieve chemical specifications demanded by glass melting and hydraulic fracturing operations. Container glass commands the largest volume share among product type segments due to recurring demand from beverage packaging, though specialty glass carries the widest margin pool owing to optical and photovoltaic purity requirements. Foundry applications face structural pressure from binder system substitutions, while oil and gas consumption fluctuates with North American rig counts and proppant intensity per well.
The U.S. EPA and OSHA impose respirable crystalline silica exposure limits that elevate processing costs and disqualify marginal deposits from commercial viability. REACH registration requirements in Europe restrict imports from non-compliant jurisdictions and favor established Quarzwerke GmbH and Sibelco processing assets. China's GB standards and Ministry of Ecology and Environment enforcement are tightening on open-pit mining restoration bonds, reshaping export availability from Shandong and Fujian provinces. Stakeholders must monitor regulatory divergence between jurisdictions as compliance cost spreads widen and determine whether to consolidate upstream mining rights or outsource beneficiation to third-party processors.
Market Dynamics
High-purity silica sand supply chains are tightening as photovoltaic glass manufacturers impose stricter chemical tolerance thresholds on feedstock, compressing the pool of commercially viable deposits and elevating processing requirements for incumbent producers.
Growth Catalysts
- REACH compliance mandates:European foundries under the Industrial Emissions Directive are upgrading to low-dust processed grades, creating sustained demand for beneficiated silica with controlled respirable crystalline silica content.
- Solar panel fabrication expansion:Glass manufacturers across Asia-Pacific are absorbing larger volumes of high-purity feedstock as photovoltaic capacity buildouts accelerate, tightening specification windows for iron and titanium impurities.
- Infrastructure buildouts:India's domestic glass capacity additions and construction material demand are drawing import flows from Australian and Southeast Asian mining operations, reshaping regional trade corridors.
Market Restraints
- Energy cost volatility:Wet processing and thermal drying operations face margin compression from natural gas and electricity price swings, particularly affecting acid-leaching facilities in energy-intensive jurisdictions.
- Deposit concentration risk:Western Wisconsin's premium round-grain deposits dominate oilfield proppant supply, creating geographic single-point vulnerability to localized weather or logistics disruptions.
- Foundry binder substitution:Ceramic and chemically bonded mold technologies are eroding traditional green sand foundry demand, displacing silica consumption in metal casting applications.
Strategic Opportunities
- Semiconductor foundry feedstock:Ultra-high-purity grades for crucible and wafer processing command premium pricing as chemical tolerance thresholds tighten below 50 ppm total impurities.
- Appalachian logistics leverage:Proximity to Marcellus-Utica shale basins enables integrated proppant-to-wellhead supply models with reduced rail and transload costs.
- EU Green Deal alignment:Carbon border adjustment mechanisms and embodied carbon tracking favor low-carbon beneficiation routes, rewarding energy-efficient processing investments.
Industry Challenges
- Respirable silica compliance:OSHA enforcement of permissible exposure limits elevates capital requirements for dust suppression systems and disqualifies marginal deposits lacking processing infrastructure.
- Beneficiation skill scarcity:Acid-leaching and magnetic separation expertise concentrates among legacy operators, constraining capacity expansion for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silica Sand Market |
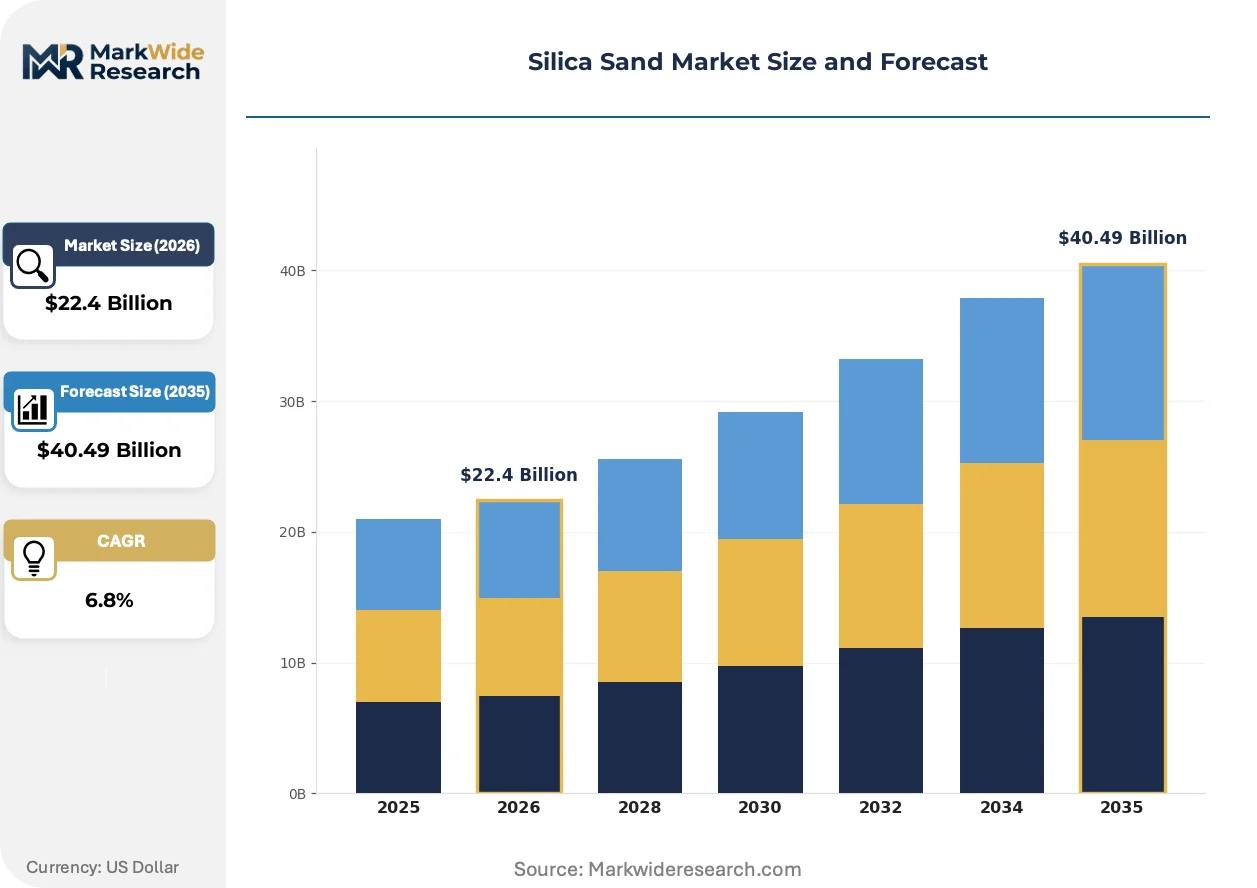
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $40.49 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Glass, Container Glass, Specialty Glass, Fiberglass Application: Construction, Foundry, Oil & Gas, Water Filtration End User: Construction Companies, Metal Manufacturers, Oil Operators, Environmental Agencies Grade: High Purity, Low Iron, Regular, Coarse |
| Companies Covered | Badger Mining Corporation, Sil Industrial Minerals, U.S. Silica, Quarzwerke GmbH, Source Energy Services, Sibelco, Mitsubishi Corporation, TOCHU CORPORATION, Covia Holdings LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silica Sand Market Emerging Trajectories
Processing technology and regulatory chemistry specifications are converging to bifurcate the silica sand market between commodity construction grades and premium specialty tiers with diverging margin structures.
Advanced optical sorting systems employing near-infrared and X-ray fluorescence detection are supplanting traditional wet gravity separation for high-purity applications. Solar glass manufacturers in India and Southeast Asia are adopting these systems at greenfield sites to achieve sub-100 ppm iron content consistently. The technology is compressing the viable supply base to deposits with favorable inherent chemistry rather than upgradeable ore bodies.
China's Ministry of Ecology and Environment is tightening enforcement of open-pit mining restoration bonds and water discharge permits under evolving GB standards. Shandong and Fujian provincial authorities are rejecting permit renewals for operations lacking closed-loop water systems. Export-oriented processors are responding by consolidating mining rights and outsourcing beneficiation to third-party toll processors with compliant infrastructure.
Container glass buyers are consolidating procurement around long-term offtake agreements with embedded price adjustment mechanisms, displacing spot market transactions. Major beverage packaging converters in Western Europe and North America are favoring vertically integrated sand-to-glass suppliers with certified carbon footprints. The shift is most visible in Germany and France, where CSRD reporting requirements and customer Scope 3 targets demand supply chain transparency.
Silica Sand Market Segmentation
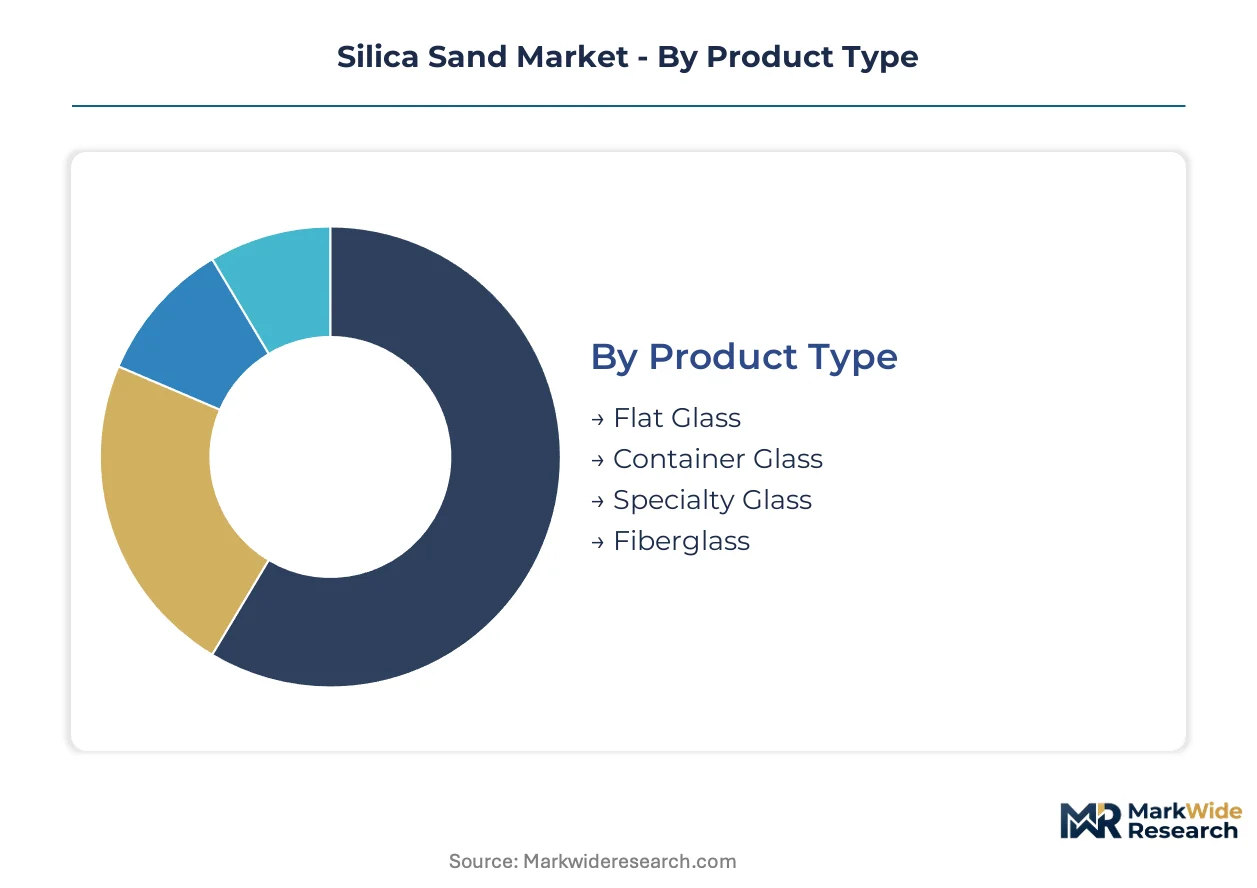
Silica sand market segmentation reveals stark margin dispersion between commodity construction grades and premium specialty tiers. Specification thresholds for iron content and grain morphology create divergent pricing structures that reward beneficiation capabilities over raw deposit quality alone.
Product Type:
Margin pools concentrate in segments where chemical purity commands premium pricing over volume throughput.
- Container Glass:Beverage packaging applications dominate volume flows with recurring demand cycles. Procurement concentrates around long-term offtake agreements with embedded price adjustment mechanisms in Western Europe and North America.
- Specialty Glass:Optical and photovoltaic purity requirements carry the widest margin spreads. Solar panel fabricators in Asia-Pacific are tightening iron and titanium tolerance thresholds below 100 ppm, compressing the supplier base to acid-leaching capable operations.
- Flat Glass:Architectural and automotive glazing consumes standardized grades with moderate beneficiation requirements.
- Fiberglass:Insulation and composite reinforcement applications prioritize consistent grain distribution over extreme purity.
The dominant share belongs to Container Glass, while Specialty Glass is closing the gap fastest.
Application:
Cost tier stratification separates energy-intensive processing segments from direct-mining sales.
- Oil & Gas:Hydraulic fracturing proppant specifications demand premium roundness and crush resistance. Western Wisconsin deposits supply North American shale basins with logistics-integrated delivery models.
- Foundry:Metal casting binders face structural displacement from ceramic and chemically bonded mold technologies. European foundries under REACH mandates are upgrading to low-dust processed grades with controlled respirable crystalline silica content.
- Construction:Concrete and mortar additives consume the lowest-cost unprocessed grades with minimal beneficiation.
- Water Filtration:Municipal and industrial treatment plants require controlled gradation and acid-soluble consistency.
Construction maintains volume leadership, though Oil & Gas exhibits the steepest margin volatility.
End User:
Customer procurement sophistication determines specification stringency and contract structure.
- Metal Manufacturers:Foundry operations demand consistent grain morphology for green sand systems. Indian infrastructure buildouts are drawing import flows from Australian mining operations.
- Oil Operators:Proppant buyers prioritize logistics reliability and wellhead proximity over marginal quality improvements. Appalachian basin proximity enables integrated supply models with reduced rail and transload costs.
- Construction Companies:Volume purchasers negotiate on delivered cost with minimal technical specification.
- Environmental Agencies:Water filtration procurement emphasizes certified compliance with discharge and restoration requirements.
Metal Manufacturers command the largest contract values, while Oil Operators are expanding procurement most aggressively.
Grade:
Supply concentration favors deposits with favorable inherent chemistry over upgradeable ore bodies.
- High Purity:Semiconductor crucible and wafer processing specifications command premium pricing. Chemical tolerance thresholds below 50 ppm total impurities restrict supply to acid-leaching and magnetic separation capable processors.
- Low Iron:Solar glass manufacturers in India and Southeast Asia are adopting optical sorting systems to achieve sub-100 ppm iron content consistently.
- Regular:Standard industrial applications tolerate moderate impurity levels with basic washing and classification.
- Coarse:Construction and filtration uses prioritize particle size distribution over chemical refinement.
Regular grade holds the broadest installed base, though High Purity is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Wisconsin's premium round-grain deposits anchor North American proppant supply, while Australian and Southeast Asian export flows increasingly serve Indian glass capacity buildouts. Regulatory divergence between EPA enforcement in the United States and REACH mandates in Europe is fragmenting processing standards across jurisdictions.
United States
Appalachian basin logistics networks sustain integrated proppant-to-wellhead supply models with reduced rail costs. OSHA respirable crystalline silica exposure limits elevate capital requirements for dust suppression systems across processing facilities. Western Wisconsin's Barron County and Chippewa County deposits dominate oilfield proppant supply with premium crush resistance specifications.
China
Shandong and Fujian provincial authorities are rejecting mining permit renewals for operations lacking closed-loop water systems. The Ministry of Ecology and Environment is tightening enforcement of open-pit mining restoration bonds under evolving GB standards. Export-oriented processors are consolidating mining rights and outsourcing beneficiation to compliant third-party toll processors.
Germany
Quarzwerke GmbH's Central European processing assets dominate high-iron glass sand deposits under REACH registration requirements. The Industrial Emissions Directive is pushing foundries toward low-dust processed grades with controlled respirable crystalline silica content. CSRD reporting requirements and customer Scope 3 targets are consolidating procurement around vertically integrated sand-to-glass suppliers.
India
Infrastructure buildouts and domestic glass capacity additions are drawing import flows from Australian mining operations. BIS standards and state-level mining department enforcement are reshaping feedstock sourcing for container glass manufacturers. Gujarat's special economic zones and Maharashtra's industrial corridors are emerging as concentration points for solar glass fabrication facilities.
Australia
Cape Flattery silica deposits in Queensland supply high-purity feedstock to Asia-Pacific photovoltaic glass manufacturers. State environmental protection agencies are tightening mine rehabilitation requirements and water discharge permits for coastal operations. Western Australia's Mid West region and New South Wales' Hunter Valley are seeing capacity additions targeting semiconductor-grade specifications.
Silica Sand Market Vendor Landscape
Concentration sits with diversified mining conglomerates and specialized regional processors rather than pure-play silica operators. The vendor base spans three tiers: integrated oilfield service providers with captive sand assets, European industrial minerals specialists with REACH-compliant processing infrastructure, and Asian trading houses with logistics control over Pacific Rim export flows. Competitive moves center on backward integration into mining rights and geographic expansion through toll processing partnerships.
Among North American specialists, U.S. Silica and Badger Mining Corporation exemplify the oilfield-proppant-to-industrial-specialty diversification archetype. Quarzwerke GmbH and its parent Sibelco occupy a position representing European regulatory compliance integration. TOCHU CORPORATION and Mitsubishi Corporation anchor the Asia-Pacific trading house model with logistics control over Australian and Southeast Asian export corridors.
| Leading Market Players |
|---|
| Badger Mining Corporation |
| Sil Industrial Minerals |
| U.S. Silica |
| Quarzwerke GmbH |
| Source Energy Services |
| Sibelco |
| Mitsubishi Corporation |
| TOCHU CORPORATION |
| Covia Holdings LLC |
| Others |
Supply Flow & Price Mechanics
Scale economies in acid-leaching and magnetic separation infrastructure compress viable supply to legacy processors with sunk capital, elevating price floors for high-purity grades while marginal deposits exit commercial viability under escalating compliance burdens. Western Wisconsin's round-grain dominance and Appalachian logistics integration reinforce geographic pricing premiums, as buyers absorb transport differentials to secure specification-compliant feedstock.
Pricing Analysis
REACH registration requirements dictate the pricing tier structure across European silica sand procurement, separating acid-leaching capable processors from commodity-grade suppliers. Three-tier pricing structure across premium, standard, and economy levels stratifies by iron content thresholds, with solar glass manufacturers in India and Southeast Asia absorbing sub-100 ppm premiums. Cost compression in standard grades is intensifying because energy-intensive wet processing faces natural gas price volatility, while foundry buyers exhibit highest price sensitivity due to binder substitution pressures.
Supply Chain Analysis
Just-in-time procurement dominates solar glass fabrication, while oilfield proppant buyers maintain strategic stockpiles at wellhead-adjacent transload terminals to weather logistics disruptions. Supply concentrates in the United States, Australia, and Germany, with raw material dependencies spanning diesel fuel for wet processing, sulfuric acid for leaching operations, and specialized magnetic separation media. Single-source vulnerability runs through Western Wisconsin's Barron and Chippewa County deposits for premium round-grain proppant. Distribution runs through rail-served transload terminals for oilfield applications and long-term offtake agreements with embedded price adjustment mechanisms for container glass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among photovoltaic glass manufacturers consolidating procurement around vertically integrated sand-to-glass suppliers with certified carbon footprints, fragmenting spot-market liquidity and elevating contract negotiation leverage for specification-compliant volumes.
For Market Incumbents: Secure acid-leaching and magnetic separation capacity expansions in Gujarat's special economic zones and Maharashtra's industrial corridors before BIS standards tighten procurement qualification windows. Cement long-term offtake agreements with solar glass fabricators embedding price adjustment mechanisms to defend margin position against energy cost volatility. Prioritize backward integration into Australian mining rights to lock in high-purity feedstock chemistry. For New Entrants and Emerging Players: Certification fast-track through REACH registration and ISO 14001 environmental management systems opens European foundry upgrade demand under Industrial Emissions Directive mandates. Target India's import-dependent glass capacity buildouts with toll-processing partnerships leveraging Australian Cape Flattery silica deposits. Lead with logistics-integrated delivery models reducing rail and transload costs to wellhead-proximate shale basins. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among acid-leaching capable processors with captive solar glass offtake agreements spanning multi-year horizons. Long-term viability across the analysis window favors assets with compliant water discharge permits under China's GB standards and closed-loop beneficiation infrastructure. Monitor semiconductor-grade specification thresholds below 50 ppm total impurities as inflection indicator for premium pricing tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Rights | Quarzwerke GmbH's Central European deposit control secures REACH-compliant feedstock chemistry for glass manufacturers. |
| Long-term Supply Agreement | U.S. Silica's Appalachian basin logistics network locks in Marcellus-Utica proppant demand with reduced rail costs. |
| Green Manufacturing Transition | EU Green Deal alignment rewards energy-efficient acid-leaching investments with carbon border adjustment preference. |
| Capacity Expansion | Badger Mining's western Wisconsin processing additions reinforce premium round-grain dominance for oilfield applications. |
| Joint Venture | TOCHU CORPORATION's Australian export corridor partnerships consolidate Pacific Rim high-purity silica trade flows. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade flow databases, SEC 10-K filings, and customs records, with input from plant managers at beneficiation facilities, procurement leads at container glass manufacturers, distribution channel partners, and technical R&D directors specializing in optical sorting systems. Bottom-up volume estimates from deposit-level capacity and utilization rates triangulate against top-down demand segmentation from end-use consumption patterns.
Segmentation dimensions modeled span grade tier (high purity, low iron, regular, coarse), end-use industry (container glass, specialty glass, oil and gas, foundry, construction), packaging format (bulk rail, bulk truck, bagged), and regional production hub. CAGRs derive from regression against industrial production indices and solar capacity installation forecasts, with oil and gas proppant intensity per well and photovoltaic glass iron tolerance thresholds as industry-specific forecast inputs across the projection horizon.
Underlying assumptions cover sustained solar panel fabrication expansion and REACH enforcement continuity, with deviation risk concentrated in foundry binder substitution rates and Chinese export permit renewal rejections under Ministry of Ecology and Environment water discharge standards. Revision becomes warranted when semiconductor-grade impurity thresholds cross below 50 ppm or when Appalachian shale rig counts deviate materially from baseline trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Silica Sand for Glass Making Market
Glass
Mexico Flat Glass Market
Glass
Dynamic Glazing Market
Glass
Ultra Violet Glass Bottles Market
Glass
Asia-Pacific Silica Sand Market
Glass
Laboratory Glass Container Market
Glass
Pharma Glass Tubing Market
Glass
Glass Lens Market
Glass
France Silica Sand Market
Glass
Global Flat Glass Market
Glass
Coated Glass Market
Glass
Recycled Glass Market
Glass
Pharmaceutical Glass Tubing Market
Glass
Flexible Glass Market
Glass
Soda Feldspar Market
Glass
Europe Glassware Market