
 Recycled Carbon Fiber Market | 2026-2036
Recycled Carbon Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Carbon Fiber Market Outlook
Buyer concentration in automotive OEMs is pivoting as tier-one suppliers fragment across European and Asian manufacturing clusters. Vartega Inc. leverages proprietary solvent recovery technology to sustain high-yield fiber reclamation from aerospace scrap streams. Toray Industries, Inc. anchors virgin-to-recycled product integration across its PAN-based portfolio, while SGL Carbon competes through specialized pyrolysis capacity serving BMW's Leipzig and Spartanburg assembly plants.
Recycled carbon fiber comprises reclaimed polyacrylonitrile-derived filaments processed through pyrolysis or solvolysis to retain minimum tensile strength of 80-90% relative to virgin grades, primarily serving weight-reduction mandates in transportation and energy sectors. Chopped fibers and mats dominate volume throughput due to lower sorting complexity and broader compatibility with compression molding lines. Aerospace components command premium positioning within application segments, whereas automotive parts scale fastest as OEMs qualify recycled content for non-structural panels and interior substrates.
The EU Green Deal and REACH compliance frameworks enforce traceable recycled content thresholds for composite waste streams entering European manufacturing chains. EPA industrial waste regulations in the United States shape landfill diversion economics, while Japan's METI circular economy roadmaps establish official recycled carbon fiber quality grades for domestic automotive qualification. Stakeholders must monitor evolving OEM material certification protocols and regional extended producer responsibility expansions to secure offtake agreements before capacity commitments crystallize.
Market Dynamics
Automotive OEM qualification protocols are compressing supplier lead times while pyrolysis capacity expansions lag aerospace scrap generation rates. The resulting feedstock-to-reclamation bottleneck is forcing tier-one suppliers to pre-commit volumes before fiber recovery yields are certified.
Growth Catalysts
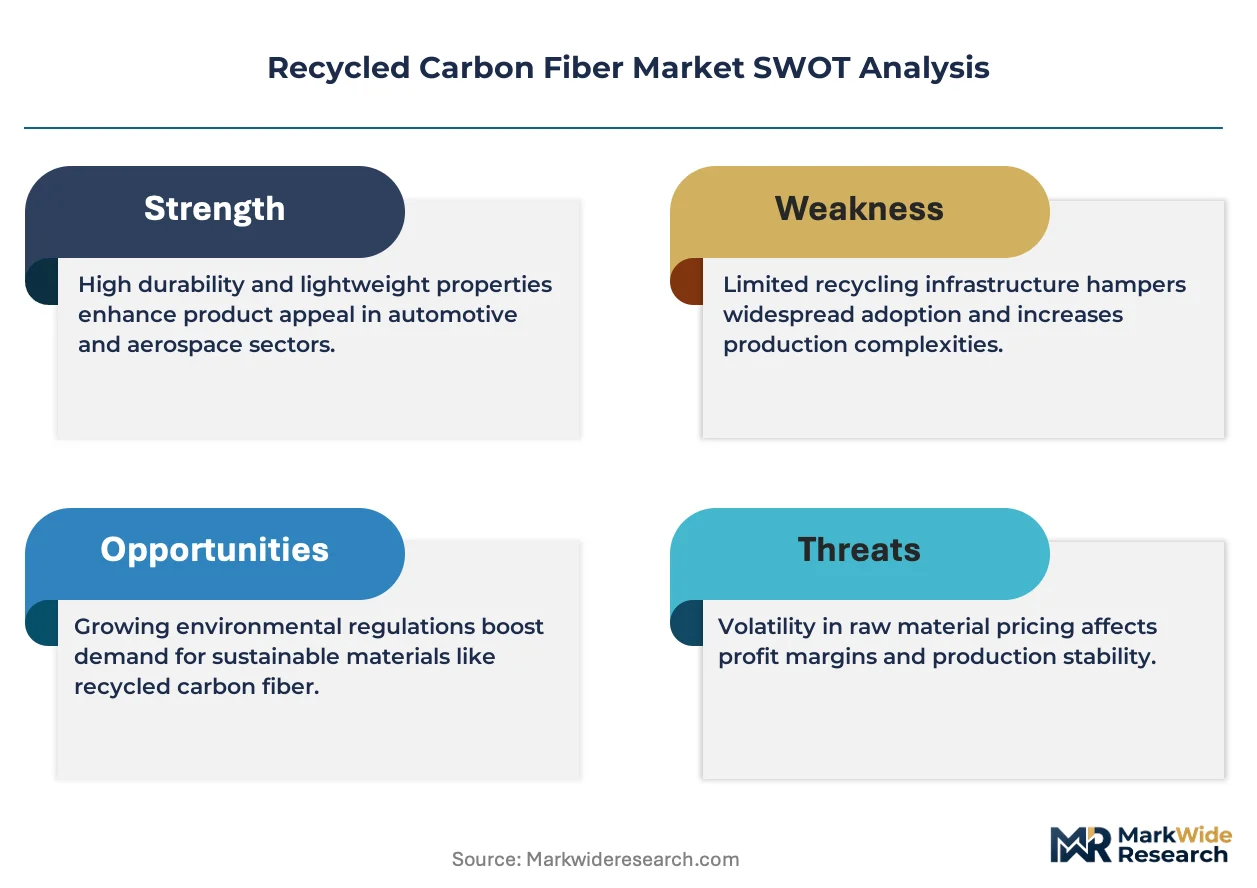
- EU Green Deal waste-reduction mandates:Closed-loop material recovery requirements are accelerating OEM procurement of secondary carbon fiber feedstocks for lightweight structural components.
- Chopped fiber mat compatibility:Lower sorting complexity and broader compression molding line integration are expanding addressable applications in transportation sectors.
- German supplier qualification programs:BMW and Volkswagen anchor certification frameworks that validate recycled content for non-structural panels and interior substrates.
Market Restraints
- Pyrolysis energy input costs:Natural gas price volatility directly impacts reclamation economics and facility operating margins.
- Aerospace scrap concentration:Boeing and Airbus manufacturing clusters in Washington State and Toulouse create geographic supply monopolies.
- Tensile strength degradation ceiling:Virgin fiber retains 10-20% performance advantage that limits structural load-bearing applications.
Strategic Opportunities
- Japan METI circular economy roadmaps:Official recycled carbon fiber quality grades create domestic automotive qualification pathways.
- Solvolysis technology convergence:Solvent recovery systems paired with automated fiber sorting enable higher-yield reclamation from contaminated waste streams.
- Wind energy blade end-of-life:Decommissioned turbine composites represent untapped feedstock volumes for mat production.
Industry Challenges
- OEM material certification timelines:BMW's Leipzig and Spartanburg qualification protocols demand 18-24 month validation cycles before volume commitments.
- REACH traceability documentation:Composite waste stream compliance requires chain-of-custody systems that small reclaimers cannot resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Carbon Fiber Market |
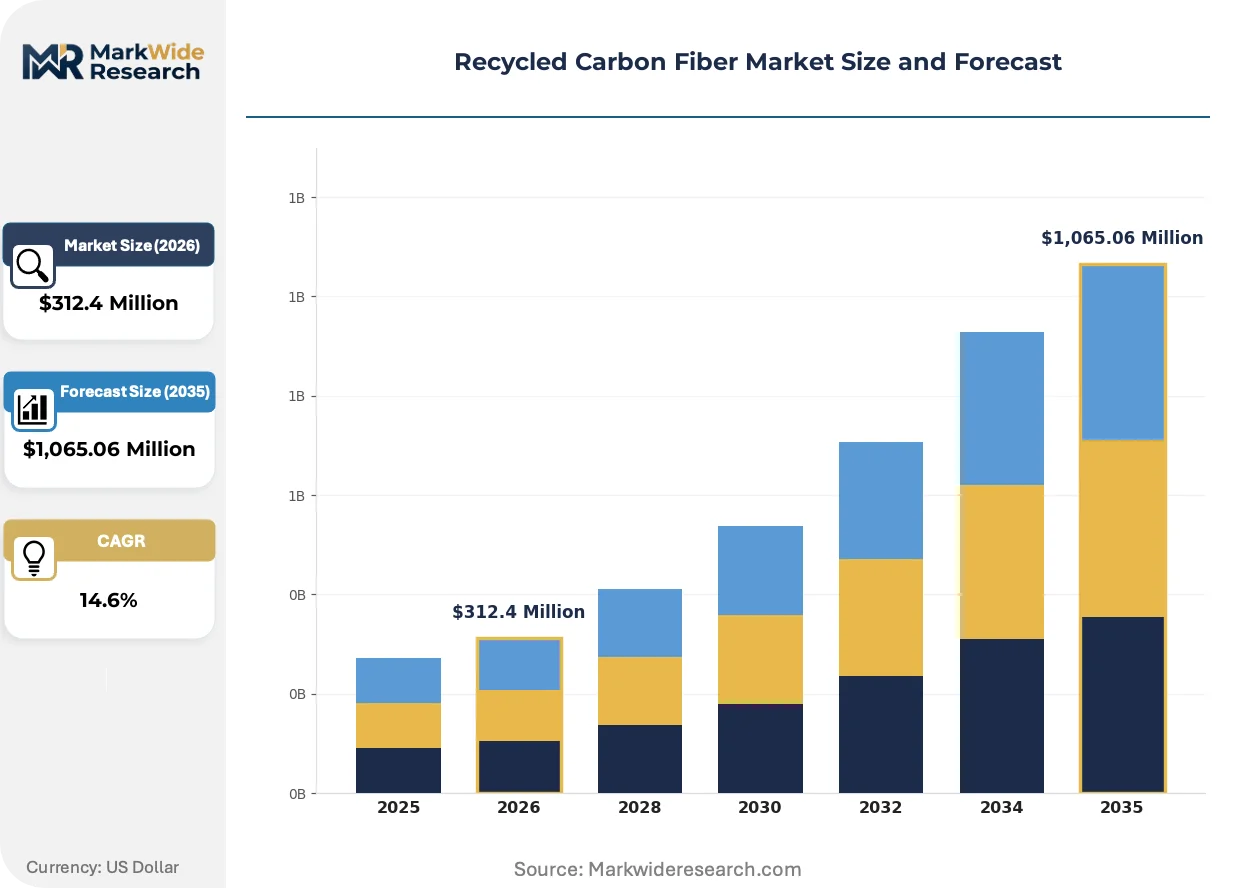
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,065.06 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Composites, Reinforced Plastics, Non-Woven Fabrics, Sheet Molding Compounds Application: Aerospace Components, Automotive Parts, Sporting Goods, Industrial Applications Form: Unidirectional Tapes, Prepregs, Chopped Fibers, Mats End User: Aerospace Manufacturers, Automotive OEMs, Construction Industry, Defense Sector |
| Companies Covered | Vartega Inc., Gen 2 Carbon Limited, Toray Industries, Inc., Carbon Fiber Remanufacturing, Carbon Conversions, Mitsubishi Chemical Group Corporation, SGL Carbon, Hera SpA, Procotex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Carbon Fiber Market Strategic Shifts
Reclamation technology maturation is compressing the performance gap between virgin and secondary fiber grades. Process automation and solvent recovery advances are reshaping facility economics.
Solvolysis-based fiber recovery is unifying previously separate pyrolysis and mechanical sorting process steps into continuous-flow reclamation lines. Automotive tier-one suppliers in Germany and Japan are piloting these integrated systems at demonstration scale. This unification is enabling real-time yield optimization that reduces energy intensity per kilogram of recovered fiber.
REACH compliance frameworks now mandate traceable recycled content thresholds for composite waste streams entering European manufacturing chains. Industrial consequence includes mandatory third-party verification of fiber origin and reclamation method. Aerospace component suppliers face the steepest documentation burdens, with many redirecting scrap volumes to automotive-qualified reclaimers.
Automotive OEMs now pre-qualify reclaimers before committing multi-year offtake agreements. Tier-one suppliers fragment across European and Asian manufacturing clusters as BMW, Volkswagen, and Japanese automakers establish parallel certification tracks. Germany anchors this behavioral shift, with Leipzig and Spartanburg assembly plants demanding validated secondary feedstock pipelines before model-year production ramps.
Recycled Carbon Fiber Market Segmentation
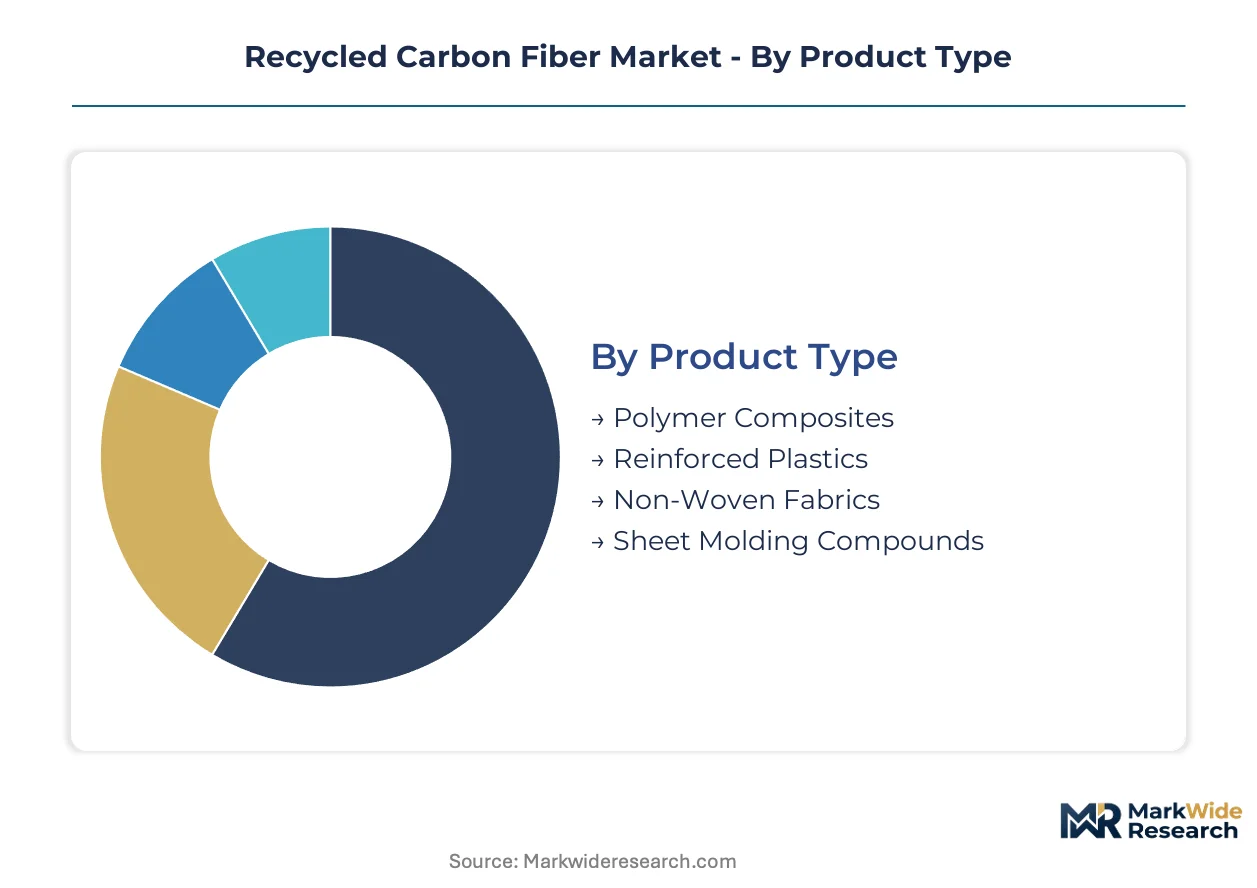
Recycled carbon fiber segmentation reflects divergent technical requirements across embedded composite systems versus standalone reinforcement applications. Product form and end-user specifications determine reclamation method selection, tensile strength thresholds, and qualification pathway complexity.
Product Type:
Standalone polymer matrices integrate reclaimed fiber as primary reinforcement, while embedded systems compound recycled content with virgin materials to preserve performance benchmarks.
- Polymer Composites:Thermoset and thermoplastic matrices incorporating 30-50% reclaimed carbon fiber by weight. Demand concentrates in automotive underbody shields and battery enclosures where BMW and Volkswagen validate secondary feedstock performance under EU Green Deal traceability mandates.
- Reinforced Plastics:Injection-moldable compounds blending chopped fiber with nylon or PEEK matrices. German tier-one suppliers are scaling compression molding lines for non-structural interior panels, driven by REACH compliance documentation requirements that favor pre-qualified reclaimers.
- Non-Woven Fabrics:Random fiber orientation mats serving acoustic and thermal insulation layers.
- Sheet Molding Compounds:Pre-impregnated formulations for high-volume automotive pressing operations.
Polymer composites lead volumes today; reinforced plastics are gaining share fastest.
Application:
Cost-tier segmentation separates premium qualification pathways from high-volume, lower-specification deployments.
- Aerospace Components:Prepregs and unidirectional tapes meeting FAA airworthiness standards for non-critical interior fittings. Toulouse and Washington State manufacturing clusters generate concentrated scrap feedstock, though qualification timelines extend 18-24 months.
- Automotive Parts:Chopped fiber mats and compression-molded panels for body-in-white applications. Japanese automakers under METI circular economy frameworks are accelerating domestic qualification of secondary feedstocks for model-year production ramps.
- Sporting Goods:Bicycle frames and recreational equipment utilizing lower-grade reclaimed fiber.
- Industrial Applications:Robotics arms and manufacturing fixtures where dimensional stability outweighs ultimate tensile strength.
Automotive parts dominate shipment volumes; aerospace components command steepest price premiums.
Form:
Volume throughput favors formats minimizing downstream processing steps and alignment complexity.
- Chopped Fibers:3-50mm length distributions compatible with bulk molding and injection processes. Leipzig and Spartanburg assembly plants specify chopped formats for interior substrate qualification, leveraging lower sorting energy versus continuous forms.
- Mats:Random and aligned fiber webs for lay-up manufacturing. Wind energy blade decommissioning in Northern Europe is emerging as feedstock source for mat production, though contamination rates challenge yield consistency.
- Unidirectional Tapes:Aligned fiber prepregs for structural reinforcement.
- Prepregs:Resin-impregnated sheets requiring cold storage and controlled shelf life.
Chopped fibers lead volumes today; mats are expanding most quickly.
End User:
Customer-type segmentation concentrates procurement authority among OEMs with captive certification frameworks.
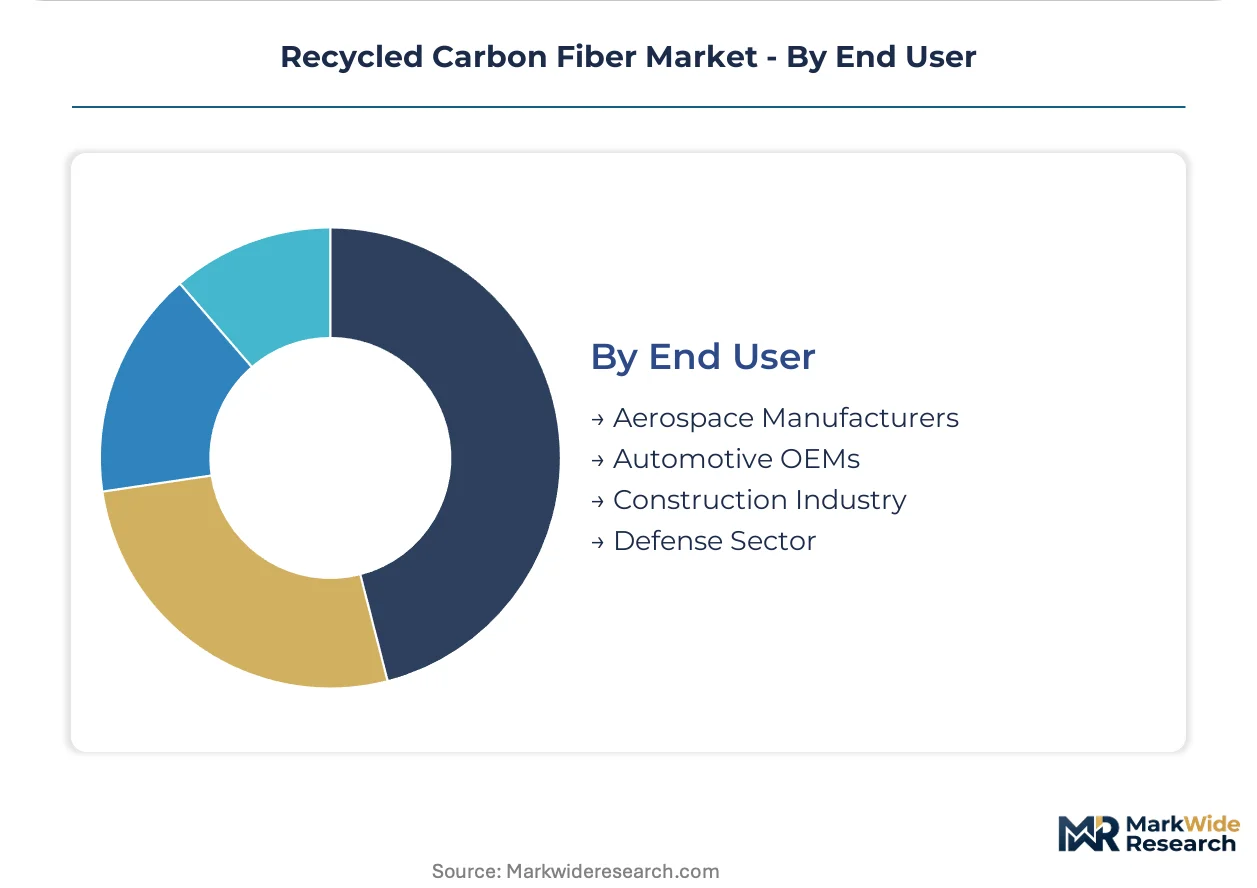
- Automotive OEMs:BMW, Volkswagen, and Japanese manufacturers operating parallel qualification tracks. Pre-commitment offtake agreements now precede capacity expansions, compressing supplier lead times while pyrolysis capacity lags scrap generation.
- Aerospace Manufacturers:Boeing and Airbus tier-one suppliers redirect scrap volumes to automotive-qualified reclaimers under REACH documentation burdens. Washington State and Toulouse clusters create geographic supply monopolies limiting reclaimer diversification.
- Construction Industry:Reinforced concrete and facade applications utilizing lower-grade fiber.
- Defense Sector:Armored vehicle and naval specifications with classified performance requirements.
Automotive OEMs anchor demand today; defense sector procurement is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the most advanced supplier qualification frameworks, while the United States concentrates aerospace scrap generation in geographically isolated manufacturing clusters. Japan's METI circular economy roadmaps create parallel domestic certification tracks. China and France round out the five-country analysis as emerging volume centers with divergent regulatory maturity.
Germany
Automotive OEM procurement of secondary carbon fiber feedstocks scales fastest here, driven by BMW and Volkswagen qualification programs. EU Green Deal waste-reduction mandates enforce closed-loop material recovery requirements across Leipzig and Spartanburg assembly plants. Bavaria and Lower Saxony anchor pyrolysis capacity expansions serving tier-one compression molding lines.
United States
EPA industrial waste regulations shape landfill diversion economics for composite scrap streams. Boeing manufacturing clusters in Washington State generate concentrated aerospace feedstock volumes that outpace domestic reclamation capacity. Vartega Inc. leverages proprietary solvent recovery technology from its Colorado base to capture high-yield fiber from these concentrated waste streams.
Japan
METI circular economy roadmaps establish official recycled carbon fiber quality grades for domestic automotive qualification. Toray Industries anchors virgin-to-recycled product integration across its PAN-based portfolio. Nagoya and Osaka manufacturing corridors pilot solvolysis-based continuous-flow reclamation systems at demonstration scale.
China
Dual carbon goals and MIIT industrial waste policies accelerate domestic pyrolysis capacity buildouts. Yangtze River Delta manufacturing clusters generate expanding composite scrap volumes from wind energy blade production. Shanghai and Jiangsu province reclaimers face yield consistency challenges from contaminated feedstock streams.
France
ECHA REACH compliance frameworks mandate traceable recycled content thresholds for composite waste entering European manufacturing chains. Toulouse aerospace manufacturing clusters create geographic supply concentration similar to Washington State. Auvergne-Rhône-Alpes and Île-de-France regions develop specialized pyrolysis capacity serving automotive-qualified reclaimers.
Recycled Carbon Fiber Market Competitive Environment
German producers anchor the premium-tier qualification vector; Japanese and American specialists hold complementary positions in solvent recovery and aerospace scrap processing. Market structure reflects moderate consolidation around integrated chemical conglomerates with captive carbon fiber operations, flanked by independent reclaimers with specialized pyrolysis or solvolysis capabilities. Three archetypes dominate: integrated chemical majors with virgin-to-recycled portfolios, independent technology specialists with proprietary recovery systems, and regional reclaimers serving single-industry feedstock streams. Capacity pre-commitments and multi-year offtake agreements represent the dominant competitive moves, compressing supplier lead times ahead of certified yield validation.
Within the technology specialist tier, Vartega Inc. and Carbon Conversions occupy positions defined by solvent-based recovery approaches. Toray Industries, Inc. exemplifies the integrated chemical major archetype through its PAN-based product integration. SGL Carbon sits within the regional reclaimer category with specialized pyrolysis capacity tied to German automotive OEM qualification frameworks. These three company types collectively represent the competitive structure without implying specific strategic actions or market share positions for any individual entity.
| Leading Market Players |
|---|
| Vartega Inc. |
| Gen 2 Carbon Limited |
| Toray Industries, Inc. |
| Carbon Fiber Remanufacturing |
| Carbon Conversions |
| Mitsubishi Chemical Group Corporation |
| SGL Carbon |
| Hera SpA |
| Procotex |
| Others |
Value Chain & Pricing Dynamics
Captive pyrolysis capacity in Germany anchors both supply security and pricing leverage for automotive-qualified reclaimers serving BMW and Volkswagen programs. This backward integration into fiber recovery insulates tier-one suppliers from natural gas volatility while compressing qualification timelines under EU Green Deal mandates.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade chopped fiber as Yangtze River Delta reclaimers scale batch pyrolysis operations. Three-tier pricing structure across aerospace-qualified, automotive-certified, and industrial-grade tiers reflects tensile strength retention thresholds and REACH documentation burdens. Cost compression in the industrial tier is intensifying because contaminated wind blade feedstock yields remain inconsistent. Tier-one automotive suppliers exhibit lowest price sensitivity due to pre-commitment offtake structures, while construction sector buyers drive spot-market volatility.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs mandate multi-supplier qualification across at least two of Germany, Japan, and the United States for volume eligibility. Aerospace scrap generation concentrates in Washington State and Toulouse, creating geographic monopolies that reclaimers must navigate through long-haul logistics or regional partnership structures. Feedstock supply draws from Boeing and Airbus manufacturing clusters, decommissioned wind energy blades in Northern Europe, and automotive production trim waste. Single-source vulnerability persists in solvent recovery technology licensing. Distribution runs through tier-one compounders who blend reclaimed fiber with virgin PAN-based material before OEM delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal waste-reduction mandates and REACH traceability frameworks create irreversible demand pull for closed-loop carbon fiber recovery.
For Market Incumbents: Cement qualification pipeline advantages by locking 18-24 month BMW and Volkswagen certification cycles ahead of competitor entries. Expand captive pyrolysis capacity in Bavaria and Lower Saxony to defend against solvolysis technology disruptors. Prioritize REACH chain-of-custody system investments that smaller reclaimers cannot resource. For New Entrants and Emerging Players: Enter via wind energy blade decommissioning feedstock streams in Northern Europe, where contamination-sorting challenges have stalled incumbent yield optimization. Target industrial-grade mat production for construction and robotics applications as the most penetrable tier. Pursue joint qualification pathways with Japanese automakers under METI circular economy frameworks as a go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional reclaimers with specialized pyrolysis capacity because automotive OEM pre-commitment structures generate predictable offtake visibility. Five-to-ten year viability hinges on securing tier-one supplier status before capacity commitments crystallize. Acquisition target archetype: German or Japanese reclaimers with validated secondary feedstock pipelines. Watch for solvolysis yield certification at demonstration scale as an inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis Capacity | Captive recovery operations insulate BMW and Volkswagen suppliers from natural gas price volatility. |
| Long-term Supply Agreement | Pre-commitment offtake structures compress supplier lead times ahead of certified yield validation. |
| Joint Venture | Solvolysis technology partnerships pair aerospace scrap access with automated fiber sorting capabilities. |
| Green Manufacturing Transition | EU Green Deal compliance creates qualification pathways for closed-loop material recovery systems. |
| Geographic Expansion | Japanese METI circular economy roadmaps establish parallel domestic automotive certification tracks. |
Study Parameters
Direct dialogue with tier-one automotive procurement managers, aerospace composite engineers, pyrolysis plant operators, and REACH compliance officers grounded qualitative findings. Secondary validation drew from ECHA regulatory filings, EU Green Deal implementation documents, METI circular economy roadmaps, and customs trade data for carbon fiber scrap movements. Bottom-up fiber recovery capacity estimates triangulated against top-down OEM demand projections across the analysis window.
Segmented outputs by product form, application tier, and end-user qualification status structured the projection framework. Modeled variables included pyrolysis energy input costs, tensile strength retention rates, and regional regulatory enforcement intensity throughout the forecast period. CAGRs derived from supply-demand balance analysis incorporating aerospace scrap generation rates and automotive qualification timeline compression.
Inputs from regulatory agency guidance documents and OEM supplier portal disclosures were available through the study window; gaps in real-time scrap volume reporting from Boeing and Airbus manufacturing clusters introduce uncertainty bands around feedstock availability assumptions. Deviation in EU Green Deal enforcement timelines or METI grade standard adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Recycled PET Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
North America BPA Free Plastic Market
Recycled Plastics
Industrial Plastic Market
Recycled Plastics
Germany Plastics Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market
Recycled Plastics
Global Recycled Plastics Market
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
India Plastic Market