
 Oman Pyrolysis Gasoline Market | 2026-2036
Oman Pyrolysis Gasoline Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Pyrolysis Gasoline Market Intelligence
Refinery-to-petrochemical integration channels are reshaping how pyrolysis gasoline moves through Oman's value chain. Oman Oil Company S.A.O.C anchors domestic supply through its Sohar refinery complex and downstream partnerships. Saudi Aramco competes via cross-border feedstock agreements that leverage proximity to Oman's industrial zones. TotalEnergies SE positions its regional trading operations to capture arbitrage flows between Gulf Cooperation Council producers.
Pyrolysis gasoline consists of C5–C12 aromatic-rich hydrocarbons produced as a byproduct of steam cracking operations, with benzene content typically ranging from 30% to 65% by volume depending on feedstock severity and cracking conditions. This stream serves primarily as a feedstock for benzene, toluene, and xylene extraction, or as a high-octane gasoline blending component after hydrotreatment. Light naphtha fractions dominate current processing volumes due to favorable yields from ethane-based crackers prevalent in the Gulf region. Petrochemical feedstock applications are expanding fastest as Oman pushes beyond fuel exports toward chemicals manufacturing. Heavy naphtha segments retain margin strength through aromatics extraction economics tied to Asian derivative demand.
Oman's Ministry of Energy and Minerals sets downstream investment frameworks that direct pyrolysis gasoline into domestic chemical synthesis value chains rather than direct fuel export. The Central Bank of Oman and Sultan Qaboos University research partnerships influence technical standards for feedstock quality and environmental compliance in industrial zones. Stakeholders must monitor how Duqm Special Economic Zone regulatory incentives restructure procurement patterns between existing Sohar infrastructure and greenfield petrochemical complexes.
Market Dynamics
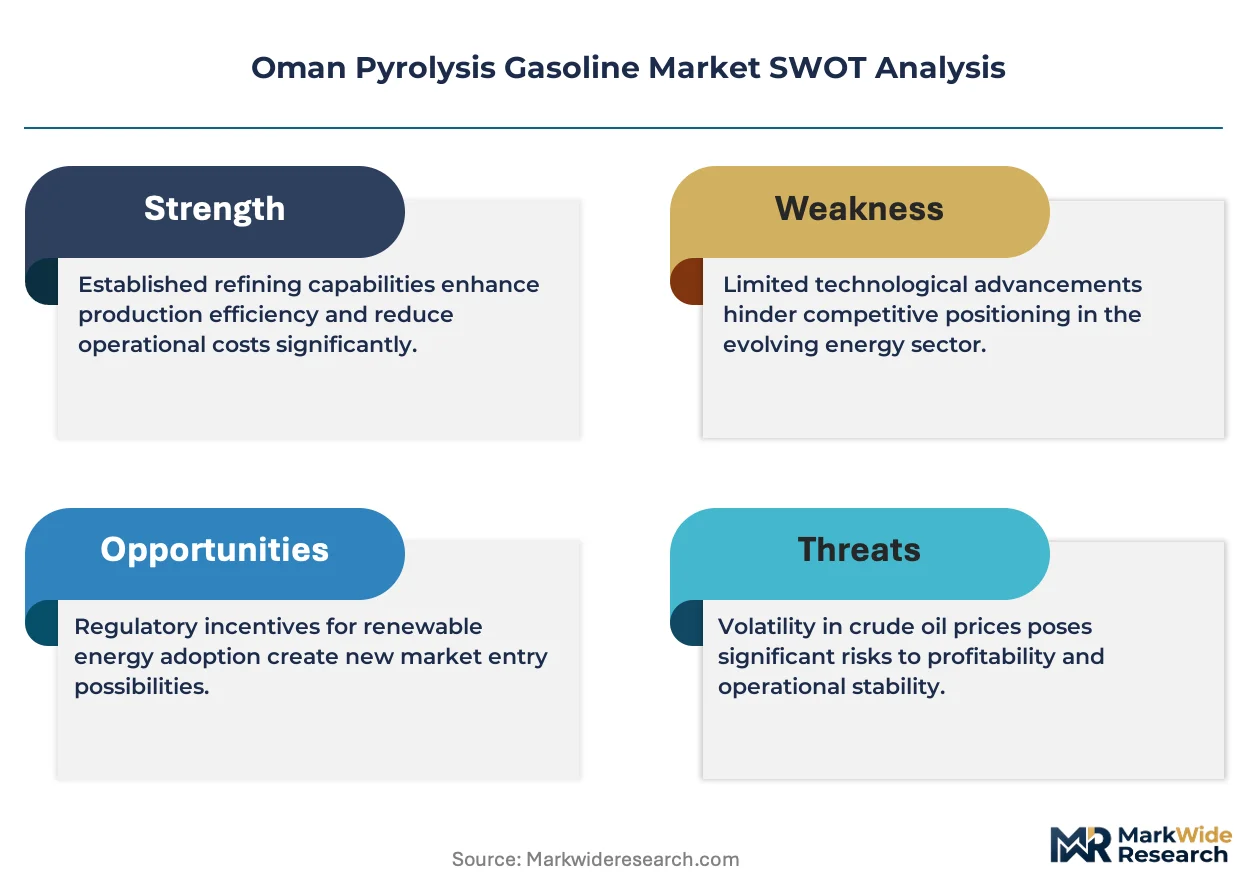
Duqm Special Economic Zone regulatory incentives are restructuring procurement patterns between existing Sohar infrastructure and greenfield petrochemical complexes, forcing midstream operators to rebalance feedstock allocation across Oman's two industrial poles.
Growth Catalysts
- Downstream diversification mandates:Oman's Ministry of Energy and Minerals directs pyrolysis gasoline into domestic chemical synthesis value chains rather than direct fuel export, anchoring local demand.
- Steam cracking technology upgrades:Ethane-based crackers prevalent in the Gulf region yield favorable light naphtha fractions, improving aromatics extraction economics for regional processors.
- Plastics sector feedstock demand:Petrochemical applications from Oman's expanding polyethylene and polypropylene capacity absorb growing pyrolysis gasoline volumes.
Market Restraints
- Feedstock concentration risk:Light naphtha supply ties to ethane availability from gas processing facilities concentrated in Al Wusta Governorate, creating geographic single-point vulnerability.
- Benzene content variability:Cracking severity fluctuations produce 30% to 65% benzene range instability, complicating consistent aromatics extraction yields.
- Asian derivative pricing exposure:Heavy naphtha margin strength depends on benzene-toluene-xylene demand cycles in Chinese and Korean downstream markets.
Strategic Opportunities
- Duqm greenfield complex integration:New refinery-petrochemical units at the Special Economic Zone offer first-mover positioning for captive pyrolysis gasoline offtake arrangements.
- Hydrotreatment capacity expansion:High-octane gasoline blending applications grow as Oman reduces fuel import dependency through domestic refining upgrades.
- Sultan Qaboos University research partnerships:Technical standards development for feedstock quality creates intellectual property positioning in environmental compliance systems.
Industry Challenges
- Specialized process engineering scarcity:Steam cracker optimization and aromatics extraction expertise remains concentrated among international contractors, constraining local workforce development.
- Cross-governorate logistics coordination:Feedstock movement between Sohar and Duqm requires integrated pipeline and marine terminal investments with multi-year commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Pyrolysis Gasoline Market |
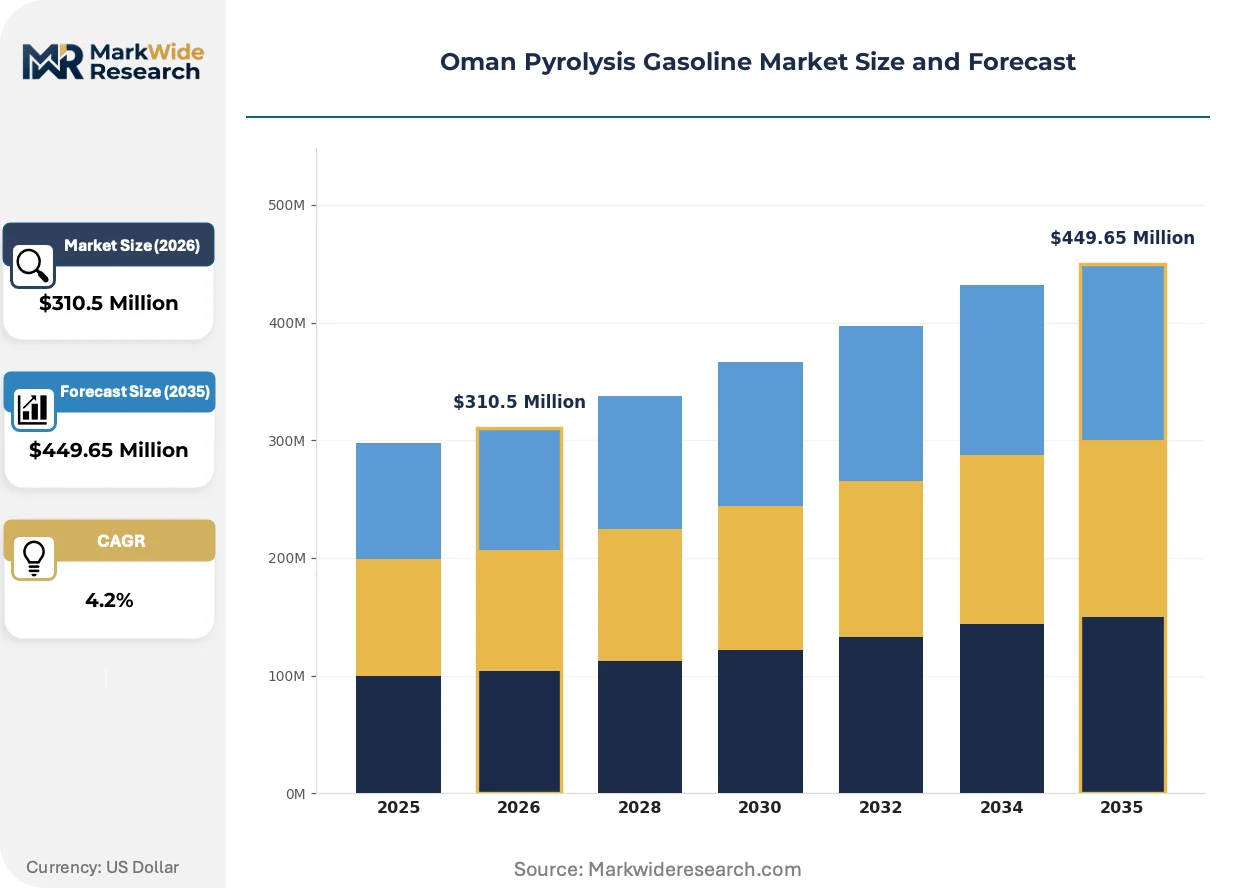
| Market Size in 2026 | $310.5 Million |
| Market Size in 2035 | $449.65 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Naphtha, Heavy Naphtha, Petrochemical Feedstock, Others End Use Industry: Plastics, Synthetic Fibers, Chemicals, Pharmaceuticals Processing Technology: Steam Cracking, Catalytic Cracking, Hydrocracking, Flash Cracking Application: Fuel Additive, Solvent, Intermediate, Chemical Synthesis |
| Companies Covered | Exxon Mobil Corporation, TotalEnergies SE, Oman Oil Company S.A.O.C, Abu Dhabi National Oil Company, Saudi Aramco, BP p.l.c., Kuwait Petroleum Corporation, Qatar Petroleum, Royal Dutch Shell plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Pyrolysis Gasoline Market Strategic Shifts & Innovations
Digital instrumentation and real-time analytics are penetrating pyrolysis gasoline processing, compressing reaction optimization cycles and enabling predictive maintenance across Oman's integrated refinery complexes.
Advanced process control systems is digitizing furnace operation parameters and product yield prediction at Sohar refinery units, allowing operators to adjust cracking severity within minutes rather than hours. Central Bank of Oman-backed industrial digitization grants accelerate adoption among mid-scale processors. The structural consequence compresses quality variability penalties and reduces off-specification volume write-offs.
Oman's Ministry of Energy and Minerals downstream investment frameworks now mandate environmental compliance monitoring for all new petrochemical feedstock installations. This industrial consequence forces existing Sohar operators to retrofit emissions tracking infrastructure ahead of greenfield Duqm complex commissioning. Heavy naphtha processing segments face accelerated capital deployment timelines to meet air quality benchmarks.
Integrated refinery-petrochemical procurement contracts are displacing spot-market feedstock purchases among Oman's largest polyethylene producers. Long-term offtake agreements with fixed aromatics extraction yields now dominate volume allocation between Sohar crackers and derivative manufacturers. This pattern concentrates most visibly in Al Wusta Governorate, where Duqm complex anchor tenants negotiate decade-long supply security arrangements.
Oman Pyrolysis Gasoline Market Segmentation
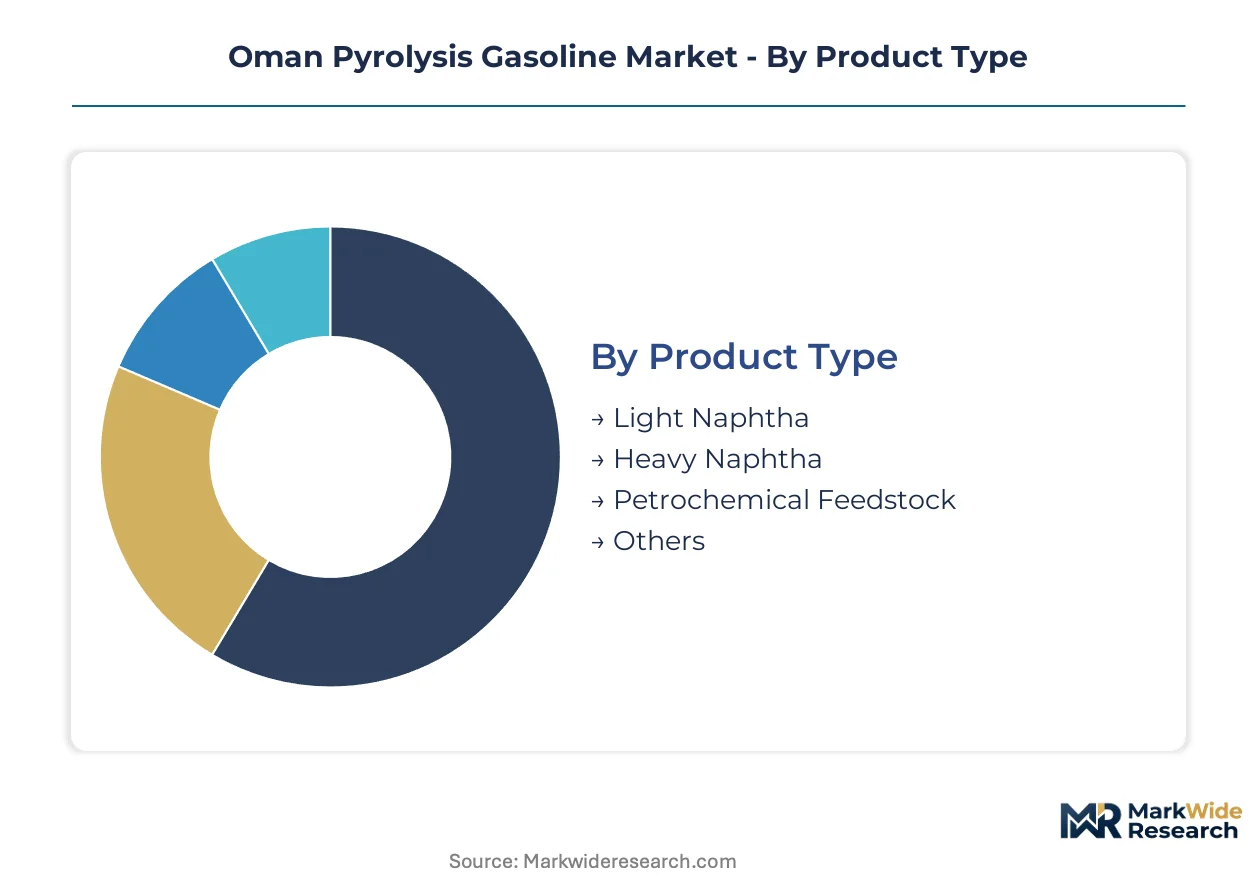
Pyrolysis gasoline segmentation in Oman reveals how feedstock quality, processing intensity, and end-use specifications fragment procurement patterns across the Sultanate's dual industrial poles. Each dimension carries distinct regulatory, logistical, and margin implications for operators navigating between Sohar's mature infrastructure and Duqm's greenfield complexes.
Product Type:
Light naphtha fractions dominate ethane-fed crackers across Al Wusta Governorate, while heavy naphtha concentrates aromatics extraction value for Asian export markets.
- Light Naphtha:C5–C6 paraffinic-rich streams from high-severity ethane cracking yield 40–50% benzene precursors with minimal sulfur contamination. Sohar refinery complexes and Duqm anchor tenants consume these volumes for polyethylene feedstock, though ethane supply concentration in central Oman creates geographic vulnerability to gas processing disruptions.
- Heavy Naphtha:C7–C12 aromatic-dense cuts command extraction premiums tied to Chinese benzene-toluene-xylene demand cycles. Duqm Special Economic Zone processors target these streams for captive aromatics units, leveraging marine terminal access to Korean and Japanese derivative markets.
- Petrochemical Feedstock:Specification-grade pyrolysis gasoline diverted from fuel blending into polymer precursor chains.
- Others:Specialty solvent cuts and non-standard fractions serving niche industrial applications.
The dominant share belongs to Light Naphtha, while Heavy Naphtha is closing the gap fastest.
End Use Industry:
Downstream diversification mandates from Oman's Ministry of Energy and Minerals are redirecting pyrolysis gasoline from fuel export toward chemical synthesis value chains.
- Plastics:Polyethylene and polypropylene manufacturers at Sohar and Duqm absorb the largest pyrolysis gasoline volumes as polymer-grade feedstock. Light naphtha fractions supply linear low-density polyethylene units, with Duqm greenfield complexes negotiating decade-long offtake security.
- Chemicals:Benzene extraction for styrene and phenol production concentrates in Al Wusta Governorate, where integrated refinery-petrochemical units achieve economies of scale impossible at standalone aromatics facilities.
- Synthetic Fibers:Purified terephthalic acid and polyester precursor demand pulls heavy naphtha toward fiber-grade paraxylene production.
- Pharmaceuticals:High-purity solvent applications for active pharmaceutical ingredient synthesis require hydrotreated pyrolysis gasoline meeting Gulf Standard Organization specifications.
Plastics retains the volume leadership position, though Chemicals is expanding most quickly as Duqm complex commissioning accelerates.
Processing Technology:
Technology selection determines benzene yield stability, energy intensity, and capital recovery timelines across Oman's steam cracking fleet.
- Steam Cracking:Thermal pyrolysis at 800–900°C remains the dominant production pathway, yielding 30–65% benzene depending on feedstock severity. Sohar refinery units deploy advanced process control systems to compress reaction optimization cycles and reduce off-specification penalties.
- Catalytic Cracking:Fluid catalytic cracking units at integrated refineries produce lower-olefin pyrolysis gasoline suitable for gasoline blending rather than aromatics extraction.
- Hydrocracking:Hydrogen-intensive upgrading of heavy feeds yields naphthenic streams with constrained aromatics potential.
- Flash Cracking:Emerging high-temperature short-residence time processes targeting maximum ethylene yields with reduced pyrolysis gasoline co-production.
Steam Cracking commands installed capacity, while Catalytic Cracking is gaining operational share through refinery-petrochemical integration projects.
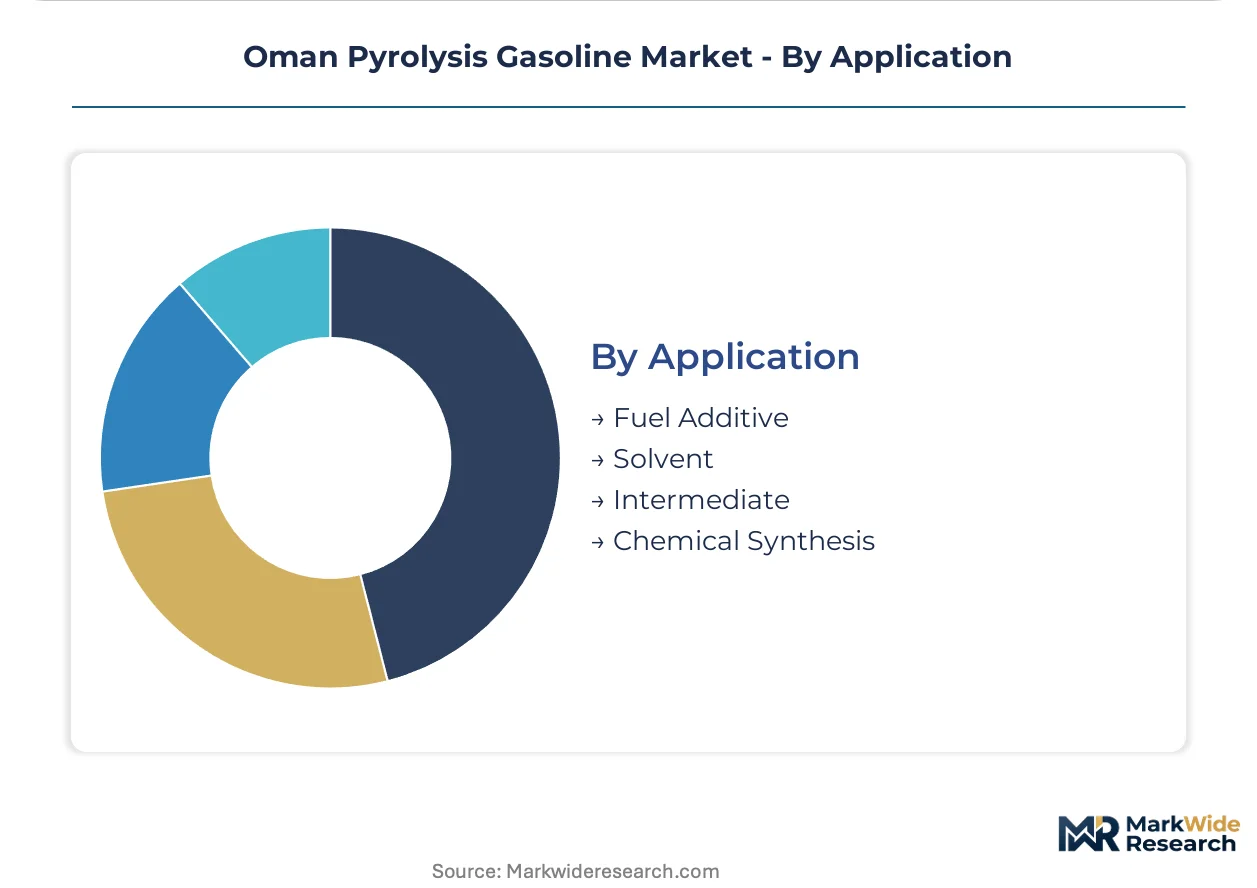
Application:
Application routing reflects tension between domestic fuel security priorities and export-oriented chemical manufacturing strategies.
- Chemical Synthesis:Benzene, toluene, and xylene extraction for downstream derivative production anchors value capture in Oman's petrochemical expansion. Heavy naphtha fractions from Duqm crackers feed dedicated aromatics complexes with direct marine export logistics.
- Fuel Additive:Hydrotreated pyrolysis gasoline blending into high-octane gasoline pools serves Oman’s strategic objective of reducing refined product import dependency. Central Bank of Oman-backed refinery upgrades expand hydrotreatment capacity for this pathway.
- Intermediate:Partially processed streams traded between Sohar and Duqm complexes before final specification.
- Solvent:Technical-grade applications in coatings, adhesives, and industrial cleaning formulations.
Chemical Synthesis holds the priority position in national industrial planning, while Fuel Additive is climbing fastest as hydrotreatment capacity comes online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry between Gulf Cooperation Council producers and Asian derivative markets dictates pyrolysis gasoline arbitrage flows through Oman's marine terminals. Heavy naphtha margins in Korean and Chinese benzene-toluene-xylene markets consistently outpace regional fuel blending economics. This divergence steers Omani output toward chemical synthesis corridors rather than domestic gasoline pools.
Al Batinah North Governorate
Industrial concentration around Sohar Port absorbs light naphtha fractions for polyethylene feedstock. Ministry of Energy and Minerals downstream frameworks mandate domestic chemical synthesis prioritization over fuel export. Sohar refinery complexes anchor aromatics extraction capacity serving regional polymer manufacturers.
Al Wusta Governorate
Duqm Special Economic Zone greenfield complexes concentrate ethane-fed steam cracking infrastructure. Central Bank of Oman-backed industrial digitization grants accelerate advanced process control adoption among anchor tenants. Duqm Refinery marine terminals enable direct benzene-toluene-xylene export to Korean and Japanese derivative markets.
Dhofar Governorate
Salalah Free Zone petrochemical investments diversify feedstock sourcing beyond Sohar-Duqm corridor concentration. Sultan Qaboos University research partnerships influence technical standards for environmental compliance monitoring. Salalah Port liquid bulk terminals expand pyrolysis gasoline transshipment capacity for East African chemical markets.
Muscat Governorate
Capital region regulatory oversight shapes national feedstock quality specifications and industrial zone permitting. Ministry of Energy and Minerals headquarters directs downstream investment frameworks toward chemical synthesis value chains. Muscat-based trading operations coordinate arbitrage flows between Gulf Cooperation Council producers and Asian offtakers.
Ad Dakhiliyah Governorate
Mid-country logistics corridors link gas processing facilities to coastal industrial zones. Pipeline infrastructure investments reduce feedstock movement costs between Al Wusta production centers and Sohar processing complexes. Regional workforce development initiatives address specialized process engineering scarcity constraining steam cracker optimization.
Oman Pyrolysis Gasoline Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in feedstock supply and aromatics extraction technology. The Oman pyrolysis gasoline market exhibits concentrated structure around national oil company anchors and integrated refinery-petrochemical complexes. Three archetypes dominate: state-backed vertical integrators controlling cracker-to-derivative value chains; international trading houses capturing inter-regional arbitrage; and technology licensors positioning advanced process control systems. Competitive intensity centers on long-term offtake security negotiations and greenfield complex integration timing.
Within the state-integrated tier, Oman Oil Company S.A.O.C anchors domestic supply through Sohar refinery infrastructure and Duqm Special Economic Zone partnerships. TotalEnergies SE occupies a position among international trading specialists leveraging regional arbitrage between Gulf Cooperation Council production and Asian derivative demand. Saudi Aramco represents cross-border feedstock competitors securing volume allocation through proximity-based supply agreements with Omani industrial zones.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| TotalEnergies SE |
| Oman Oil Company S.A.O.C |
| Abu Dhabi National Oil Company |
| Saudi Aramco |
| BP p.l.c. |
| Kuwait Petroleum Corporation |
| Qatar Petroleum |
| Royal Dutch Shell plc |
| Others |
Cost & Logistics Intelligence
Al Wusta Governorate's ethane-fed cracker concentration concentrates feedstock bargaining power among Duqm Special Economic Zone anchor tenants, translating upstream capacity control into downstream pricing leverage over Sohar-based processors competing for light naphtha volumes.
Pricing Analysis
Configured-to-order pricing for specification-grade petrochemical feedstock commands a 15-20% premium over standard fuel-blending pyrolysis gasoline. Contract-based long-term offtake agreements dominate volume allocation, with price differentiation driven by aromatics extraction yield guarantees and Duqm marine terminal access for Asian export. Cost compression in fuel-additive tiers is intensifying because Central Bank of Oman-backed hydrotreatment capacity expansions are reducing import dependency. Polyethylene manufacturers exhibit the highest price sensitivity due to thin polymer margins, while aromatics extractors for Korean and Japanese markets absorb premium feedstock costs.
Supply Chain Analysis
Tariff exposure between Gulf Cooperation Council producers and Chinese derivative markets dominates supply chain risk calculus for Omani exporters. Geographic supply concentration centers on Oman, Saudi Arabia, and Qatar for ethane-based feedstock, with raw material dependencies on natural gas processing output, catalyst supplies from German and Japanese licensors, and specialized aromatics extraction equipment. Single-source vulnerability exists for advanced process control systems concentrated among international engineering contractors. Distribution runs through integrated pipeline networks linking Al Wusta production to Sohar processing, with marine terminals at Duqm and Sohar Port handling export volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman pyrolysis gasoline represents an early-cycle expansion story as downstream diversification mandates from the Ministry of Energy and Minerals accelerate domestic chemical synthesis capacity buildout ahead of regional feedstock demand maturation.
For Market Incumbents: Build captive supply moats through decade-long offtake agreements with Duqm greenfield complex anchor tenants. Incumbents should secure exclusive pipeline access rights between Al Wusta gas processing and coastal crackers before logistics corridor saturation. Flash cracking technology adoption by international competitors threatens light naphtha yield economics, making advanced process control R&D investment essential for yield stability defense. For New Entrants and Emerging Players: Mid-scale hydrotreatment operators serving Oman's fuel-blending security objectives represent the most penetrable entry point for regional traders without cracker infrastructure. New entrants should target Salalah Free Zone petrochemical investments diversifying beyond Sohar-Duqm corridor concentration. A go-to-market angle through Sultan Qaboos University research partnerships for environmental compliance technology licensing offers lower capital barriers than greenfield cracking capacity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated refinery-petrochemical operators with fixed aromatics extraction yield contracts spanning the analysis window. Long-term viability over a 5-10 year horizon favors acquisition targets with Duqm Special Economic Zone regulatory incentives locked in ahead of complex commissioning. The signal to watch is Central Bank of Oman industrial digitization grant allocation velocity as an indicator of midstream infrastructure modernization commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethane Supply | Oman Oil Company S.A.O.C control over Al Wusta gas processing reduces feedstock cost volatility for crackers. |
| Long-term Supply Agreement with Asian Aromatics Extractors | Duqm marine terminal access enables direct benzene-toluene-xylene export to Korean derivative manufacturers. |
| Advanced Process Control System Deployment | Central Bank of Oman-backed digitization grants compress reaction optimization cycles at Sohar refinery units. |
| Green Manufacturing Transition | Ministry of Energy and Minerals environmental compliance mandates force emissions tracking infrastructure retrofit ahead of Duqm commissioning. |
| Joint Venture with International Trading House | TotalEnergies SE regional arbitrage expertise captures margin between Gulf Cooperation Council production and Asian demand cycles. |
Research Approach
Desk research of customs trade data, SEC 10-K filings from petrochemical majors, and Sultanate of Oman regulatory gazettes preceded structured interviews with steam cracker plant managers, procurement leads at polyethylene manufacturers, Duqm Special Economic Zone development officers, and aromatics extraction technology licensors. Primary fieldwork across Al Batinah North and Al Wusta Governorates validated secondary estimates of capacity utilization and feedstock flow patterns. Bottom-up volume builds from individual cracker units were triangulated against top-down petrochemical demand projections.
Assumptions held fixed include Ministry of Energy and Minerals downstream diversification policy continuity and Gulf Cooperation Council ethane supply pricing mechanisms, while variables tested included Duqm complex commissioning timelines and Chinese benzene-toluene-xylene demand cyclicality. The analytical framework modeled product type, end-use industry, processing technology, and application dimensions across the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by aromatics extraction economics and fuel-blending substitution elasticity.
Practitioners should monitor Duqm Special Economic Zone anchor tenant contract finalizations and Asian derivative market inventory cycles for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Pentaerythritol Market
Petrochemicals
Global Polypropylene Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market
Petrochemicals
Olefin Derivatives Market
Petrochemicals
Alkylate Market
Petrochemicals
Malaysia Chemical and Petrochemical Market
Petrochemicals
Chemical and Petroleum Containers Market
Petrochemicals
Synthetic and Biobased Butadiene Market
Petrochemicals
Bio Butadiene Market
Petrochemicals
Propylene Carbonate Market
Petrochemicals
Light Olefins Market
Petrochemicals
Propylene Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Tert Butyl Hydroperoxide Market
Petrochemicals
Fossil Fuel-Based Plastics Market
Petrochemicals
Petrochemicals Market