
 Plastic Waste Management Market | 2026-2036
Plastic Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Waste Management Market Analysis
India's waste-to-energy corridor is reconfiguring investment flows across South Asia. Veolia Environment leverages its European mechanical recycling expertise to compete for contracts in emerging Asian megacities. Waste Management Inc. anchors North American landfill-gas capture operations while extending into chemical recycling partnerships. Republic Services Inc. differentiates through integrated residential collection networks that sustain pricing power across Sun Belt states.
Plastic waste management encompasses the systematic collection, sorting, processing, and disposal or recovery of discarded polymer materials, typically operating through mechanical shredding at 200-400 RPM followed by extrusion and pelletization for reintroduction into manufacturing streams. Its primary purpose is to reduce environmental leakage of persistent synthetic polymers while recovering embedded energy and material value. The process dimension shows recycling outpacing landfill as regulatory bans on single-use plastics expand across OECD jurisdictions. Chemical recycling within the technology dimension is attracting capital as it handles contaminated and mixed polymer streams that mechanical systems cannot process. Household waste dominates the category dimension in volume terms, though industrial waste generates higher per-tonne margins due to cleaner feedstock streams and established reverse logistics.
The EPA enforces landfill methane standards under Subtitle D of RCRA, while the EU Green Deal's Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds for contact-sensitive applications. India's Central Pollution Control Board implements Extended Producer Responsibility frameworks that obligate brand owners to finance collection infrastructure for post-consumer plastics. Stakeholders must monitor how chemical recycling cost curves intersect with mechanical recycling margins as feedstock quality deteriorates and policy incentives shift toward circularity verification.
Market Dynamics
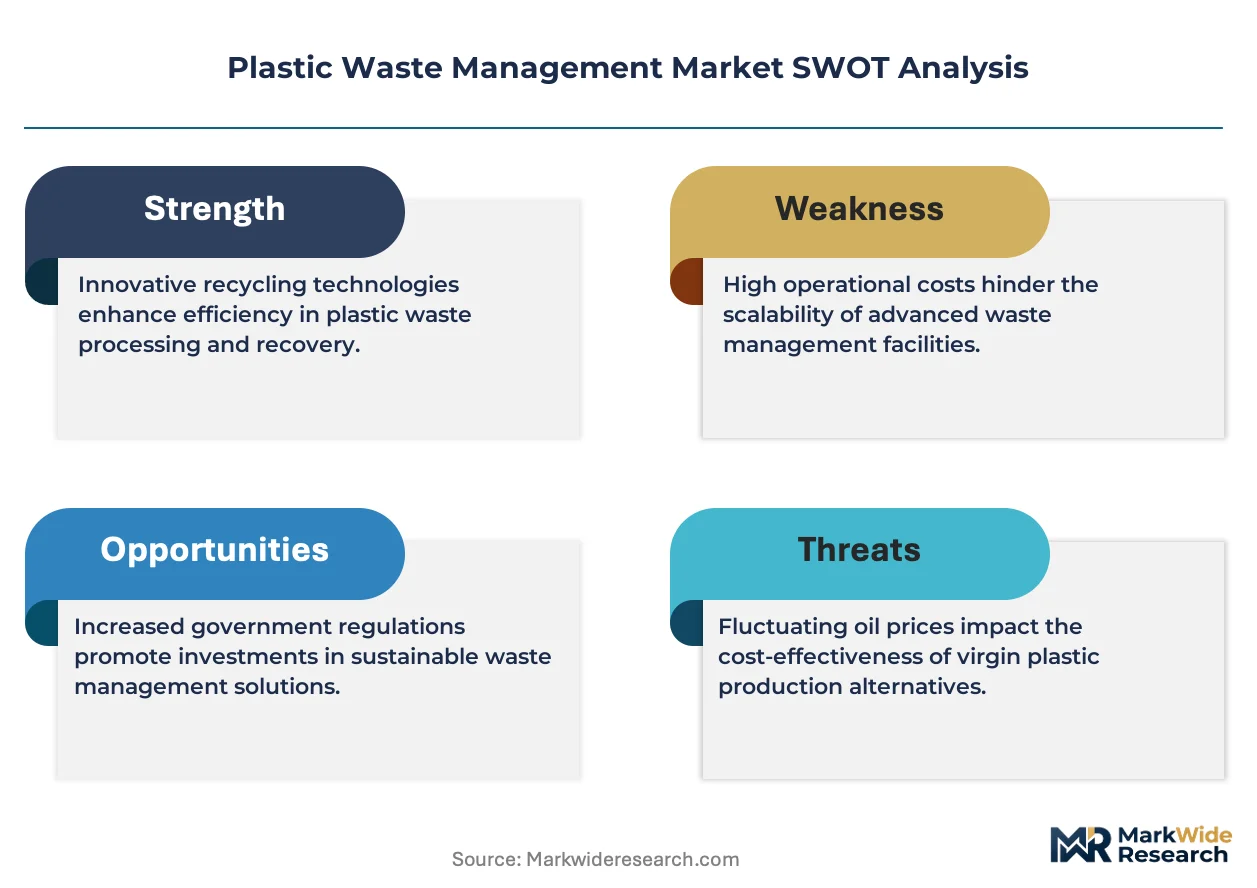
Chemical recycling capacity expansion is compressing mechanical recycling margins as feedstock quality deteriorates and polymer contamination thresholds tighten across OECD jurisdictions. The technology shift forces incumbents to reconfigure asset portfolios while municipal collection contracts fragment across competing processing standards.
Growth Catalysts
- EU Green Deal Packaging and Packaging Waste Regulation:Mandates minimum recycled content thresholds for contact-sensitive applications, forcing brand owners to secure long-term offtake agreements with advanced recyclers.
- India's Swachh Bharat Mission 2.0:Urban local bodies are modernizing solid waste handling infrastructure, creating concentrated demand corridors for integrated collection-to-pelletization systems.
- Pyrolysis oil upgrading:Refinery offtake contracts for chemically recycled feedstocks are displacing virgin naphtha in select European petrochemical clusters.
Market Restraints
- Natural gas price volatility:Pyrolysis and gasification operations face margin compression when feedstock energy costs spike above contract-indexed thresholds.
- Collection infrastructure fragmentation:Southeast Asian municipal authorities operate incompatible sorting standards, preventing feedstock aggregation at scale.
- Mechanical recycling contamination limits:Mixed polymer streams exceeding 5% cross-contamination rates are rejected by European reprocessors, shrinking addressable feedstock pools.
Strategic Opportunities
- India's waste-to-energy corridor:Investment flows are reconfiguring toward South Asian megacities where landfill diversion mandates are tightening fastest.
- Blockchain-tracked circularity verification:Brand owners are piloting digital provenance systems to document post-consumer content claims for EU regulatory compliance.
- Industrial waste reverse logistics:Automotive and electronics manufacturers are establishing captive collection networks for cleaner polymer streams commanding premium pellet pricing.
Industry Challenges
- Polymer chemist talent scarcity:Chemical recycling operations require specialized expertise in catalytic cracking that outpaces current vocational training output.
- Extended Producer Responsibility compliance timelines:India's Central Pollution Control Board enforcement deadlines are compressing brand owner infrastructure deployment schedules.
- Legacy mechanical recycling asset stranding:Municipal contract renegotiations are triggering disputes over who bears decommissioning costs for shredded equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Waste Management Market |
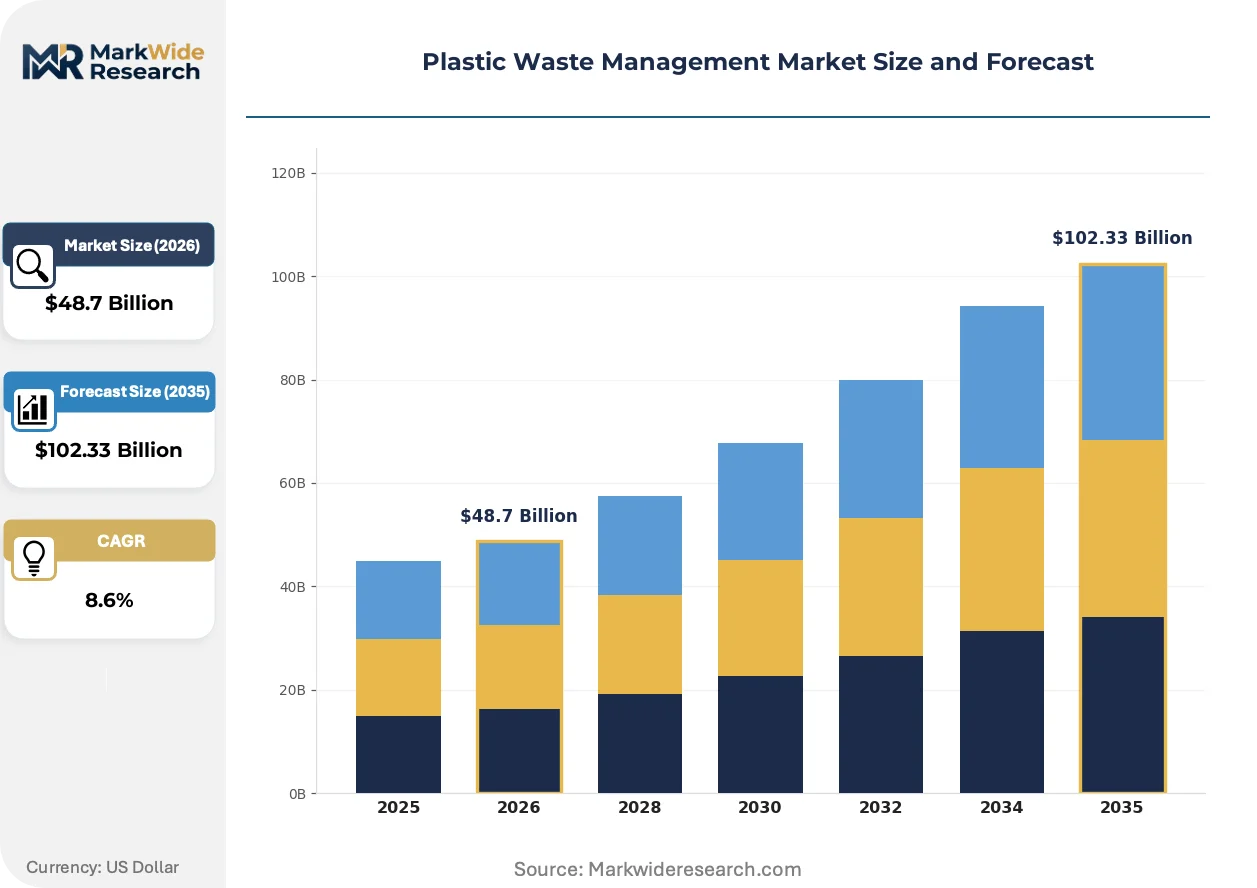
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Category: Industrial Waste, Household Waste, Commercial Waste, Agricultural Waste Process: Recycling, Incineration, Landfill, Biodegradation Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Technology: Mechanical Recycling, Chemical Recycling, Energy Recovery, Composting |
| Companies Covered | Veolia Environment, Waste Management Inc., SUEZ, Republic Services Inc., Waste Connections Inc., Clean Harbors Inc., Covanta Holding Corporation, Stericycle Inc., Remondis SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Waste Management Market Emerging Trajectories
Digital sorting technologies and catalytic depolymerization platforms are converging to unlock contaminated feedstocks that mechanical systems cannot process. The competitive landscape is splitting between capital-intensive chemical recyclers and nimble mechanical operators defending municipal contract positions.
AI-powered near-infrared sorting systems are rendering obsolete manual pick-line operations at materials recovery facilities. Municipal operators in Germany and the Netherlands are deploying these systems at throughput rates exceeding 10 tonnes per hour. The labor cost compression is enabling European recyclers to compete with lower-wage jurisdictions for post-consumer packaging contracts.
REACH authorization requirements for persistent organic pollutants in recycled plastics are tightening contamination thresholds for food-contact applications. The European Chemicals Agency is expanding substance restriction lists to cover legacy additives in post-consumer streams. Packaging manufacturers are responding by segregating feedstock streams at collection source rather than relying on downstream purification.
Brand owners are consolidating supplier relationships around recyclers offering mass-balance certification for chemically recycled content. The shift from spot-market pellet purchasing to multi-year offtake agreements is compressing working capital cycles for advanced recycling projects. Consumer goods multinationals headquartered in France and Switzerland are leading this procurement consolidation, locking in capacity ahead of regulatory mandate deadlines.
Plastic Waste Management Market Segmentation
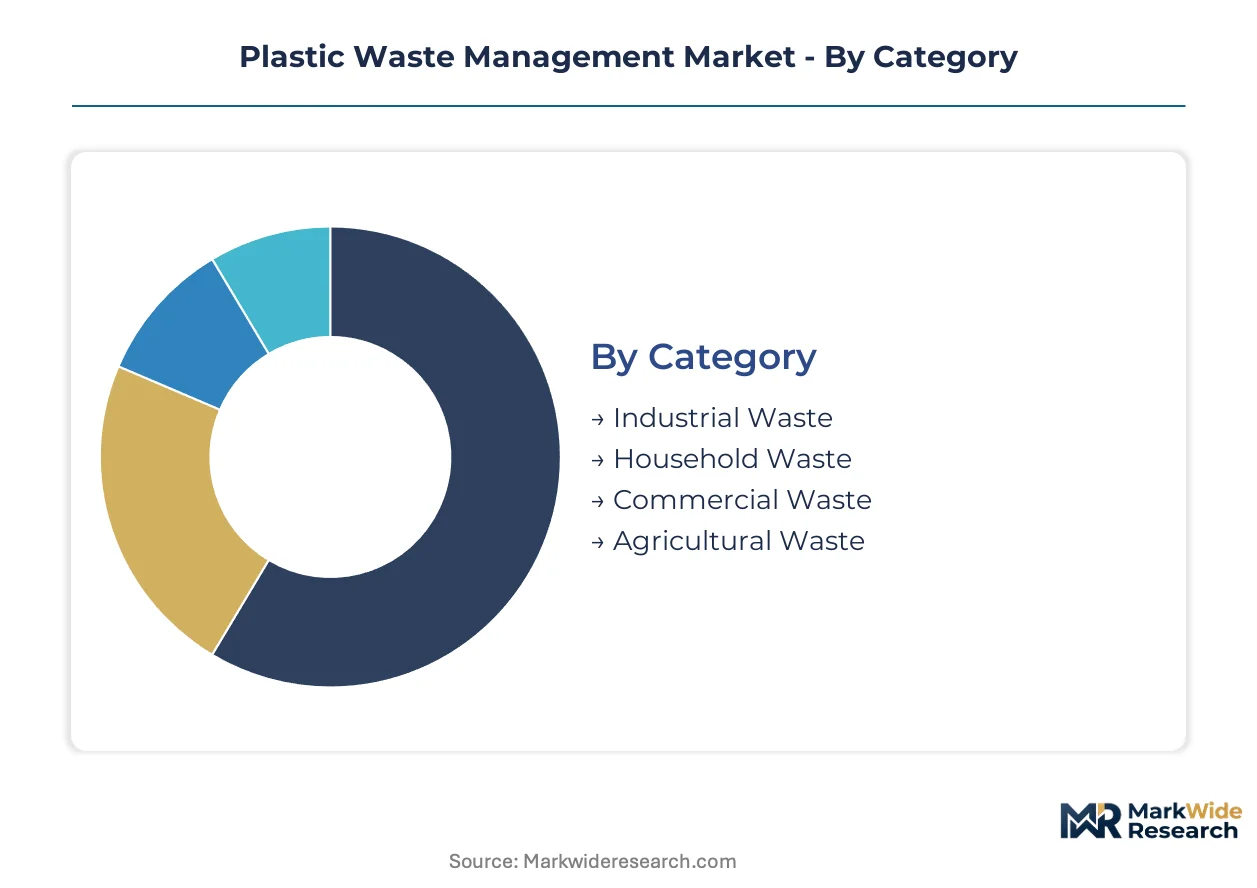
Segmentation reveals how service intensity varies across waste streams. Collection frequency, contamination handling, and processing complexity diverge sharply between industrial generators and dispersed household sources.
Category:
After-sales service intensity peaks with commercial waste contracts requiring scheduled collection windows and contamination reporting. Municipal household programs demand lower touch but higher capital deployment for route optimization.
- Industrial Waste:Generated by manufacturing facilities, construction sites, and institutional generators with established waste manifests and cleaner polymer streams. Automotive suppliers in Germany and electronics assemblers in South Korea are consolidating reverse logistics networks to capture this feedstock. By volume, Industrial Waste leads. By growth pace, Commercial Waste is ahead.
- Household Waste:Post-consumer packaging discarded by residential populations, characterized by high contamination rates and seasonal volume fluctuations. India's urban local bodies under Swachh Bharat Mission 2.0 are expanding door-to-door collection to aggregate these dispersed streams.
- Commercial Waste:Retail, hospitality, and office-generated packaging with moderate contamination and predictable generation patterns. Quick-service restaurant chains in France are piloting segregated collection for contact-sensitive recycling mandates.
- Agricultural Waste:Mulch films, greenhouse covers, and silage wraps contaminated with soil and crop residues. Collection networks in California's Central Valley and Almería, Spain are deploying specialized washing infrastructure.
Industrial Waste dominates revenue per tonne. Household Waste commands the steepest expansion trajectory as EPR frameworks expand coverage.
Process:
Capital intensity separates mechanical shredding operations from thermal treatment facilities. Energy recovery plants require continuous feedstock supply contracts that landfill operations do not.
- Recycling:Mechanical or chemical transformation of waste polymers into secondary raw materials meeting specification for reintroduction to manufacturing. EU Green Deal recycled content mandates are tightening offtake contract terms for mechanical reprocessors in the Netherlands and Belgium.
- Incineration:Controlled combustion with energy recovery, operating at 850-1100°C with flue gas treatment for dioxin control. Waste-to-energy plants in Sweden and Denmark are optimizing heat district integration to improve project economics.
- Landfill:Engineered disposal with leachate containment and methane capture systems. EPA Subtitle D standards in the US and EU Landfill Directive restrictions are compressing permitted capacity in OECD jurisdictions.
- Biodegradation:Microbial decomposition of certified compostable polymers in industrial aerobic or anaerobic facilities. Italy's CONAI consortium is expanding separate collection for food-contact compostables.
Recycling claims the largest volume share. Chemical recycling within this category is climbing the fastest as contamination thresholds tighten.
Type:
Polymer density and additive packages determine processing pathway compatibility. Flexible films require different handling than rigid containers regardless of base resin.
- Polyethylene:Includes LDPE films and HDPE rigid containers, representing the highest volume polymer category in packaging applications. Film reclaimers in Germany are deploying advanced washing lines to handle retail bag streams.
- Polypropylene:Rigid containers, automotive components, and woven sacks with higher melting points enabling broader reprocessing windows. India's rPET and rPP capacity expansion is targeting food-grade certification.
- Polyvinyl Chloride:Construction profiles, medical devices, and cable insulation containing plasticizers requiring specialized separation. REACH authorization constraints in Europe are limiting post-consumer PVC feedstock pools for sensitive applications.
- Polystyrene:Expanded and rigid forms used in protective packaging and food service, characterized by low bulk density challenging collection economics. Densification infrastructure in Japan's metropolitan prefectures is improving transport efficiency.
Polyethylene leads by tonnage processed. Polypropylene is gaining share fastest through automotive closed-loop programs.
Technology:
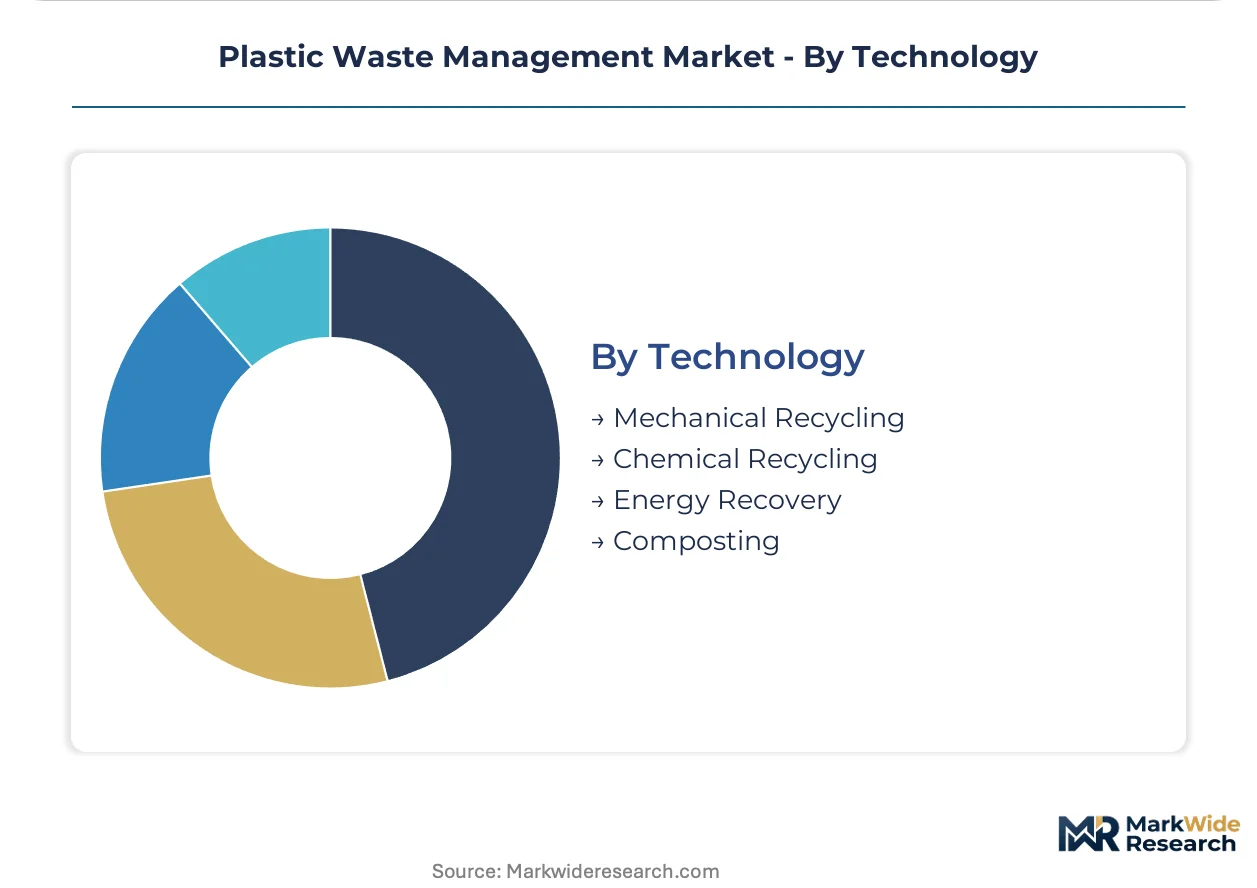
Technology selection hinges on feedstock quality and output specification. Mechanical systems compete on throughput; chemical systems compete on contamination tolerance.
- Mechanical Recycling:Shredding, washing, and re-extrusion without altering polymer molecular structure, limited to single-resin streams below contamination thresholds. European reprocessors are rejecting mixed loads exceeding 5% cross-contamination.
- Chemical Recycling:Depolymerization or pyrolysis converting polymers to monomers or synthetic crude, handling mixed and contaminated streams mechanical systems cannot process. Brand owners in Switzerland and France are locking in multi-year offtake agreements ahead of regulatory deadlines.
- Energy Recovery:Combustion or gasification capturing embedded calorific value as electricity, steam, or syngas. Refinery integration projects in the Port of Rotterdam cluster are upgrading pyrolysis oil to circular naphtha.
- Composting:Aerobic biological processing of certified biodegradable polymers in controlled industrial facilities. Italian and French municipalities are expanding separate brown bin collection for food-contact compostables.
Mechanical Recycling retains volume dominance. Chemical Recycling is expanding most quickly as pyrolysis capacity scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced recycling capacity clusters along the Rhine-Ruhr corridor and the US Gulf Coast, while collection infrastructure investments concentrate in South Asian megacities. Regulatory divergence between EU recycled content mandates and EPR frameworks in emerging economies fragments feedstock aggregation standards.
United States
Landfill-gas capture operations anchor revenue in Texas and Pennsylvania as EPA Subtitle D standards tighten methane emissions thresholds. The IRA's clean energy tax credits accelerate pyrolysis facility development along the Houston Ship Channel. Waste Management Inc. and Republic Services Inc. dominate municipal collection contracts across Sun Belt states.
Germany
Mechanical reprocessors in North Rhine-Westphalia face margin compression from REACH authorization requirements for persistent organic pollutants. The EU Green Deal's Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds for food-contact applications. Veolia Environment leverages its European recycling expertise to secure brand owner offtake agreements.
India
Urban local bodies in Maharashtra and Gujarat modernize solid waste handling under Swachh Bharat Mission 2.0, creating demand corridors for integrated collection-to-pelletization systems. The Central Pollution Control Board enforces Extended Producer Responsibility frameworks obligating brand owners to finance post-consumer plastic collection. Mumbai and Ahmedabad anchor the waste-to-energy corridor attracting South Asian investment flows.
Netherlands
AI-powered near-infrared sorting systems deployed at Rotterdam-area materials recovery facilities achieve throughput rates exceeding 10 tonnes per hour. ECHA substance restriction lists for legacy additives drive feedstock segregation at collection source. The Port of Rotterdam cluster upgrades pyrolysis oil to circular naphtha through refinery integration projects.
Japan
Densification infrastructure in Tokyo and Osaka metropolitan prefectures improves transport economics for low bulk-density polystyrene streams. METI circular economy roadmaps tighten landfill diversion targets for packaging waste. Electronics assemblers in Kansai establish captive collection networks for cleaner polymer streams commanding premium pellet pricing.
Plastic Waste Management Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream sorting technology and processing equipment. The vendor base splits between capital-intensive chemical recyclers scaling pyrolysis capacity and nimble mechanical operators defending municipal contract positions. Three archetypes dominate: integrated waste conglomerates with collection-to-processing networks, pure-play advanced recyclers securing refinery offtake agreements, and equipment fabricators supplying sorting and densification machinery. Competitive moves center on multi-year offtake contract lock-ins and geographic expansion into EPR-mandated jurisdictions.
Among European-anchored environmental service conglomerates, Veolia Environment and SUEZ occupy positions exemplifying the integrated platform archetype, while Republic Services Inc. represents the North American municipal contract specialist tier. These entities anchor competitive dynamics without individual strategic claims.
| Leading Market Players |
|---|
| Veolia Environment |
| Waste Management Inc. |
| SUEZ |
| Republic Services Inc. |
| Waste Connections Inc. |
| Clean Harbors Inc. |
| Covanta Holding Corporation |
| Stericycle Inc. |
| Remondis SE |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European mechanical recycling is compressing utilization rates below 65%, forcing asset owners to accept lower gate fees while pyrolysis operators capture premium pricing for chemically recycled feedstocks. This utilization divergence reconfigures supplier bargaining power across the value chain.
Pricing Analysis
The EU Green Deal's Packaging and Packaging Waste Regulation dictates the pricing tier structure across the European market. Three-tier pricing structure across premium, standard, and economy levels separates food-grade certified recyclate from industrial-grade pellet and unprocessed baled feedstock. Cost compression in mechanical recycling is intensifying because contamination thresholds below 5% cross-contamination rates are shrinking addressable feedstock pools. Municipal waste authorities demonstrate highest price sensitivity due to budget-constrained collection contracts, while brand owners under Extended Producer Responsibility frameworks show lowest sensitivity when securing long-term offtake agreements for regulatory compliance.
Supply Chain Analysis
Tariff exposure between Southeast Asian collection hubs and European reprocessing centers dominates supply chain risk calculus for post-consumer plastic feedstocks. Feedstock aggregation concentrates in India, Germany, and the Netherlands, with pyrolysis oil upgrading drawing from refinery integration clusters in the Port of Rotterdam. Raw material dependencies rest on baled post-consumer packaging, catalytic cracking additives, and polymer sorting equipment. Single-source vulnerability around AI-powered near-infrared sorting systems from limited equipment fabricators threatens throughput expansion. Distribution runs through integrated collection-to-pelletization networks anchored by municipal contract holders and brand-owner financed reverse logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plastic waste management is approaching a platform-economics inflection where blockchain-tracked circularity verification systems create interoperability standards between brand owners, recyclers, and regulators. This ecosystem shift rewards early movers who embed digital provenance into collection infrastructure.
For Market Incumbents: Insulate municipal contract positions by deploying AI-powered sorting systems that achieve throughput rates exceeding 10 tonnes per hour, compressing labor costs against lower-wage jurisdiction competition. Deepen backward integration into pyrolysis capacity to capture premium pricing as chemical recycling displaces mechanical margins. Prioritize certification investment for food-grade recyclate to defend against REACH authorization constraints tightening contamination thresholds.
For New Entrants and Emerging Players: Build out captive collection networks for industrial polymer streams in automotive and electronics manufacturing corridors where cleaner feedstock commands premium pellet pricing. Target India's waste-to-energy corridor under Swachh Bharat Mission 2.0 where landfill diversion mandates are tightening fastest and municipal infrastructure gaps persist. Lead with blockchain-tracked circularity verification as the go-to-market angle to differentiate from incumbent spot-market pellet suppliers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chemical recycling sub-segments as pyrolysis facility deployments require refinery integration and continuous feedstock supply contracts. Frame long-term viability around recyclers securing multi-year offtake agreements with consumer goods multinationals headquartered in France and Switzerland ahead of regulatory mandate deadlines. Target acquisition candidates among pure-play advanced recyclers with mass-balance certification capabilities. Watch pyrolysis oil upgrading cost curves intersecting with virgin naphtha pricing as the inflection signal for scaled deployment economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis Capacity | Captures premium pricing for chemically recycled feedstocks as EU Green Deal mandates tighten. |
| AI-Powered Sorting System Deployment | Enables throughput rates exceeding 10 tonnes per hour, compressing labor costs against global competition. |
| Blockchain-Tracked Circularity Verification | Documents post-consumer content claims for EU Packaging and Packaging Waste Regulation compliance. |
| Long-Term Offtake Agreement Lock-In | Secures working capital cycles for advanced recycling projects ahead of regulatory deadline compression. |
| Geographic Expansion into EPR-Mandated Jurisdictions | Positions collection infrastructure to capture brand owner financing under India's Central Pollution Control Board frameworks. |
Methodological Framework
A standing panel of municipal solid waste directors, chemical recycling plant managers, brand owner sustainability leads, and polymer procurement specialists provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against customs and trade data, EPA enforcement records, EU regulatory filings, and SEC disclosures from publicly traded waste management conglomerates. Bottom-up feedstock volume estimates triangulated against top-down market sizing from national waste characterization studies.
Scenario-bracketing framed the analytical approach across the projection horizon, with high-growth and conservative cases bounding the central forecast. Segmentation dimensions modeled include waste category, process type, polymer chemistry, and technology pathway alongside geographic regulatory cluster. CAGRs derived from trend extrapolation of historical collection infrastructure deployment rates and policy mandate implementation timelines. Industry-specific inputs incorporated pyrolysis capacity buildout schedules and EPR framework enforcement intensity variations.
Stress conditions across natural gas price volatility, feedstock contamination rate spikes, and regulatory deadline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about polymer chemist talent pipeline expansion and refinery offtake contract availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Malaysia Plastics Market
Recycled Plastics
USA Plastic-To-Fuel Market
Recycled Plastics
Europe Recycled Plastics Market
Recycled Plastics
Global Recycled Base Oil Market
Recycled Plastics
China Plastics Market
Recycled Plastics
Recycled Leather Market
Recycled Plastics
Environmentally Friendly RPET Webbing Market
Recycled Plastics
Graphite Recycling Market
Recycled Plastics
Fiber-Reinforced Plastic (FRP) Recycling Market
Recycled Plastics
Waste Plastic Bricks Market
Recycled Plastics
Foam Plastics Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
Plastic Color Sorter Market
Recycled Plastics
South-East Asia (SEA) Plastics Market
Recycled Plastics
Vietnam Recycled Plastics Market
Recycled Plastics
US Recycled Plastics Market