
 Global Thermoset Resin Market | 2026-2036
Global Thermoset Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermoset Resin Market Foresight
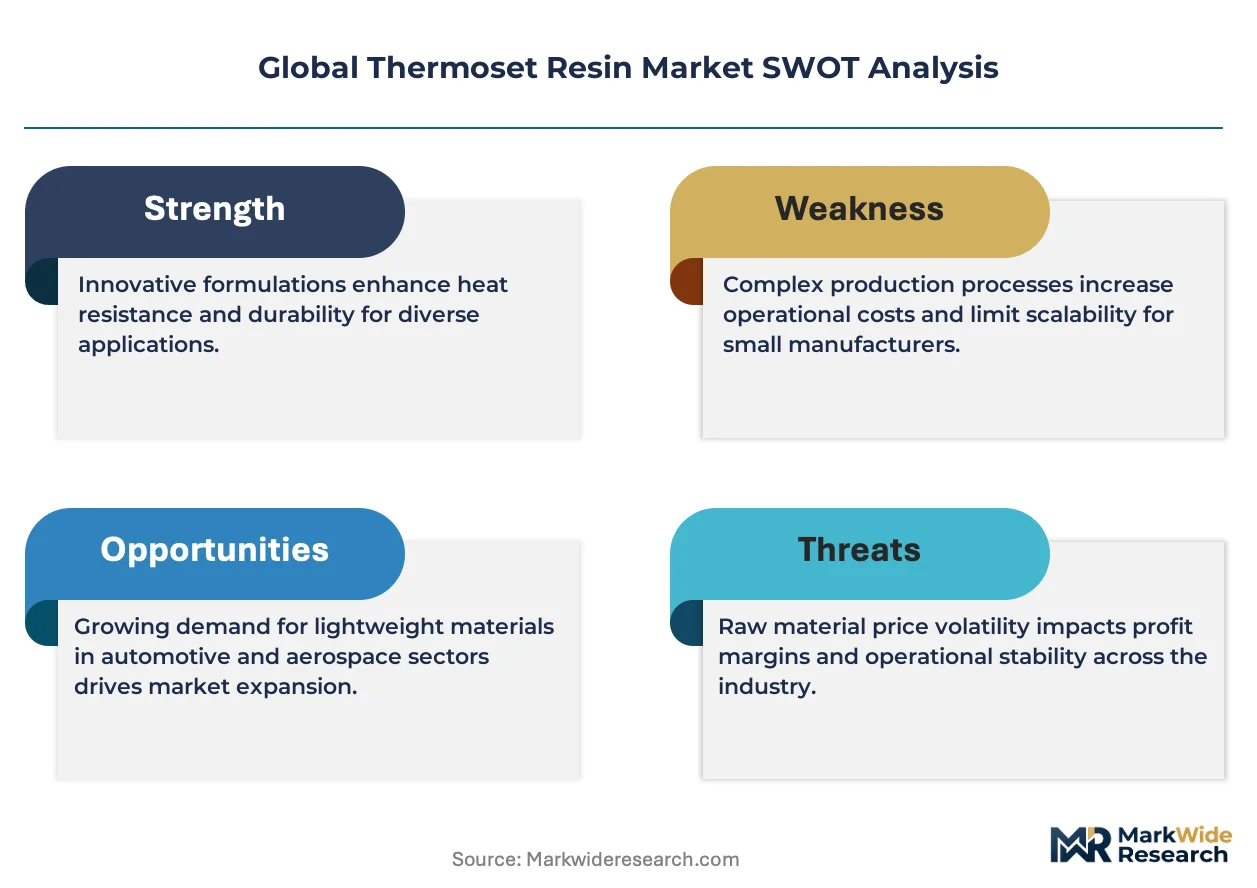
Wind energy turbine manufacturers are bifurcating from construction-grade buyers as blade specifications demand higher-performance epoxy formulations. Huntsman Corporation leverages its specialty amine curing agent portfolio to anchor supply relationships with Vestas and Siemens Gamesa tier-one molders. Hexion Inc. competes through backward integration into phenolic resin feedstocks, sustaining cost discipline across North American and European laminators. BASF SE differentiates via nano-silica modified epoxies for lightning-protection layers, a sub-area where technical specifications tighten faster than commodity grades.
Thermoset resins are cross-linked polymers that permanently harden through irreversible chemical curing, typically requiring precise stoichiometric ratios of base resin to hardener and controlled exotherm management above 120°C to achieve glass transition temperatures exceeding 150°C. Their primary industrial purpose is to deliver dimensional stability, chemical resistance, and structural load-bearing capacity in applications where thermoplastic re-melting would constitute catastrophic failure. Epoxy formulations dominate aerospace primary structures and wind blade spar caps, where margin pools concentrate in certified aerospace-grade material qualification cycles. Phenolic resins retain mature positions in mass-transit interior panels and foundry binders, while polyester segments face displacement in marine hull construction as vinyl ester alternatives demonstrate superior blister resistance and fatigue performance.
REACH registration requirements and EU Green Deal carbon-border adjustment mechanisms are forcing reformulation of aromatic amine curing agents toward aliphatic and bio-derived substitutes, directly elevating R&D overhead for EU-market participants. EPA TSCA Section 5 pre-manufacture notifications and China's GB standards for volatile organic compound emissions in composite manufacturing are creating divergent compliance pathways that segment global product portfolios. China's MEE enforcement of dual carbon goals at provincial level is tightening phenolic resin plant operating permits in Shandong and Jiangsu clusters. Stakeholders must monitor curing technology substitution rates as UV-initiated systems challenge thermal curing energy intensity in automotive and electronics applications.
Market Dynamics
Blade length inflation in wind turbine manufacturing is compressing formulation tolerances and forcing resin suppliers to certify entirely new epoxy-amine systems for 120-meter-plus spar caps.
Growth Catalysts
- Offshore wind installation targets:China's state-backed coastal wind programs are pulling phenolic and vinyl ester prepreg imports into domestic nacelle assembly hubs.
- REACH reformulation mandates:ECHA pressure on aromatic amine curing agents redirects R&D budgets toward aliphatic and bio-based substitutes with equivalent glass transition performance.
- Lightning protection layering:Nano-silica modified epoxies for conductive blade skins create specification tiers that outpace commodity-grade margin compression.
Market Restraints
- Bisphenol-A feedstock volatility:Petrochemical price swings compress working capital cycles for unsaturated polyester and vinyl ester compounders.
- Shandong-Jiangsu permit tightening:China's MEE enforcement of dual carbon goals restricts phenolic resin plant operating licenses in coastal chemical clusters.
- Thermoplastic substitution in automotive:Recyclable PEEK and PPS composites displace thermosets in under-hood applications where re-melting tolerance exists.
Strategic Opportunities
- India wind nacelle localization:PLI scheme incentives for domestic blade manufacturing create captive demand for epoxy prepregs currently imported from China and Germany.
- UV-initiated curing convergence:Photopolymerization technology intersects with automated fiber placement to reduce thermal curing energy intensity in automotive body panels.
- EU carbon-border adjustment arbitrage:CBAM implementation on imported composites rewards EU-based resin producers with verified low-carbon process certifications.
Industry Challenges
- Certified aerospace material qualification:FAA and EASA approval cycles for primary structure epoxies extend 18-36 months, freezing formulation changes mid-program.
- Legacy thermal curing asset stranding:Capital-intensive autoclave and oven infrastructure resists rapid retooling for out-of-autoclave resin infusion processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermoset Resin Market |
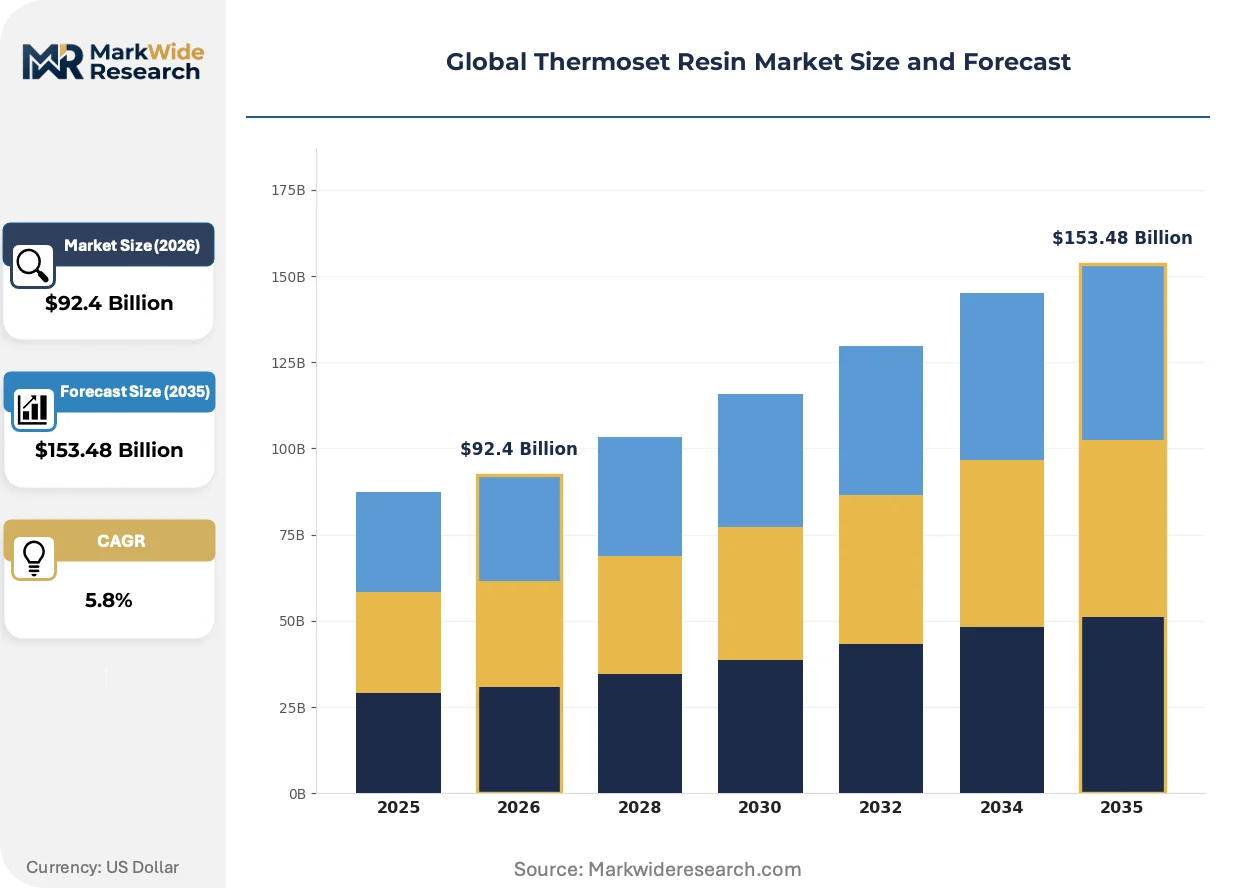
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $153.48 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Phenolic, Polyester, Melamine, Urea, Silicone Technology: Curing Agents, Catalysts, Accelerators, Nano-fillers, UV Curing, Thermal Curing Application: Electrical & Electronics, Construction, Marine, Aerospace, Wind Energy, Sporting Goods End User Industry: Electronics Manufacturing, Infrastructure Development, Aviation Manufacturing, Renewable Energy, Consumer Goods Production, Transportation Equipment |
| Companies Covered | Huntsman Corporation, Hexion Inc., BASF SE, Mitsui Chemicals Inc., Henkel AG & Co. KGaA, Dow Chemical Company, DuPont, DIC Corporation, Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermoset Resin Market Shifts & Advancements
Formulation chemistry is bifurcating between ultra-high-performance certified grades for critical structures and cost-optimized systems for commoditized laminates.
Out-of-autoclave epoxy prepregs with integrated heating elements are miniaturizing cure cycle times from hours to minutes. Aerospace tier-two suppliers in Italy and Japan are piloting these systems for satellite bus structures. The technology is miniaturizing capital requirements for composite manufacturing, enabling mid-scale molders to compete without autoclave infrastructure.
EPA TSCA Section 5 pre-manufacture notifications for novel amine hardeners are extending lead times for US-market introductions. Industrial consequences include portfolio fragmentation, with EU-registered substances diverging from American-available chemistries. Affected segments are redirecting toward grandfathered curing agents rather than innovating through new molecular architectures.
Specification-driven procurement now dominates wind blade supply negotiations, with OEMs unbundling resin selection from general composite sourcing. Tier-one molders in Denmark and Spain are establishing direct relationships with specialty hardener producers, bypassing traditional distributor channels. This pattern concentrates most visibly in offshore wind supply chains where blade failure costs exceed material premiums by orders of magnitude.
Global Thermoset Resin Market Segmentation
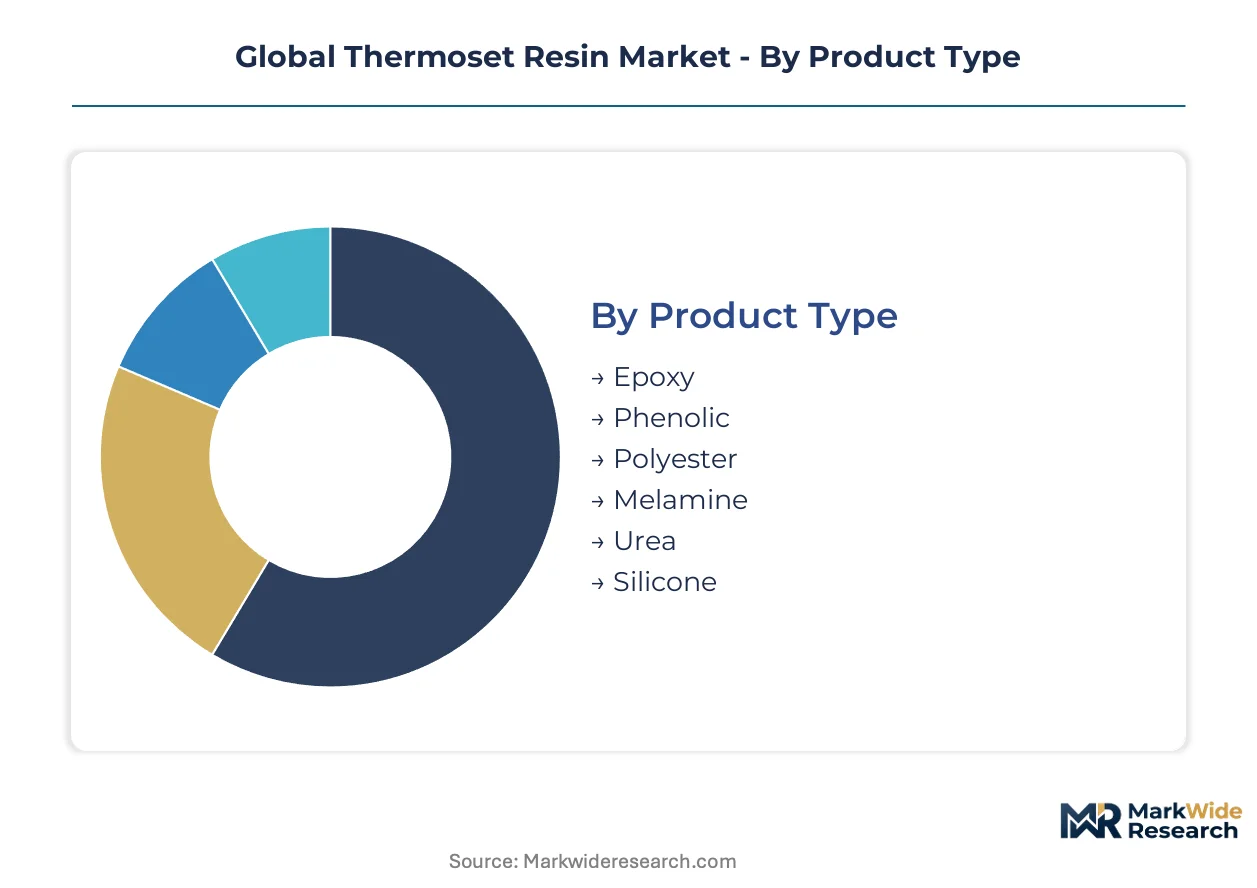
Formulation chemistry and end-use specifications fragment the thermoset resin landscape into distinct procurement channels. Each segment carries divergent margin structures, certification burdens, and supply chain configurations that reshape competitive positioning.
Product Type:
Epoxy and phenolic formulations flow through specialized distributors serving certified aerospace and wind energy molders, while polyester and melamine grades reach construction and consumer goods manufacturers via bulk chemical traders.
- Epoxy:Cross-linked systems built from bisphenol-A or bisphenol-F precursors with amine or anhydride hardeners deliver glass transition temperatures exceeding 150°C. Demand concentrates in China and Denmark for wind blade spar caps exceeding 100 meters, where OEMs mandate lightning-conductive nano-silica modifications. REACH aromatic amine restrictions are elevating R&D overhead for EU-qualified grades.
- Phenolic:Formaldehyde-condensed resins with inherent flame resistance and low smoke toxicity specifications. Procurement clusters in Chinese coastal provinces for mass-transit interior panels and foundry binders, though MEE permit tightening in Shandong and Jiangsu is constraining domestic supply expansion.
- Polyester:Unsaturated formulations cross-linked with styrene monomer dominate commodity composite fabrication.
- Melamine:Amino resin systems providing surface hardness and decorative finishes for laminates and molding compounds.
- Urea:Cost-competitive amino resins for wood adhesives and industrial binders with moderate moisture resistance.
- Silicone:Organosiloxane networks delivering thermal stability and electrical insulation for high-heat electronics encapsulation.
By volume, polyester leads through construction and marine fabrication. By growth pace, epoxy is ahead, pulled by offshore wind blade scaling and aerospace material qualification backlogs.
Technology:
Margin concentration follows energy intensity and automation compatibility, with thermal curing systems commanding premium pricing in certified applications while UV-initiated platforms capture automotive and electronics volume through reduced cycle times.
- Curing Agents:Amine and anhydride functional hardeners governing cross-link density and thermal performance. Specification divergence between EU REACH-registered aliphatic systems and grandfathered aromatic alternatives in the US is fragmenting global product portfolios.
- Catalysts:Acid and base compounds initiating condensation polymerization in phenolic and amino resin systems.
- Accelerators:Cobalt and tertiary amine promoters reducing gel times in unsaturated polyester processing.
- Nano-fillers:Silica, clay, and carbon nanotube additives modifying mechanical and conductive properties.
- UV Curing:Photoinitiator-triggered polymerization eliminating thermal energy input for thin-film and coating applications.
- Thermal Curing:Elevated-temperature processing delivering maximum cross-link density for structural composites.
By installed base, thermal curing dominates. By substitution momentum, UV curing is climbing the fastest as automotive tier-one suppliers retool for out-of-autoclave body panel production.
Application:
Certification tier determines channel access, with aerospace and wind energy segments requiring direct supplier-OEM relationships while construction and sporting goods flow through distributor networks.
- Wind Energy:Spar caps, root joints, and lightning protection layers for blades exceeding 100 meters. Procurement concentrates with Vestas and Siemens Gamesa tier-one molders in Denmark and Spain, who are establishing direct hardener supplier relationships bypassing traditional distributors.
- Aerospace:Primary structures, satellite buses, and interior components subject to FAA and EASA qualification cycles extending 18-36 months. Italian and Japanese tier-two suppliers are piloting out-of-autoclave prepregs with integrated heating elements to compress capital requirements.
- Electrical & Electronics:Encapsulation, printed circuit boards, and insulation systems.
- Construction:Reinforced concrete, architectural panels, and corrosion-resistant infrastructure.
- Marine:Hull construction and deck components where vinyl ester alternatives displace polyester for blister resistance.
- Sporting Goods:Bicycles, hockey sticks, and recreational equipment utilizing commodity prepreg grades.
By revenue concentration, aerospace commands premium pricing. By expansion trajectory, wind energy is gaining share fastest through China's state-backed offshore installation targets.
End User Industry:
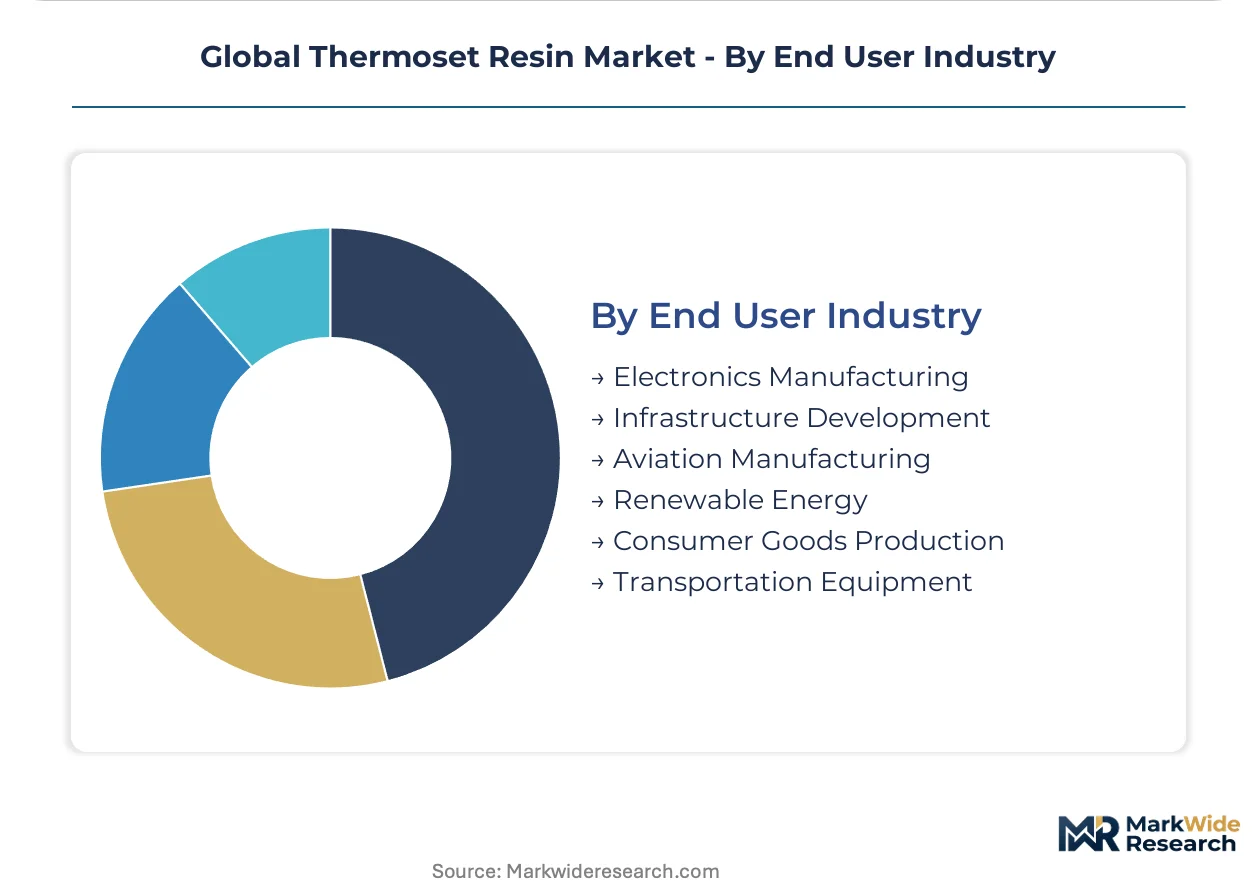
Procurement sophistication separates electronics and aviation manufacturers with dedicated resin qualification teams from infrastructure developers and consumer goods producers purchasing on specification and price.
- Renewable Energy:Wind turbine OEMs and component fabricators with unbundled resin selection from general composite sourcing. India's PLI scheme for domestic nacelle localization is creating captive demand for epoxy prepregs currently imported from China and Germany.
- Aviation Manufacturing:Airframe and engine producers with material qualification protocols freezing formulation changes mid-program. EASA and FAA approval cycles create substantial switching costs for incumbent suppliers.
- Electronics Manufacturing:Semiconductor packaging and device producers.
- Infrastructure Development:Bridge, tunnel, and building contractors.
- Consumer Goods Production:Appliance and furniture manufacturers.
- Transportation Equipment:Automotive and rail producers where thermoplastic PEEK and PPS composites displace thermosets in under-hood recyclability applications.
By contract value, aviation manufacturing leads. By policy tailwinds, renewable energy shows the steepest demand expansion through coastal wind targets in China and localization incentives in India.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater ports and bonded logistics zones anchor China's dominance in phenolic and vinyl ester prepreg imports for offshore wind nacelle assembly.
China
State-backed coastal wind installation targets pull phenolic and vinyl ester prepreg imports through Shanghai and Ningbo-Zhoushan port clusters. MEE enforcement of dual carbon goals tightens phenolic resin plant operating permits in Shandong and Jiangsu provinces. Domestic nacelle assembly capacity in Jiangsu concentrates procurement relationships with Vestas and Siemens Gamesa tier-one molders.
United States
Wind blade manufacturing expansion in Texas and Iowa drives epoxy-amine system demand for 100-meter-plus spar caps. EPA TSCA Section 5 pre-manufacture notifications extend lead times for novel amine hardeners, fragmenting portfolios from EU-registered alternatives. Gulf Coast petrochemical corridors supply bisphenol-A feedstocks to unsaturated polyester compounders facing working capital compression.
Germany
REACH aromatic amine restrictions redirect R&D budgets toward aliphatic and bio-based curing agents with equivalent glass transition performance. ECHA pressure forces reformulation of legacy epoxy systems for wind energy and aerospace applications. Industrial clusters in North Rhine-Westphalia house specialty hardener producers establishing direct relationships with Danish blade molders.
India
PLI scheme incentives for domestic wind nacelle localization create captive demand for epoxy prepregs currently imported from China and Germany. CEA grid integration mandates accelerate offshore wind project pipelines along Gujarat and Tamil Nadu coastlines. Manufacturing hubs in Pune and Chennai attract hardener suppliers bypassing traditional distributor channels.
Denmark
Vestas and Siemens Gamesa headquarters concentrate specification-driven procurement for lightning-conductive nano-silica modified epoxies. EU Green Deal carbon-border adjustments reward domestic resin producers with verified low-carbon process certifications. Copenhagen logistics corridors channel formulations to blade molding facilities across Jutland and Funen.
Global Thermoset Resin Market Competitive Landscape
Concentration sits with diversified chemical conglomerates controlling curing agent portfolios and backward-integrated phenolic feedstock operations. Three archetypes define competitive positioning: specialty amine hardener specialists anchoring wind energy supply relationships, integrated petrochemical players managing bisphenol-A cost volatility, and nano-silica modification technologists capturing lightning protection premiums. Dominant competitive moves include direct supplier-OEM relationship formation bypassing distributors and out-of-autoclave curing technology licensing to compress mold cycle times.
Within the specialty hardener tier, Huntsman Corporation and Hexion Inc. occupy positions reflecting divergent integration strategies. Huntsman exemplifies the amine curing agent specialist archetype through its portfolio breadth serving certified aerospace and wind blade molders. Hexion represents backward-integrated phenolic resin operations sustaining cost discipline across North American and European laminators. BASF SE anchors the nano-modification vector, its position reflecting technical differentiation in conductive blade skin applications where specifications tighten faster than commodity grades.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Hexion Inc. |
| BASF SE |
| Mitsui Chemicals Inc. |
| Henkel AG & Co. KGaA |
| Dow Chemical Company |
| DuPont |
| DIC Corporation |
| Solvay S.A. |
| Others |
Supply & Pricing Matrix
Scale economies in 120-meter blade epoxy certification are compressing margin dispersion and anchoring price floors to amortized qualification costs. China's coastal nacelle assembly expansion and REACH reformulation mandates in Germany are bifurcating procurement channels between volume-contracted commodity grades and specification-locked premium tiers.
Pricing Analysis
Three-tier pricing structure across aerospace-qualified, wind-certified, and commodity construction grades separates procurement channels. Price differentiation hinges on EASA/FAA certification status and lightning-conductive nano-silica modification levels. Cost compression in unsaturated polyester runs through bisphenol-A feedstock volatility, while epoxy-amine systems for offshore wind show pricing resilience. Construction laminators exhibit highest price sensitivity; aerospace tier-one molders prioritize qualification continuity over unit cost.
Supply Chain Analysis
China and Germany anchor phenolic resin production and specialty hardener formulation respectively. Raw material dependencies draw from Shandong petrochemical corridors for formaldehyde, North Rhine-Westphalia for aliphatic amine intermediates, and Gulf Coast bisphenol-A crackers. Single-source vulnerability concentrates in aromatic amine curing agents facing REACH substitution deadlines. Distribution runs through direct supplier-OEM relationships in wind energy, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry fragmentation creates niche entry points as blade specifications diverge from construction-grade standards. Unbundled resin selection by Vestas and Siemens Gamesa tier-one molders is opening direct procurement channels outside incumbent distributor networks.
For Market Incumbents: Consolidate backward integration into bisphenol-A and phenol feedstocks to buffer petrochemical price swings. Lock in multi-year qualification cycles with EASA and FAA to freeze formulation changes mid-program, defending against UV-curing substitution in automotive panels. For New Entrants and Emerging Players: Lead with bio-based aliphatic curing agents targeting REACH-compliant EU wind energy procurement. India's PLI scheme for domestic nacelle localization offers the most penetrable geography, with hardener supply agreements as the go-to-market angle bypassing established distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty hardener producers with certified aerospace relationships over commodity polyester compounders. Long-term viability hinges on out-of-autoclave curing technology licensing revenue streams. Watch UV-initiated system adoption rates in automotive body panels as the inflection signal for thermal curing asset obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenolic Feedstocks | Hexion's captive formaldehyde supply shields margin compression from Shandong permit tightening. |
| Direct Supplier-OEM Relationship Formation | Huntsman's Vestas and Siemens Gamesa bypass of distributors captures specification-driven procurement premiums. |
| Out-of-Autoclave Curing Technology Licensing | Italian and Japanese tier-two satellite bus suppliers compress capital requirements for mid-scale molders. |
| REACH-Compliant Aliphatic Hardener R&D | BASF's bio-based curing agent investment redirects R&D overhead toward EU carbon-border adjustment compliance. |
| Long-Term Supply Agreement with Offshore Wind Developers | China's state-backed coastal wind targets pull phenolic and vinyl ester prepreg imports through bonded logistics zones. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, ACC/Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Plant managers at Shandong and Jiangsu phenolic resin facilities, procurement leads at Vestas and Siemens Gamesa tier-one molders, distribution channel partners serving North American construction laminators, and technical R&D directors at specialty hardener producers provided qualitative validation. Bottom-up volume modeling triangulates against top-down value estimates across formulation chemistry tiers.
Segmentation dimensions modeled include resin chemistry type, curing technology platform, certification grade tier, end-use application intensity, and regional production hub clustering. CAGRs derive from elasticity-adjusted demand projections and capacity utilization trajectories across the analysis window. Forecast inputs incorporate blade length scaling curves for wind energy and REACH substitution timelines for aromatic amine hardeners.
The analysis sits within stated boundaries; outcomes outside sustained offshore wind installation execution or accelerated UV-curing adoption would require recalibration. Forecasts reflect assumptions on feedstock price stability and regulatory enforcement consistency. Recalibration cycles align with material shifts in MEE permit enforcement and ECHA substance restriction timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Polymer Ingredients Market
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
Global UV Curable Resins and Formulated Products Market
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
Bio-Based PVC Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
Liquid Polybutadiene [LPBD] Market
Polymers & Resins
Casting Resin Market
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
Global Medium Molecular Weight Polyisobutylene Market