
 Filters and Particle Monitoring Market | 2026-2036
Filters and Particle Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Filters and Particle Monitoring Market Foresight
The EU Green Deal's industrial emissions benchmarks are recalibrating procurement priorities across European process industries. 3M leverages its fluoropolymer membrane expertise to dominate high-purity air handling for semiconductor foundries. Donaldson Company, Inc. anchors its position in heavy-duty industrial filtration through backward integration into pleated media manufacturing. Sartorius Group specializes in single-use filtration assemblies that reduce cross-contamination risk in biopharmaceutical production.
Filters and particle monitoring encompass mechanical separation media and real-time aerosol or liquid-borne particle detection instrumentation, typically rated by efficiency at 0.3 micron particle size under standardized test protocols. These systems protect product integrity, equipment longevity, and occupational health across contamination-sensitive operations. HEPA filters command premium pricing in cleanroom technology applications where ISO 14644-1 Class 3-5 compliance is mandatory. Optical monitoring and laser diffraction technologies are displacing gravimetric methods in continuous emissions monitoring systems due to faster response times and lower maintenance burden. Mass spectrometry-based particle characterization occupies a high-margin niche in research laboratories and pharmaceutical quality control.
EPA National Ambient Air Quality Standards and EU F-Gas Regulation are tightening permissible emissions thresholds, compelling facility operators to replace aging baghouse filters and install continuous opacity monitors. China's MEE enforces GB 13271 boiler emission limits that mandate electrostatic precipitator upgrades in steel and cement plants. Stakeholders must weigh capital intensity against regulatory enforcement timelines when sequencing filtration infrastructure investments across multi-site manufacturing networks.
Market Dynamics
Semiconductor fabrication scaling in East Asia and EPA PM2.5 enforcement in North America are compressing replacement cycles for high-efficiency filtration media while elevating real-time monitoring instrumentation to mission-critical status.
Growth Catalysts
- EPA National Ambient Air Quality Standards:Tightened PM2.5 thresholds are compelling steel and cement operators to upgrade electrostatic precipitators and install continuous opacity monitors.
- HEPA filtration in biologics manufacturing:Single-use filtration assemblies are displacing stainless-steel systems to eliminate cross-contamination risk in multi-product facilities.
- Optical particle monitoring:Laser diffraction technologies are displacing gravimetric methods in continuous emissions monitoring due to faster response times and reduced maintenance burden.
Market Restraints
- Fluoropolymer supply concentration:PTFE membrane production concentrates among a handful of chemical conglomerates, creating input cost volatility for high-purity filter manufacturers.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases are complicating membrane chemistry transitions and extending product requalification timelines.
- Electrostatic precipitator longevity:Decades-long service life in heavy industry delays upgrade cycles even where regulatory deadlines have passed.
Strategic Opportunities
- India's PLI scheme for semiconductors:Incentivized fab construction in Gujarat and Karnataka will generate demand for ISO 14644-1 Class 3-5 cleanroom infrastructure.
- Mass spectrometry particle characterization:Convergence of ion mobility spectroscopy with optical counting is opening high-margin niches in pharmaceutical quality control.
- Direct-to-facility monitoring-as-a-service:Sensor networks with cloud analytics are bypassing traditional distributor channels in emissions-intensive process industries.
Industry Challenges
- Cleanroom certification bottlenecks:ISO 14644-1 compliance testing requires specialized aerosol photometer operators, creating talent scarcity in rapidly expanding semiconductor markets.
- Legacy baghouse retrofit complexity:Integrating continuous monitoring instrumentation with pre-digital dust collection systems demands custom engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filters and Particle Monitoring Market |
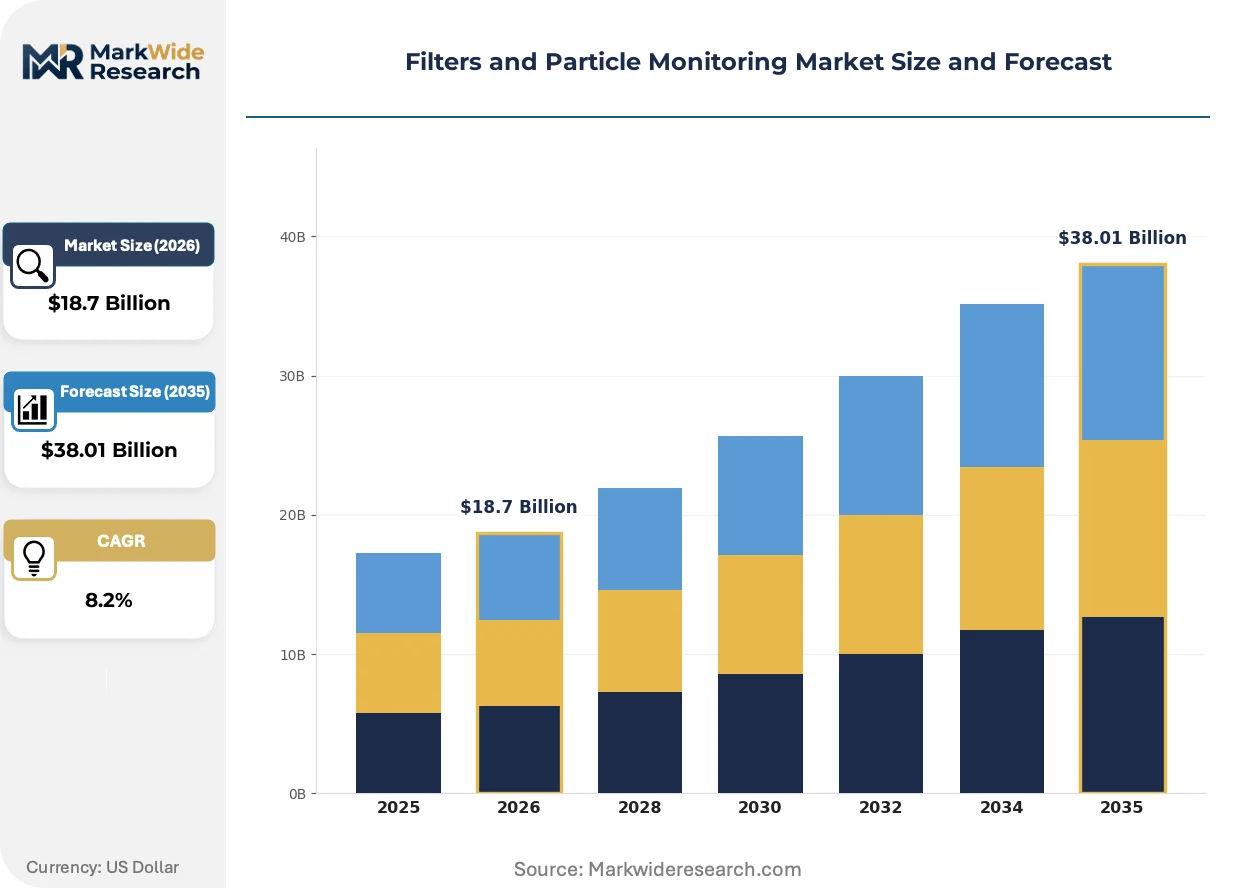
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.01 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Activated Carbon Filters, Baghouse Filters, Electrostatic Filters Application: Air Purification, Water Treatment, Industrial Processing, Cleanroom Technology Technology: Filtration Systems, Optical Monitoring, Laser Diffraction, Mass Spectrometry End User: Manufacturing Plants, Healthcare Facilities, Research Laboratories, Food Processing |
| Companies Covered | Agilent Technologies, Inc., 3M, Merck Millipore, Thermo Fisher Scientific, Donaldson Company, Inc., Sartorius Group, Honeywell International Inc, TSI Incorporated, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filters and Particle Monitoring Market Shifts & Advancements
Filter media chemistry, monitoring instrumentation architecture, and procurement contracting models are undergoing simultaneous transformation as contamination control requirements tighten across process industries.
Membrane-based filtration is modularizing through the adoption of cassette and capsule formats that eliminate stainless-steel hardware from biopharmaceutical production. Contract manufacturers in the Yangtze River Delta are standardizing on single-use assemblies to accelerate product changeovers. This shift is compressing capital requirements for multi-product facilities while creating aftermarket revenue concentration in consumables.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing membrane suppliers to reformulate PTFE alternatives without sacrificing 0.3-micron retention efficiency. The EU Green Deal's industrial emissions benchmarks are recalibrating procurement priorities toward fluoropolymer-free options where technically feasible. Pharmaceutical and food-grade applications face the steepest compliance timelines given patient safety exposure pathways.
Lifecycle service contracts are bundling filter media supply with predictive maintenance analytics, displacing transactional spot purchasing in heavy industrial accounts. Equipment OEMs are capturing recurring revenue through sensor-embedded filtration systems that automate replacement scheduling. This pattern is most visible in German automotive paint shops and South Korean battery electrode coating operations where unplanned downtime carries severe cost penalties.
Filters and Particle Monitoring Market Segmentation
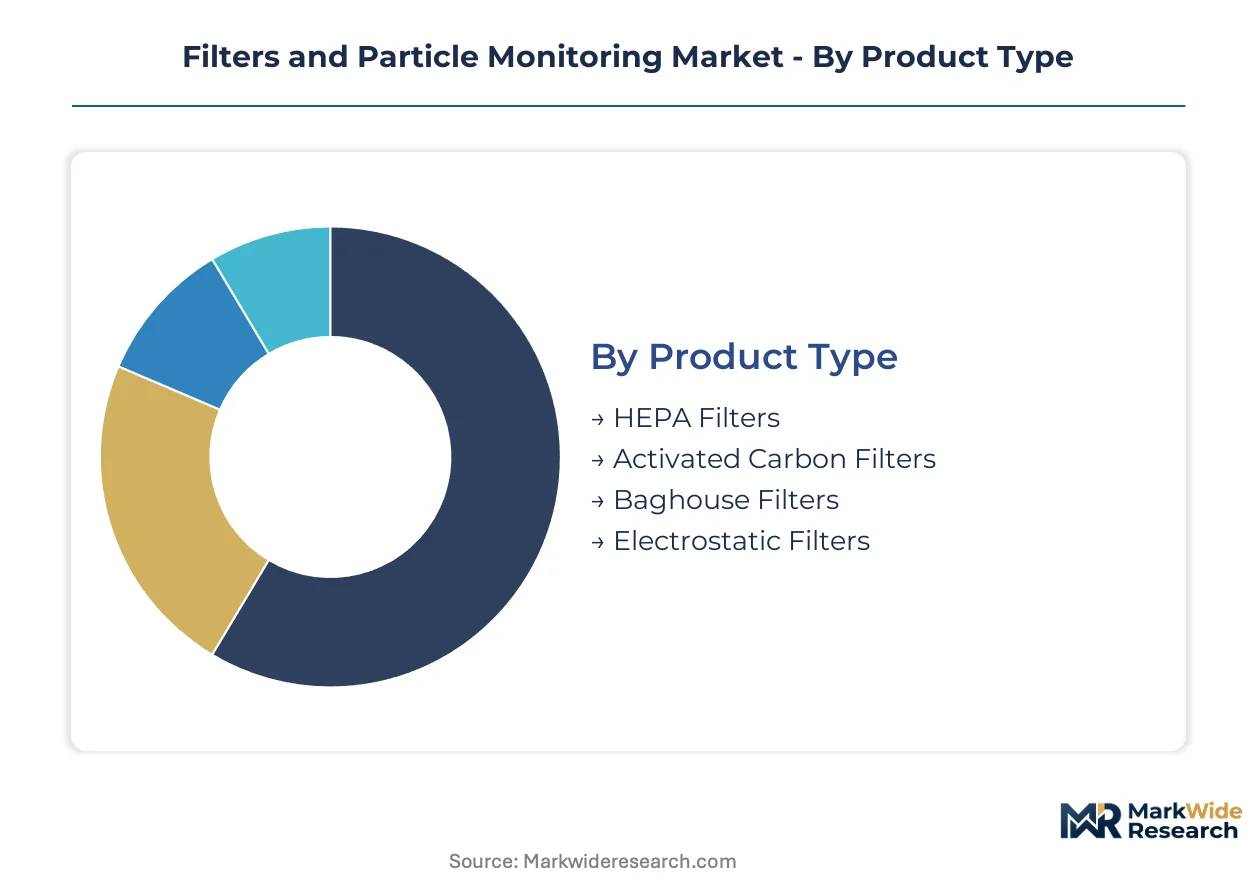
Segmentation in filters and particle monitoring reflects divergent contamination control requirements across semiconductor fabrication, pharmaceutical production, and heavy industrial emissions compliance. Procurement patterns split between capital-intensive fixed installations and high-velocity consumable replacements, with regulatory deadlines forcing synchronized upgrade cycles across multi-site operators.
Product Type:
Buyers select media based on particle retention efficiency, chemical compatibility, and replacement cycle economics rather than upfront hardware cost alone.
- HEPA Filters:Fiberglass or PTFE membrane media rated at 99.97% efficiency for 0.3-micron particles under EN 1822 or IEST-RP-CC001 protocols. Taiwan Semiconductor Manufacturing Company and Samsung Foundry specify these for ISO 14644-1 Class 3-5 cleanrooms as chip sovereignty investments accelerate.
- Activated Carbon Filters:Adsorptive media impregnated with potassium iodide or phosphoric acid for molecular contamination control. Battery gigafactories in China's Yangtze River Delta deploy these for volatile organic compound removal during electrode coating operations.
- Baghouse Filters:Woven or felt fabric sleeves in pulse-jet or reverse-air configurations for particulate capture above 10 microns. EPA PM2.5 enforcement is compressing replacement cycles for legacy installations in US steel and cement plants.
- Electrostatic Filters:Ionization-charged collection plates or wet electrostatic precipitators for sub-micron particulate and acid mist removal. China's MEE enforces GB 13271 upgrades that mandate retrofits in coal-fired boiler stacks.
HEPA filters lead on scale; activated carbon filters lead on momentum.
Application:
Application selection tracks end-product contamination sensitivity, with semiconductor and biologics operations commanding premium pricing tiers unavailable to industrial emissions control.
- Air Purification:Ambient and process air treatment spanning residential units to centralized HVAC systems. South Korea's KOSHA occupational exposure limits are tightening requirements for manufacturing workplace air quality monitoring.
- Water Treatment:Membrane bioreactors, ultrafiltration, and reverse osmosis pre-treatment for process and wastewater applications. Municipal utilities in Germany's Ruhr industrial region prioritize these for PFAS remediation under EU Drinking Water Directive revisions.
- Industrial Processing:Emissions control and product recovery in mining, chemicals, and primary metals production. India's Central Pollution Control Board mandates continuous opacity monitoring for category-I highly polluting industries.
- Cleanroom Technology:Unidirectional airflow systems with HEPA/ULPA ceiling coverage and real-time particle counting. Gujarat and Karnataka fabs under India's PLI scheme are driving ISO 14644-1 certification demand.
Cleanroom technology commands premium margins; industrial processing delivers volume scale.
Technology:
Technology adoption splits between established mechanical separation and emerging real-time analytical instrumentation, with response time requirements determining procurement priority.
- Filtration Systems:Depth and surface media configurations including pleated cartridges, depth filters, and membrane cassettes. Sartorius Group and Merck Millipore dominate single-use biopharmaceutical assemblies that eliminate stainless-steel cleaning validation.
- Optical Monitoring:Light scattering and extinction-based particle counters for continuous cleanroom certification. These displace gravimetric methods in pharmaceutical quality control due to second-resolution data output.
- Laser Diffraction:Angular light scattering for particle size distribution analysis in liquid suspensions and aerosols. Battery electrode slurry manufacturers in Japan's Kansai region specify these for coating uniformity control.
- Mass Spectrometry:Ion mobility and time-of-flight characterization for chemical identity of particulate matter. Research laboratories and CMOs in Switzerland's Basel pharmaceutical cluster deploy these for extractables and leachables testing.
Filtration systems anchor revenue; mass spectrometry delivers steepest expansion trajectory.
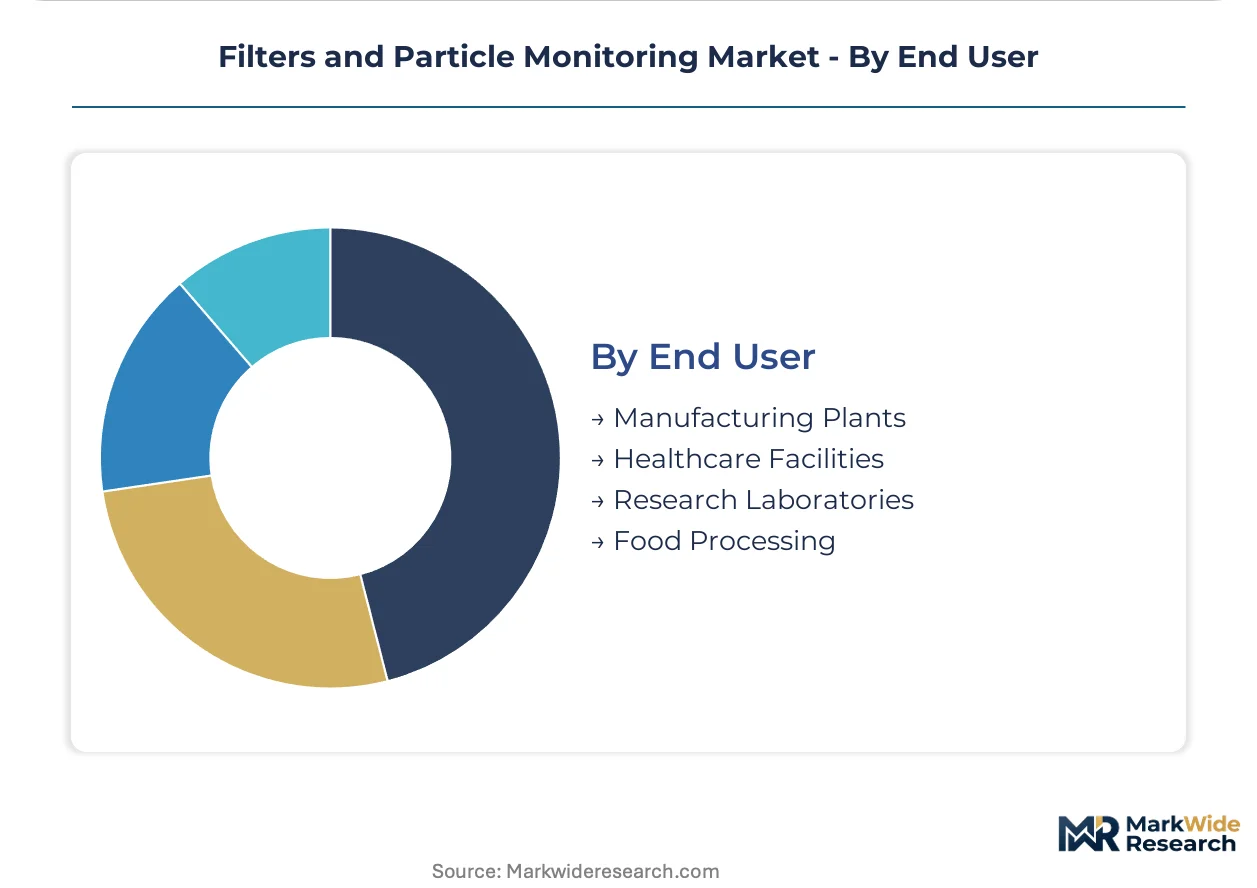
End User:
End-user procurement patterns diverge between centralized engineering departments with capital budgets and decentralized quality teams with operational expenditure authority.
- Manufacturing Plants:Automotive paint shops, semiconductor foundries, and battery electrode coating operations with zero-defect contamination protocols. German OEMs bundle lifecycle service contracts with predictive maintenance analytics to prevent unplanned downtime.
- Healthcare Facilities:Hospital pharmacies, compounding centers, and surgical suites requiring USP <797> and <800> compliance. FDA enforcement of sterile compounding standards is accelerating HEPA upgrade cycles in US health systems.
- Research Laboratories:Academic and government facilities with grant-funded capital equipment procurement. NIH and NSF funding priorities are shifting toward mass spectrometry-based particle characterization for environmental health research.
- Food Processing:Dairy, beverage, and ready-to-eat operations with allergen control and pathogen exclusion requirements. FSSAI's Food Safety and Standards Regulations mandate HACCP-aligned filtration for high-risk product categories in India.
Manufacturing plants dominate absolute spend; healthcare facilities show most consistent replacement velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized aerosol photometer operators and cleanroom certification technicians concentrate in East Asian semiconductor corridors and German industrial regions, creating talent scarcity that constrains facility expansion timelines.
United States
Steel mills in Gary, Indiana and cement plants along the Ohio River are retrofitting electrostatic precipitators as EPA PM2.5 enforcement hardens. The National Ambient Air Quality Standards now mandate continuous opacity monitoring at category-I highly polluting facilities. Houston's petrochemical corridor is installing laser diffraction particle counters to meet tightened refinery emissions benchmarks.
China
Battery gigafactories and biologics plants cluster in the Yangtze River Delta around Shanghai and Suzhou, driving HEPA filter demand for ISO 14644-1 compliance. MEE enforces GB 13271 boiler emission limits that require electrostatic precipitator upgrades in steel and cement operations. Tianjin's pharmaceutical freezers are converting to single-use filtration assemblies to accelerate multi-product changeovers.
Germany
Automotive paint shops in Stuttgart and Wolfsburg bundle lifecycle service contracts with predictive maintenance analytics to prevent contamination-related downtime. The EU Green Deal's industrial emissions benchmarks are recalibrating procurement priorities toward fluoropolymer-free membrane options. BASF's Ludwigshafen complex is piloting mass spectrometry-based particle characterization for extractables testing.
South Korea
Samsung Foundry and SK Hynix are scaling cleanroom investments in Gyeonggi Province as chip sovereignty becomes a national priority. KOSHA occupational exposure limits are tightening workplace air quality monitoring requirements across manufacturing plants. Busan's battery electrode coating operations specify laser diffraction instruments for slurry uniformity control.
India
Gujarat and Karnataka fabs under the PLI scheme for semiconductors are generating demand for ISO 14644-1 Class 3-5 cleanroom infrastructure. FSSAI mandates HACCP-aligned filtration for high-risk food processing categories. Maharashtra's pharmaceutical clusters in Mumbai and Pune are upgrading to single-use biopharmaceutical assemblies to eliminate cross-contamination risk.
Filters and Particle Monitoring Market Competitive Landscape
Capital-heavy membrane producers compete with asset-light instrumentation designers for differentiation in a market splitting between consumable filtration media and analytical hardware. The vendor base organizes around three strategic archetypes: diversified conglomerates with fluoropolymer chemistry depth, specialized filtration fabricators with backward integration into pleated media, and precision instrumentation houses with optical counting expertise. Consolidation pressures concentrate in membrane supply where PTFE production requires chemical industry scale, while particle monitoring remains fragmented across laser diffraction and ion mobility specialists. Dominant competitive moves include captive supply of raw membrane materials and cloud-connected sensor networks that displace distributor channels.
Among diversified technology conglomerates, 3M and Honeywell International Inc exemplify the integrated archetype spanning material science through systems engineering. Donaldson Company, Inc. and Sartorius Group occupy distinct specialization vectors within filtration—heavy-duty industrial dust collection versus single-use biopharmaceutical assemblies. Agilent Technologies, Inc. and Thermo Fisher Scientific represent the precision instrumentation tier where mass spectrometry and optical monitoring converge. TSI Incorporated anchors the particle counting segment with laser-based aerosol detection, while Merck Millipore and Danaher Corporation sit within life science tools portfolios that bundle filtration consumables with analytical workflows.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| 3M |
| Merck Millipore |
| Thermo Fisher Scientific |
| Donaldson Company, Inc. |
| Sartorius Group |
| Honeywell International Inc |
| TSI Incorporated |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
Specialized aerosol photometer operators in Taiwan and South Korea command wage premiums that compress margins at the ISO 14644-1 certification tier while widening spreads between premium HEPA membrane pricing and commodity baghouse fabric tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates PTFE membrane HEPA filters for semiconductor cleanrooms from fiberglass HEPA variants for healthcare, and from commodity baghouse sleeves for industrial emissions. Price differentiation rests on EN 1822 certification grade and captive fluoropolymer supply. Pricing pressure stems from REACH authorization timelines for per- and polyfluoroalkyl substances forcing membrane reformulation costs. Battery gigafactories in China's Yangtze River Delta exhibit highest price sensitivity; pharmaceutical CMOs in Switzerland's Basel cluster show lowest.
Supply Chain Analysis
Direct-to-facility channels handle hyperscale semiconductor foundry demand while distributor networks serve fragmented industrial maintenance procurement. PTFE resin production concentrates in the United States, Japan, and China. Filter media manufacturing draws from fluoropolymer chemistry, borosilicate microfiber, and activated carbon substrate inputs. Single-source vulnerability in PTFE membrane supply creates exposure to chemical conglomerate pricing power. Distribution runs through life science tools distributors for biopharmaceutical accounts and industrial supply houses for heavy manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Filters and Particle Monitoring Market functions as a regulatory compounder where EPA PM2.5 enforcement and EU F-Gas Regulation phase-downs synchronize multi-site upgrade cycles across process industries.
For Market Incumbents: Anticipate fluoropolymer-free membrane substitution by accelerating in-house production of bio-based filter media before REACH authorization deadlines eliminate incumbent chemistry advantages. Defend position by locking long-term service contracts with predictive analytics bundling at German automotive paint shops and South Korean battery coating operations where unplanned downtime costs dwarf filtration spend.
For New Entrants and Emerging Players: India's PLI scheme for semiconductors in Gujarat and Karnataka opens a window for ISO 14644-1 certification services where aerosol photometer operator scarcity constrains incumbent expansion velocity. Target direct-to-facility monitoring-as-a-service models in emissions-intensive Indian process industries bypassing legacy distributor relationships. Lead with cloud-connected sensor networks that automate replacement scheduling.
For Investors and Strategic Acquirers: Life science tools conglomerates are the most active acquirer in this space, consolidating single-use filtration consumables with mass spectrometry analytical workflows. Five-to-ten year viability favors membrane specialists with reformulation capabilities for fluoropolymer-free alternatives. Acquire targets with backward integration into pleated media manufacturing and established pharmaceutical validation dossiers. Watch for EPA enforcement variance across US steel and cement regions as inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pleated Media | Donaldson Company secures input cost control for heavy-duty industrial dust collection systems. |
| Single-Use Filtration Assembly Expansion | Sartorius Group eliminates stainless-steel cleaning validation for multi-product biopharmaceutical facilities. |
| Cloud-Connected Sensor Network Deployment | Equipment OEMs capture recurring revenue through automated replacement scheduling in German automotive paint shops. |
| Fluoropolymer-Free Membrane Reformulation | Membrane suppliers address REACH authorization requirements without sacrificing 0.3-micron retention efficiency. |
| Lifecycle Service Contract Bundling | Predictive maintenance analytics displace transactional spot purchasing in South Korean battery electrode coating operations. |
Research Methodology
Bottom-up cleanroom infrastructure and emissions control modeling reconciled against top-down membrane production and instrumentation shipment tracking forms the analytical core of this study. Primary interviews with cleanroom certification technicians, pharmaceutical quality control directors, industrial plant maintenance managers, and filtration procurement specialists combined with secondary validation from EPA enforcement databases, EU ECHA substance restriction filings, SEC 10-K disclosures from diversified materials conglomerates, and customs trade data for PTFE resin imports. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map HEPA filter demand from semiconductor fab construction pipelines, battery gigafactory cleanroom specifications, and industrial emissions compliance deadlines across the analysis window. Segmentation dimensions include product efficiency tier, application contamination sensitivity, technology response time requirement, and end-user procurement authority structure. CAGRs derive from facility investment cycle modeling and regulatory enforcement timeline probability weighting. Forecast inputs incorporate India's PLI scheme fab construction schedules and China's MEE GB 13271 upgrade mandates.
Revisions become necessary when EPA enforcement variance materializes across US steel regions, when REACH authorization timelines accelerate for per- and polyfluoroalkyl substances, or when fluoropolymer supply disruptions alter membrane pricing trajectories. Forecasts reflect documented assumptions regarding regulatory deadline adherence and facility operator capital allocation priorities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Diatomaceous Filter Aid Market
Filters
Filter Coatings Market
Filters
United States Activated Carbon Market
Filters
Global Filter Market
Filters
Global Tangential Flow Filtration Market
Filters
Filter Bag Market
Filters
Anti-Microbial Filter Market
Filters
Fabric Filters Market
Filters
Sintered Metal Filters Market
Filters
Chloramine Filter Market
Filters
Fabric Filter System Market
Filters
Global Industrial Filters Market
Filters
Nonwoven Air Conditioning Filter Market
Filters
Ceramic Filters Market
Filters
Air Filtration Media Market
Filters
GCC Industrial Air Filtration Market