
 Post-Consumer Recycled Plastics in Consumer Electronics Market | 2026-2036
Post-Consumer Recycled Plastics in Consumer Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Post-Consumer Recycled Plastics in Consumer Electronics Market Intelligence
Green bond financing and sustainability-linked lending is narrowing the capital gap between virgin resin incumbents and recycled material specialists. SABIC leverages its petrochemical infrastructure to secure offtake agreements with major electronics brands. MBA Polymers, Inc. anchors its competitiveness through proprietary sorting and purification systems for complex waste streams. Covestro AG differentiates by integrating chemically recycled polycarbonate into high-performance laptop housings.
Post-consumer recycled plastics in consumer electronics denotes polymers recovered from end-of-life products, reprocessed to meet OEM specifications for flame retardancy, color consistency, and mechanical durability, typically achieving 30-85% recycled content depending on application grade. These materials serve primarily to reduce Scope 3 emissions and satisfy brand sustainability commitments across the device lifecycle. rPET dominates material type segments due to established collection infrastructure and FDA and EFSA food-contact precedents that ease electronics-grade qualification. Injection molding leads manufacturing process adoption because existing tooling requires minimal modification for approved recycled grades, while 3D printing represents the fastest-growing process segment as additive manufacturing firms develop filament formulations with verified recycled content.
The EPA oversees e-waste collection targets in the United States, while the EU Green Deal and Ecodesign for Sustainable Products Regulation mandate minimum recycled content thresholds and digital product passports for electronics sold in Europe. China's MIIT enforces GB standards for recycled plastic quality that directly affect import eligibility and domestic OEM procurement rules. Stakeholders must monitor how rapidly evolving extended producer responsibility schemes alter cost allocation between resin suppliers, contract manufacturers, and brand owners.
Market Dynamics
Binding recycled-content mandates from the EU Ecodesign for Sustainable Products Regulation and China's MIIT are forcing OEMs to requalify supply chains around verified post-consumer feedstocks rather than virgin resins.
Growth Catalysts
- EU Green Deal implementation:Mandatory digital product passports and minimum recycled thresholds for electronics sold in Europe are accelerating supplier audits and material traceability investments across the value chain.
- Smartphone housing specifications:Major device manufacturers are expanding rPET and recycled polycarbonate content in exterior frames to meet Scope 3 reduction targets and brand sustainability commitments.
- Injection molding compatibility:Existing tooling infrastructure requires minimal modification for approved recycled grades, lowering switching costs for contract manufacturers in Germany, China, and the United States.
Market Restraints
- Flame-retardant additive costs:Post-consumer streams require additional brominated or phosphorus-based compounds to meet UL 94 V-0 standards, compressing margins versus virgin resin formulations.
- Collection infrastructure concentration:Quality-assured e-waste feedstock clusters heavily in German and Chinese urban corridors, creating geographic supply vulnerability for North American processors.
- Color consistency limitations:Mixed-waste origins produce batch-to-batch chromatic variation that restricts recycled content in premium device finishes where aesthetic uniformity commands price premiums.
Strategic Opportunities
- India's extended producer responsibility rollout:Draft e-waste rules under the Ministry of Environment are creating first-mover advantages for recyclers establishing domestic purification and compounding capacity ahead of formal mandates.
- Chemical recycling convergence:Pyrolysis and depolymerization technologies are opening electronics-grade output from contaminated or degraded feedstocks previously excluded from mechanical reprocessing routes.
- 3D printing filament channels:Additive manufacturing firms are developing verified recycled-content formulations for prototyping and low-volume production, bypassing traditional injection molding procurement hierarchies.
Industry Challenges
- Spectroscopy technician scarcity:Advanced sorting facilities require operators trained in near-infrared and X-ray fluorescence identification of polymer grades, with certification programs lagging facility expansion timelines.
- OEM qualification cycles:Material validation protocols spanning twelve to eighteen months for flame-retardancy and mechanical durability testing delay revenue recognition for recycled resin suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post-Consumer Recycled Plastics in Consumer Electronics Market |
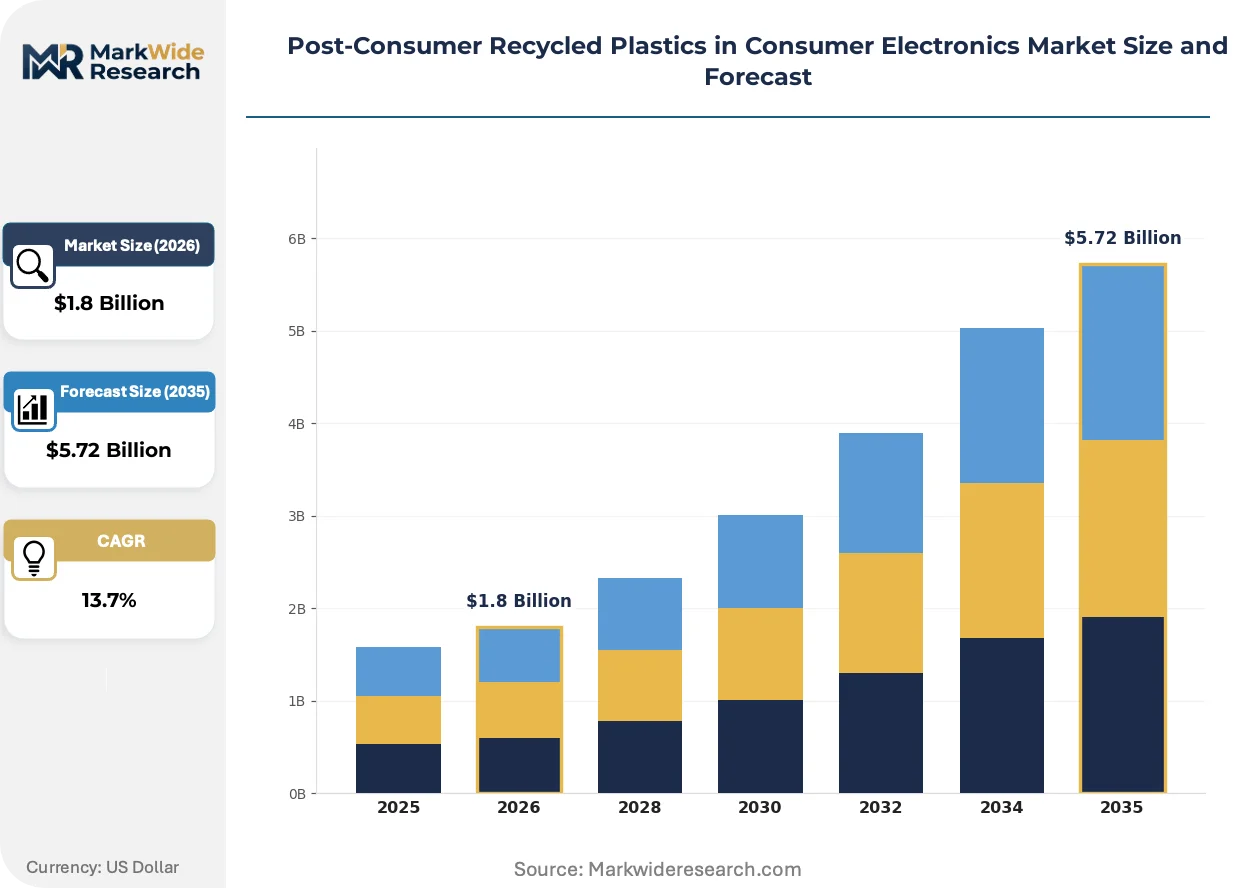
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: rPET, rHDPE, rPP, Bioplastics Product Category: Smartphones, Laptops, Tablets, Wearables Manufacturing Process: Injection Molding, Blow Molding, Extrusion, 3D Printing End User: Consumers, Manufacturers, Retailers, Distributors |
| Companies Covered | Trinseo, INEOS Styrolution Group GmbH, BASF SE, PolyVisions, LAVERGNE, Inc., SABIC, MBA Polymers, Inc., Dow Inc, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post-Consumer Recycled Plastics in Consumer Electronics Market Strategic Shifts & Innovations
Material traceability systems and purification technologies are compressing the performance gap between post-consumer and virgin resins, reshaping how electronics brands contract for sustainable feedstocks.
Advanced spectroscopic sorting systems equipped with artificial intelligence classification are rendering obsolete manual polymer identification and density-separation methods that previously limited throughput and purity. Electronics-focused compounders in Germany and China are deploying these systems at commercial scale. The technology is rendering obsolete first-generation mechanical recycling economics that relied on homogeneous waste streams.
China's MIIT enforcement of revised GB standards for recycled plastic quality is tightening import eligibility criteria and domestic OEM procurement rules simultaneously. Processors must now document chain-of-custody from collection through compounding to maintain supply relationships with major device manufacturers. Laptop and smartphone assemblers operating in Shenzhen and Dongguan are accelerating in-house laboratory investments to pre-validate incoming material certificates.
Brand sustainability officers are consolidating supplier relationships around recyclers offering mass-balance certification and blockchain-tracked provenance documentation. This procurement concentration is displacing spot-market purchasing of unverified recycled claims in favor of multi-year offtake agreements with audited processors. The shift is most visible among United States-based consumer electronics brands targeting California's pending recycled-content disclosure requirements.
Post-Consumer Recycled Plastics in Consumer Electronics Market Segmentation
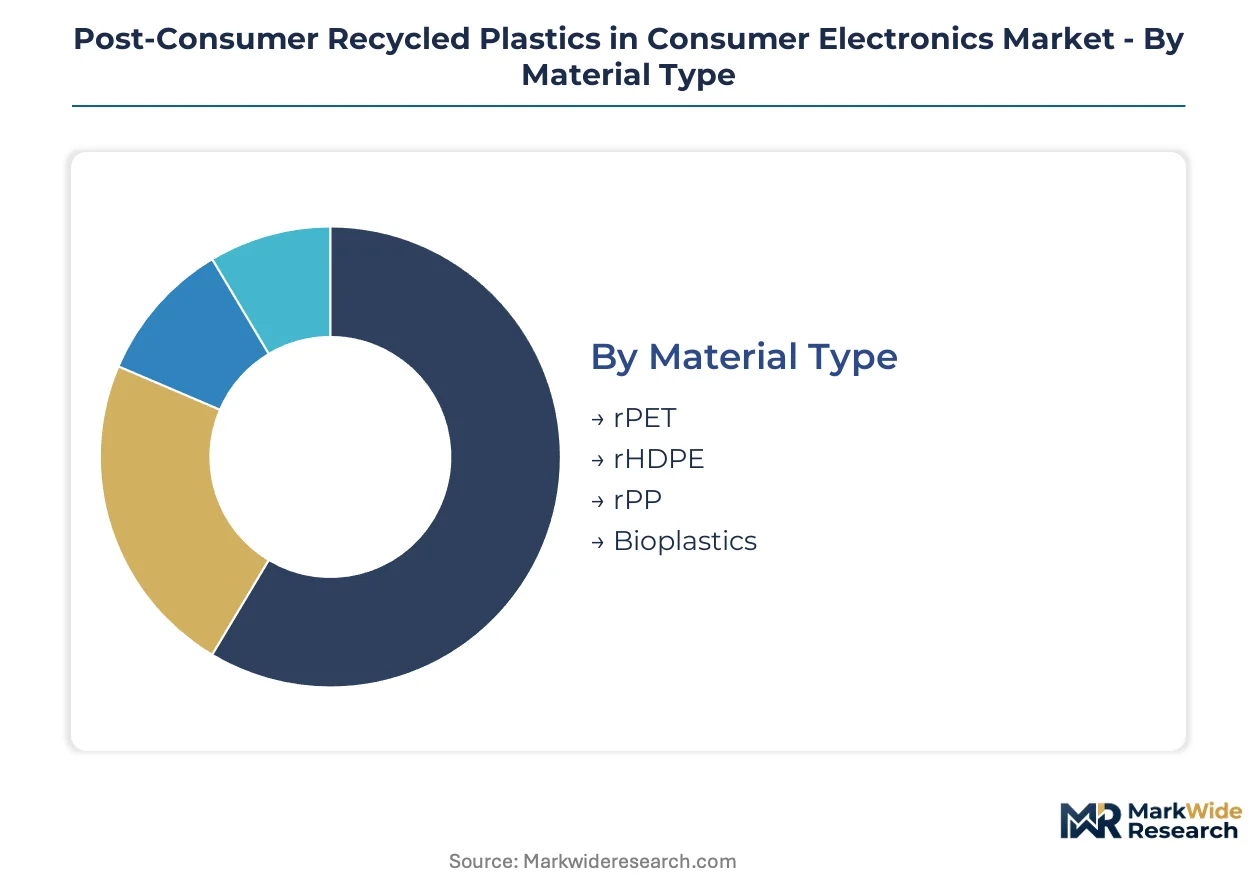
Segmentation in post-consumer recycled plastics for electronics reveals distinct material qualification cycles and manufacturing readiness levels. OEM procurement teams prioritize segments with established certification pathways and compatible tooling infrastructure.
Material Type:
rPET cycles through qualification fastest due to existing food-contact precedents easing electronics-grade approval, while bioplastics face extended validation timelines for flame-retardant compatibility.
- rPET:Dominates material flows through established collection infrastructure and FDA and EFSA food-contact precedents that streamline electronics-grade qualification. Demand concentrates in smartphone housings and laptop frames where OEMs face binding recycled-content mandates from the EU Ecodesign for Sustainable Products Regulation and China's MIIT.
- rHDPE:Serves cable insulation and internal structural components with proven mechanical durability. German and Chinese processors anchor supply relationships through mass-balance certification and blockchain-tracked provenance documentation.
- rPP:Targets internal brackets and non-structural housings where color consistency requirements are less stringent. Compounders leverage proprietary sorting systems to secure multi-year offtake agreements.
- Bioplastics:Faces extended OEM qualification cycles spanning twelve to eighteen months for flame-retardancy validation under UL 94 standards. Limited commercial deployment concentrates in premium device finishes where brand sustainability commitments justify material premiums.
rPET dominates installed base. Bioplastics represent where expansion concentrates despite qualification friction.
Product Category:
Volume scale separates high-unit categories from emerging form factors, with procurement concentration tracking replacement cycle frequency and housing material intensity.
- Smartphones:Highest unit volumes and shortest replacement cycles drive rPET and recycled polycarbonate integration in exterior frames. Shenzhen and Dongguan assemblers accelerate in-house laboratory investments to pre-validate incoming material certificates under China's revised GB standards.
- Laptops:Larger surface areas per unit increase material intensity, with Covestro AG chemically recycled polycarbonate qualifying for high-performance housings. California's pending recycled-content disclosure requirements shape procurement for United States-bound brands.
- Tablets:Moderate volumes with premium positioning constraints limit recycled content in aesthetic-critical finishes. Batch-to-batch chromatic variation from mixed-waste origins restricts adoption in top-tier product lines.
- Wearables:Miniaturization and skin-contact requirements impose additional biocompatibility testing beyond standard flame-retardancy protocols. First-mover recyclers are establishing domestic purification capacity ahead of India's formal extended producer responsibility mandates.
Smartphones generate the steepest volume trajectory. Laptops concentrate margin capture through material intensity.
Manufacturing Process:
Tooling modification requirements create switching cost tiers, separating incumbent-compatible methods from emerging additive routes.
- Injection Molding:Existing infrastructure requires minimal modification for approved recycled grades, lowering barriers for contract manufacturers in Germany, China, and the United States. This process anchors current procurement hierarchies through proven flame-retardant additive integration.
- 3D Printing:Additive manufacturing firms develop filament formulations with verified recycled content, bypassing traditional injection molding supply chains for prototyping and low-volume production. This segment climbs the fastest as equipment manufacturers qualify recycled-content inputs.
- Blow Molding:Serves hollow structural components and packaging elements with established processing parameters for rHDPE streams. Limited electronics penetration outside cable management and protective casing applications.
- Extrusion:Processes continuous profiles for cable jacketing and frame edging with consistent cross-sectional requirements. German urban corridor processors concentrate quality-assured feedstock supply for this method.
Injection Molding holds the largest operational footprint. 3D Printing captures the steepest expansion trajectory through qualification of recycled-content filaments.
End User:
Procurement authority and sustainability target ownership determine segment access, with brand-level mandates cascading through contract manufacturer specifications.
- Manufacturers:Contract assemblers in Shenzhen, Dongguan, and German industrial corridors execute OEM material specifications under binding recycled-content thresholds. These entities validate incoming certificates through accelerated in-house laboratory investments.
- Consumers:End purchasers drive brand sustainability commitments that translate into procurement mandates, though direct material specification authority remains limited. California disclosure requirements and EU digital product passports increase visibility into recycled content claims.
- Retailers:Electronics retailers in the United States and Europe increasingly require sustainability documentation for shelf placement, exerting indirect pressure on upstream material selection.
- Distributors:Wholesale channels aggregate demand across smaller OEMs with limited direct recycler relationships, relying on spot-market purchasing displaced by multi-year offtake agreements.
Manufacturers control specification authority. Consumers concentrate demand signaling through brand preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OEM procurement teams concentrate in three national markets where recycled-content mandates and e-waste collection infrastructure intersect most densely. Contract manufacturers in these territories face binding compliance deadlines that compress supplier qualification timelines.
Germany
Automotive and electronics OEMs in Bavaria and North Rhine-Westphalia drive rPET and rPP demand for laptop housings and internal brackets. The EU Ecodesign for Sustainable Products Regulation mandates digital product passports and minimum recycled thresholds, forcing recyclers in the Rhine-Ruhr urban corridor to deploy AI-equipped spectroscopic sorting systems at commercial scale.
China
Shenzhen and Dongguan assemblers specify post-consumer resins for smartphone frames and tablet housings under Scope 3 reduction commitments. MIIT enforcement of revised GB standards tightens import eligibility and domestic procurement rules simultaneously, compelling processors to document chain-of-custody from collection through compounding.
United States
California's pending recycled-content disclosure requirements shape procurement for consumer electronics brands headquartered in Silicon Valley and Seattle. The EPA oversees e-waste collection targets nationally, while contract manufacturers in Texas and the Midwest validate incoming material certificates through accelerated in-house laboratory investments.
India
Draft e-waste rules under the Ministry of Environment are creating first-mover advantages for recyclers establishing purification capacity in Maharashtra and Karnataka ahead of formal extended producer responsibility mandates. Domestic smartphone assembly growth in Tamil Nadu concentrates demand for rHDPE cable insulation and rPP internal structural components.
Japan
METI guidelines on circular material procurement drive electronics manufacturers in the Kanto and Kansai regions to requalify supply chains around verified post-consumer feedstocks. Osaka-based compounders leverage mass-balance certification to secure multi-year offtake agreements with laptop and camera OEMs.
Post-Consumer Recycled Plastics in Consumer Electronics Market Key Industry Players
Channel-controlling players compete with product-specialist players across three discernible tiers. Petrochemical conglomerates with captive resin infrastructure anchor the upper tier through backward integration into collection networks. Mid-scale compounders occupy a middle tier through proprietary purification systems that command premium pricing for electronics-grade output. Regional processors fill a lower tier through spot-market supply of unverified recycled claims. Dominant competitive moves include capacity expansion in German and Chinese urban corridors and strategic partnerships between resin suppliers and contract manufacturers seeking multi-year offtake security.
Within the petrochemical-backed tier, SABIC, BASF SE, and Dow Inc exemplify archetypes leveraging existing infrastructure to secure brand relationships. SABIC represents the Middle Eastern-origin conglomerate with downstream plastics operations. BASF SE anchors the European chemical-major position through Ludwigshafen-based compounding capabilities. Dow Inc occupies the North American integrated-resin-supplier role with Midland, Michigan operational heritage. These entities sit within a competitive structure where mass-balance certification and blockchain-tracked provenance documentation increasingly determine procurement access.
| Leading Market Players |
|---|
| Trinseo |
| INEOS Styrolution Group GmbH |
| BASF SE |
| PolyVisions |
| LAVERGNE, Inc. |
| SABIC |
| MBA Polymers, Inc. |
| Dow Inc |
| Covestro AG |
| Others |
Cost & Logistics Intelligence
Single-source dependency on German and Chinese urban corridor processors determines both pricing tier spreads and supply chain shape, as quality-assured e-waste feedstock concentration in the Rhine-Ruhr and Shenzhen-Dongguan clusters creates procurement bottlenecks that compress margins for North American compounders while elevating premiums for mass-balance-certified output.
Pricing Analysis
Cost-plus contracts indexed to virgin resin benchmarks dominate procurement between electronics OEMs and recycled resin suppliers, with price differentiation resting on UL 94 flame-retardancy certification tier and blockchain-tracked provenance documentation. Three-tier pricing structure across premium, standard, and economy levels separates mass-balance-certified grades from spot-market unverified claims. Cost compression in standard-tier rPET is intensifying because brominated additive expenses outpace virgin resin fluctuations. Contract manufacturers in Shenzhen exhibit highest price sensitivity due to thin assembly margins, while German laptop OEMs absorb premiums for aesthetic-grade recycled polycarbonate.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for compounders serving California-bound electronics brands, forcing qualification of alternative Southeast Asian purification capacity. Supply concentrates in Germany, China, and the United States for quality-assured feedstock, with raw material dependencies on post-consumer e-waste collection networks, flame-retardant additive packages, and spectroscopic sorting equipment. Single-source vulnerability in German AI-equipped sorting technology creates chokepoint risk for processors scaling electronics-grade output. Distribution runs through multi-year offtake agreements with audited processors, displacing spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign for Sustainable Products Regulation's binding recycled-content thresholds constitute a technological-regulatory inflection that transforms post-consumer recycled plastics from niche procurement to mandatory specification, compressing supplier qualification timelines and consolidating procurement around verified mass-balance-certified processors.
For Market Incumbents: Entrench competitive position through backward integration into collection networks in German and Chinese urban corridors, securing captive e-waste feedstock against emerging chemical recycling entrants. Accelerate in-house laboratory investments for pre-validation of incoming material certificates under China's revised GB standards to compress OEM qualification cycles. Prioritize mass-balance certification and blockchain-tracked provenance documentation as procurement access requirements tighten.
For New Entrants and Emerging Players: Build out purification and compounding capacity in Maharashtra and Karnataka ahead of India's formal extended producer responsibility mandates, capturing first-mover advantage in a market where domestic smartphone assembly growth concentrates demand for rHDPE cable insulation. Target 3D printing filament channels for prototyping and low-volume production, bypassing traditional injection molding procurement hierarchies dominated by established compounders. Deploy direct-to-OEM technical sales teams emphasizing rapid qualification support.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-scale compounders with proprietary AI-equipped spectroscopic sorting systems and existing mass-balance certification. Long-term viability over the next decade rests on processors capable of documenting chain-of-custody from collection through compounding under tightening EU and Chinese regulatory frameworks. The signal to watch is MIIT enforcement actions against processors failing revised GB standards, which will accelerate procurement concentration around audited suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | SABIC and petrochemical incumbents secure captive e-waste feedstock against emerging chemical recycling competitors in German urban corridors. |
| Mass-Balance Certification Investment | Processors document chain-of-custody to maintain supply relationships with major device manufacturers under EU digital product passport requirements. |
| AI-Equipped Spectroscopic Sorting Deployment | German compounders replace manual polymer identification with throughput-scaling systems that render first-generation mechanical recycling economics obsolete. |
| Long-Term Offtake Agreement Structuring | Brand sustainability officers displace spot-market purchasing with multi-year contracts securing verified recycled-content supply for Scope 3 reduction targets. |
| Chemical Recycling Capacity Buildout | Pyrolysis and depolymerization technologies open electronics-grade output from contaminated feedstocks previously excluded from mechanical reprocessing routes. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings in this analysis. The research team conducted structured discussions with sustainability officers at consumer electronics OEMs, procurement leads at contract manufacturers in Shenzhen and Dongguan, technical directors at recycled resin compounders, regulatory affairs specialists tracking EU Ecodesign implementation, and laboratory validation managers at German processing facilities. Secondary validation drew from MIIT GB standard filings, EU Ecodesign regulatory impact assessments, EPA e-waste collection databases, SEC 10-K disclosures from petrochemical conglomerates, and mass-balance certification registries. Bottom-up and top-down triangulation reconciled processor capacity estimates with OEM procurement volume projections.
Calibration against historical qualification cycle timelines and regulatory implementation phases shaped the analytical framework across the projection horizon. The model segmented by material type, product category, manufacturing process, and end-user procurement authority, with additional dimensioning by regional regulatory cluster to capture EU, Chinese, and United States mandate differential impacts. CAGRs derived from fitted growth curves incorporating OEM recycled-content commitment disclosures and e-waste collection infrastructure expansion trajectories. Industry-specific forecast inputs included flame-retardant additive cost curves and spectroscopic sorting equipment deployment rates in German and Chinese urban corridors.
Sensitivities concentrate around MIIT enforcement intensity against GB standard violations, EU digital product passport implementation speed, and California recycled-content disclosure requirement finalization. Forecasts reflect assumptions regarding OEM qualification cycle compression and chemical recycling technology cost-down trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
USA Plastic-To-Fuel Market
Recycled Plastics
Recycled PET Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Recycled Carbon Fiber Market
Recycled Plastics
Global Recycled Base Oil Market
Recycled Plastics
Recycled Leather Market
Recycled Plastics
Vietnam Recycling Market
Recycled Plastics
Polyvinyl Chloride (PVC) Market
Recycled Plastics
Foam Plastics Market
Recycled Plastics
Global Recycled Asphalt Market
Recycled Plastics
US Recycled Plastics Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Global Recycled Plastics Market
Recycled Plastics
China Plastics Market