
 Topical Wound Agents Market | 2026-2036
Topical Wound Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Topical Wound Agents Market Outlook
Bioresorbable polymer integration into hydrogel matrices is rewriting manufacturing standards for moisture-retentive dressings. Smith & Nephew plc leverages its end-to-end wound care portfolio to anchor positions across acute and chronic settings. Mölnlycke Health Care AB sustains competitive differentiation through specialized silicone-adhesive technologies that minimize trauma during dressing changes. Johnson & Johnson Services, Inc. dominates hospital procurement channels through extensive surgical wound care franchises.
Topical wound agents comprise pharmaceutical and device-grade formulations applied directly to dermal lesions to prevent infection, maintain physiologic moisture balance, and accelerate re-epithelialization; hydrogel variants typically contain 90% water cross-linked with polyethylene oxide or carboxymethyl cellulose to enable autolytic debridement. Chronic wound therapy areas command substantial clinical attention due to prolonged treatment cycles and recurring reimbursement, while surgical wound applications benefit from standardized procedural volumes and predictable formulary placement. Infection control applications lead absolute demand as antimicrobial resistance intensifies prophylactic protocol rigor across hospitals and long-term care facilities.
FDA 510(k) premarket notifications govern combination product classifications, while the EU Medical Device Regulation imposes clinical evidence requirements that reshape market access timelines for hydrogel and foam dressings. ISO 10993 biocompatibility testing standards determine material eligibility for sustained dermal contact, directly influencing formulation chemistry decisions by manufacturers. Stakeholders must monitor evolving reimbursement banding for home care wound management as payors scrutinize cost-per-healed-episode metrics against institutional alternatives.
Market Dynamics
FDA's streamlined 510(k) pathways for combination wound products are compressing development timelines while EU MDR clinical evidence requirements simultaneously extend market access durations, creating divergent regulatory velocity across major jurisdictions.
Growth Catalysts
- Antimicrobial resistance protocols:Hospital infection control mandates in the United States intensify prophylactic dressing deployment. Acute care facilities now standardize silver-ion and PHMB-impregnated formulations across surgical and trauma wards.
- Japan's super-aging demographic:Diabetes prevalence above 7.5 million cases elevates chronic wound incidence. Pressure ulcer management consumes substantial long-term care budgets, driving sustained demand for advanced moisture-retentive therapies.
- Bioresorbable polymer integration:Hydrogel matrices incorporating polylactic-co-glycolic acid enable controlled active release without dressing removal. Manufacturers reformulate carboxymethyl cellulose backbones to accommodate enzymatic degradation timelines.
Market Restraints
- Petrochemical input volatility:Polyethylene oxide and silicone adhesive feedstocks fluctuate with crude oil derivatives. Dressing manufacturers absorb margin compression or pass costs to constrained hospital procurement budgets.
- EU MDR transition friction:Clinical evidence requirements for Class IIa and IIb wound dressings extend notified body review timelines. Small and mid-sized manufacturers face certificate gaps during conformity assessment backlogs.
- Autolytic debridement substitution:Enzymatic debriding agents and biosynthetic skin substitutes capture select chronic wound cases. Hydrogel dressings defend position through pain reduction and exudate management superiority.
Strategic Opportunities
- Home care reimbursement expansion:Germany's structured disease management programs for diabetes mellitus extend dressing coverage to outpatient settings. Payers evaluate cost-per-healed-episode metrics against institutional alternatives.
- Digital wound monitoring convergence:Smartphone-enabled imaging and AI-powered tissue assessment integrate with dressing change protocols. Telehealth platforms in the United States incorporate remote wound documentation for rural patient populations.
- Bioactive agent incorporation:Platelet-derived growth factors and collagen peptides embed within hydrogel architectures. Regenerative medicine applications target stalled chronic wounds unresponsive to standard moisture-retentive therapy.
Industry Challenges
- ISO 10993 biocompatibility testing bottlenecks:Cytotoxicity and sensitization studies for novel polymer formulations extend qualification timelines. Contract research organization capacity constraints delay material validation for sustained dermal contact.
- Legacy EHR integration complexity:Wound documentation modules in hospital information systems require custom API development for connected dressing technologies. IT security protocols obstruct real-time biometric data transmission from embedded sensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Topical Wound Agents Market |
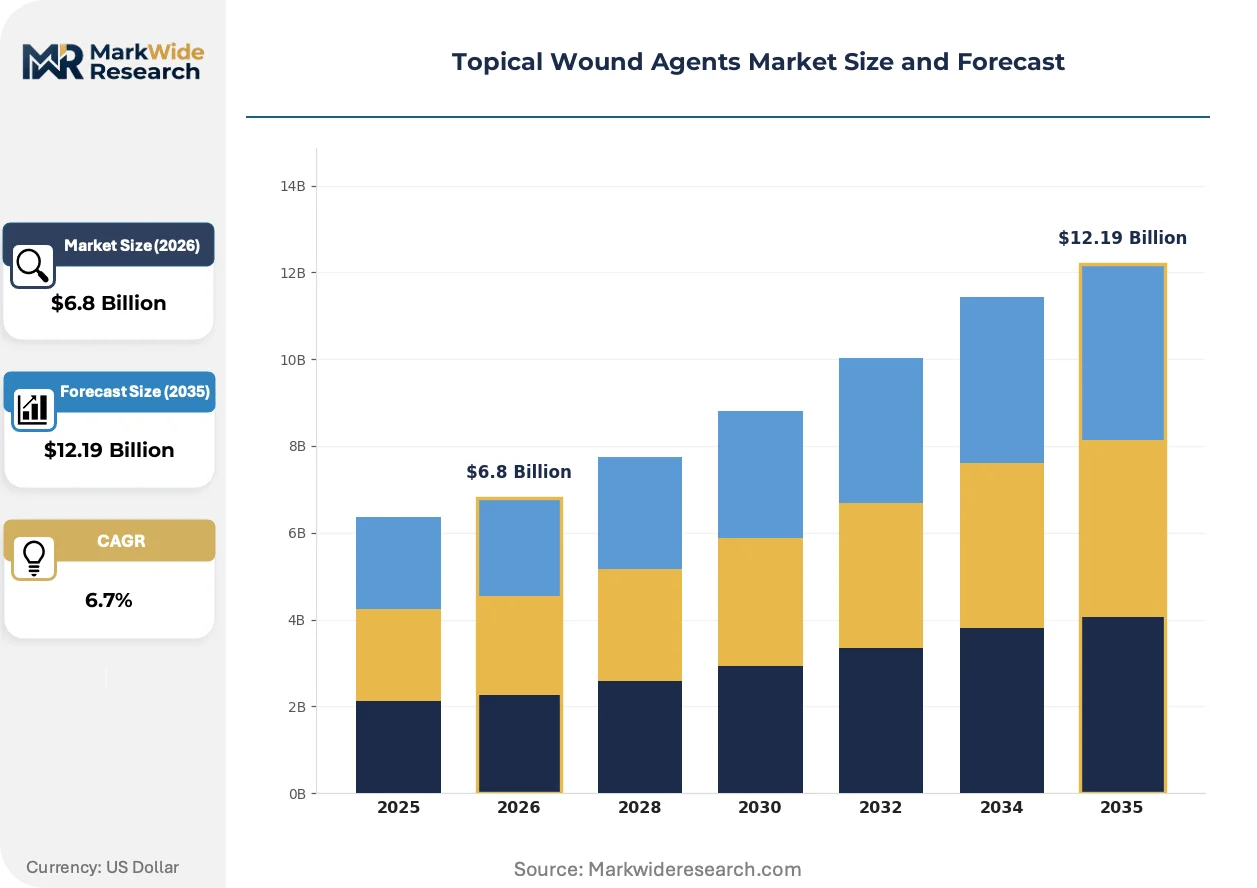
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiseptics, Dressings, Hydrogels, Foams Therapy Area: Chronic Wounds, Surgical Wounds, Burn Care, Diabetic Ulcers End User: Hospitals, Home Care, Clinics, Long-term Care Facilities Application: Infection Control, Healing Promotion, Pain Management, Moisture Retention |
| Companies Covered | Smith & Nephew plc, 3M Company, Mölnlycke Health Care AB, ConvaTec Group plc, Coloplast A/S, Johnson & Johnson Services, Inc., Paul Hartmann AG, Becton, Dickinson and Company, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Topical Wound Agents Market Strategic Shifts
Digital health integration and bioactive material science are redefining therapeutic dressing functionality beyond passive moisture management, shifting competitive advantage toward data-enabled care coordination and tissue regeneration support.
Electrospun nanofiber scaffolds is virtualizing the structural foundation of moisture-retentive dressings. Polyvinyl alcohol and polycaprolactone nanofibers achieve 90% porosity with sub-micron fiber diameters, enabling superior exudate wicking and breathability. Academic medical centers in Germany and Japan pilot these architectures for burn and donor site applications. The technology is virtualizing manufacturing investment requirements by reducing solvent processing steps and enabling roll-to-roll continuous production.
EU MDR Article 117 and associated implementing acts impose clinical performance requirements on wound dressings with ancillary medicinal substances. Manufacturers must generate clinical data equivalent to pharmaceutical benchmarks for antimicrobial and analgesic claims. Hydrogel-foam combination products face the steepest evidence burden. German and French notified bodies prioritize reviews for legacy products with established clinical histories, disadvantaging novel entrants.
Hospital procurement consolidation concentrates purchasing authority within integrated delivery networks. Group purchasing organizations in the United States aggregate demand across multi-hospital systems, compressing supplier margins through volume-commitment contracting. Standardized formularies displace individual physician preference items. This concentration is most visible in the southeastern and midwestern United States, where Catholic health initiatives and for-profit chains dominate acute care bed capacity.
Topical Wound Agents Market Segmentation
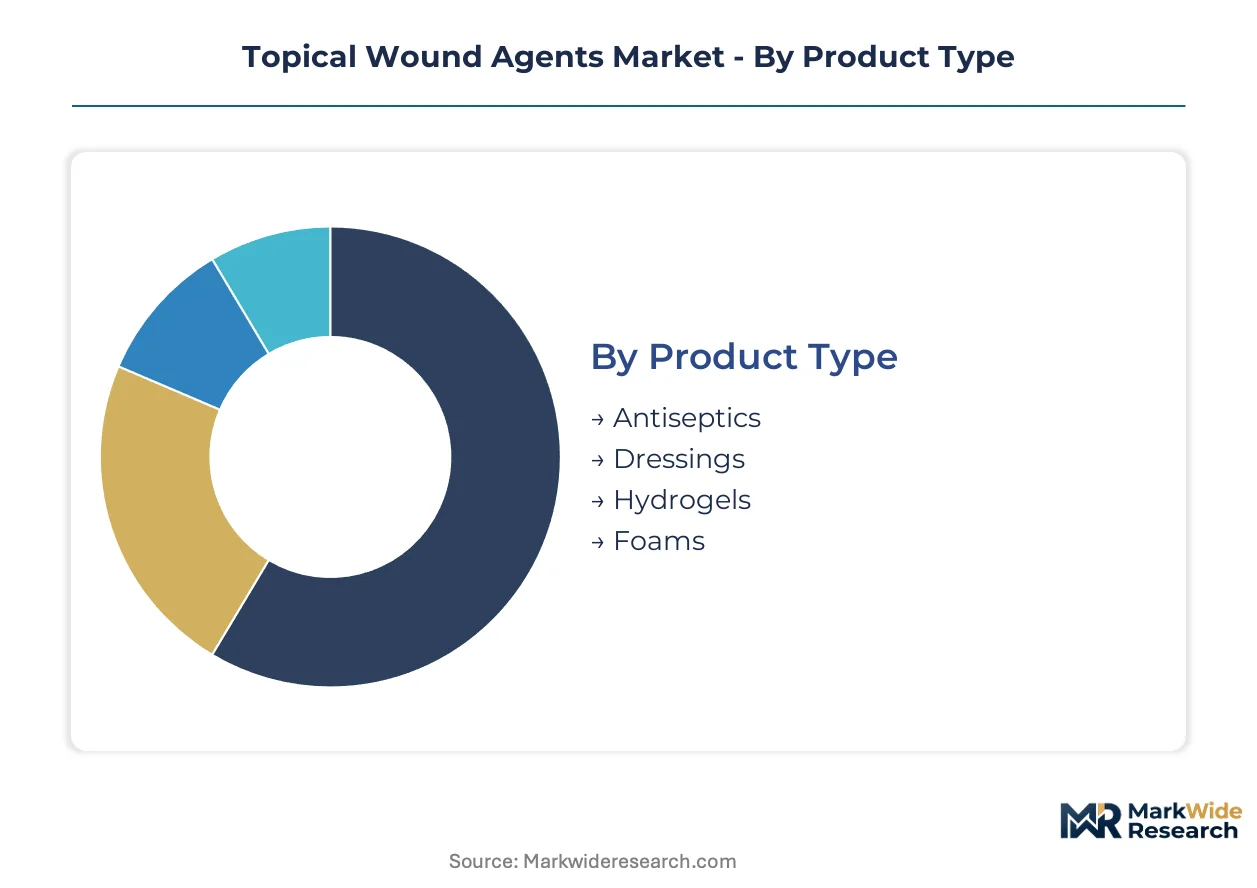
Wound care procurement decisions fragment across clinical setting hierarchies, reimbursement banding, and material performance specifications. Manufacturers must align formulation chemistry with specific therapy area protocols rather than pursuing undifferentiated market presence.
Product Type:
Cost tier differentiation separates commodity antiseptics from advanced polymer matrices commanding premium formulary placement.
- Dressings:Silicone-adhesive and foam-backed variants dominate hospital procurement through trauma and post-operative protocols. Acute care facilities in the United States and Germany standardize these across surgical wards as infection control mandates intensify.
- Hydrogels:Cross-linked polyethylene oxide and carboxymethyl cellulose matrices enable autolytic debridement while maintaining physiologic moisture balance. Japan's long-term care facilities deploy these extensively for pressure ulcer management amid super-aging demographic pressures.
- Antiseptics:Iodine and chlorhexidine formulations serve prophylactic protocols in resource-constrained settings.
- Foams:Polyurethane absorbent layers manage moderate-to-heavy exudate in chronic wound cases.
Dressings hold installed capacity. Hydrogels are rotating up the share rankings.
Therapy Area:
Application severity determines reimbursement eligibility and product qualification requirements across jurisdictions.
- Chronic Wounds:Venous leg ulcers and pressure injuries require sustained moisture-retentive therapy over extended treatment cycles. Germany's structured disease management programs extend coverage to outpatient settings, elevating demand for advanced dressing technologies.
- Diabetic Ulcers:Neuropathic lesions in diabetic populations drive specialized growth factor and antimicrobial formulations. Japan's diabetes prevalence above 7.5 million cases concentrates clinical attention on limb preservation protocols.
- Surgical Wounds:Standardized procedural volumes enable predictable formulary placement and volume contracting.
- Burn Care:Specialized centers require biosynthetic and silver-impregnated formulations for thermal injury management.
Chronic wounds hold installed capacity. Diabetic ulcers are climbing the fastest.
End User:
Customer type dictates purchasing authority concentration and technical support requirements.
- Hospitals:Integrated delivery networks and group purchasing organizations aggregate demand across multi-hospital systems. The southeastern and midwestern United States exhibit pronounced procurement consolidation through Catholic health initiatives and for-profit chains.
- Home Care:Telehealth platform integration and remote wound documentation expand addressable populations. Rural patient access programs in the United States incorporate smartphone-enabled imaging with dressing change protocols.
- Clinics:Outpatient wound centers balance cost constraints with clinical outcome accountability.
- Long-term Care Facilities:Pressure ulcer prevention protocols drive recurring demand for moisture-retentive therapies.
Hospitals hold installed capacity. Home care is gaining share fastest.
Application:
Functional purpose determines regulatory pathway selection and clinical evidence requirements.
- Infection Control:Silver-ion and PHMB-impregnated formulations address antimicrobial resistance protocols in acute care settings. FDA 510(k) premarket notifications govern combination product classifications for these antimicrobial claims.
- Healing Promotion:Bioactive agent incorporation targets stalled wounds unresponsive to standard moisture-retentive therapy. Platelet-derived growth factors and collagen peptides embed within hydrogel architectures for regenerative applications.
- Moisture Retention:Passive moisture balance maintenance serves foundational wound bed preparation.
- Pain Management:Analgesic-impregnated dressings reduce dressing change trauma in sensitive patient populations.
Infection control holds installed capacity. Healing promotion is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hydrogel manufacturers export advanced moisture-retentive dressings to Japan's long-term care networks, while US-based suppliers feed hospital procurement channels across North American integrated delivery systems.
United States
Hospital infection control mandates intensify silver-ion dressing deployment across surgical and trauma wards. FDA 510(k) premarket notifications govern combination product classifications for antimicrobial claims. The southeastern and midwestern states exhibit pronounced procurement consolidation through Catholic health initiatives and for-profit chains.
Germany
Structured disease management programs for diabetes mellitus extend advanced dressing coverage to outpatient settings. EU MDR Article 117 imposes clinical performance requirements on wound dressings with ancillary medicinal substances. The Baden-Württemberg and North Rhine-Westphalia clusters concentrate electrospun nanofiber R&D for burn applications.
Japan
Diabetes prevalence above 7.5 million cases elevates chronic wound incidence in long-term care facilities. METI coordinates industrial policy supporting domestic medical device manufacturing. The Kanto region around Tokyo anchors pressure ulcer management protocol development for super-aging demographic pressures.
United Kingdom
NHS procurement frameworks standardize formulary placement for post-operative wound care across acute trusts. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with EU MDR equivalence principles. The Oxford-Cambridge corridor hosts biosynthetic skin substitute development programs.
India
CDSCO medical device rules classify advanced wound dressings under risk-based frameworks accelerating market access. The Maharashtra and Gujarat pharmaceutical corridors expand contract manufacturing for hydrogel and foam dressing exports. Domestic hospital chains in Delhi-NCR and Bangalore pilot antimicrobial dressing protocols for surgical site infection reduction.
Topical Wound Agents Market Competitive Environment
On the supply side, the industry is consolidating around integrated wound care portfolios that span acute and chronic therapy settings. Three archetypes dominate competitive positioning: diversified medical device conglomerates with surgical franchise depth, specialized wound care pure-plays with silicone-adhesive differentiation, and pharmaceutical-device hybrids pursuing combination product pathways. Capacity expansion and strategic portfolio diversification represent the dominant competitive moves as manufacturers respond to divergent FDA and EU MDR regulatory velocities.
Within the diversified conglomerate tier, Johnson & Johnson Services, Inc. and 3M Company exemplify scale-driven positioning through extensive hospital procurement channel access. Smith & Nephew plc occupies a specialized position spanning end-to-end wound care portfolios across acute and chronic settings. These three anchors illustrate how competitive advantage increasingly derives from regulatory navigation capability and formulary integration depth rather than single-product differentiation.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| 3M Company |
| Mölnlycke Health Care AB |
| ConvaTec Group plc |
| Coloplast A/S |
| Johnson & Johnson Services, Inc. |
| Paul Hartmann AG |
| Becton, Dickinson and Company |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese hydrogel polymer production is compressing feedstock margins and forcing European dressing manufacturers into aggressive procurement postures. This utilization imbalance simultaneously depresses spot prices for carboxymethyl cellulose while elevating long-term contract premiums for medical-grade polyethylene oxide.
Pricing Analysis
Technology-generation pricing gaps separate legacy silicone-adhesive dressings from next-generation electrospun nanofiber architectures and prior-generation gauze-based products. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 certification tier and volume scale. Pricing pressure stems from petrochemical input volatility as crude oil derivatives fluctuate. Hospital procurement committees exhibit highest price sensitivity through GPO-aggregated volume commitments, while burn centers demonstrate lowest sensitivity due to clinical outcome prioritization.
Supply Chain Analysis
EU dual-use export controls on advanced polymer processing equipment constrain technology transfer to emerging manufacturing hubs. Supply concentrates in Germany for silicone-adhesive technologies, the United States for antimicrobial formulations, and Japan for pressure-ulcer-specific hydrogels. Raw material dependencies include polyethylene oxide, medical-grade silicones, and silver-ion precursors. Single-source vulnerability characterizes electrospun nanofiber scaffold production. Distribution runs through hospital group purchasing organizations and specialized wound care distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital wound monitoring platforms are creating platform-economics inflection as smartphone-enabled imaging and AI-powered tissue assessment integrate with dressing protocols, requiring interoperability across telehealth infrastructure.
For Market Incumbents: Pre-empt biosynthetic skin substitute encroachment by embedding platelet-derived growth factors within hydrogel architectures. Deepen backward integration into bioresorbable polymer production to secure polylactic-co-glycolic acid supply. Lock hospital procurement channels through EHR-integrated wound documentation modules.
For New Entrants and Emerging Players: Establish a beachhead in Germany's outpatient diabetes disease management programs where reimbursement expansion creates white-space opportunity. Target rural US telehealth wound care through smartphone-enabled imaging partnerships. Pursue FDA 510(k) clearance for combination antimicrobial-hydrogel products as fastest regulatory pathway.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electrospun nanofiber manufacturing as roll-to-roll continuous production equipment demands scale investment. Long-term viability favors specialized wound care pure-plays with silicone-adhesive differentiation over commodity antiseptic producers. Watch EU MDR notified body backlog resolution as inflection signal for novel entrant market access timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates antimicrobial combination product clearance through streamlined premarket notification pathways. |
| CE Marking Pathway | EU MDR Article 117 compliance enables hydrogel-foam combination product access to German outpatient markets. |
| Hospital System Partnership | Integrated delivery network contracts secure formulary placement across southeastern US Catholic health initiatives. |
| Software Companion Development | AI-powered tissue assessment integration addresses rural patient access programs through telehealth platforms. |
| Reimbursement Strategy | Germany's structured disease management programs for diabetes extend coverage to home care wound management. |
Study Parameters
Desk research of FDA 510(k) premarket notification databases, EU MDR technical documentation, and hospital procurement contract filings preceded structured interviews with wound care clinicians, biomedical engineers, GPO contracts managers, and regulatory affairs leads. Secondary validation drew from ISO 10993 biocompatibility testing standards, CMS Medicare reimbursement schedules, and METI industrial policy coordination documents. Bottom-up demand modeling and top-down market sizing triangulated across these inputs.
Assumptions held fixed include FDA regulatory pathway stability and EU MDR implementation timelines, while variables included antimicrobial resistance protocol intensity and home care reimbursement expansion rates. Segmentation dimensions encompassed product type, therapy area, end user, and application function across the analysis window. CAGRs derived from patient population epidemiology, procedural volume trajectories, and pricing elasticity modeling for chronic versus acute wound settings.
Stress conditions across petrochemical input volatility, notified body capacity constraints, and digital health platform adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Material shifts in EU MDR clinical evidence requirements or FDA combination product classification guidance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Maggot Debridement Market
Wound Care
Global Wound Irrigation System Market
Wound Care
Animal Wound Care Market
Wound Care
Bioactive Wound Management Market
Wound Care
Global Silver Wound Dressing Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Single-Use Negative Pressure Wound Therapy Devices Market
Wound Care
Wound Irrigation Devices Market
Wound Care
Pressure Ulcer Treatment Market
Wound Care
Wound Skin Care Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Wound Debridement Products Market
Wound Care
Bioadhesive Wound Care Market
Wound Care
Wound Care Centers Market
Wound Care
Wound Closure Market