
 Skin Grafting System Market | 2026-2036
Skin Grafting System Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Grafting System Market Analytics
Market Context
Multi-source procurement for biological graft materials is restructuring how hospital systems evaluate vendor portfolios. Smith & Nephew leverages its integrated wound management platform to anchor long-term supply agreements with tier-one burn centers. Zimmer Biomet competes through orthopedic-derived tissue processing capabilities that extend into reconstructive applications. Integra LifeSciences specializes in dermal regeneration matrices, occupying a defensible position in complex wound protocols.
Technical Definition and Segment Structure
A skin grafting system encompasses the instruments, consumables, and biologic materials used to transplant skin tissue onto wound beds, with modern platforms integrating pneumatic dermatome blades operating at 3,500–6,000 RPM for controlled thickness harvesting between 0.15–0.40 mm. Autografts command the largest revenue share due to permanent engraftment and minimal immunogenic response, though dermal substitutes are recording the fastest expansion as acellular matrices reduce donor site morbidity. Hospitals dominate end-user demand through centralized procurement of capital equipment and recurring biologic supplies, while ambulatory surgical centers are gaining share as outpatient burn and wound procedures migrate from inpatient settings.
Regulatory Framework
The FDA regulates skin grafting systems as Class II medical devices under 21 CFR Part 878, while biological graft materials face additional Center for Biologics Evaluation and Review oversight for human cell and tissue-based products. The EU Medical Device Regulation imposes stricter clinical evidence requirements for dermal substitutes, extending conformity assessment timelines for manufacturers seeking CE marking. Stakeholders must monitor evolving reimbursement pathways for bioengineered skin substitutes as Medicare and private payors recalibrate coverage determinations around clinical efficacy thresholds.
Market Dynamics
Consolidation of wound care supply contracts within integrated health networks is concentrating purchasing power and forcing vendors to bundle capital equipment with recurring biologic consumables, reshaping how procurement teams evaluate total cost of ownership across multi-year agreements.
Growth Catalysts
- Outpatient procedure migration:Ambulatory surgical centers in the United States are expanding capacity for burn and wound interventions previously confined to inpatient settings, driving demand for compact harvesting platforms.
- 21 CFR Part 820 updates:The FDA's revised quality system regulation is accelerating validation timelines for biological graft materials, creating competitive advantage for manufacturers with pre-validated manufacturing processes.
- Acellular matrix advancement:Dermal substitutes derived from processed cadaveric or xenogeneic tissue are reducing donor site morbidity and expanding treatable patient populations beyond autograft limitations.
Market Restraints
- Biological material input volatility:Supply of human allograft tissue depends on donor network expansion rates and recovery protocols that vary by procurement organization.
- EU MDR conformity timelines:The Medical Device Regulation's stricter clinical evidence requirements are extending CE marking assessment periods for dermal substitute manufacturers.
- Reimbursement compression:Medicare coverage determinations for bioengineered skin substitutes remain contested, creating payment uncertainty for hospital wound care programs.
Strategic Opportunities
- India's hospital infrastructure expansion:Private burn center construction in tier-two cities is creating first-mover advantage for automated dermatome platform suppliers.
- 3D bioprinting convergence:Integration of cell-laden bioinks with automated harvesting systems promises patient-specific graft geometry matched to wound topography.
- Japan's regenerative medicine framework:The PMDA's conditional approval pathway for tissue-engineered products is accelerating market access for novel dermal regeneration matrices.
Industry Challenges
- Specialized technician scarcity:Burn centers face recruitment gaps for dermatome operators trained in precise thickness calibration across variable anatomical sites.
- Legacy EMR integration:Automated harvesting platforms must interface with hospital information systems that lack standardized data fields for graft tracking and outcomes documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Grafting System Market |
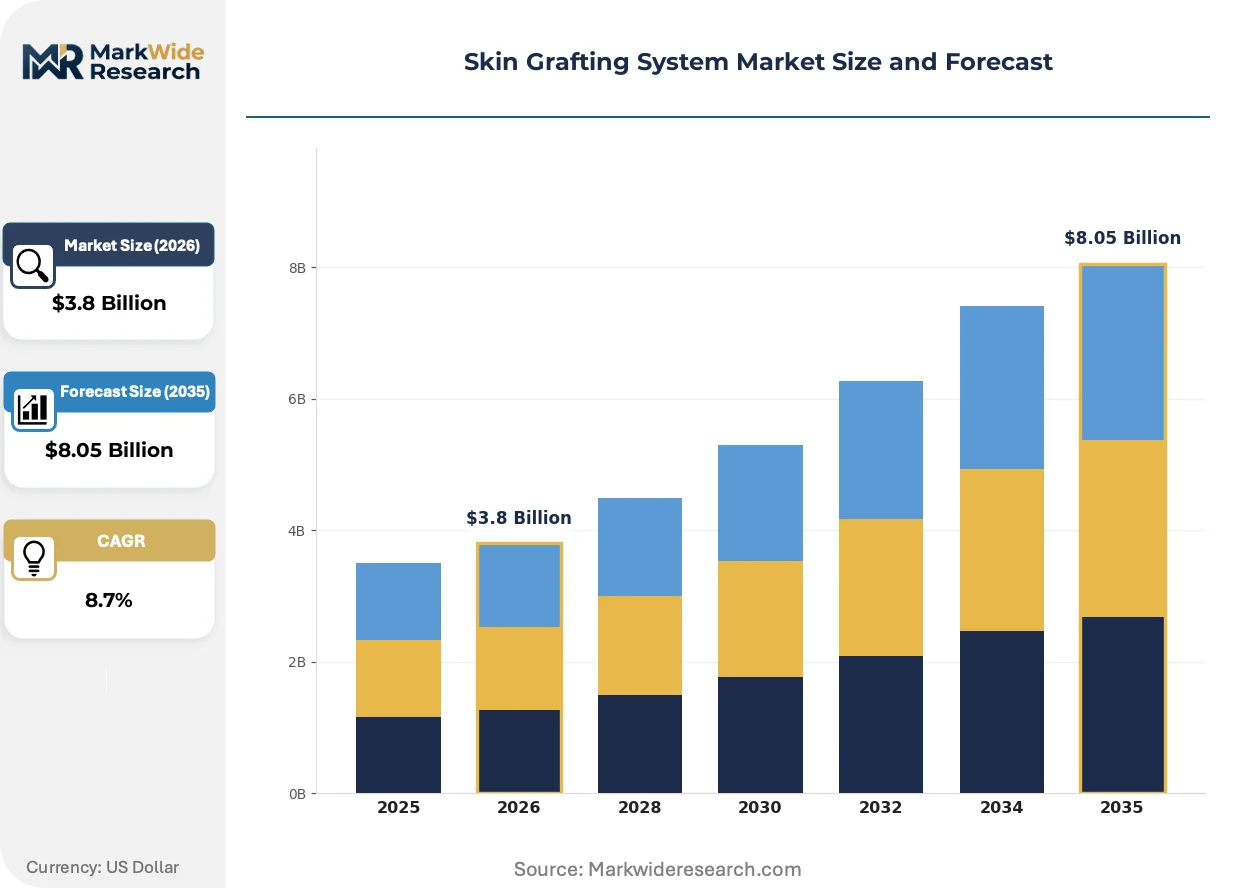
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dermal Substitutes, Autografts, Allografts, Xenografts Application: Burn Treatment, Chronic Wounds, Surgical Procedures, Cosmetic Surgery Material: Biological Materials, Synthetic Polymers, Natural Polymers, Composite Materials End User: Hospitals, Clinics, Ambulatory Surgical Centers, Homecare Settings |
| Companies Covered | Smith & Nephew, De Soutter Medical, Zimmer Biomet, Aygun Surgical Instruments, Exsurco Medical, Stryker, B. Braun, Johnson & Johnson, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Grafting System Market Evolving Landscape
Pneumatic dermatome platforms are incorporating real-time thickness feedback sensors that eliminate manual calibration variability, while regulatory bodies on three continents are tightening evidence standards for biological graft claims.
Robotic-assisted harvesting systems are absorbing precision control functions previously dependent on operator experience, reducing thickness variability in split-thickness grafts. Tier-one burn centers in the United States are piloting these platforms for large surface area burns where manual harvesting introduces unacceptable donor site trauma. The technology is absorbing mid-volume procedure share from conventional air-driven dermatomes by standardizing outcomes across operator skill levels.
The EU Medical Device Regulation's clinical evidence requirements are extending conformity assessment timelines for dermal substitutes seeking CE marking. Manufacturers must now generate prospective data on engraftment rates and scarring outcomes that exceed legacy predicate device equivalence standards. Small and mid-cap tissue processors face capital constraints for building compliant clinical programs, favoring larger entities with established European notified body relationships.
Integrated health networks are unbundling capital equipment procurement from biologic supply agreements, creating separate vendor relationships for hardware and consumables. Hospital systems in the United States are negotiating three-to-five-year biologic supply contracts with volume guarantees while leasing harvesting platforms through independent equipment finance arrangements. This bifurcation is most visible in consolidated networks spanning multiple states, where centralized procurement teams seek pricing transparency across previously siloed purchasing decisions.
Skin Grafting System Market Segmentation
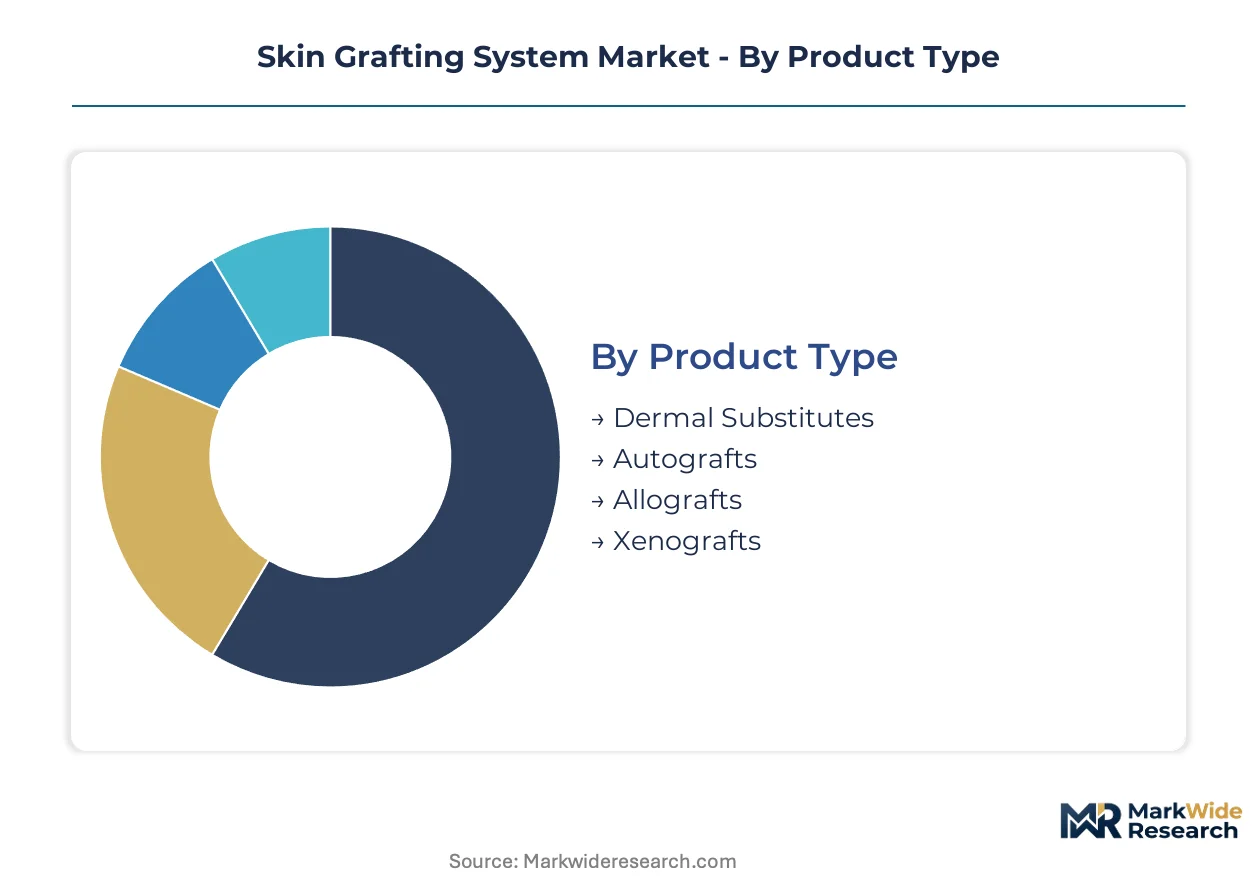
Procurement teams evaluate skin grafting systems through multiple lenses, balancing clinical outcomes against total cost of ownership across hardware lifecycles and recurring biologic consumables. Segmentation reveals where purchasing power concentrates and which technology platforms command premium positioning.
Product Type:
Upgrade cycles for harvesting equipment accelerate when adjacent biologic categories demonstrate superior engraftment metrics, reshaping capital allocation priorities across burn center capital budgets.
- Dermal Substitutes:Acellular matrices derived from processed cadaveric or xenogeneic tissue eliminate donor site morbidity entirely. Demand clusters in United States integrated health networks where Medicare coverage determinations for bioengineered products are contested but expanding.
- Autografts:Split-thickness and full-thickness grafts harvested via pneumatic dermatome at 3,500–6,000 RPM remain the clinical gold standard for permanent engraftment. United States tier-one burn centers anchor procurement volumes despite operator skill dependencies.
- Allografts:Cadaveric skin serves as temporary biological dressings for massive burns where autograft donor sites are insufficient.
- Xenografts:Porcine-derived products offer cost-advantaged temporary coverage for partial-thickness burns in resource-constrained settings.
Volume placements concentrate in Autografts; the faster expansion belongs to Dermal Substitutes.
Application:
Cost tier differentiation separates emergency burn interventions from elective reconstructive procedures, with reimbursement pathways determining technology selection.
- Burn Treatment:Massive surface area injuries exceeding 50% total body surface area demand staged grafting protocols combining temporary biological dressings with permanent autografts. United States trauma centers drive capital equipment procurement for automated harvesting platforms.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers resistant to standard care represent the fastest-expanding indication for bioengineered skin substitutes. Medicare Advantage plans in the United States are recalibrating prior authorization requirements around clinical efficacy thresholds.
- Surgical Procedures:Oncologic resections and trauma closures utilize split-thickness grafts for primary wound coverage.
- Cosmetic Surgery:Elective scar revision and aesthetic resurfacing command premium pricing for ultra-thin grafts.
Volume placements concentrate in Burn Treatment; the steepest expansion trajectory belongs to Chronic Wounds.
Material:
Application-specific requirements dictate material selection, with biological products commanding price premiums over synthetic alternatives in complex wound protocols.
- Biological Materials:Human allograft and autograft tissues provide native extracellular matrix architecture that supports cellular infiltration and vascularization. FDA Center for Biologics Evaluation and Review oversight extends validation timelines for manufacturers.
- Synthetic Polymers:Silicone and polyurethane constructs offer standardized manufacturing with reduced supply volatility compared to donor-dependent biological inputs.
- Natural Polymers:Collagen and chitosan matrices derived from marine or bovine sources bridge biological and synthetic categories.
- Composite Materials:Hybrid constructs combining synthetic scaffolds with biological coatings aim to capture performance advantages of both material classes.
Volume placements concentrate in Biological Materials; the fastest gain in share belongs to Composite Materials.
End User:
Customer type determines procurement modality, with centralized hospital purchasing contrasting against decentralized ambulatory site decision-making.
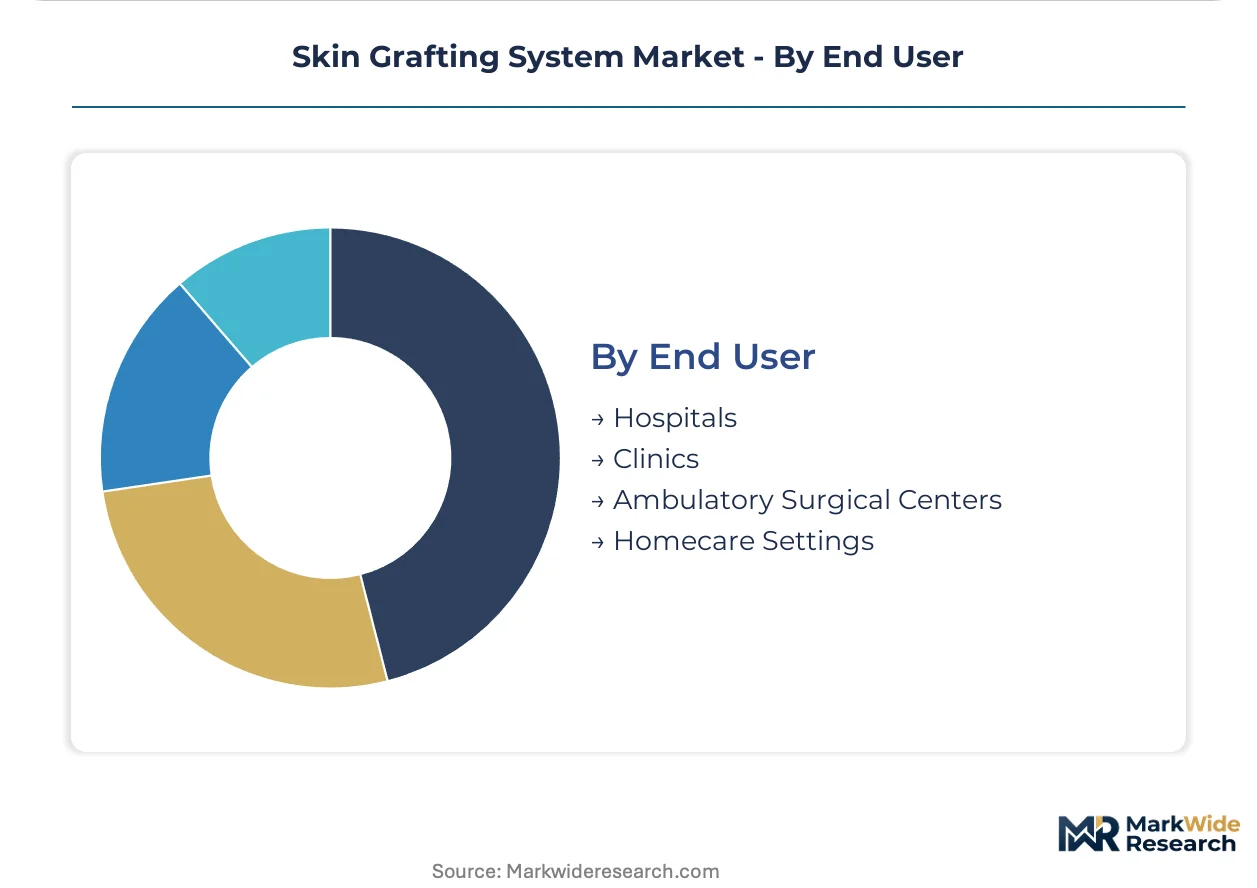
- Hospitals:Tier-one burn centers and academic medical centers dominate capital equipment procurement through multi-year lease arrangements bundled with biologic supply contracts. United States integrated health networks are consolidating wound care purchasing across state boundaries.
- Ambulatory Surgical Centers:Outpatient migration for partial-thickness burn and wound procedures drives demand for compact, portable harvesting platforms with reduced footprint.
- Clinics:Wound care clinics in United States metropolitan areas are expanding capacity for grafting procedures previously confined to hospital settings.
- Homecare Settings:Advanced dressings and negative pressure wound therapy systems enable post-acute monitoring outside institutional settings.
Volume placements concentrate in Hospitals; the most rapid expansion belongs to Ambulatory Surgical Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Human allograft tissue procurement networks in the United States anchor geographic demand concentration, with cadaveric skin recovery organization density determining regional supply availability for burn center clusters.
United States
Tier-one burn centers in Texas, Arizona, and Florida drive automated dermatome platform procurement through consolidated health network contracts. FDA 21 CFR Part 820 quality system updates accelerate validation timelines for biological graft manufacturers. The Dallas-Fort Worth metroplex anchors a dense cluster of tissue processing facilities serving southwestern trauma centers.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia anchor dermal substitute adoption for chronic wound protocols. EU Medical Device Regulation clinical evidence requirements extend CE marking timelines for matrix manufacturers. The Munich-Stuttgart corridor concentrates orthopedic-derived tissue processing capabilities extending into reconstructive applications.
Japan
Conditional approval pathways under PMDA's regenerative medicine framework accelerate market access for novel dermal matrices. Burn centers in Kanto and Kansai regions pilot robotic-assisted harvesting systems for standardized split-thickness grafts. Osaka-based research hospitals collaborate with bioink developers on 3D bioprinting convergence for patient-specific graft geometry.
India
Private burn center construction in tier-two cities creates first-mover opportunity for automated platform suppliers. CDSCO medical device registration requirements shape import timelines for capital equipment and biological materials. Hyderabad and Chennai emerge as hubs for cost-advantaged dermis processing serving domestic and export markets.
Brazil
Public hospital burn unit modernization in São Paulo and Rio de Janeiro states drives demand for pneumatic harvesting systems. ANVISA medical device conformity assessment timelines influence procurement planning for imported platforms. The São Paulo metropolitan region concentrates reconstructive surgery capacity serving Latin American referral networks.
Skin Grafting System Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and tissue processing infrastructure. Market structure tilts toward consolidation among integrated wound management platforms, with mid-cap specialists occupying niche positions in automated harvesting technology. Three archetypes dominate: diversified medical technology conglomerates with wound care divisions, orthopedic-focused tissue processors extending into reconstructive applications, and pure-play dermatome manufacturers with precision instrument expertise. Competitive moves concentrate on bundling capital equipment with biologic supply contracts and securing pre-validated manufacturing processes ahead of FDA quality system deadlines.
Within the diversified technology tier, Smith & Nephew and Stryker exemplify integrated platform strategies that anchor long-term supply agreements with tier-one burn centers. Zimmer Biomet occupies a position bridging orthopedic tissue processing and reconstructive wound care applications. Among precision instrument specialists, De Soutter Medical and Aygun Surgical Instruments represent regional fabrication expertise serving price-sensitive procurement segments. Integra LifeSciences sits within the biological materials tier, specializing in dermal regeneration matrices for complex wound protocols.
| Leading Market Players |
|---|
| Smith & Nephew |
| De Soutter Medical |
| Zimmer Biomet |
| Aygun Surgical Instruments |
| Exsurco Medical |
| Stryker |
| B. Braun |
| Johnson & Johnson |
| Integra LifeSciences |
| Others |
Value Network & Pricing Analysis
Robotic-assisted harvesting platforms are simultaneously compressing per-procedure labor costs and concentrating procurement leverage among tier-one burn centers with capital deployment capacity. This technology transition rewards integrated health networks that can amortize equipment across high-volume sites while squeezing standalone facilities into rental or leasing arrangements with less favorable unit economics.
Pricing Analysis
Service bundling separates vendors who wrap multi-year preventive maintenance and operator training into capital leases from those offering bare equipment with à la carte support. Three-tier pricing structure across premium, standard, and economy levels tracks FDA validation status and CE marking completeness, with pre-validated biological materials commanding substantial premiums. Cost compression in the economy tier is intensifying because mid-cap tissue processors lack capital for compliant clinical programs. Ambulatory surgical centers exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize engraftment metrics over acquisition cost.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan maintain hub-and-spoke patterns for temperature-sensitive biological materials with strict cold-chain protocols. Human allograft tissue draws from donor network expansion rates that vary by procurement organization density. Single-source vulnerability concentrates in cadaveric skin recovery organizations serving multiple burn centers within catchment areas. Distribution runs through hospital system central warehouses for capital equipment and direct-to-site cold chain for perishable biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into tissue processing capabilities to secure pre-validated manufacturing pipelines ahead of FDA quality system deadlines.
For Market Incumbents: Cement long-term supply agreements with tier-one burn centers by bundling robotic harvesting platforms with guaranteed biologic consumable volumes. Counter emerging pure-play dermatome manufacturers by acquiring regional tissue processors with established donor networks. Prioritize in-house production of acellular matrices to reduce dependency on third-party allograft suppliers. For New Entrants and Emerging Players: Ambulatory surgical center networks represent the most penetrable channel partner type for compact, portable harvesting platforms with reduced footprint. Target India's tier-two city private burn centers where first-mover advantage remains available for automated platform suppliers. Pursue software companion development for EMR integration as a differentiated go-to-market angle against legacy equipment vendors. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical technology conglomerates seeking wound care platform consolidation. Long-term viability hinges on regulatory compliance infrastructure rather than product innovation alone. Watch FDA warning letter frequency against biological graft manufacturers as an inflection indicator for competitive shakeout timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21 CFR Part 820 Compliance Investment | Pre-validated manufacturing processes create competitive moats against smaller tissue processors facing capital constraints. |
| Hospital System Partnership | Multi-year biologic supply contracts with volume guarantees anchor recurring revenue streams across consolidated networks. |
| CE Marking Pathway | EU MDR clinical evidence requirements favor larger entities with established European notified body relationships. |
| Software Companion Development | EMR integration capabilities resolve legacy data field gaps for graft tracking and outcomes documentation. |
| Reimbursement Strategy | Medicare coverage determination alignment determines payment certainty for hospital wound care programs. |
Research Methodology
Multi-period observation of dermatome platform procurement volumes, biological graft engraftment rates, and burn center capacity expansion anchored the trend analysis, supplemented by interviews with burn surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, CMS Medicare coverage determinations, hospital procurement databases, and EU notified body conformity assessment records. Bottom-up segment sizing triangulated against top-down health expenditure flows.
Segment-weighting across product type, application, material, and end user dimensions fed into growth rate derivation through the projection horizon. CAGRs were computed from modeled annual progression rather than endpoint approximation. Forecast inputs incorporated outpatient procedure migration rates, robotic platform adoption curves, and biological donor network expansion trajectories specific to burn care.
Caveats apply where Medicare reimbursement recalibration, EU MDR enforcement intensity, or 3D bioprinting technological breakthrough could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Sun-Care Wipes Market
Skincare
Skin Boosters Market
Skincare
Incontinence Skin Care Products Market
Skincare
Pseudo Collagen Market
Skincare
Cosmeceutical Ingredients Market
Skincare
Preoperative Skin Preparation Market
Skincare
Mineral Sunscreen Market
Skincare
Facial Skincare Market
Skincare
Skin Toner Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
Organic Skincare Products Market
Skincare
Professional Skin Care Market
Skincare
Ultrasound Skin Cleaners Market
Skincare
United Kingdom Skincare Market
Skincare
Skincare Serums Market
Skincare
Acne Treatment Market