
 Wound Measurement Devices Market | 2026-2036
Wound Measurement Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Measurement Devices Market Outlook
Silicon photonics is expanding into optical sensor architectures for wound measurement, displacing legacy CMOS-based imaging modules in premium device tiers. Stryker leverages its hospital supply chain scale to bundle measurement hardware with surgical navigation ecosystems. MolecuLight Inc. differentiates through fluorescence imaging specialization for bacterial load detection. ARANZ Medical Limited anchors its position in 3D wound surface mapping for diabetic foot ulcer protocols.
Wound measurement devices quantify tissue dimensions, depth, and surface area using structured light projection, stereo photogrammetry, or time-of-flight laser scanning with sub-millimeter precision. These instruments enable objective tracking of healing trajectories and support reimbursement documentation for chronic wound management programs. Digital devices and image analysis systems command the dominant revenue share due to software subscription attach rates and interoperability mandates with electronic health records. 3D imaging technology represents the fastest-expanding segment as clinicians demand volumetric data for pressure injury staging and flap monitoring decisions.
FDA 510(k) clearance requirements govern software-as-medical-device classifications for automated wound segmentation algorithms in the United States, while the EU MDR imposes clinical evidence thresholds for optical diagnostic claims in Europe. HIPAA compliance obligations and GDPR data localization rules constrain cloud-based image storage architectures, forcing vendors to maintain regional server infrastructure. Stakeholders must monitor evolving predicate device equivalence standards as artificial intelligence modules proliferate in next-generation platforms.
Market Dynamics
Silicon photonics architectures are displacing legacy CMOS imaging modules across premium wound measurement tiers, forcing incumbent hardware vendors to requalify optical sensor supply chains or cede high-margin hospital contracts to specialized component suppliers.
Growth Catalysts
- EU MDR clinical evidence thresholds:Stricter documentation requirements for optical diagnostic claims are filtering out marginal competitors and consolidating procurement decisions around established 3D imaging platforms with predicate device histories.
- Integrated EHR mandates:United States hospital systems are prioritizing connected measurement devices with native HL7 interoperability, pulling capital allocation toward vendors with certified health information exchange modules.
- Fluorescence imaging specialization:Bacterial load detection protocols for diabetic foot ulcers are creating dedicated reimbursement codes that favor purpose-built optical sensors over generalist wound cameras.
Market Restraints
- Regional server infrastructure costs:GDPR data localization rules and HIPAA cloud storage constraints force vendors to maintain redundant compute clusters across three or more jurisdictions, elevating operating overhead for SaaS-enabled platforms.
- Silicon photonics component concentration:Advanced optical sensor fabrication depends on a narrow base of specialty foundries concentrated in East Asia, exposing hardware margins to single-source supply risk.
- Time-of-flight module power requirements:Battery-operated handheld devices face thermal management limitations that compress measurement session duration in point-of-care settings without tethered power.
Strategic Opportunities
- Home health penetration gaps:Post-acute care settings in Germany and France remain underserved by connected wound assessment tools, presenting first-mover advantage for platforms with simplified user interfaces and cellular data transmission.
- AI-enabled segmentation algorithms:Automated wound boundary detection software qualifies for FDA 510(k) clearance under software-as-medical-device pathways, creating recurring revenue attach rates distinct from hardware sales cycles.
- Volumetric data integration:Pressure injury staging protocols are expanding to require depth-based tissue classification, opening substitution opportunities against legacy 2D photography systems in long-term care facilities.
Industry Challenges
- Predicate device equivalence navigation:FDA clearance pathways for AI-augmented platforms require extensive clinical validation against manually segmented reference standards, extending time-to-market by 18-24 months for algorithm-heavy submissions.
- Legacy EHR interoperability friction:Hospital procurement committees are rejecting measurement devices without native integration into Cerner or Epic workflows, forcing retrofit engineering cycles for established hardware vendors.
- Optical calibration skill scarcity:Structured light projection systems require trained biomedical technicians for field recalibration, constraining deployment velocity in rural health networks with limited service infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Measurement Devices Market |
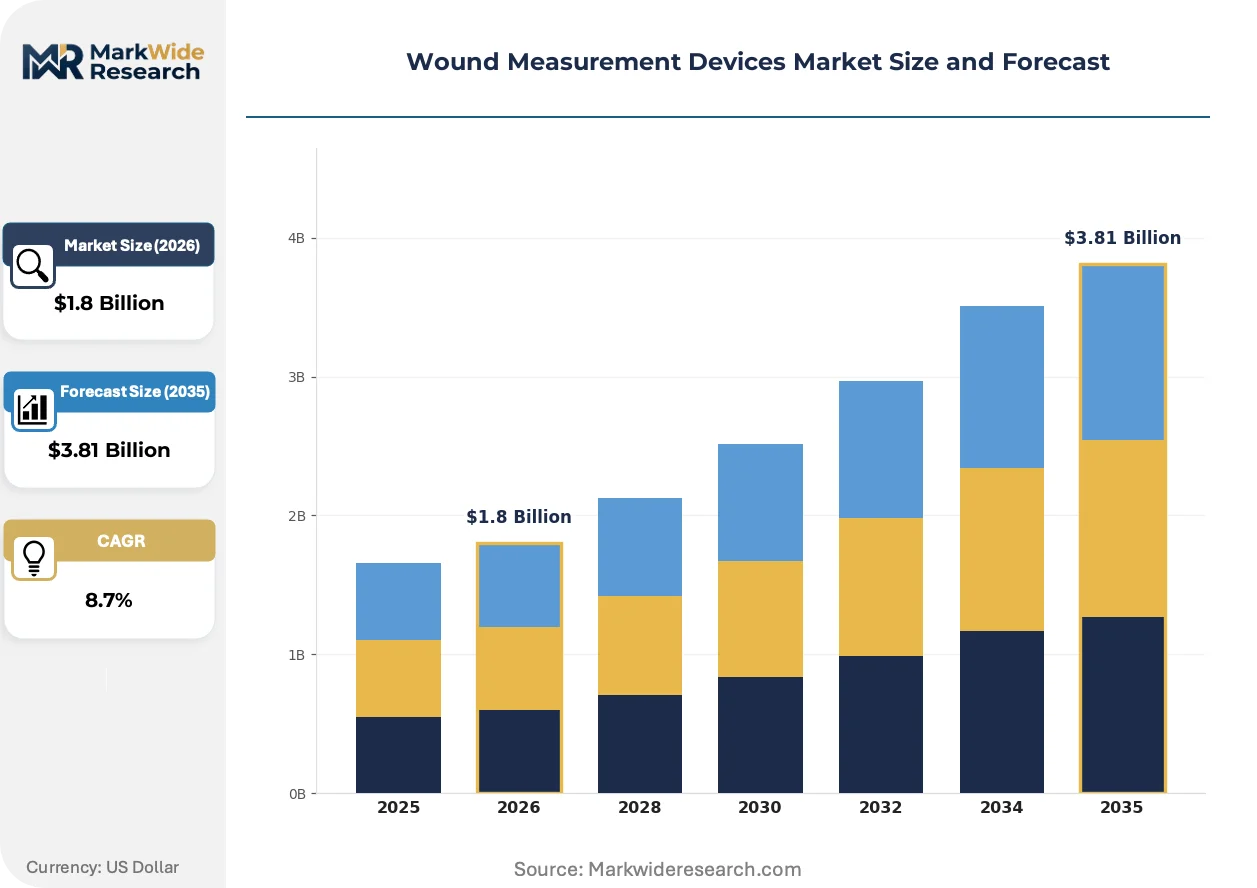
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Devices, Manual Devices, Image Analysis Systems, Optical Sensors End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Technology: Ultrasonic Technology, Laser Technology, Infrared Technology, 3D Imaging Application: Chronic Wounds, Surgical Wounds, Traumatic Wounds, Burns |
| Companies Covered | ARANZ Medical Limited, MolecuLight Inc., Swift Medical Inc., Net Health, Kent Imaging Inc., eKare Inc., WoundVision LLC, Wound Matrix Inc., Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Measurement Devices Market Strategic Shifts
Computational imaging pipelines are fragmenting traditional hardware value capture, embedding diagnostic intelligence directly into sensor firmware and compressing the boundary between optical acquisition and clinical decision support.
Structured light projection with embedded edge inference is decentralizing wound assessment from centralized radiology departments to bedside nursing workflows. Community hospitals in the United States are piloting these systems for pressure injury documentation, eliminating the 24-48 hour lag between image capture and specialist interpretation. This shift is compressing healing trajectory documentation cycles and accelerating reimbursement claim submission timelines.
FDA 510(k) software-as-medical-device classifications are tightening equivalence standards for automated segmentation algorithms. Predicate device submissions now require prospective clinical studies demonstrating non-inferiority to manual wound tracing methods, elevating regulatory capital requirements for algorithm-centric entrants. Early-stage vendors are responding by partnering with academic medical centers for multi-site validation cohorts.
Subscription-based software attach rates are displacing perpetual license models across hospital procurement channels. Materials management departments in integrated delivery networks are prioritizing vendors with predictable annual expenditure profiles over capital-intensive hardware purchases. This preference shift is most visible in United States health systems consolidating vendor relationships under single-source agreements.
Wound Measurement Devices Market Segmentation
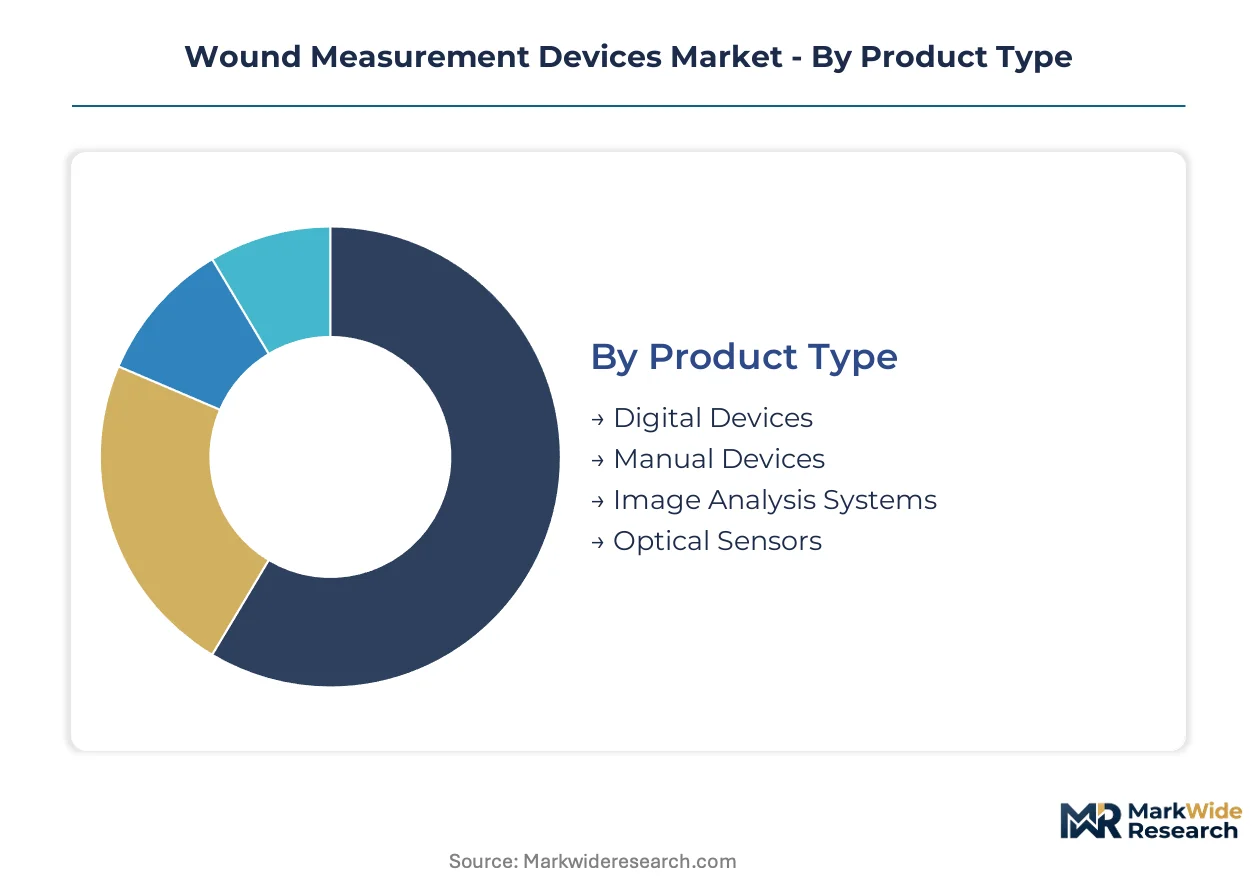
Wound measurement devices fragment across four distinct dimensions that shape procurement patterns and technology adoption curves. Product type determines capital intensity and software attach rates. End user concentration dictates connectivity requirements and regulatory exposure. Technology selection governs precision thresholds and calibration complexity. Application focus influences reimbursement pathway design and clinical workflow integration.
Product Type:
Hospital materials management departments prioritize subscription predictability over hardware ownership, reshaping vendor pricing architectures across all tiers.
- Digital Devices:Handheld units with embedded edge processors execute wound boundary detection without cloud dependency. United States health systems with Epic integration mandates drive procurement concentration toward HL7-certified platforms.
- Image Analysis Systems:Software platforms layer automated segmentation atop standard photography, converting 2D captures into calibrated measurements through photogrammetric algorithms. SaaS pricing models displace perpetual licenses as integrated delivery networks consolidate vendor relationships under single-source agreements.
- Manual Devices:Disposable rulers and tracing films retain relevance in resource-constrained settings. Low unit economics sustain penetration in rural clinics with limited biomedical engineering support.
- Optical Sensors:Silicon photonics modules enable sub-millimeter depth resolution for pressure injury staging. Foundry concentration in East Asia exposes hardware margins to single-source supply risk.
Digital devices lead volumes today; image analysis systems are expanding most quickly through software subscription attach rates.
End User:
Procurement authority concentrates in supply chain executives who bundle wound assessment tools with broader surgical navigation ecosystems.
- Hospitals:Acute care facilities demand native EHR interoperability and FDA 510(k) clearance documentation for liability protection. Capital committees reject platforms without Cerner or Epic certification.
- Clinics:Outpatient wound centers prioritize portability and rapid image-to-report turnaround. Cellular transmission capabilities enable same-day reimbursement claim submission.
- Home Care:Post-acute settings in Germany and France remain underserved, presenting first-mover openings for simplified interfaces with automated quality checks.
- Long-term Care Facilities:Nursing homes face regulatory pressure for pressure injury documentation compliance. 3D depth measurement supports CMS reimbursement thresholds for advanced wound care.
Hospitals dominate revenue capture today; home care demonstrates the steepest expansion trajectory as post-acute diversion policies accelerate.
Technology:
Precision requirements and power constraints create divergent deployment economics across measurement modalities.
- 3D Imaging:Structured light projection and time-of-flight laser scanning generate volumetric data for flap monitoring and deep tissue injury classification. Thermal management limitations compress session duration in battery-operated handhelds.
- Laser Technology:Triangulation-based systems deliver sub-millimeter accuracy for diabetic foot ulcer protocols. Optical calibration skill scarcity constrains rural deployment velocity.
- Ultrasonic Technology:Subsurface tissue characterization supports infection assessment beneath wound beds. Higher per-procedure costs limit penetration outside academic medical centers.
- Infrared Technology:Thermal mapping identifies inflammatory response patterns. Lower resolution thresholds restrict use to screening applications rather than definitive measurement.
Laser technology anchors current installed base; 3D imaging is climbing the fastest as volumetric data integrates into pressure injury staging protocols.
Application:
Reimbursement code availability and documentation burden intensity segment addressable market economics.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers generate recurring measurement needs over extended healing trajectories. Dedicated bacterial load detection codes favor fluorescence imaging specialization.
- Surgical Wounds:Post-operative monitoring demands rapid baseline-to-follow-up comparison for dehiscence detection. OR integration requirements favor sterile-compatible hardware designs.
- Traumatic Wounds:Emergency department throughput pressures favor automated measurement with minimal operator training. Pre-hospital deployment remains limited by device durability concerns.
- Burns:Total body surface area calculation requirements drive demand for full-torso scanning capabilities. Specialized burn centers concentrate procurement decisions regionally.
Chronic wounds command the largest revenue pool today; surgical wounds are gaining share fastest through bundled payment program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston metropolitan area anchors wound measurement device innovation through its concentration of academic medical centers piloting structured light projection systems for pressure injury documentation.
United States
Integrated delivery networks in Texas and California drive procurement concentration toward HL7-certified platforms with native Epic interoperability. FDA 510(k) clearance documentation requirements filter vendor selection to established 3D imaging platforms with predicate device histories. The Research Triangle in North Carolina hosts validation cohorts for multi-site clinical studies supporting algorithm-heavy submissions.
Germany
Post-acute care settings in Bavaria and Baden-Württemberg remain underserved by connected wound assessment tools, creating first-mover openings for simplified cellular-enabled platforms. EU MDR clinical evidence thresholds for optical diagnostic claims consolidate procurement around vendors with established predicate histories. The Rhine-Ruhr industrial corridor concentrates component fabrication for silicon photonics modules displacing legacy CMOS imaging.
United Kingdom
NHS trusts in Greater London and the Midlands prioritize subscription predictability over capital-intensive hardware purchases, reshaping vendor pricing architectures toward SaaS models. GDPR data localization rules force maintenance of redundant compute clusters within UK jurisdiction, elevating operating overhead for cloud-based platforms. The Cambridge cluster advances computational imaging pipelines embedding diagnostic intelligence directly into sensor firmware.
Japan
Metropolitan Tokyo hospitals demand sub-millimeter depth resolution for diabetic foot ulcer protocols, pulling procurement toward time-of-flight laser scanning systems. METI standards for medical device software interoperability constrain platform selection to vendors with certified health information exchange modules. The Osaka-Kobe manufacturing belt produces optical calibration equipment for structured light projection systems requiring trained biomedical technicians.
Australia
Rural health networks in Queensland and Western Australia face deployment velocity constraints due to optical calibration skill scarcity for structured light systems. TGA conformity assessment procedures for software-as-medical-device classifications extend time-to-market for algorithm-centric entrants. The Sydney biomedical precinct hosts academic partnerships for automated wound boundary detection validation against manually segmented reference standards.
Wound Measurement Devices Market Competitive Environment
Strategic partnerships dominate the current landscape as hardware vendors align with academic medical centers for multi-site validation cohorts. The vendor base stratifies across three tiers: diversified medical technology conglomerates with hospital supply chain scale, specialized optical imaging firms with fluorescence or 3D mapping expertise, and software-centric platforms layering automated segmentation atop standard photography. M&A activity concentrates around SaaS-enabled measurement platforms with recurring revenue attach rates, while geographic expansion targets post-acute penetration gaps in Germany and France.
Among North American specialists, ARANZ Medical Limited and Swift Medical Inc. exemplify the 3D imaging and software-centric archetypes respectively. Stryker represents the diversified conglomerate tier with hospital supply chain leverage. MolecuLight Inc. occupies a position within the fluorescence imaging specialization segment. These entities anchor competitive positioning across distinct technology vectors without overlapping core competencies.
| Leading Market Players |
|---|
| ARANZ Medical Limited |
| MolecuLight Inc. |
| Swift Medical Inc. |
| Net Health |
| Kent Imaging Inc. |
| eKare Inc. |
| WoundVision LLC |
| Wound Matrix Inc. |
| Stryker |
| Others |
Value Chain & Pricing Dynamics
Three-tier pricing structure across premium, standard, and economy levels splits wound measurement devices by silicon photonics depth resolution, FDA 510(k) clearance tier, and EHR interoperability certification. Premium tiers with sub-millimeter 3D imaging capabilities command subscription-based SaaS attach rates from United States integrated delivery networks, while economy tiers of disposable rulers serve rural clinics with minimal biomedical support. This divergence concentrates component sourcing in East Asian foundries for optical sensors and North American contract manufacturers for handheld housings.
Pricing Analysis
Silicon photonics wafer costs pass through directly to premium device tiers, compressing hardware margins unless offset by software subscription attach rates. Pricing stratifies across premium, standard, and economy tiers based on depth resolution thresholds and HL7 certification status. Cost compression in the standard tier intensifies as hospital procurement committees consolidate vendor relationships under single-source agreements. Rural health networks exhibit highest price sensitivity, while academic medical centers prioritize optical precision over unit economics.
Supply Chain Analysis
GDPR data localization rules and HIPAA cloud storage constraints reshape sourcing toward regional server infrastructure maintenance across United States, Germany, and United Kingdom jurisdictions. Advanced optical sensor fabrication draws from specialty foundries concentrated in Taiwan, Japan, and South Korea, exposing hardware margins to single-source vulnerability. Structured light projection modules and time-of-flight laser components face tariff exposure from East Asian trade corridors. Distribution runs through hospital supply chain executives who bundle measurement hardware with surgical navigation ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in wound measurement devices hinges on software subscription attach rates displacing perpetual licenses, with silicon photonics cost curves flattening as foundry capacity scales in East Asia.
For Market Incumbents: Anchor hospital supply chain relationships through native Epic and Cerner interoperability certification, defending against software-centric entrants layering automated segmentation atop standard photography. Deepen backward integration into silicon photonics module design to secure optical sensor supply against single-source foundry concentration in Taiwan and Japan. Prioritize FDA 510(k) clearance documentation for AI-enabled segmentation algorithms to extend predicate device equivalence moats. For New Entrants and Emerging Players: The price-point gap between premium 3D imaging systems and economy manual devices creates entry space for mid-tier platforms with simplified cellular-enabled interfaces. Target post-acute care settings in Germany and France where connected wound assessment tools remain underserved, deploying automated quality checks for home health penetration. Pursue EU MDR clinical evidence partnerships with Bavarian academic medical centers to establish predicate device histories. For Investors and Strategic Acquirers: Consolidation pressure builds where SaaS-enabled measurement platforms with recurring revenue attach rates trade at premium multiples against hardware-only vendors. Long-term viability favors software-centric archetypes with FDA 510(k) software-as-medical-device classifications and hospital system partnership density. Watch for inflection signals in CMS reimbursement code expansion for bacterial load detection protocols favoring fluorescence imaging specialization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software-as-Medical-Device Submission | Accelerates market entry for AI-enabled wound segmentation algorithms with predicate device equivalence. |
| Hospital System Partnership | Secures procurement preference through native HL7 interoperability with Epic and Cerner workflows. |
| CE Marking Pathway | Unlocks EU MDR compliance for optical diagnostic claims in German and French post-acute markets. |
| Software Companion Development | Generates recurring SaaS revenue attach rates distinct from capital-intensive hardware sales cycles. |
| Reimbursement Strategy | Captures dedicated CMS codes for bacterial load detection in diabetic foot ulcer protocols. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and wound care clinicians with secondary validation. Primary fieldwork sources include FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and CMS reimbursement code updates. Secondary triangulation draws from SEC filings of diversified medical technology conglomerates, trade customs data for optical sensor components, and academic medical center pilot study disclosures. Bottom-up and top-down approaches reconcile unit shipment estimates with aggregate revenue projections.
Rate-of-change decomposition separates volume expansion from value capture across the projection horizon, modeling wound measurement devices by product type, end user concentration, technology modality, and application focus. Segmentation dimensions include digital device versus image analysis system revenue mix, hospital versus home care deployment velocity, and 3D imaging versus laser technology adoption curves. CAGRs derive from fitted growth curves calibrated against EHR interoperability mandate timelines and EU MDR implementation phases. Industry-specific forecast inputs incorporate silicon photonics foundry capacity expansion and FDA software-as-medical-device clearance velocity.
Caveats apply where FDA predicate device equivalence standard revisions or EU MDR clinical evidence threshold escalations could materially shift the outlook for algorithm-heavy entrants. Forecasts reflect assumptions around hospital procurement committee vendor consolidation preferences and GDPR data localization compliance costs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Healing Market
Wound Care
Moist Wound Dressings Market
Wound Care
Pressure Bandages Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Wound Care Market
Wound Care
Wound Closure Strips Market
Wound Care
Wound Cleanser Products Market
Wound Care
Advanced Wound Management Market
Wound Care
Wound Debridement Products Market
Wound Care
South Korea Wound Care Management Market
Wound Care
Interactive Wound Dressing Market
Wound Care
Philippines Wound Care Market