
 North America and Europe Group 2 Powered Mobility Devices Market | 2026-2036
North America and Europe Group 2 Powered Mobility Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Group 2 Powered Mobility Devices Market Intelligence
Certified rehabilitation equipment technician availability is collapsing across the United States and Germany, forcing distributors to extend service wait times and pressuring manufacturers to simplify field-repair protocols. Pride Mobility Products Corporation leverages its dealer training academy to sustain technician pipelines in underserved metro areas. Ottobock SE & Co. KGaA anchors its European service network with regionally stocked component hubs that reduce technician dispatch requirements.
North America and Europe Group 2 Powered Mobility Devices comprise electrically powered wheelchairs and scooters designed for indoor and limited outdoor use, typically supporting user weights up to 300 pounds with top speeds of 4-5 mph and drive ranges of 10-15 miles per charge; these devices serve individuals with mobility limitations who lack the upper body strength for manual propulsion but do not require the enhanced suspension or environmental controls of Group 3 devices. Power Wheelchairs command the largest revenue pool due to higher Medicare and statutory health insurance reimbursement rates, while Smart Mobility Solutions represent the fastest-expanding technology segment as Bluetooth connectivity and remote diagnostic capabilities attract institutional buyers. Scooters retain volume leadership among private-pay seniors seeking lower-cost alternatives to power wheelchairs.
FDA 510(k) premarket notification requirements and the European Union Medical Device Regulation (MDR) impose clinical evidence and post-market surveillance obligations that elevate compliance costs for new entrants. The U.S. Centers for Medicare & Medicaid Services (CMS) National Coverage Determination framework and Germany's statutory health insurance medical aids catalogue shape reimbursement eligibility, directly steering manufacturer R&D priorities toward billable feature sets. Stakeholders must monitor divergence between FDA and MDR software validation standards as smart connectivity becomes standard equipment rather than premium differentiation.
Market Dynamics
Certified rehabilitation equipment technician availability is collapsing across the United States and Germany, forcing distributors to extend service wait times and pressuring manufacturers to simplify field-repair protocols.
Growth Catalysts
- MDR conformity requirements:The European Union Medical Device Regulation elevates post-market surveillance standards, accelerating consolidation among quality-certified manufacturers.
- Aging-in-place infrastructure:Home healthcare providers across Germany and the United States are expanding procurement of Group 2 devices for seniors requiring mobility support in residential settings.
- Bluetooth connectivity modules:Smart diagnostic capabilities embedded in power wheelchairs attract institutional buyers seeking remote fleet management.
Market Restraints
- Lithium-ion battery supply concentration:Battery cell production concentrates in East Asian manufacturing hubs, exposing European and North American assemblers to input cost volatility and logistics disruption.
- FDA 510(k) clinical evidence thresholds:Premarket notification pathways require substantial equivalence demonstrations that extend development timelines for software-enabled mobility devices.
- Manual wheelchair substitution:Lightweight manual alternatives retain preference among younger users with preserved upper body function, capping addressable population expansion.
Strategic Opportunities
- France and Netherlands expansion:Reimbursement frameworks in these markets remain underdeveloped relative to Germany, creating whitespace for manufacturers establishing early presence.
- Remote diagnostic service contracts:Predictive maintenance offerings leveraging Bluetooth telemetry enable recurring revenue streams beyond hardware sales.
- Component hub localization:Regional stocking facilities reduce technician dispatch requirements and compress service response intervals in underserved metro areas.
Industry Challenges
- Certified technician pipeline collapse:Rehabilitation engineering training programs produce insufficient graduates to match device deployment growth, forcing manufacturers to internalize field service capabilities.
- FDA-MDR software validation divergence:Smart mobility platforms face conflicting cybersecurity and algorithmic transparency requirements across Atlantic regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Group 2 Powered Mobility Devices Market |
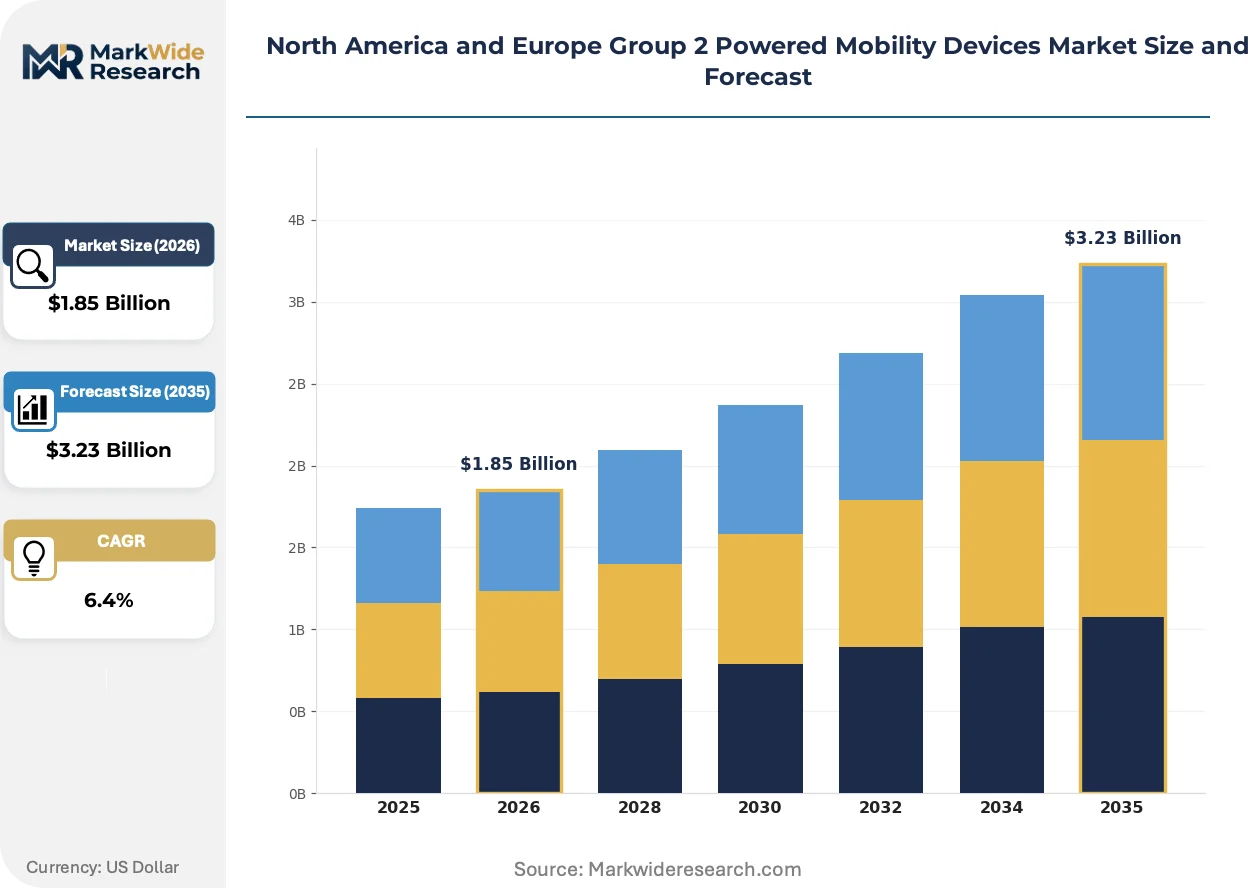
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Wheelchairs, Scooters, Standing Wheelchairs, Specialty Mobility Devices Technology: Electric, Manual, Hybrid, Smart Mobility Solutions End User: Seniors, Disabled Individuals, Rehabilitation Centers, Assisted Living Facilities Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Medical Supply Distributors |
| Companies Covered | National Seating & Mobility, Inc., 1800wheelchair.com, Pride Mobility Products Corporation, Ottobock SE & Co. KGaA, Wal-Mart Stores, Inc., Invacare Corporation, Numotion, Permobil AB, Golden Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Group 2 Powered Mobility Devices Market Strategic Shifts & Innovations
Connectivity architectures and service delivery models are restructuring how powered mobility devices generate value, shifting competitive advantage from hardware specifications to integrated ecosystem control.
Modular drive systems are decomposing traditional power wheelchair architectures into standardized sub-assemblies. Home healthcare providers in the United States are specifying swappable motor and control modules to reduce capital deployment and accelerate fleet refresh cycles. This standardization is decomposing manufacturer lock-in and enabling third-party component sourcing.
The EU Medical Device Regulation's post-market clinical follow-up requirements are reshaping product lifecycle obligations. Manufacturers must now maintain active surveillance registries for software-enabled devices, elevating compliance infrastructure costs. German statutory health insurance funds are tightening medical aids catalogue entries to exclude devices lacking MDR-compliant clinical evidence.
Institutional procurement is consolidating vendor relationships through multi-year fleet management agreements. Hospital systems and home healthcare networks in the United States are unbundling device acquisition from maintenance services, awarding separate contracts to specialized service providers. This bifurcation is most visible in Medicare Advantage plan networks seeking operational cost predictability.
North America and Europe Group 2 Powered Mobility Devices Market Segmentation
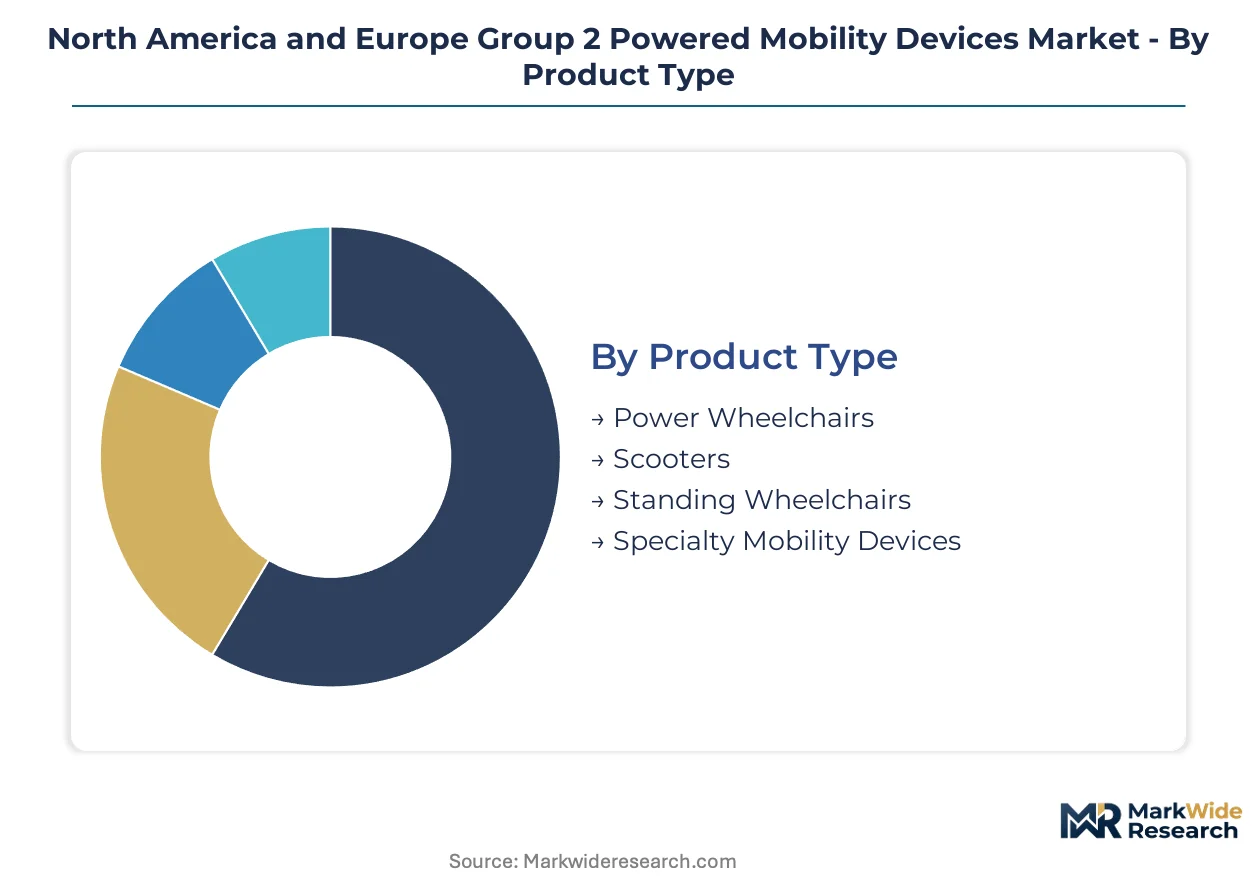
Segmentation in Group 2 powered mobility devices reveals distinct margin architectures across hardware categories, technology tiers, and procurement channels. Reimbursement eligibility criteria in the United States and Germany directly steer volume concentration toward specific product configurations and end-user segments.
Product Type:
Margin pools concentrate in power wheelchairs where Medicare and statutory health insurance reimbursement rates sustain premium pricing, while scooters compete on volume through private-pay channels.
- Power Wheelchairs:Electromechanical seating systems with programmable drive controls and customizable seating modules. Demand concentrates among disabled individuals in Germany and the United States where reimbursement frameworks favor powered alternatives over manual propulsion. Medicare Advantage plans in Florida and Texas are expanding prior authorization pathways for Group 2 configurations.
- Scooters:Three- and four-wheeled mobility platforms with tiller steering and detachable battery packs. Private-pay seniors in suburban United States markets drive volume, attracted by lower acquisition costs and simpler transport logistics. Retail mobility showrooms in Arizona and Nevada report strongest scooter turnover among aging-in-place populations.
- Standing Wheelchairs:Motorized frames enabling vertical position transitions for pressure relief and social interaction.
- Specialty Mobility Devices:Bariatric configurations and pediatric adaptations serving narrow clinical indications.
Power Wheelchairs hold installed capacity. Scooters are rotating up the share rankings among private-pay demographics.
Technology:
Technology segmentation tracks the shift from electromechanical hardware toward software-defined mobility platforms with recurring service revenue potential.
- Electric:Brushless DC motor systems with sealed lead-acid or lithium-ion battery architectures. Rehabilitation centers across Pennsylvania and Bavaria standardize on electric platforms for fleet uniformity and technician training efficiency.
- Smart Mobility Solutions:Bluetooth-enabled drive systems with remote diagnostic telemetry and predictive maintenance algorithms. Institutional buyers in Michigan and North Rhine-Westphalia are specifying smart connectivity for multi-device fleet management. FDA 510(k) software validation requirements and MDR cybersecurity standards are elevating compliance barriers for new platform entrants.
- Manual:Unpowered configurations retained for lightweight transport and backup mobility scenarios.
- Hybrid:Dual-mode systems combining manual propulsion with electric assist for variable exertion control.
Electric systems dominate current procurement volumes. Smart Mobility Solutions are climbing the fastest as connectivity becomes standard in institutional tenders.
End User:
End-user segmentation aligns with reimbursement channel structures and care delivery settings across North American and European healthcare systems.
- Seniors:Aging populations requiring mobility support for independent residential living. Home healthcare providers in Ohio and Baden-Württemberg are expanding Group 2 device deployment for aging-in-place programs. CMS National Coverage Determination criteria shape device specification requirements for Medicare eligibility.
- Disabled Individuals:Users with congenital or acquired mobility limitations requiring daily functional support. Medicaid waiver programs in Illinois and statutory health insurance medical aids catalogues in Germany prioritize this segment for comprehensive coverage.
- Rehabilitation Centers:Post-acute facilities managing device fleets for transitional patient populations.
- Assisted Living Facilities:Residential care operators procuring shared mobility resources for resident pools.
Seniors represent the largest addressable population. Disabled Individuals are rotating up the share rankings as diagnostic expansion and disability rights frameworks broaden eligibility.
Distribution Channel:
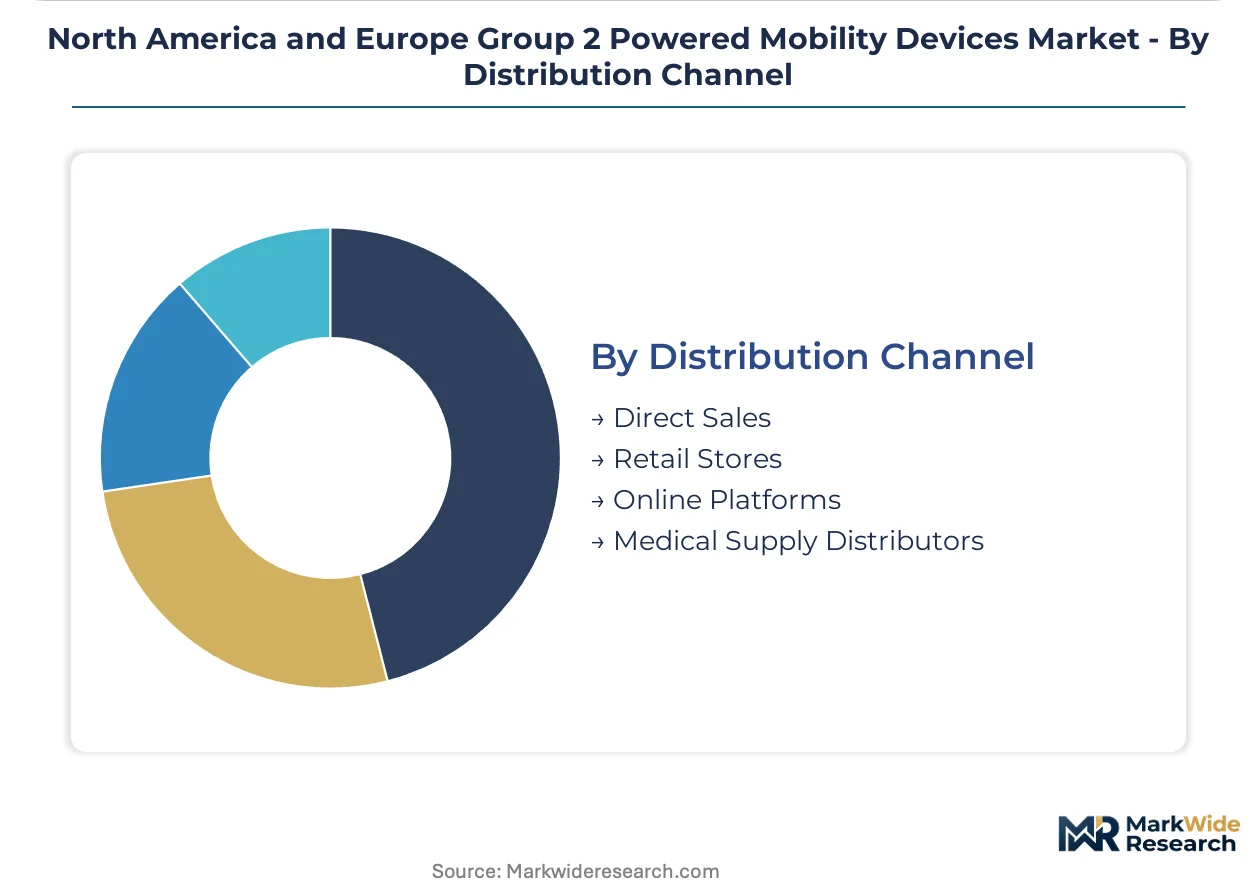
Channel segmentation reflects the unbundling of device acquisition from service delivery in institutional procurement patterns.
- Medical Supply Distributors:Full-service providers combining device fulfillment with certified technician networks. Distributors in California and Hesse are consolidating vendor relationships through multi-year fleet management agreements. Technician availability constraints are forcing distributors to extend service territories and compress response intervals.
- Direct Sales:Manufacturer-employed specialists serving high-volume institutional accounts. Hospital systems in New York and hospital networks in Lower Saxony are awarding separate contracts to specialized service providers.
- Retail Stores:Brick-and-mortar showrooms targeting private-pay consumers with immediate fulfillment.
- Online Platforms:E-commerce channels with limited service integration, primarily serving accessory and replacement part demand.
Medical Supply Distributors hold installed capacity. Direct Sales is rotating up the share rankings as institutional procurement consolidates vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways and CMS National Coverage Determination criteria anchor the United States as the dominant geography, while Germany's statutory health insurance medical aids catalogue drives parallel demand concentration across Europe.
United States
Medicare Advantage plans in Florida and Texas are expanding prior authorization pathways for Group 2 configurations, while home healthcare providers in Ohio deploy devices for aging-in-place seniors. CMS reimbursement frameworks directly steer manufacturer R&D priorities toward billable feature sets. Rehabilitation centers in Pennsylvania standardize on electric platforms for fleet uniformity and technician training efficiency.
Germany
Statutory health insurance funds are tightening medical aids catalogue entries to exclude devices lacking MDR-compliant clinical evidence, accelerating consolidation among quality-certified manufacturers. Home healthcare providers in Baden-Württemberg expand Group 2 device deployment for residential mobility support. Ottobock SE & Co. KGaA anchors its European service network with regionally stocked component hubs in Lower Saxony.
United Kingdom
NHS wheelchair service specifications are shifting toward outcomes-based procurement models that favor devices with remote diagnostic capabilities. The Medicines and Healthcare products Regulatory Agency enforces MDR transition timelines for legacy device registrations. Hospital networks in the Midlands are awarding separate contracts to specialized service providers for fleet management.
France
Reimbursement frameworks remain underdeveloped relative to Germany, creating whitespace for manufacturers establishing early presence through direct institutional relationships. ANSM post-market surveillance requirements elevate compliance infrastructure costs for software-enabled platforms. Home healthcare networks in Île-de-France are specifying Bluetooth-enabled drive systems for multi-device fleet visibility.
Netherlands
Long-term care insurance (WLZ) funding mechanisms are gradually expanding powered mobility coverage beyond manual alternatives, opening procurement channels for Group 2 configurations. Healthcare Inspectorate (IGJ) quality audits emphasize technician certification standards that constrain distributor capacity. Medical supply distributors in the Randstad are consolidating vendor relationships through multi-year fleet management agreements.
North America and Europe Group 2 Powered Mobility Devices Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the market structure reflecting vertical differentiation between full-service providers and component-focused assemblers. The upper tier commands institutional procurement relationships through certified technician networks and regional service infrastructure, while mid-tier players compete on private-pay volume through retail and e-commerce channels. Two strategic archetypes dominate: vertically integrated manufacturers with captive distribution, and specialized distributors with multi-vendor service capabilities. Competitive moves concentrate on geographic service territory expansion and predictive maintenance service contract development.
Among US-based integrated manufacturers, Pride Mobility Products Corporation and Invacare Corporation exemplify the full-service archetype with established dealer training infrastructure, while Permobil AB represents Swedish engineering-focused positioning within the premium rehabilitation equipment tier. National Seating & Mobility, Inc. and Numotion occupy positions within the specialized distributor archetype, competing through multi-year fleet management agreements with hospital systems and home healthcare networks. Golden Technologies represents private-pay volume leadership through retail channel penetration.
| Leading Market Players |
|---|
| National Seating & Mobility, Inc. |
| 1800wheelchair.com |
| Pride Mobility Products Corporation |
| Ottobock SE & Co. KGaA |
| Wal-Mart Stores, Inc. |
| Invacare Corporation |
| Numotion |
| Permobil AB |
| Golden Technologies |
| Others |
Cost & Logistics Intelligence
East Asian battery cell manufacturing at scale creates asymmetric cost structures that compress price floors for North American and European assemblers while elevating margin pressure on downstream distributors. Capacity utilization rates in lithium-ion production directly transmit into input cost volatility that reimbursement-constrained buyers cannot fully absorb.
Pricing Analysis
Geographic price spreads between Germany and the United States reflect divergent statutory health insurance and Medicare reimbursement ceilings rather than manufacturing cost differentials. Three-tier pricing structure across premium smart-connected, standard electric, and economy scooter tiers separates institutional fleet buyers from private-pay seniors. Cost compression in the standard tier is intensifying because MDR compliance investments elevate fixed cost burdens without corresponding reimbursement expansion. Private-pay seniors exhibit highest price sensitivity, while hospital systems locked into multi-year fleet agreements show lowest elasticity.
Supply Chain Analysis
China, South Korea, and Japan anchor lithium-ion battery cell production for Group 2 powered mobility devices. Brushless DC motors, programmable control modules, and sealed lead-acid alternatives draw from Taiwanese and Malaysian component specialists. Single-source vulnerability concentrates in cathode active material supply, exposing assemblers to logistics disruption through Red Sea chokepoints. Distribution runs through medical supply distributors with certified technician networks, though direct sales channels are gaining share among consolidated hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in Group 2 powered mobility devices stems from aging-in-place infrastructure deployment outpacing manual wheelchair substitution rates across Medicare Advantage and statutory health insurance channels.
For Market Incumbents: Compound service infrastructure advantages by expanding component hub localization into technician-underserved metro areas in Texas and Florida. Invest in FDA 510(k) software validation capabilities ahead of MDR cybersecurity divergence to defend against emerging smart-platform entrants. Vertical integration into predictive maintenance service contracts locks in recurring revenue beyond hardware replacement cycles. For New Entrants and Emerging Players: Lead with reimbursement pathway expertise in France and Netherlands where statutory frameworks remain underdeveloped relative to Germany. Target private-pay scooter segments in Arizona and Nevada retail channels where brand recognition gaps exist. Pursue white-label manufacturing partnerships with established distributors to bypass captive technician network requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with MDR-compliant quality systems and established GPO contracts. Long-term viability rests on predictive maintenance platform monetization rather than hardware shipment volume. Acquisition target archetype: regional distributors with certified technician density in consolidating hospital system territories. Watch Bluetooth telemetry adoption rates in Medicare Advantage prior authorization pathways as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Infrastructure Investment | Statutory health insurance funds in Germany now exclude non-compliant devices from medical aids catalogues. |
| Predictive Maintenance Platform Development | Bluetooth telemetry enables recurring revenue streams beyond hardware sales for institutional fleet managers. |
| Component Hub Localization | Regional stocking facilities in Lower Saxony and Ohio compress service response intervals for aging-in-place programs. |
| Technician Training Academy Expansion | Pride Mobility's dealer academy model addresses certified pipeline collapse in underserved United States metro areas. |
| Smart Connectivity Standardization | FDA 510(k) software validation capabilities differentiate institutional procurement winners from commodity assemblers. |
Research Approach
A spread of perspectives from rehabilitation equipment technicians, home healthcare procurement directors, statutory health insurance fund administrators, and FDA regulatory consultants converged on the working assumptions. Primary interviews combined with secondary validation against CMS National Coverage Determination databases, MDR conformity assessment body filings, and hospital GPO contract repositories. Bottom-up device shipment modeling triangulated against top-down reimbursement expenditure analysis across the analysis window.
Segmentation dimensions modeled include product type, technology tier, end-user category, and distribution channel across the projection horizon. CAGRs derived from reimbursement policy trajectory analysis, technician supply-demand gap projections, and lithium-ion input cost elasticity estimates. Forecast inputs incorporated Medicare Advantage penetration rates and MDR transition timeline compliance costs.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and German statutory health insurance medical aids catalogue structures; material policy shifts would require re-modeling. Specific risks include lithium-ion supply disruption, certified technician pipeline collapse, and reimbursement rate compression. Recalibration cycles align with material shifts in CMS National Coverage Determination criteria and MDR post-market surveillance enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nerve Repair and Regeneration Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Medication Management System Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
Military Wearable Medical Device Market
Medical Devices
Airotar Handpiece Market
Medical Devices
Heel Incision Devices Market
Medical Devices
Creatinine Meter Market
Medical Devices
Human Augmentation in Healthcare Market
Medical Devices
Skull Deformity Implants Market
Medical Devices
Global Cardiac Prosthetic Devices Market
Medical Devices
Endodontic Devices Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Vaginal Inserts Market
Medical Devices
Pancreatic and Biliary Stents Market