
 Asia Pacific Negative Pressure Wound Therapy Market | 2026-2036
Asia Pacific Negative Pressure Wound Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Negative Pressure Wound Therapy Market Insights
CE marking under the EU MDR is bifurcating competitive access across the Asia Pacific region, as manufacturers without updated technical documentation face exclusion from distributor networks serving premium hospital chains. Smith & Nephew Plc leverages its established regulatory infrastructure to sustain commercial presence across Australian and Japanese tertiary centers. Cardinal Health, Inc. competes through channel control of disposable canister supply lines, while Mölnlycke Health Care AB anchors its position with specialized adhesive dressing portfolios calibrated to tropical humidity conditions.
Negative Pressure Wound Therapy applies sub-atmospheric pressure, typically negative 125 mmHg, through sealed foam or gauze dressings to accelerate granulation tissue formation and reduce edema in acute and chronic wounds. Portable systems command expanding share as homecare discharge protocols shorten hospital length of stay across South Korean and Taiwanese reimbursement frameworks. Electromechanical technology leads installed base value, though software-integrated platforms capturing pressure modulation data represent the fastest-growing margin pool for device vendors.
Japan's PMDA, Australia's TGA, and China's NMPA each enforce distinct software validation and biocompatibility testing requirements that fragment product registration timelines and limit cross-border kit standardization. India's CDSCO has signaled forthcoming medical device rule harmonization with IMDRF principles, which will reshape import licensing pathways for multinational NPWT suppliers. Stakeholders must monitor reimbursement coding divergence between national health insurance schemes and private hospital procurement consortia to anticipate volume shifts across institutional and homecare delivery channels.
Market Dynamics
Japan's PMDA software-as-medical-device guidelines are fragmenting product registration pathways and forcing manufacturers toward localized clinical validation, reshaping competitive access across the Asia Pacific Negative Pressure Wound Therapy Market.
Growth Catalysts
- Rising surgical volumes:Tertiary hospitals in China and India are expanding device procurement budgets for advanced wound care systems. Public hospital networks in China's tier-one cities centralize high-value medical device purchasing.
- Homecare discharge protocols:South Korean and Taiwanese reimbursement frameworks are shortening hospital length of stay and expanding portable NPWT system demand. Electromechanical technology leads installed base expansion.
- India's CDSCO harmonization:Forthcoming medical device rule alignment with IMDRF principles will reshape import licensing pathways for multinational suppliers. This regulatory convergence accelerates market entry timelines.
Market Restraints
- Biocompatibility testing fragmentation:Japan's PMDA, Australia's TGA, and China's NMPA enforce distinct validation requirements that limit cross-border kit standardization. Product registration timelines extend unpredictably.
- Software validation costs:Connected NPWT systems face escalating compliance expenditure under tightened guidelines. Small and mid-sized manufacturers lack capital to sustain multi-jurisdictional filings.
- Disposable canister supply concentration:Channel control over consumable supply lines creates dependency on single-source distributors. Tropical humidity conditions degrade standard adhesive performance in Southeast Asian deployments.
Strategic Opportunities
- Software-integrated platforms:Pressure modulation data capture represents the fastest-growing margin pool for device vendors. Real-time wound monitoring creates recurring revenue attachment.
- Tier-two and tier-three Chinese cities:Underpenetrated procurement networks outside Beijing, Shanghai, and Guangzhou offer volume expansion potential. Provincial hospital consortia are consolidating purchasing authority.
- Reimbursement coding arbitrage:Divergence between national health insurance schemes and private hospital procurement consortia creates channel-switching opportunities. Stakeholders can anticipate volume shifts across institutional and homecare delivery.
Industry Challenges
- Multi-jurisdictional regulatory talent scarcity:Firms struggle to recruit specialists conversant with PMDA, TGA, NMPA, and CDSCO filing requirements simultaneously. Compliance function expansion outpaces qualified candidate supply.
- Legacy system integration complexity:Connected NPWT platforms must interface with hospital electronic health record architectures that vary across Australian, Japanese, and Chinese provider networks. Data interoperability standards remain unsettled.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Negative Pressure Wound Therapy Market |
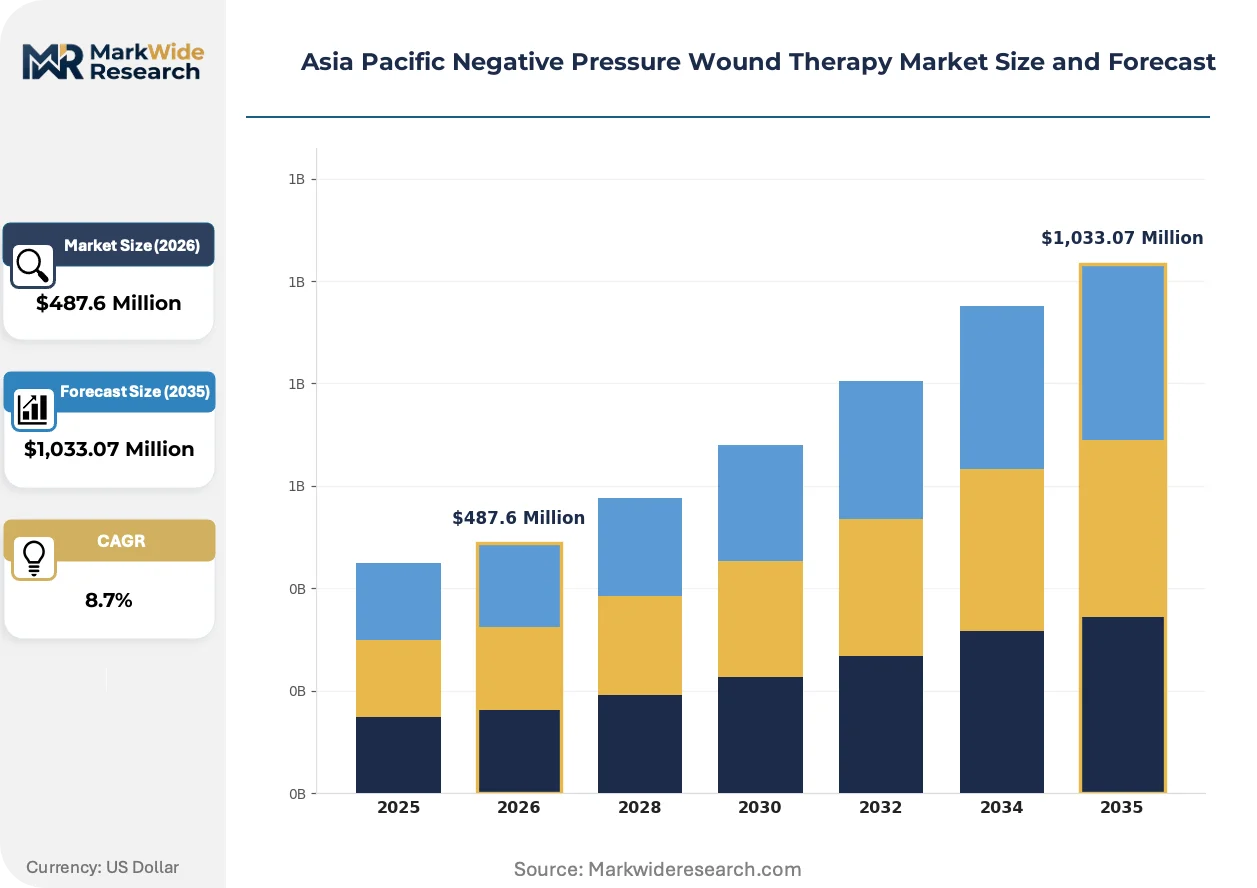
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Fixed Systems, Disposable Canisters, Adhesive Dressings End User: Hospitals, Homecare Settings, Rehabilitation Centers, Long-term Care Facilities Technology: Electromechanical, Pneumatic, Software-Integrated, Hybrid Systems Application: Chronic Wounds, Surgical Wounds, Traumatic Wounds, Burns |
| Companies Covered | Smith & Nephew Plc, Solventum Corporation, Cardinal Health, Inc., DeRoyal Industries, Inc., Mölnlycke Health Care AB, ConvaTec Group Plc, Direct Healthcare Group, Medela AG, 3M Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Negative Pressure Wound Therapy Market Trends and Innovations
Software-integrated NPWT platforms are capturing pressure modulation data and reshaping margin structures, while regulatory divergence and procurement centralization are compressing traditional commercial models across the Asia Pacific region.
Foam and gauze dressing materials optimized for tropical humidity conditions are displacing standard adhesive portfolios in Southeast Asian deployments. Australian and Singaporean tertiary centers are adopting these specialized formulations at accelerated pace. This material innovation is displacing incumbent suppliers lacking climate-calibrated product lines and compressing their distributor relationships.
CE marking under the EU MDR is bifurcating competitive access across distributor networks serving premium hospital chains. Manufacturers without updated technical documentation face systematic exclusion from procurement shortlists. Australian and Japanese tertiary centers are prioritizing vendors with established regulatory infrastructure, narrowing the qualified supplier base.
Public hospital procurement networks in China's tier-one cities are consolidating high-value medical device purchasing authority. Traditional distributor intermediaries are losing access to centralized tender processes. This concentration is most visible in Beijing and Shanghai, where municipal health commissions now control category-level contracting for advanced wound care systems.
Asia Pacific Negative Pressure Wound Therapy Market Segmentation
Channel mix varies sharply across NPWT segments in Asia Pacific. Portable systems flow through homecare reimbursement networks, while fixed installations anchor tertiary hospital procurement. Understanding segment-channel alignment reveals where margin pools concentrate and where regulatory barriers fragment access.
Product Type:
Portable systems and disposable canisters dominate homecare discharge channels across South Korea and Taiwan, while fixed systems and adhesive dressings concentrate in centralized hospital procurement networks.
- Portable Systems:Battery-powered units delivering sub-atmospheric pressure through sealed dressings enable early discharge protocols. South Korean national health insurance and Taiwanese diagnosis-related group reimbursement are expanding portable system volumes fastest. PMDA software validation requirements are compressing supplier participation in Japan.
- Fixed Systems:Wall-mounted or cart-based electromechanical units serve operating theaters and intensive care wards. China's tier-one city hospital networks centralize fixed system purchasing through municipal health commission tenders, squeezing distributor margins.
- Disposable Canisters:Single-use fluid collection reservoirs lock in recurring revenue streams. Cardinal Health controls dominant supply lines across Australian distributor networks.
- Adhesive Dressings:Specialized foam and gauze interfaces optimized for tropical humidity displace standard formulations in Southeast Asia. Mölnlycke's climate-calibrated portfolios anchor position in Singaporean and Australian tertiary centers.
Fixed systems dominate installed base across institutional channels. Portable systems are where expansion concentrates.
End User:
Cost tier stratification separates premium tertiary hospital demand from price-sensitive homecare and long-term care procurement.
- Hospitals:Tertiary centers in Beijing, Shanghai, Tokyo, and Sydney drive premium system adoption. China's provincial hospital consortia are consolidating purchasing authority outside tier-one cities, reshaping access patterns.
- Homecare Settings:Post-acute discharge protocols in South Korea and Taiwan are shortening hospital length of stay and expanding portable NPWT rental and purchase volumes through national reimbursement schemes.
- Rehabilitation Centers:Intermediate care facilities in India's metro clusters are emerging as volume pockets for mid-range electromechanical systems as CDSCO harmonization accelerates import pathways.
- Long-term Care Facilities:Nursing homes and aged care residences in Japan and Australia face constrained budgets that favor durable, low-maintenance pneumatic systems over software-integrated platforms.
Hospitals capture the highest per-unit pricing. Homecare settings are expanding most quickly.
Technology:
Margin concentration tracks software integration depth, with electromechanical platforms anchoring volume and connected systems capturing premium pricing.
- Electromechanical:Motor-driven vacuum pumps with analog pressure control constitute the largest installed base across Asia Pacific. These systems face commoditization pressure in China's centralized procurement environment.
- Pneumatic:Compressed gas or wall-suction dependent systems serve cost-constrained long-term care and rehabilitation facilities. Simpler architectures bypass software validation burdens that fragment registration timelines.
- Software-Integrated:Connected platforms capturing pressure modulation data and enabling remote monitoring represent the steepest expansion trajectory. PMDA, TGA, and NMPA each enforce distinct validation requirements that limit cross-border standardization.
- Hybrid Systems:Dual-mode platforms switching between electromechanical and pneumatic operation address backup power reliability concerns in Southeast Asian deployments with intermittent grid stability.
Electromechanical technology anchors installed base value. Software-integrated platforms are gaining share fastest.
Application:
Volume concentration varies by wound etiology, with surgical and chronic wounds driving differentiated technology requirements and reimbursement coding.
- Chronic Wounds:Diabetic foot ulcers and pressure injuries in Japan's aging population and India's diabetes-prevalent metros sustain demand for extended-duration therapy. These cases favor portable systems with long battery life.
- Surgical Wounds:Post-operative sternal, abdominal, and orthopedic closures in Australian and Chinese tertiary centers drive fixed system procurement. Surgical application reimbursement codes are most established across national health insurance schemes.
- Traumatic Wounds:Acute injury management in emergency departments concentrates in urban trauma centers. These deployments prioritize rapid application speed over advanced monitoring features.
- Burns:Specialized foam dressing configurations for partial-thickness burns see concentrated demand in Singapore's regional burn referral center and select Australian units.
Surgical wounds dominate procedure-linked reimbursement volume. Chronic wounds are where homecare channel expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement managers in tier-one Chinese cities and Japanese tertiary centers concentrate purchasing authority for advanced wound care systems, while homecare discharge protocols in South Korea and Taiwan shift volume toward portable rental channels.
China
Municipal health commissions in Beijing, Shanghai, and Guangzhou centralize high-value medical device tendering for fixed NPWT systems, squeezing traditional distributor margins. NMPA software validation requirements for connected platforms extend registration timelines unpredictably. Provincial hospital consortia in Sichuan and Shandong are consolidating purchasing authority outside tier-one cities.
Japan
Aging demographics and diabetic foot ulcer prevalence sustain demand for extended-duration portable therapy in Kanto and Kansai regions. PMDA tightened software-as-medical-device guidelines force manufacturers toward localized clinical validation for connected systems. Tokyo and Osaka tertiary centers prioritize vendors with established regulatory infrastructure.
India
Rising surgical volumes in Delhi-NCR, Mumbai, and Bangalore metro clusters expand device procurement budgets for advanced wound care. CDSCO has signaled forthcoming medical device rule harmonization with IMDRF principles, reshaping import licensing pathways. Rehabilitation centers in Chennai and Hyderabad emerge as volume pockets for mid-range electromechanical systems.
South Korea
National health insurance reimbursement frameworks shorten hospital length of stay and expand portable NPWT rental volumes through homecare discharge protocols. MFDS enforces distinct biocompatibility testing requirements that limit cross-border kit standardization. Seoul Capital Area tertiary hospitals drive premium system adoption while Busan-Ulsan corridor facilities scale mid-range deployments.
Australia
TGA software validation and biocompatibility requirements fragment product registration timelines for connected platforms. Sydney and Melbourne tertiary centers adopt specialized adhesive dressing formulations optimized for tropical humidity conditions. Distributor networks serving premium hospital chains systematically exclude manufacturers without updated EU MDR technical documentation.
Asia Pacific Negative Pressure Wound Therapy Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with established regulatory infrastructure alongside specialized wound care pure-plays. Market structure concentrates around three archetypes: full-system vendors controlling device and consumable integration, disposable specialists dominating canister and dressing supply lines, and software-integrated platform developers capturing premium pricing. Competitive moves center on regulatory documentation updates for EU MDR alignment and geographic expansion through distributor network consolidation.
Among diversified medical technology conglomerates, Smith & Nephew Plc and 3M Company occupy positions anchored by established regulatory infrastructure across multiple Asia Pacific jurisdictions. Cardinal Health, Inc. sits within the disposable supply line control archetype. These three entities exemplify how scale and documentation breadth determine access to centralized procurement networks in premium hospital chains.
| Leading Market Players |
|---|
| Smith & Nephew Plc |
| Solventum Corporation |
| Cardinal Health, Inc. |
| DeRoyal Industries, Inc. |
| Mölnlycke Health Care AB |
| ConvaTec Group Plc |
| Direct Healthcare Group |
| Medela AG |
| 3M Company |
| Others |
Pricing and Supply Chain Analysis
Ninety-to-one-hundred-day NMPA registration timelines for connected NPWT systems compress distributor inventory turns and amplify pricing power for manufacturers with pre-validated technical documentation. This lead-time band concentrates margin capture among established players while forcing smaller competitors toward spot-market canister sourcing at elevated cost.
Pricing Analysis
Cost-plus contracts with medical-grade polymer indexation dominate disposable canister procurement across Australian hospital networks. Pricing stratifies across premium software-integrated platforms, standard electromechanical systems, and economy pneumatic units based on PMDA validation status and after-sales service bundling. Cost compression in China's centralized municipal tenders is intensifying as provincial consortia consolidate purchasing authority. Public hospital procurement committees exhibit highest price sensitivity, while private tertiary centers in Tokyo and Sydney prioritize regulatory documentation over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Japanese distributors serving Kanto region tertiary centers, while strategic stockpiling of adhesive dressings buffers Southeast Asian deployments against monsoon-season logistics disruption. Manufacturing concentration rests on China for electromechanical pump assemblies, Japan for precision pressure sensors, and South Korea for battery modules. Medical-grade foam and specialized hydrocolloid adhesives draw from petrochemical feedstocks vulnerable to commodity price volatility. Distribution runs through GPO-affiliated distributors in tier-one Chinese cities and specialized wound-care distributors elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as homecare discharge protocols accelerate portable NPWT penetration beyond institutional settings. South Korean and Taiwanese reimbursement frameworks provide the clearest adoption tailwind.
For Market Incumbents: Secure PMDA software-as-medical-device validation ahead of guideline enforcement to lock out competitors lacking localized clinical data. Deepen backward integration into foam dressing manufacturing to offset tropical humidity formulation costs that squeeze distributor margins. Cardinal Health's canister supply line control and Mölnlycke's climate-calibrated portfolios demonstrate how captive production anchors position against emerging pure-play software entrants. For New Entrants and Emerging Players: Anchor in China's tier-two provincial hospital consortia where centralized purchasing authority remains fragmented and incumbent documentation advantages are weakest. Target rehabilitation centers in India's metro clusters as CDSCO harmonization accelerates import pathways. Lead with simplified pneumatic systems that bypass multi-jurisdictional software validation burdens while building clinical evidence for eventual connected platform migration. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because software-integrated platforms with validated pressure modulation data capture recurring revenue attachment and premium pricing that commoditized electromechanical systems cannot match. Acquisition targets should display established PMDA, TGA, or NMPA filing infrastructure alongside proprietary dressing formulations. The signal to watch is reimbursement coding consolidation between national health insurance schemes and private procurement consortia, which would accelerate volume shifts toward homecare channels and reward portable-system specialists.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software Validation Pathway | Localized clinical trials for connected NPWT systems unlock Tokyo and Osaka tertiary center access. |
| Hospital System Partnership | Municipal health commission relationships in Beijing and Shanghai bypass distributor margin compression. |
| Software Companion Development | Pressure modulation data platforms create recurring revenue attachment beyond device sale. |
| CE Marking Pathway | EU MDR technical documentation satisfies Australian distributor qualification requirements. |
| Reimbursement Strategy | National health insurance coding alignment accelerates portable NPWT rental volumes in South Korea. |
Research Methodology
A standing panel of hospital procurement managers, biomedical engineers, GPO contracts managers, and wound care clinicians provided ongoing calibration against primary fieldwork and secondary validation. Hospital procurement databases, GPO contract repositories, CMS Medicare data analogs, and regulatory filing records supplied quantitative anchors. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end user, technology depth, and wound etiology dimensions. CAGRs derived from fitted growth curves applied to installed base expansion and replacement cycle assumptions. Reimbursement coding evolution and regulatory timeline uncertainty served as key forecast sensitivity inputs.
Material uncertainties — PMDA guideline enforcement timing, CDSCO harmonization implementation, and NMPA software validation backlog clearance — sit outside the modeled envelope. Forecasts reflect documented assumptions about procurement centralization velocity and homecare discharge protocol adoption. Revision becomes warranted when reimbursement divergence between national insurance schemes and private consortia crosses thresholds that alter channel economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Advanced Wound Care Management Market
Wound Care
Wound Cleanser Products Market
Wound Care
Global Active Wound Care Market
Wound Care
Animal Wound Care Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Philippines Wound Care Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Autologous Wound Patches Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
North America Advanced Wound Care Market
Wound Care
Biopatches Market
Wound Care
Interactive Wound Dressing Market
Wound Care
Asia Pacific Wound Care Market
Wound Care
Global Surgical Drains/Wound Drainage Market
Wound Care
Global Antimicrobial Dressings Market
Wound Care
Wound Care Sealants Market