
 Global Burn Care Market | 2026-2036
Global Burn Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Burn Care Market Foresight
China is narrowing the supply gap for advanced burn dressings through expanded domestic manufacturing of antimicrobial wound care materials. Smith & Nephew leverages its biosynthetic skin substitute portfolio to sustain leadership in European hospital procurement. Integra LifeSciences anchors North American reconstructive surgery channels with dermal regeneration matrices. Coloplast Corp. competes through specialized hydrofiber dressing lines tailored to partial-thickness thermal injuries.
Burn care encompasses the clinical management of tissue damage resulting from thermal, chemical, electrical, or radiation exposure, utilizing advanced dressings, skin substitutes, topical agents, and surgical interventions to prevent infection, maintain moisture balance, and promote re-epithelialization across partial-thickness and full-thickness wound beds. The primary purpose spans acute wound stabilization through functional and aesthetic reconstruction. Dressings and skin substitutes command the deepest margin pools due to recurring application cycles and premium pricing for biologic matrices. Thermal burns generate the highest procedure volume across emergency and specialized settings, while outpatient treatment models are expanding fastest as advanced home-care dressings reduce hospital length of stay.
FDA medical device regulations govern skin substitute classifications and 510(k) clearance pathways, directly shaping product development timelines and market entry costs for manufacturers. EMA's Medical Device Regulation enforces stricter clinical evidence requirements for burn grafts and antimicrobial solutions across European markets, elevating compliance investments. ISO 13485 quality management standards and WHO burn management guidelines further harmonize safety benchmarks. Stakeholders must monitor evolving reimbursement frameworks for biologic wound products and telemedicine-integrated burn assessment protocols to capture shifting care delivery economics.
Market Dynamics
The FDA's streamlined 510(k) clearance pathway for skin substitutes is compressing product development timelines and redistributing competitive advantage toward biologic matrix manufacturers with established quality management systems.
Growth Catalysts
- Biologic skin substitute adoption:Hospital burn centers in the United States are integrating dermal regeneration matrices into standard wound protocols, expanding addressable procedure volumes beyond traditional autograft limitations.
- EMA Medical Device Regulation harmonization:Stricter clinical evidence requirements across European markets are elevating barriers for marginal competitors while rewarding manufacturers with robust trial portfolios.
- Antimicrobial dressing manufacturing expansion:China's domestic production capacity for advanced wound care materials is narrowing supply constraints and reducing import dependency for hospital procurement networks.
Market Restraints
- Biologic matrix input cost volatility:Collagen sourcing from porcine and bovine tissues faces price instability tied to agricultural commodity cycles and disease outbreak controls.
- Specialized burn unit concentration:Germany maintains the highest density of dedicated burn centers in Europe, creating geographic access disparities that limit market penetration in adjacent markets.
- Reimbursement framework heterogeneity:Divergent national health technology assessment processes for advanced wound products create fragmented market access conditions across OECD markets.
Strategic Opportunities
- Outpatient burn care protocols:Advanced home-care dressing technologies are enabling procedure migration from hospital settings, creating channel expansion potential for manufacturers with patient training capabilities.
- Telemedicine-integrated assessment:Remote wound monitoring platforms are converging with digital imaging standards to extend specialist consultation reach into underserved rural and frontier regions.
- WHO burn management guideline alignment:Harmonized safety benchmarks in emerging markets are reducing regulatory friction for manufacturers with established ISO 13485 certification pathways.
Industry Challenges
- Reconstructive surgery fellowship pipeline constraints:Limited specialized training program capacity in North America and Europe is constraining qualified surgeon availability for complex graft procedures.
- Biologic product cold chain integrity:Temperature-controlled distribution requirements for living cell therapies impose logistical complexity and failure risk across last-mile hospital delivery networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Burn Care Market |
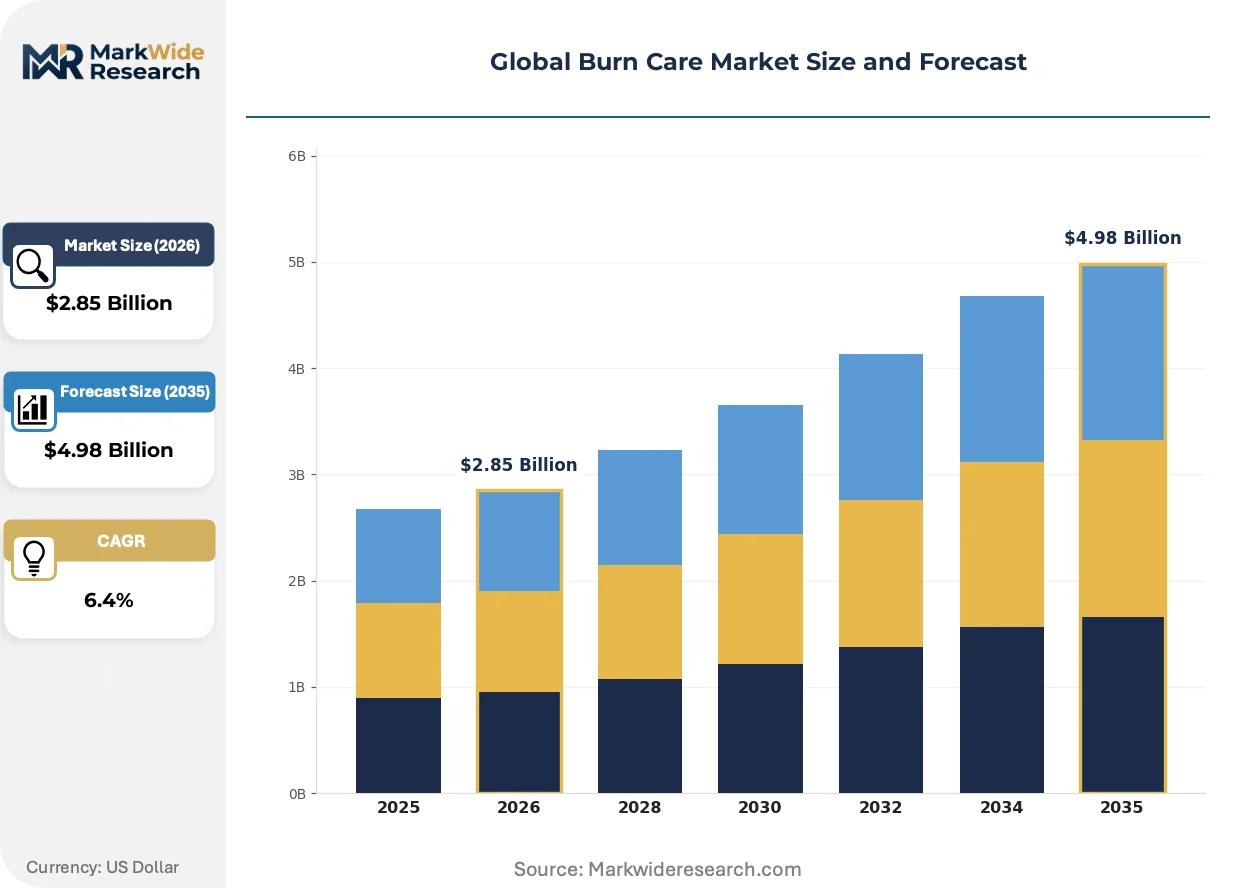
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Skin Substitutes, Topical Agents, Surgical Devices, Burn Grafts, Antimicrobial Solutions Application: Thermal Burns, Chemical Burns, Electrical Burns, Radiation Burns, Scald Burns, Frostbite End User: Burn Centers, Specialized Clinics, Rehabilitation Centers, Emergency Units, Research Institutes, Trauma Units Deployment Model: Hospital-Based Care, Outpatient Treatment, Home Healthcare, Mobile Medical Units, Telemedicine Services, Clinics |
| Companies Covered | 3M, Smith & Nephew, Mölnlycke Health Care AB, ConvaTec Inc., Cardinal Health, Integra LifeSciences Corporation, Coloplast Corp., Medtronic, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Burn Care Market Shifts & Advancements
Digital wound assessment platforms are virtualizing traditional bedside evaluation protocols, compressing specialist consultation cycles while generating structured data assets for outcome tracking and reimbursement documentation.
Biosynthetic skin substitutes are virtualizing conventional autograft and allograft procedures by combining engineered collagen scaffolds with antimicrobial silver ion release. Academic medical centers in the United States and university hospitals in Germany are adopting these matrices for partial-thickness thermal injuries at accelerating replacement rates. This virtualization is compressing operating room time requirements and reducing donor site morbidity while expanding treatable patient populations beyond traditional graft candidacy limits.
The FDA's updated medical device classification framework for composite wound care products is accelerating 510(k) clearance timelines for manufacturers with predicate device strategies. This regulatory recalibration is lowering capital requirements for market entry and compressing time-to-revenue for novel dressing technologies. Biologic matrix categories and antimicrobial composite dressings are experiencing the most pronounced clearance velocity improvements, with sponsor companies restructuring regulatory affairs functions to exploit pathway efficiencies.
Hospital procurement consortia are consolidating purchasing authority for advanced wound care products through centralized formulary management and outcome-based vendor selection criteria. Integrated delivery networks in the United States are displacing standalone hospital purchasing autonomy with regional contracting committees that prioritize total cost-of-care metrics over unit price. Germany's university hospital alliances and France's public hospital groups exhibit the most advanced procurement centralization, compressing supplier margins while rewarding manufacturers with robust clinical evidence packages and logistics integration capabilities.
Global Burn Care Market Segmentation
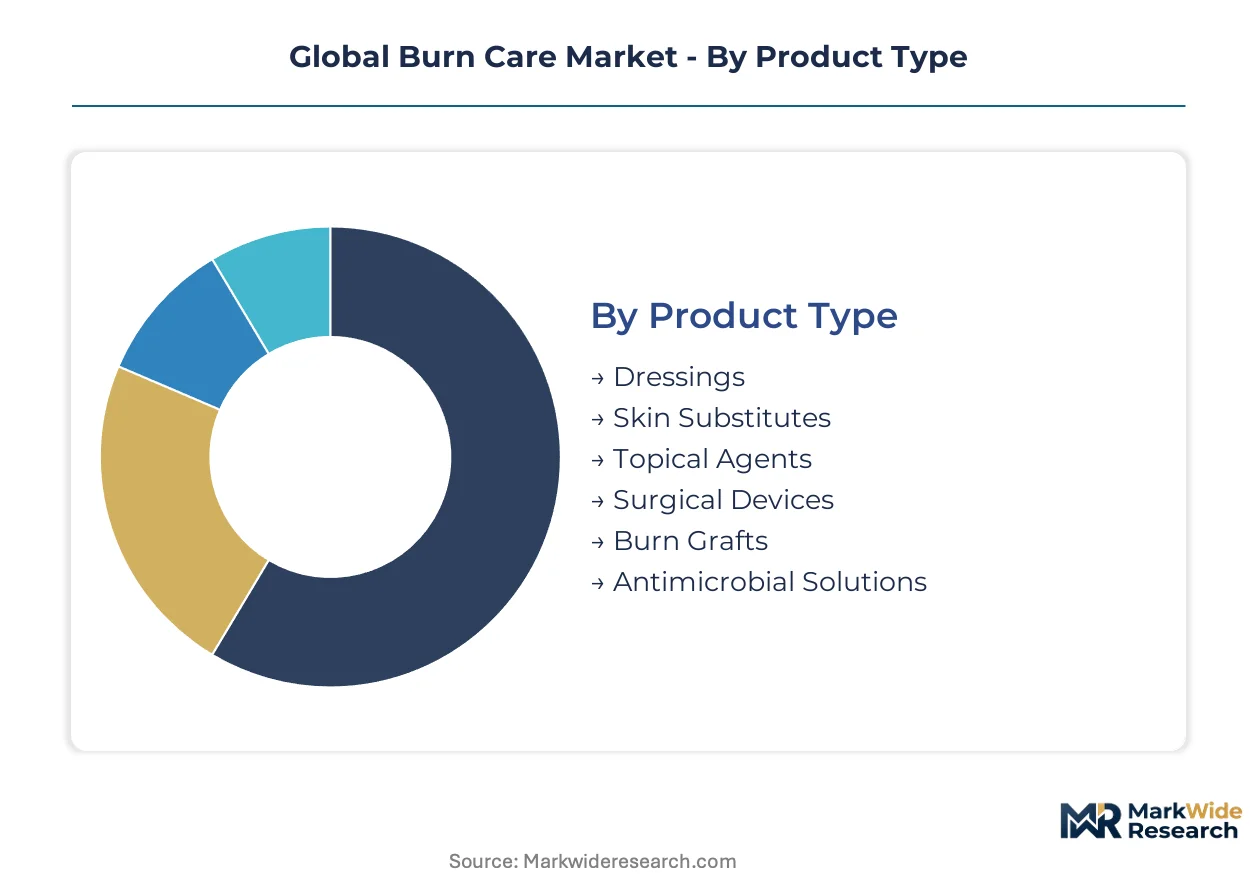
Burn care segmentation reveals distinct margin structures and procurement dynamics across product, application, and delivery channels. Manufacturers must align portfolio investments with the highest-recurrence segments while monitoring channel migration toward outpatient and home settings.
Product Type:
The use-case spectrum spans acute wound stabilization through long-term functional reconstruction, with each product category serving distinct clinical phases and reimbursement profiles.
- Dressings:Advanced hydrofiber and foam dressings maintain moisture balance across partial-thickness wound beds. Hospital procurement networks in Germany prioritize antimicrobial silver-impregnated variants for thermal injury protocols, driven by EMA Medical Device Regulation evidence requirements for infection prevention claims.
- Skin Substitutes:Biosynthetic and biologic matrices replace traditional autografts for full-thickness defects. United States burn centers are expanding dermal regeneration matrix adoption beyond traditional candidacy limits, compressing operating room time while reducing donor site morbidity.
- Topical Agents:Silver sulfadiazine and antimicrobial creams remain standard for superficial thermal injuries.
- Surgical Devices:Dermatomes and wound debridement systems support excisional procedures in specialized burn units.
- Burn Grafts:Autologous and allograft tissues address extensive full-thickness injury reconstruction.
- Antimicrobial Solutions:Irrigation fluids and topical biologics prevent colonization in contaminated wound beds.
The dominant share belongs to Dressings, while Skin Substitutes is closing the gap fastest.
Application:
Volume concentration varies sharply by injury mechanism, with thermal and scald presentations driving emergency department throughput while electrical and radiation cases concentrate in specialized referral networks.
- Thermal Burns:Flame and contact injuries generate the highest procedure volume across emergency and specialized settings. United States hospital-based burn centers are expanding advanced dressing protocols for partial-thickness thermal cases, reducing length of stay through moisture-retentive technologies.
- Chemical Burns:Acid and alkali exposures require specialized decontamination protocols and extended monitoring. Industrial corridor clusters in Germany's Ruhr region and China's Guangdong province concentrate prophylactic procurement for manufacturing workforce protection.
- Electrical Burns:High-voltage injuries necessitate multidisciplinary reconstruction approaches.
- Radiation Burns:Oncology-related tissue damage demands coordinated radiation oncology and wound care management.
- Scald Burns:Pediatric and elderly populations dominate this category with high recurrence potential.
- Frostbite:Cold injury management overlaps with vascular and plastic surgery referral pathways.
Thermal Burns commands the deepest procedure volume, though Outpatient Treatment models for Scald Burns are expanding most quickly.
End User:
Facility type determines product specification, with dedicated burn centers driving biologic matrix adoption while emergency units concentrate high-volume dressing consumption.
- Burn Centers:Dedicated facilities in the United States and Germany anchor biologic skin substitute procurement through standardized wound protocols. These centers generate the highest per-patient revenue through reconstructive surgery integration.
- Specialized Clinics:Outpatient wound care facilities are capturing procedure migration from hospital settings. France's public hospital group networks are expanding clinic-based follow-up capacity to reduce central burn center congestion.
- Rehabilitation Centers:Long-term functional recovery and scar management services.
- Emergency Units:Triage and initial stabilization for acute presentations.
- Research Institutes:Clinical trial sites for novel matrix and dressing technologies.
- Trauma Units:Multidisciplinary coordination for polytrauma with burn components.
Burn Centers retain the dominant procurement authority, while Specialized Clinics are gaining share fastest through outpatient protocol expansion.
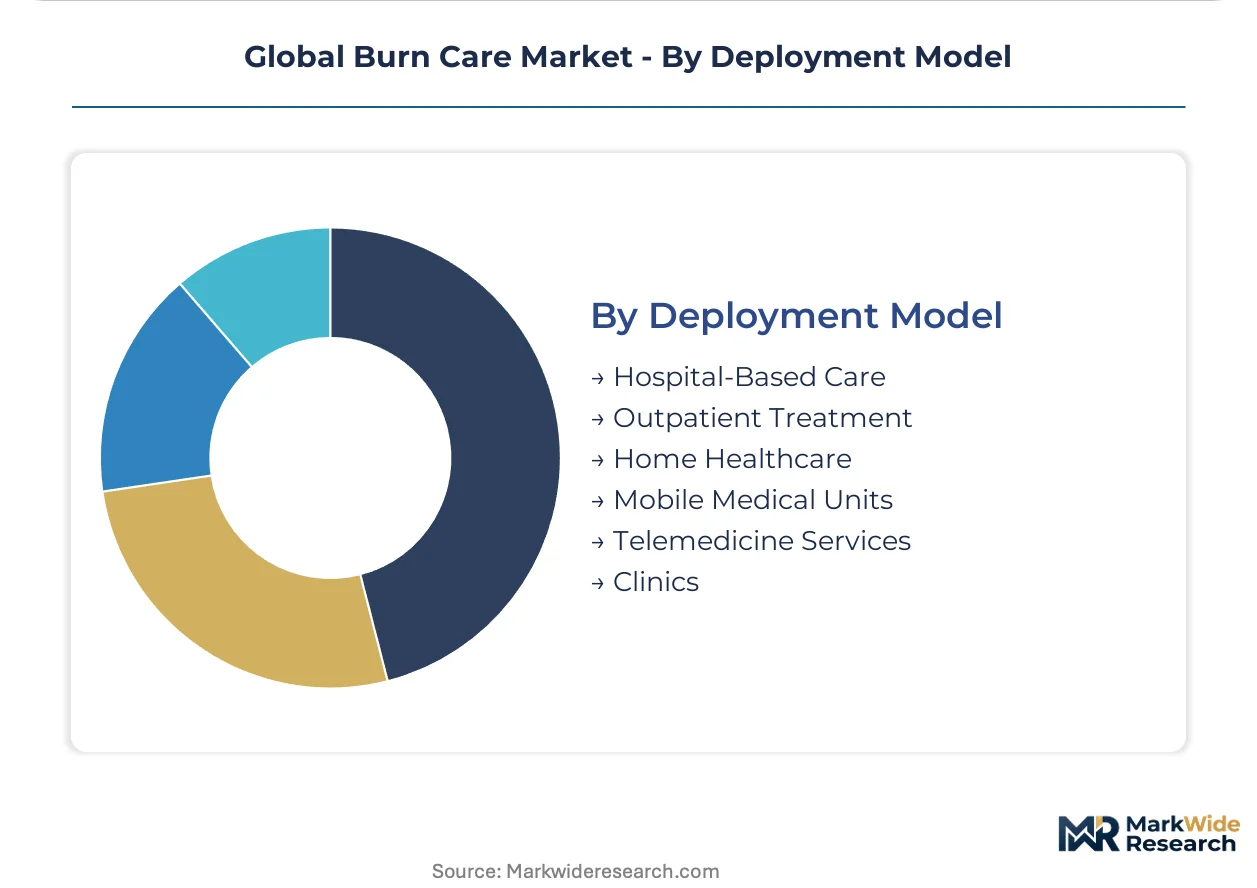
Deployment Model:
Care delivery location is restructuring around patient acuity, with advanced home-care technologies enabling channel migration from inpatient to community settings.
- Hospital-Based Care:Inpatient burn centers in the United States maintain the highest acuity case concentration. Germany's university hospital alliances are consolidating purchasing authority through centralized formulary management for advanced wound products.
- Outpatient Treatment:Advanced dressing technologies are reducing hospital length of stay for partial-thickness injuries. China's expanded domestic manufacturing capacity for antimicrobial materials is narrowing supply constraints for clinic network procurement.
- Home Healthcare:Patient-administered dressing protocols with remote specialist oversight.
- Mobile Medical Units:Field response capacity for mass casualty and remote access scenarios.
- Telemedicine Services:Remote wound assessment platforms extending specialist consultation reach.
- Clinics:Community-based follow-up and chronic wound management services.
Hospital-Based Care maintains the dominant revenue share, while Outpatient Treatment is climbing the fastest as home-care dressing technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's updated medical device classification framework for skin substitutes anchors North American market entry velocity, while EMA's Medical Device Regulation and China's NMPA standards create divergent compliance pathways across the three dominant geographies.
United States
Hospital-based burn centers in Texas and California are expanding advanced wound care protocols for partial-thickness thermal injuries. FDA's streamlined 510(k) clearance pathway is compressing product development timelines for biologic matrix manufacturers. The Texas Medical Center in Houston anchors the highest concentration of specialized burn units, driving procurement standardization for dermal regeneration matrices.
Germany
University hospital alliances in North Rhine-Westphalia and Bavaria maintain Europe's highest density of dedicated burn centers per capita. EMA Medical Device Regulation enforcement elevates clinical evidence requirements for antimicrobial dressing claims. The Ruhr industrial corridor concentrates prophylactic procurement networks for chemical burn workforce protection in manufacturing sectors.
China
Domestic manufacturing expansion in Guangdong and Jiangsu provinces is narrowing supply constraints for antimicrobial wound care materials. NMPA's harmonization with ISO 13485 standards is accelerating quality certification for local producers. Guangzhou's medical device industrial cluster is scaling biosynthetic dressing production to reduce import dependency for hospital procurement networks.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas are elevating scald burn incidence among elderly populations requiring outpatient treatment protocols. PMDA's medical device review standards prioritize clinical evidence for advanced dressing technologies. The Kansai region's university hospital networks are piloting telemedicine-integrated wound assessment platforms for rural specialist consultation extension.
India
Thermal and electrical burn presentations dominate emergency department throughput in Maharashtra and Tamil Nadu industrial corridors. CDSCO's medical device rules alignment with global standards is streamlining import pathways for biologic skin substitutes. Mumbai's public hospital networks are expanding specialized burn unit capacity through central government health mission funding.
Global Burn Care Market Competitive Landscape
Capability concentration sits with biologic matrix specialists possessing robust clinical trial portfolios; scale advantage sits with diversified medical technology conglomerates with established hospital procurement relationships. The market structure exhibits tiered consolidation, with premium-tier manufacturers commanding burn center formulary positions while mid-tier dressing suppliers compete on antimicrobial feature differentiation. Strategic archetypes include biologic scaffold innovators, antimicrobial composite specialists, and integrated wound care platform operators. Dominant competitive moves encompass regulatory affairs function restructuring to exploit 510(k) pathway efficiencies and outcome-based contracting alignment with integrated delivery network procurement committees.
Among diversified health technology conglomerates, 3M and Johnson & Johnson exemplify scale-driven platform operators with cross-category hospital supply relationships. Smith & Nephew occupies a position within the biologic matrix specialist tier, representing European leadership in biosynthetic skin substitute development. These three entities anchor distinct competitive vectors—materials science breadth, consumer health integration, and wound care specialization—without overlapping strategic positioning.
| Leading Market Players |
|---|
| 3M |
| Smith & Nephew |
| Mölnlycke Health Care AB |
| ConvaTec Inc. |
| Cardinal Health |
| Integra LifeSciences Corporation |
| Coloplast Corp. |
| Medtronic |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Single-source dependency on porcine and bovine collagen suppliers determines both the premium-to-economy spread in biologic matrix pricing and the geographic clustering of manufacturing assets around agricultural processing hubs. Buyers face tiered procurement economics where hospital formulary committees leverage volume concentration to compress margins on commoditized antimicrobial dressings while accepting premium pricing for cold-chain-dependent living cell therapies.
Pricing Analysis
German hospital procurement networks command lower unit pricing on silver-impregnated hydrofiber dressings than United States integrated delivery networks due to centralized formulary management and outcome-based vendor selection criteria. Three-tier pricing structure across premium, standard, and economy levels separates biologic skin substitutes with full-thickness reconstruction claims from biosynthetic matrices and conventional antimicrobial dressings. Pricing pressure stems from procurement committee consolidation favoring total cost-of-care metrics over unit price. Burn centers demonstrate lowest price sensitivity for dermal regeneration matrices, while outpatient clinics exhibit highest sensitivity for recurring dressing purchases.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for antimicrobial dressing manufacturers sourcing woven substrates. Manufacturing concentration in China's Guangdong and Jiangsu provinces, Germany's North Rhine-Westphalia, and the United States' Texas Medical Center corridor shapes regional procurement lead times. Raw material dependencies span porcine dermal tissue, bovine collagen, silver ion antimicrobial compounds, and synthetic polymer scaffolds. Single-source vulnerability in agricultural collagen supply creates price volatility tied to livestock disease controls. Distribution runs through hospital procurement consortia and specialized medical device distributors with temperature-controlled logistics capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The burn care market rewards manufacturers possessing integrated quality management systems and established clinical evidence portfolios, while penalizing those without ISO 13485 certification or robust trial data. Specialized surgeon training capacity constraints create bottlenecks that determine which product categories can scale procedure volumes.
For Market Incumbents: Insulate formulary positions in United States burn centers by deepening backward integration into collagen sourcing and expanding ISO 13485-certified manufacturing capacity in Germany's university hospital alliance regions. Defend against biosynthetic substitute displacement by accelerating predicate device strategies under FDA's streamlined 510(k) pathway. Prioritize outcome-based contracting alignment with integrated delivery network procurement committees to lock out emerging antimicrobial composite specialists. For New Entrants and Emerging Players: Establish a beachhead in China's outpatient clinic networks by leveraging domestic manufacturing cost advantages for antimicrobial dressing production targeting partial-thickness thermal injuries. Target France's public hospital group expansion of clinic-based follow-up capacity as the most penetrable European entry point. Pursue telemedicine-integrated wound assessment platform partnerships as the primary go-to-market angle to bypass entrenched hospital supply relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors biologic scaffold innovators with robust clinical trial portfolios over undifferentiated dressing manufacturers. Long-term viability over the projection horizon rests on regulatory affairs capabilities and cold-chain logistics infrastructure rather than commodity scale. Monitor FDA 510(k) clearance velocity trends and EMA Medical Device Regulation enforcement intensity as the critical inflection signals for portfolio rebalancing toward premium-tier matrix specialists.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market entry for biologic matrix manufacturers with predicate device strategies in United States burn centers. |
| CE Marking Pathway | Enables EMA Medical Device Regulation compliance for antimicrobial dressing claims across German university hospital networks. |
| Hospital System Partnership | Secures formulary positioning through outcome-based contracting with Texas Medical Center procurement committees. |
| Backward Integration | Captures margin from porcine collagen supply volatility while ensuring cold-chain integrity for living cell therapies. |
| Reimbursement Strategy | Aligns biologic skin substitute coding with CMS Medicare and commercial payer frameworks for reconstructive procedures. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with burn surgeons, hospital procurement managers, biomedical engineers, and GPO contracts directors; and secondary validation against FDA 510(k) filings, EMA Medical Device Regulation submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up triangulation across product segment volumes and top-down macroeconomic overlay produced convergent market sizing estimates.
Forecast inputs incorporated procedure volume modeling by injury mechanism, deployment model migration rates, and regulatory pathway velocity across the analysis window. Segmentation dimensions spanned product type, application, end-user facility category, and regional regulatory cluster. CAGRs derived from logistic adoption curves for biosynthetic substitutes and linear extrapolation for mature dressing categories. Industry-specific inputs included surgeon fellowship pipeline capacity and cold-chain infrastructure expansion rates.
Macroeconomic conditions sit as an overlay; deviation in livestock commodity prices, healthcare reimbursement policy, or trade tariff schedules would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory clearance timelines and procurement centralization momentum. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Negative Pressure Wound Therapy Market
Wound Care
Wound Debridement Products Market
Wound Care
Advanced Wound Management Market
Wound Care
Global Compression Bandages Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
Biopatches Market
Wound Care
Liquid Bandages Market
Wound Care
Collagen Dressings Market
Wound Care
Philippines Wound Care Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Advanced Wound Care Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Global Traditional Wound Management Market
Wound Care
Burn Care Centers Market
Wound Care
Japan Wound Care Management Devices Market