
 Medical X-Ray Equipment and Imaging Software Market | 2026-2036
Medical X-Ray Equipment and Imaging Software Market Size, Share, and Industry Trends Forecast 2026-2036
Medical X-Ray Equipment and Imaging Software Market Foresight
EU MDR is expanding pre-market clinical evidence requirements for X-ray device manufacturers. Siemens Healthineers leverages its installed base of angiography suites to sustain service revenue across European hospital networks. GE Healthcare anchors its position through captive supply of flat panel detectors and proprietary image reconstruction algorithms. Fujifilm competes in mobile radiography by specializing in lightweight, battery-powered systems for emergency departments and intensive care units.
Medical X-ray equipment and imaging software encompasses ionizing radiation generators operating at 20-150 kVp, coupled with digital detector arrays and post-processing algorithms that enhance contrast resolution for diagnostic interpretation. The primary commercial purpose centers on non-invasive visualization of bone structures, soft tissue differentiation, and real-time procedural guidance across clinical settings. Digital radiography leads product type revenue due to replacement demand from aging computed radiography fleets in hospital radiology departments. Flat panel detector technology captures the fastest growth trajectory as manufacturers shift from amorphous silicon to cesium iodide direct-conversion layers for improved dose efficiency. Oncology applications concentrate margin pools where fused PET-CT and image-guided radiation therapy systems command premium pricing from proton therapy centers.
FDA 21 CFR Part 1020 governs X-ray system performance standards and annual compliance testing, while the EU MDR requires notified body involvement for Class IIa and above radiological devices. The FDA's recent emphasis on cybersecurity premarket guidance for networked imaging software is reshaping vendor R&D allocation toward embedded threat detection. IEC 60601-2-54 establishes international safety benchmarks for pediatric radiography dose limits, pressuring OEMs to integrate automatic exposure control with patient-size-specific algorithms. Stakeholders must weigh regulatory compliance costs against the strategic imperative to deploy artificial intelligence-enabled diagnostic workflows before reimbursement pathways solidify.
Market Dynamics
Flat panel detector conversion from amorphous silicon to cesium iodide direct-conversion layers is compressing dose efficiency benchmarks and forcing OEMs to redesign tube-generator architectures around lower kVp operating ranges.
Growth Catalysts
- FDA 21 CFR Part 1020 enforcement:Annual compliance testing mandates for diagnostic imaging devices accelerate hospital radiology department replacement cycles for aging computed radiography fleets.
- Oncology imaging centers:Fused PET-CT and image-guided radiation therapy systems command premium procurement allocations from proton therapy centers seeking real-time procedural guidance capabilities.
- EU MDR pre-market clinical evidence expansion:Notified body involvement requirements for Class IIa radiological devices elevate barriers for marginal competitors and consolidate procurement toward established installed-base vendors.
Market Restraints
- Flat panel detector supply concentration:Captive production of cesium iodide direct-conversion layers by integrated OEMs limits third-party sourcing options and inflates component lead times.
- Cybersecurity premarket validation costs:FDA guidance for networked imaging software threat detection diverts R&D capital from image reconstruction algorithm development.
- IEC 60601-2-54 pediatric dose limits:Mandatory automatic exposure control integration with patient-size-specific algorithms adds firmware complexity and extends type-testing timelines.
Strategic Opportunities
- Mobile radiography in intensive care units:Lightweight battery-powered systems address unmet demand for bedside imaging in emergency departments lacking fixed radiography infrastructure.
- AI-enabled diagnostic workflow deployment:Reimbursement pathway uncertainty creates first-mover advantage windows for vendors establishing clinical evidence libraries ahead of formal coding.
- Academic medical center fluoroscopy replacement:United States teaching hospitals anchor demand for angiography suites with advanced 3D rotational capabilities.
Industry Challenges
- Embedded cybersecurity engineering talent scarcity:FDA premarket guidance requirements exceed current workforce supply for threat detection firmware development.
- Legacy computed radiography-to-digital radiography migration complexity:PACS integration and technologist retraining extend deployment timelines and strain hospital IT resources.
- Dual regulatory track synchronization:Parallel FDA 21 CFR Part 1020 and EU MDR conformity assessment processes fragment certification resources and delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical X-Ray Equipment and Imaging Software Market |
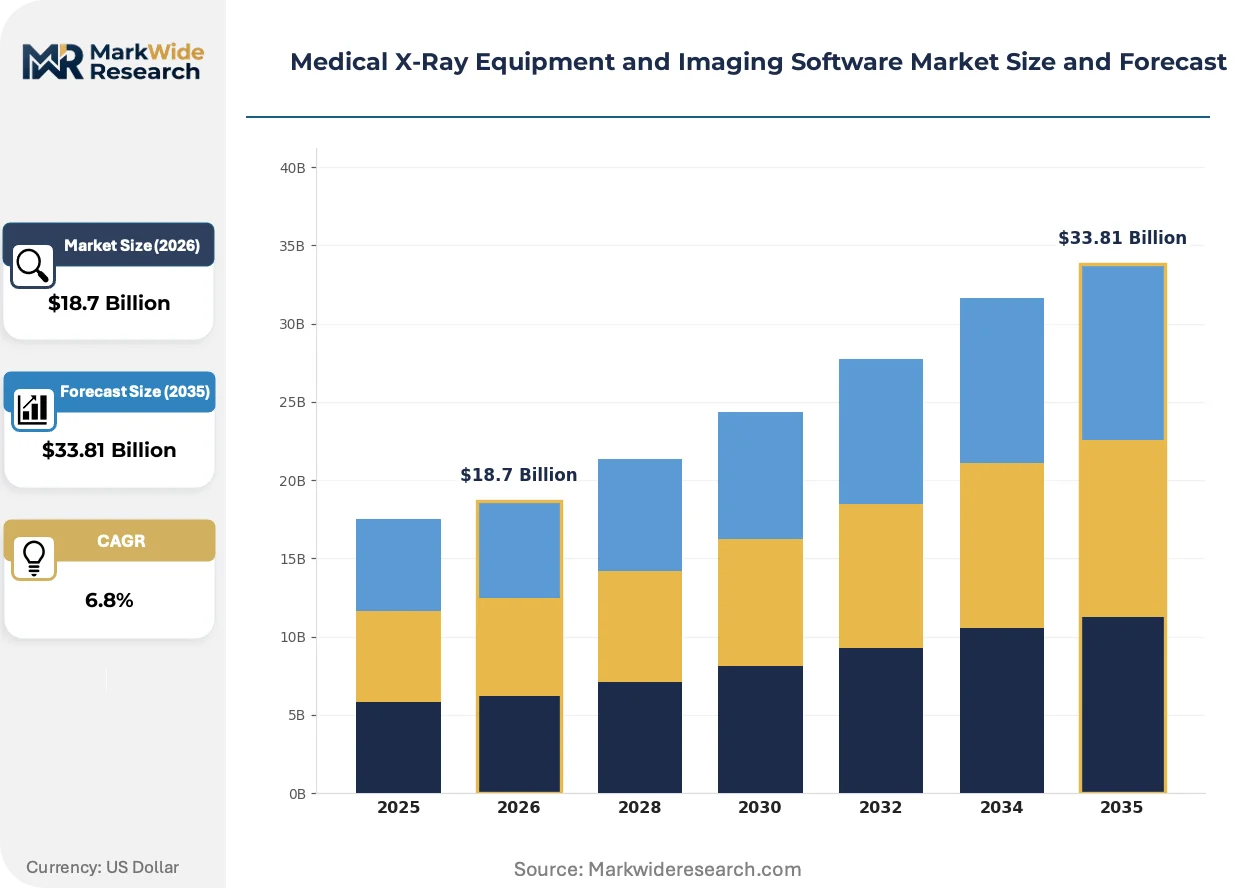
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computed Radiography, Digital Radiography, Mobile X-Ray, Fluoroscopy Application: Orthopedics, Cardiovascular, Dental Imaging, Oncology Technology: X-Ray Tube, Flat Panel Detector, Image Processing Software, Laser Imaging End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips, Carestream Health, Canon Medical Systems, Fujifilm, Hitachi, Shimadzu Corporation, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical X-Ray Equipment and Imaging Software Market Shifts & Advancements
Artificial intelligence integration into image reconstruction and diagnostic interpretation workflows is compressing radiologist reading times and redefining competitive differentiation beyond hardware specifications.
Photon-counting detector technology is rewriting dose-efficiency benchmarks for spectral imaging applications. Academic medical centers in Germany and Japan are piloting cadmium telluride sensor arrays for cardiac CT angiography. This architecture is enabling material decomposition at sub-mSv exposure levels previously unattainable with energy-integrating detectors.
EU MDR cybersecurity annex requirements are mandating software bill of materials disclosure and post-market surveillance protocols for networked imaging devices. European notified bodies are rejecting technical documentation lacking structured threat modeling for remote service access ports. Class IIa radiological device manufacturers are responding by segregating imaging acquisition engines from hospital network infrastructure through hardware-enforced isolation.
After-sales service unbundling is fragmenting traditional equipment procurement contracts. United States hospital systems are negotiating detector-array replacement schedules and software maintenance as separate line items rather than bundled ten-year agreements. This pattern concentrates margin pressure on OEMs while creating openings for independent service organizations specializing in flat panel detector refurbishment.
Medical X-Ray Equipment and Imaging Software Market Segmentation
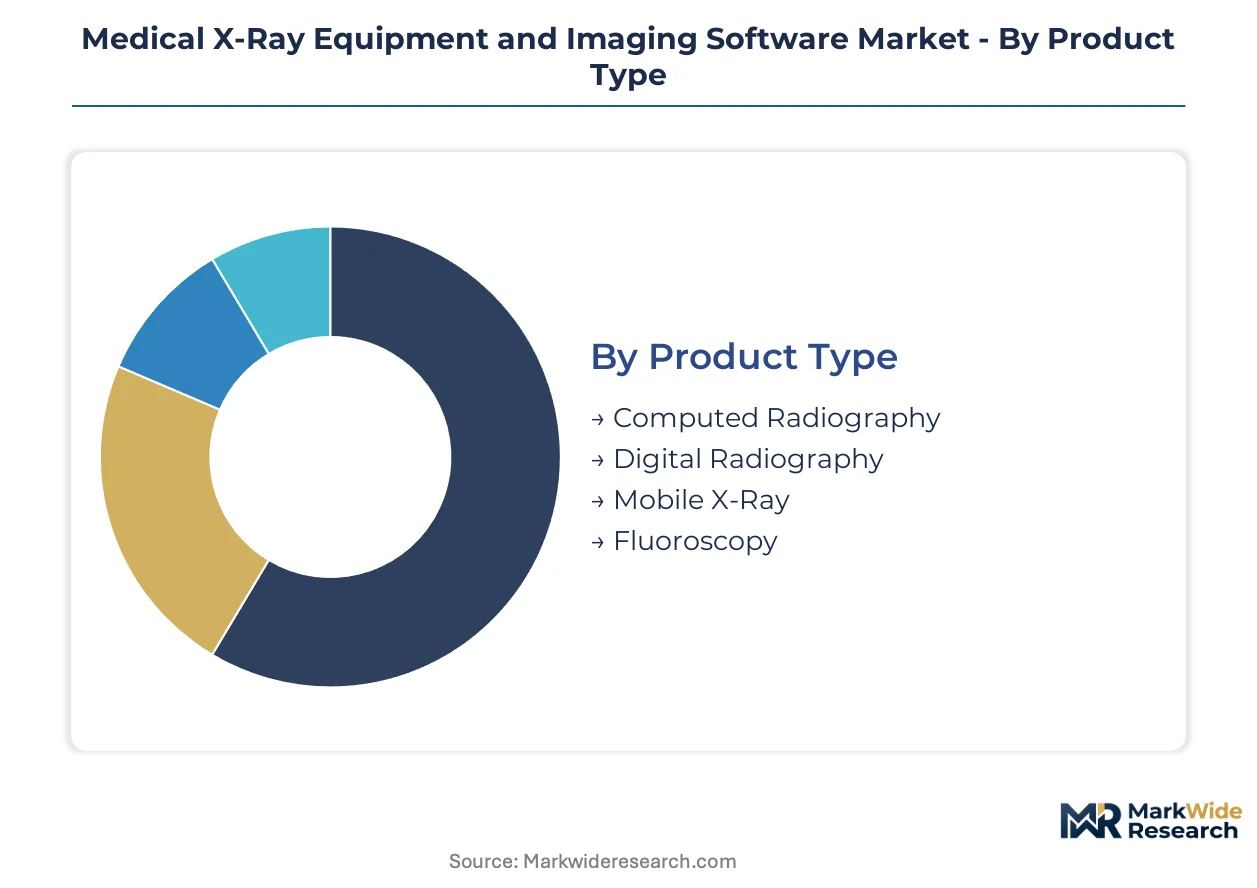
Segmentation in medical X-ray equipment reveals divergent capital deployment strategies across hardware, software, and service layers. Procurement patterns vary sharply between fixed-installation systems requiring infrastructure overhauls and portable units targeting point-of-care expansion.
Product Type:
Capital intensity peaks with fixed-room digital radiography installations, where construction, shielding, and PACS integration can exceed equipment costs.
- Digital Radiography:Fixed-room systems with cesium iodide flat panel detectors dominate hospital procurement budgets. United States academic medical centers anchor replacement demand as FDA quality assurance mandates accelerate retirement of aging computed radiography fleets.
- Mobile X-Ray:Battery-powered units with wireless detector transmission enable bedside imaging in intensive care units lacking fixed infrastructure. Fujifilm specializes in lightweight architectures for emergency departments where space constraints prevent permanent installation.
- Computed Radiography:Cassette-based photostimulable phosphor systems face accelerated obsolescence from regulatory pressure and inferior workflow efficiency.
- Fluoroscopy:Real-time X-ray systems with image intensifiers or flat panel detectors support interventional procedures and angiography suites.
Most installed capacity flows through Digital Radiography. Expansion is steepest in Mobile X-Ray.
Application:
Procedure volume and reimbursement rates create tiered investment returns across clinical specialties.
- Oncology:Fused PET-CT and image-guided radiation therapy systems command premium pricing from proton therapy centers. Real-time procedural guidance capabilities justify capital allocation despite extended procurement cycles.
- Orthopedics:Weight-bearing digital radiography and extremity imaging concentrate demand in ambulatory surgery centers. Siemens Healthineers leverages installed base relationships to sustain service revenue across European hospital networks.
- Cardiovascular:Cardiac catheterization laboratories require angiography suites with 3D rotational capabilities and advanced image reconstruction algorithms.
- Dental Imaging:Cone-beam computed tomography and intraoral sensors serve private practice workflows with lower per-unit capital thresholds.
Revenue concentration centers on Oncology. Patient throughput advantages are expanding fastest in Orthopedics.
Technology:
Component-level supply constraints and R&D intensity determine vendor margin structures.
- Flat Panel Detector:Direct-conversion cesium iodide layers are displacing amorphous silicon architectures for dose efficiency gains. GE Healthcare anchors market position through captive production and proprietary detector supply.
- Image Processing Software:AI-enabled diagnostic workflows and embedded cybersecurity features divert R&D capital from hardware development. FDA premarket guidance for networked imaging threat detection extends validation timelines.
- X-Ray Tube:Rotating anode generators with thermal management systems determine system uptime and maintenance schedules.
- Laser Imaging:Film-based output systems persist in regulatory environments with delayed digital infrastructure adoption.
Supply bottleneck severity peaks with Flat Panel Detector. Capability investment is accelerating most rapidly in Image Processing Software.
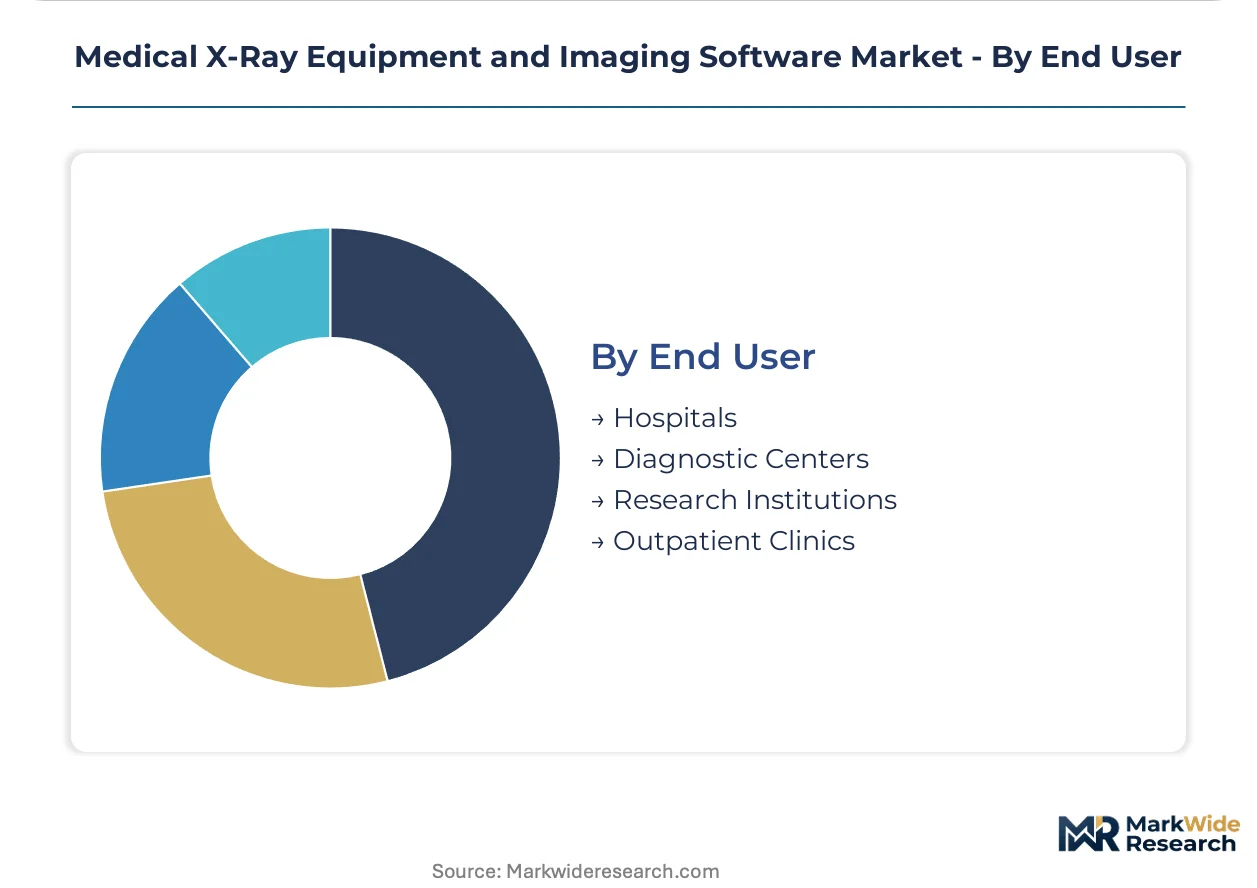
End User:
Procurement authority and capital access create distinct purchasing patterns across facility types.
- Hospitals:Radiology departments consolidate purchasing power for multi-modality installations. EU MDR pre-market clinical evidence requirements favor established vendors with installed base service relationships.
- Diagnostic Centers:Independent imaging facilities prioritize throughput optimization and rapid patient turnaround over advanced feature sets.
- Research Institutions:Academic medical centers pilot photon-counting detector technology and spectral imaging applications.
- Outpatient Clinics:Limited capital budgets drive leasing arrangements and refurbished equipment procurement for basic radiography services.
Capital deployment volume concentrates in Hospitals. Procurement flexibility is expanding fastest in Diagnostic Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiological engineering talent clusters in Germany, Japan, and the United States anchor global equipment development. These concentrations shape regional procurement patterns and regulatory influence across diagnostic imaging markets.
United States
Academic medical centers in Boston and the Research Triangle drive fluoroscopy replacement cycles for advanced angiography suites. FDA 21 CFR Part 1020 enforcement tightens annual compliance testing mandates across hospital radiology departments. The Cleveland Clinic and Mayo Clinic anchor demand for PET-CT fusion systems in proton therapy centers.
Germany
Precision engineering capabilities in Bavaria and Baden-Württemberg sustain flat panel detector manufacturing clusters. EU MDR pre-market clinical evidence requirements elevate barriers for Class IIa radiological device entrants. Siemens Healthineers leverages its Erlangen headquarters to service installed base relationships across European hospital networks.
Japan
Photon-counting detector R&D concentrates in Tokyo and Osaka metropolitan areas for spectral imaging applications. METI funding accelerates cadmium telluride sensor array pilots in cardiac CT angiography. Canon Medical Systems and Shimadzu Corporation anchor manufacturing in Kanto and Kansai regions.
China
Domestic procurement quotas favor NMPA-registered manufacturers for hospital digital radiography systems. Tier-one cities including Beijing, Shanghai, and Guangzhou concentrate replacement demand from aging computed radiography fleets. Local producers capture mid-tier mobile X-ray segments while imported systems retain premium fluoroscopy positions.
India
Diagnostic center expansion in Maharashtra and Karnataka drives demand for cost-optimized digital radiography. CDSCO medical device rules tighten quality assurance documentation for imported imaging equipment. Hyderabad and Bengaluru clusters specialize in imaging software development and PACS integration services.
Medical X-Ray Equipment and Imaging Software Market Competitive Landscape
The competitive structure tilts toward integrated OEMs with captive detector production and established service networks. Vendor concentration remains pronounced at the premium tier where installed base relationships and regulatory compliance capabilities create defensive moats. Three archetypes dominate: diversified conglomerates with healthcare divisions, pure-play diagnostic imaging specialists, and regional champions with government procurement access. Competitive moves center on detector technology licensing partnerships and cybersecurity firmware co-development with hospital IT departments.
Among diversified healthcare conglomerates, Siemens Healthineers and GE Healthcare exemplify integrated OEM archetypes with upstream control over flat panel detector supply chains. Fujifilm occupies a position within the mobile radiography specialist tier, representing lightweight system architecture focused on emergency department workflows. These three anchors demonstrate how competitive positioning diverges between fixed-installation infrastructure players and point-of-care mobility specialists.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Carestream Health |
| Canon Medical Systems |
| Fujifilm |
| Hitachi |
| Shimadzu Corporation |
| Hologic |
| Others |
Supply & Pricing Matrix
Flat panel detector conversion from amorphous silicon to cesium iodide direct-conversion layers simultaneously compresses dose efficiency benchmarks and concentrates component sourcing among integrated OEMs with captive production capabilities. This technology transition elevates capital requirements for new entrants while compressing margins for third-party detector assemblers lacking upstream material control.
Pricing Analysis
The bundled-vs-unbundled service split defines current pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates angiography suites with 3D rotational capabilities from basic digital radiography systems and refurbished mobile units. Price differentiation hinges on FDA 510(k) clearance tier and installed base service contract duration. Pricing pressure stems from after-sales service unbundling as United States hospital systems negotiate detector-array replacement schedules separately from equipment procurement. Diagnostic centers exhibit highest price sensitivity due to throughput-dependent revenue models, while proton therapy centers absorb premium pricing for real-time procedural guidance capabilities.
Supply Chain Analysis
Radiological engineering talent scarcity in Bavaria, Baden-Württemberg, and Tokyo metropolitan areas constrains flat panel detector production scaling and extends firmware development timelines. Manufacturing gravity centers on Germany, Japan, and the United States for precision detector assembly and tube-generator fabrication. Supply chains draw from cesium iodide crystal growers, amorphous silicon foundries, and tungsten-rhenium anode suppliers. Single-source vulnerability concentrates in direct-conversion layer deposition equipment held by two European vendors. Distribution runs through hospital GPO contracts in North America and direct OEM service networks across European hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Medical X-Ray Equipment and Imaging Software Market represents a late-cycle quality story where academic medical center demand for photon-counting detector technology and AI-enabled diagnostic workflows shifts procurement toward premium specifications despite extended replacement cycles.
For Market Incumbents: Deploy captive flat panel detector production as the primary lever to defend margin position against independent service organizations refurbishing legacy detector arrays. Siemens Healthineers and GE Healthcare should accelerate firmware development for embedded cybersecurity threat detection ahead of FDA premarket guidance finalization, while consolidating procurement influence through multi-modality installed base service contracts that bundle angiography suite maintenance with digital radiography detector replacement schedules. For New Entrants and Emerging Players: EU MDR pre-market clinical evidence requirements in Europe open a window for cybersecurity firmware specialists to partner with established OEMs lacking embedded engineering talent. Target mobile radiography in Indian diagnostic centers and Chinese tier-two cities where cost-optimized digital radiography systems face less stringent premium-tier competition. Pursue software companion development for AI-enabled diagnostic workflows ahead of reimbursement pathway solidification, establishing clinical evidence libraries through academic medical center pilot programs. For Investors and Strategic Acquirers: Valuations sit cheapest among independent service organizations specializing in flat panel detector refurbishment and PACS integration services. Long-term viability across the analysis window favors vendors with upstream control over cesium iodide direct-conversion layer supply and established cybersecurity firmware capabilities. Watch FDA premarket guidance finalization timing as the inflection indicator for R&D capital reallocation toward threat detection engineering.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body involvement elevates barriers for Class IIa radiological device entrants. |
| Hospital System Partnership | Academic medical center pilot programs establish clinical evidence libraries for AI-enabled diagnostic workflows. |
| Software Companion Development | FDA cybersecurity premarket guidance diverts R&D capital toward embedded threat detection firmware. |
| Reimbursement Strategy | First-mover advantage windows open for vendors establishing evidence ahead of formal coding pathways. |
| Backward Integration into Detectors | Captive cesium iodide direct-conversion layer production secures supply against third-party sourcing constraints. |
Research Methodology
Direct dialogue with hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and radiology department directors grounded qualitative insights across the primary research phase. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation requirements, hospital procurement contract filings, and CMS Medicare imaging reimbursement schedules. Bottom-up equipment shipment estimates triangulated against top-down radiology department capital budget surveys.
Segment-level value outputs across the projection horizon incorporated product type, application, technology, and end user dimensions with regional regulatory cluster overlays. CAGRs derived from replacement cycle analysis for aging computed radiography fleets, proton therapy center expansion pipelines, and mobile radiography point-of-care penetration curves. Forecast inputs included FDA 21 CFR Part 1020 enforcement intensity, EU MDR notified body capacity constraints, and photon-counting detector pilot program scaling timelines.
Revisions become necessary when FDA cybersecurity guidance finalization delays, EU MDR notified body backlogs, or cesium iodide crystal supply disruptions materialize beyond baseline assumptions. Forecasts reflect documented assumptions regarding academic medical center capital allocation priorities and proton therapy center construction pipelines. Material deviation in regulatory enforcement intensity or flat panel detector production yields warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
US Contrast Media Market
Medical Imaging
Middle East and Africa Clinical Trial Imaging Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
Spain Magnetic Resonance Imaging Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
South America Fluoroscopy Market
Medical Imaging
South Africa Mammography Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
North America Digital X-Ray Market
Medical Imaging
Spain Diagnostic Imaging Equipment Market
Medical Imaging
Robotic X-Ray Scanner Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
Portable Ultrasound Market
Medical Imaging
India Magnetic Resonance Imaging Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
Computed Tomography (CT) Scanners Market