
 Automated Contouring Radiotherapy Software Market | 2026-2036
Automated Contouring Radiotherapy Software Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Contouring Radiotherapy Software Market Outlook
Subscription-based licensing and cloud-hosted deployment models are reconfiguring capital requirements for automated contouring radiotherapy software vendors, enabling mid-tier hospitals to access enterprise-grade tools without upfront infrastructure investments. TheraPanacea leverages its Paris-based R&D concentration to sustain algorithm development for multi-site adaptive therapy protocols. Siemens Healthineers anchors its competitive position through hardware-software bundling across imaging and linear accelerator portfolios. Limbus AI differentiates via lightweight integration architectures that reduce IT burden for outpatient clinic deployments.
Automated contouring radiotherapy software encompasses algorithmic platforms that delineate organs-at-risk and target volumes from CT, MRI, or PET datasets using rule-based segmentation, atlas-based mapping, or neural network inference, typically achieving sub-millimeter spatial accuracy to support dose calculation fidelity. Treatment planning modules command the largest revenue share within product type segmentation, as these systems sit at the critical path between imaging acquisition and dose optimization. Deep learning technology within the technology dimension is expanding fastest, driven by convolutional neural network architectures that reduce inter-observer contouring variability below traditional atlas-based methods. Hospitals represent the most concentrated end user segment, though cancer research centers are capturing disproportionate margin pools through grant-funded pilot-to-production conversion contracts.
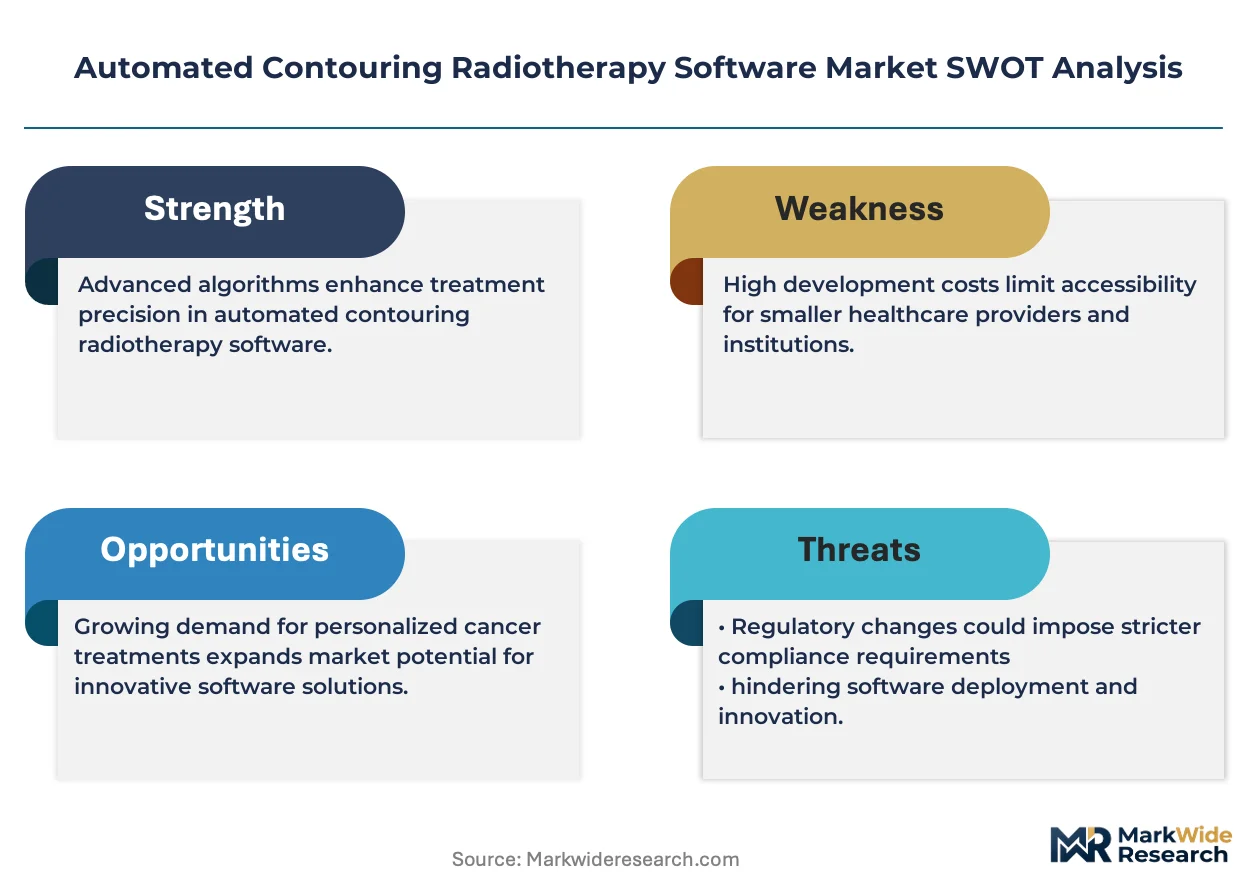
The FDA software-as-a-medical-device framework and EU MDR Class IIa/IIb pathways impose clinical validation and post-market surveillance obligations that extend development timelines and favor vendors with established quality management systems. ISO 13485 certification and IEC 62304 software lifecycle compliance function as de facto market access filters, particularly for European hospital procurement committees. Stakeholders must monitor evolving reimbursement codes for AI-assisted planning across Medicare and national health systems, as payment parity decisions will determine whether automated contouring achieves standard-of-care status or remains a premium add-on.
Market Dynamics
The FDA software-as-a-medical-device framework is compressing validation timelines while elevating compliance burdens, forcing vendors to restructure quality management systems around algorithmic transparency requirements.
Growth Catalysts
- Deep Learning Architectures:Convolutional neural networks are reducing inter-observer contouring variability below atlas-based methods, accelerating clinical acceptance in academic medical centers.
- Cloud Deployment Models:Subscription licensing is eliminating upfront infrastructure barriers, expanding access for mid-tier hospitals previously excluded from enterprise-grade radiotherapy planning tools.
- EU MDR Pathways:Class IIa/IIb certification requirements are creating competitive moats for vendors with established ISO 13485 quality systems, filtering out undercapitalized entrants.
Market Restraints
- Clinical Validation Costs:FDA algorithm-based segmentation requirements demand multi-site prospective studies, elevating development expenditures for neural network training pipelines.
- IT Integration Friction:Legacy PACS and RIS architectures in established cancer centers resist API-based connectivity, prolonging deployment cycles for automated contouring modules.
- Reimbursement Uncertainty:Medicare AI-assisted planning codes remain unsettled, creating payment parity risk that constrains hospital capital allocation to premium software tiers.
Strategic Opportunities
- Adaptive Therapy Protocols:Multi-site fractionation workflows are creating demand for real-time contour adjustment capabilities in proton and MR-linac centers.
- Outpatient Clinic Penetration:Lightweight deployment architectures are opening community oncology practices previously served only by manual contouring services.
- Grant-Funded Conversion:Cancer research centers are piloting automated tools through NIH and EU Horizon funding, creating production-scale reference sites for vendor expansion.
Industry Challenges
- Radiation Oncology Informatics Talent:Shortage of professionals cross-trained in dose calculation physics and machine learning operations is constraining vendor implementation teams.
- IEC 62304 Compliance:Software lifecycle documentation for neural network updates exceeds traditional medical device maintenance protocols, extending release cycles.
- Inter-Observer Variability Litigation:Contouring standardization disputes between AI-generated and physician-reviewed volumes are elevating malpractice exposure for early adopters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Contouring Radiotherapy Software Market |
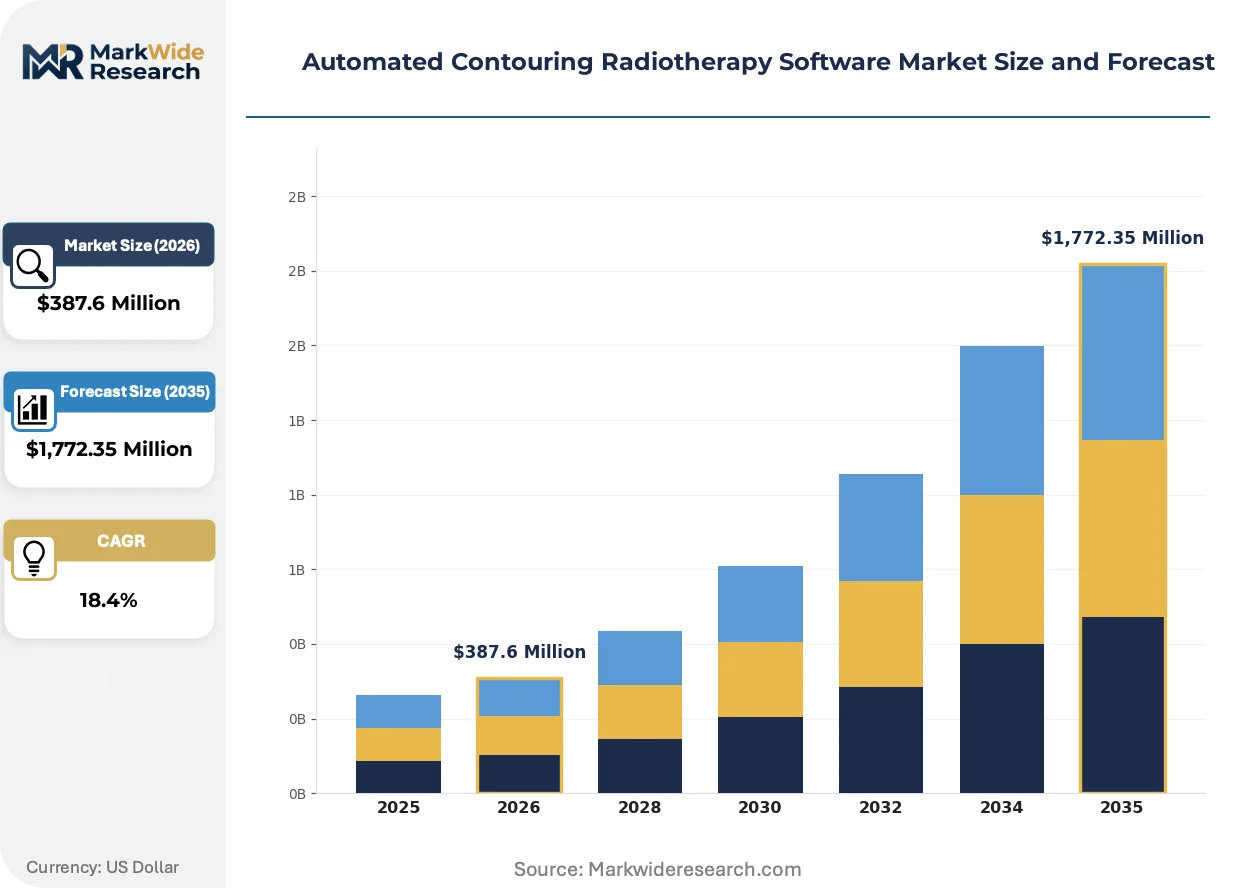
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treatment Planning, Optimization Software, Integration Tools, Patient Management End User: Hospitals, Cancer Research Centers, Outpatient Clinics, Academic Institutions Technology: Artificial Intelligence, Machine Learning, Deep Learning, Image Processing Application: Oncology, Radiation Therapy, Patient Monitoring, Imaging |
| Companies Covered | TheraPanacea, Limbus AI, Synaptiq, Spectronic Medical, GE HealthCare, Radformation, Siemens Healthineers, Brainlab, MVision AI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Contouring Radiotherapy Software Market Strategic Shifts
Algorithmic segmentation is migrating from research environments into production clinical workflows, reshaping how radiation oncology departments structure treatment planning teams and capital budgets.
Self-supervised learning architectures are advancing organ-at-risk delineation accuracy from multimodal imaging inputs. Academic medical centers in the United States are deploying these systems across lung and head-and-neck protocols within eighteen-month procurement cycles. This capability is digitizing the handoff between diagnostic radiology and radiation oncology, compressing planning timelines from days to hours.
The EU AI Act high-risk system classification is imposing conformity assessment obligations on automated contouring platforms deployed in European cancer centers. Vendors must now maintain post-market performance monitoring and algorithmic change control documentation. Treatment planning modules with deep learning components face the steepest compliance burden, driving consolidation toward vendors with dedicated regulatory affairs infrastructure.
Hospital procurement committees are unbundling hardware-software contracts that previously locked contouring tools to specific linear accelerator manufacturers. Independent software vendors are capturing evaluation slots through API-first architectures that interoperate across imaging and delivery platforms. This pattern is most pronounced in United States academic medical centers consolidating vendor relationships into best-of-breed digital workflows.
Automated Contouring Radiotherapy Software Market Segmentation
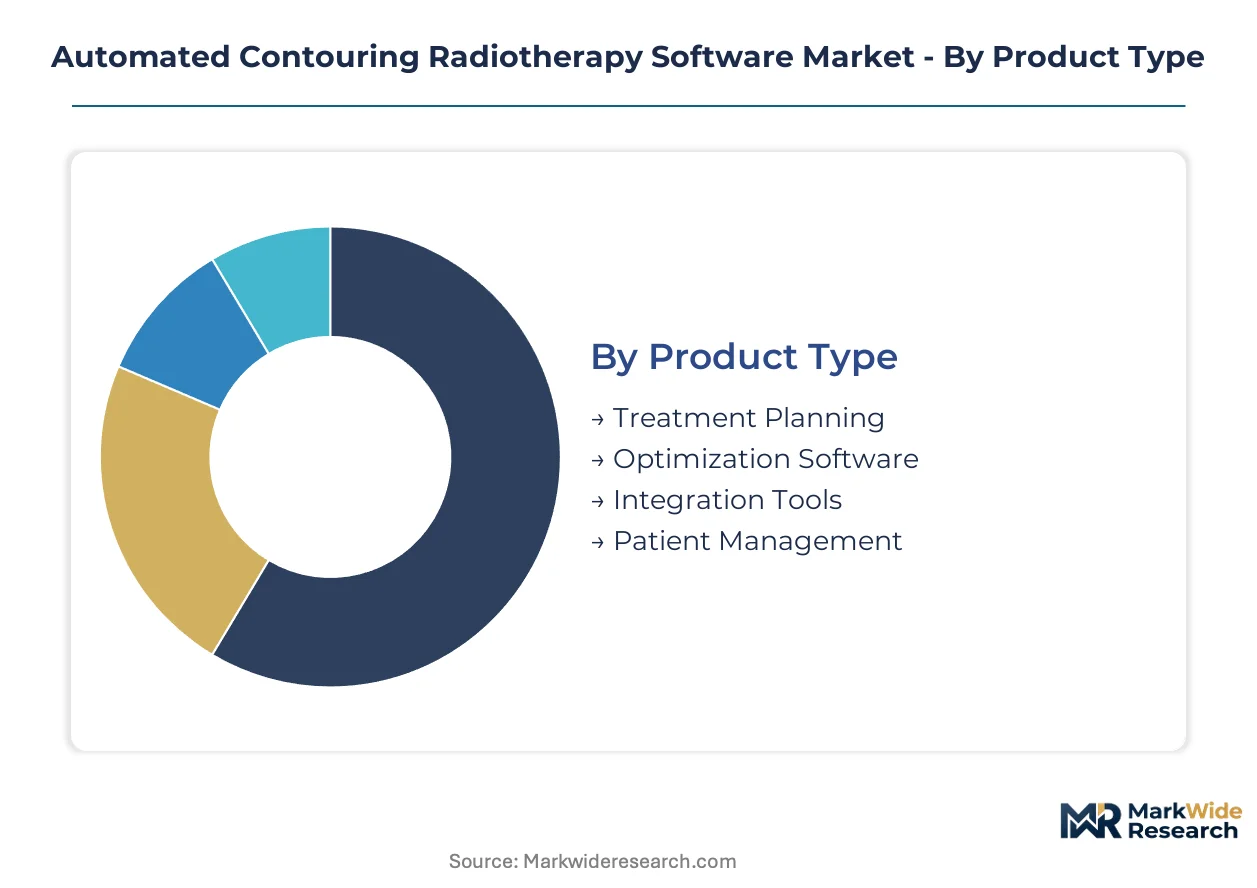
Automated contouring radiotherapy software vendors structure product portfolios around distinct deployment architectures and clinical workflows. Segmentation reveals where algorithmic sophistication commands premium positioning versus where integration simplicity drives procurement decisions.
Product Type:
After-sales service intensity varies sharply across product categories, with treatment planning modules demanding continuous algorithm retraining support while integration tools require lighter ongoing engagement.
- Treatment Planning:These systems execute the critical handoff between imaging acquisition and dose optimization, incorporating convolutional neural network inference engines that achieve sub-millimeter spatial accuracy. Academic medical centers in the United States concentrate procurement here, driven by FDA software-as-a-medical-device validation requirements that favor established quality management systems. By volume, Treatment Planning leads. By growth pace, Integration Tools is ahead.
- Optimization Software:Dose calculation refinement modules reduce planning variability through iterative algorithmic adjustment of beam angles and intensity modulation parameters. Cancer research centers capture disproportionate margin pools through grant-funded pilot-to-production conversion contracts for these tools.
- Integration Tools:API-first architectures that bridge automated contouring outputs to legacy PACS and RIS systems, reducing IT burden for outpatient clinic deployments.
- Patient Management:Workflow orchestration platforms that track contouring task assignment, physician review queues, and treatment readiness milestones across multi-site radiation oncology departments.
Margin concentration follows algorithmic complexity, with neural network-based systems capturing premium pricing over rule-based alternatives.
End User:
Customer archetypes diverge sharply in procurement authority, with hospitals consolidating vendor relationships into integrated digital workflows while research centers operate through grant-funded acquisition channels.
- Hospitals:Integrated delivery networks command the largest revenue concentration, leveraging capital budgets to deploy enterprise-grade contouring platforms across multiple linear accelerator sites. Mid-tier hospitals are accessing these tools through subscription licensing that eliminates upfront infrastructure investments.
- Cancer Research Centers:NIH and EU Horizon funding streams enable pilot-to-production conversion contracts, creating reference sites for vendor expansion into clinical production environments.
- Outpatient Clinics:Community oncology practices previously served only by manual contouring services are adopting lightweight deployment architectures with reduced IT overhead.
- Academic Institutions:Training programs and residency curricula generate demand for educational licensing of contouring platforms, though these contracts carry lower per-seat pricing than clinical production deployments.
Procurement scale tilts toward Hospitals, while Cancer Research Centers generate the steepest expansion trajectory through grant-funded adoption.
Technology:
Development cost structures stratify across algorithmic approaches, with supervised learning pipelines demanding extensive annotated training datasets while image processing methods require less specialized expertise.
- Deep Learning:Convolutional neural network architectures are reducing inter-observer contouring variability below traditional atlas-based methods, accelerating clinical acceptance in academic medical centers. FDA algorithmic transparency requirements and EU AI Act high-risk system classifications impose the steepest compliance burden on these systems.
- Artificial Intelligence:Broad category encompassing rule-based segmentation and atlas-based mapping approaches that preceded neural network methods, still deployed in cost-sensitive settings.
- Machine Learning:Supervised and semi-supervised approaches including random forest and support vector machine classifiers for organ-at-risk delineation.
- Image Processing:Traditional computer vision techniques including edge detection, region growing, and morphological operations for contour initialization.
Deep Learning captures the fastest share gains, while Image Processing retains installed base in legacy deployments.
Application:
Clinical use case specificity determines regulatory pathway complexity, with oncology applications facing the most stringent validation requirements while imaging workflows operate under lighter oversight.
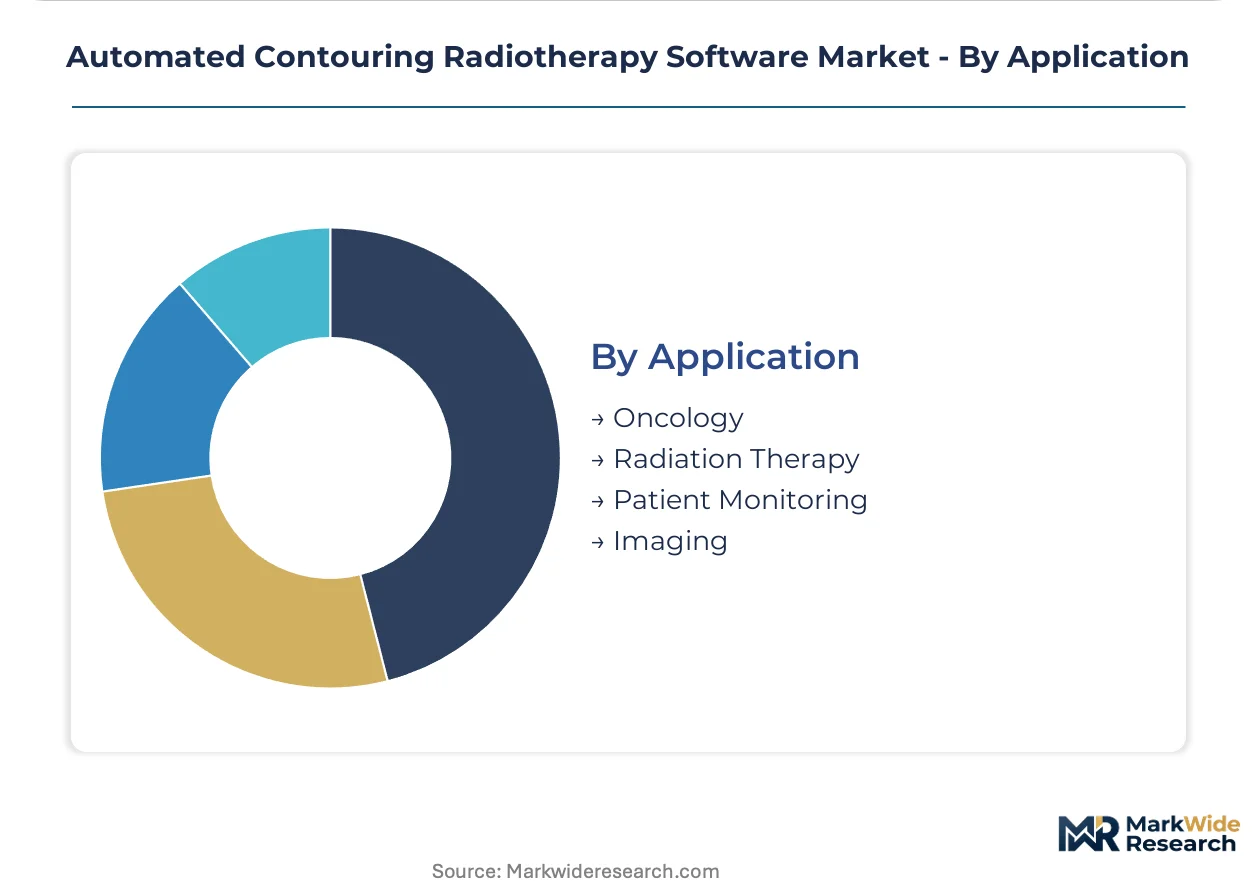
- Oncology:Organ-at-risk and target volume delineation for curative and palliative radiotherapy protocols across lung, head-and-neck, prostate, and central nervous system indications. FDA software-as-a-medical-device framework and EU MDR Class IIa/IIb pathways impose multi-site prospective study requirements.
- Radiation Therapy:Treatment planning-specific workflows encompassing dose calculation, beam optimization, and plan evaluation within the critical path to treatment delivery.
- Patient Monitoring:Adaptive therapy protocols requiring real-time contour adjustment capabilities in proton and MR-linac centers for multi-site fractionation workflows.
- Imaging:Diagnostic radiology handoff applications that digitize the transfer of segmented structures into radiation oncology planning systems.
Oncology dominates current deployment value, with Patient Monitoring climbing fastest on adaptive therapy protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where academic medical centers consolidate procurement into integrated digital workflows, while European markets fragment across national reimbursement systems and regulatory pathways.
United States
Major cancer centers including MD Anderson and Memorial Sloan Kettering are deploying AI-assisted contouring platforms across multi-site linear accelerator networks. The FDA software-as-a-medical-device framework imposes algorithmic transparency requirements that extend validation timelines for neural network-based segmentation tools. Boston and Houston clusters concentrate vendor reference sites where grant-funded pilot programs convert to production-scale contracts.
Germany
University hospitals in Heidelberg and Munich are integrating automated contouring into proton therapy and MR-linac workflows for adaptive radiotherapy protocols. The EU MDR Class IIa/IIb certification pathway and BfArM post-market surveillance obligations favor vendors with established ISO 13485 quality management systems. The Baden-Württemberg medical technology corridor anchors Siemens Healthineers' hardware-software bundling strategies across imaging and treatment delivery portfolios.
France
Paris-based TheraPanacea leverages national R&D tax incentives and ANSM streamlined software medical device pathways to sustain algorithm development for multi-site adaptive therapy. The Gustave Roussy and Institut Curie cancer centers serve as European reference sites for real-time contour adjustment capabilities. Île-de-France concentrates grant-funded innovation contracts linking academic research to clinical production deployment.
United Kingdom
NHS England's specialized commissioning framework is evaluating AI-assisted radiotherapy planning for inclusion in standard tariff reimbursement, creating payment parity uncertainty for hospital capital allocation. The Royal Marsden and Christie NHS Foundation Trusts pilot automated contouring through NIHR-funded research translation programs. London and Manchester clusters dominate procurement authority within integrated cancer center networks.
Canada
Provincial health technology assessment agencies including CADTH and INESSS are developing evidence frameworks for algorithm-based segmentation tools prior to formulary inclusion. The Princess Margaret Cancer Centre and BC Cancer serve as multi-site evaluation hubs for cloud-hosted deployment models. Ontario and British Columbia concentrate subscription licensing adoption that eliminates upfront infrastructure barriers for mid-tier hospitals.
Automated Contouring Radiotherapy Software Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the architecture layer. The vendor base stratifies between imaging-linear accelerator conglomerates with bundled hardware-software contracts and independent software vendors with API-first interoperability architectures. Three archetypes dominate: hardware-anchored platforms, lightweight cloud-native specialists, and research-to-production converters. Consolidation pressures favor M&A activity targeting regulatory affairs infrastructure and algorithmic training datasets.
Among independent software specialists, TheraPanacea, Limbus AI, and Radformation exemplify the lightweight deployment archetype that reduces IT integration friction for outpatient clinic and mid-tier hospital segments. Siemens Healthineers and GE HealthCare occupy platform-integrator positions where hardware-software bundling across imaging and linear accelerator portfolios creates competitive moats. Brainlab and MVision AI sit within the research-to-production conversion tier, leveraging academic medical center reference sites to establish clinical validation credentials for regulatory pathway navigation.
| Leading Market Players |
|---|
| TheraPanacea |
| Limbus AI |
| Synaptiq |
| Spectronic Medical |
| GE HealthCare |
| Radformation |
| Siemens Healthineers |
| Brainlab |
| MVision AI |
| Others |
Value Chain & Pricing Dynamics
The Trans-Atlantic data corridor carries algorithm training datasets and cloud deployment infrastructure between United States and European development centers, with bandwidth costs and latency requirements concentrating supply in Frankfurt and Ashburn nodes while pushing price differentiation between real-time adaptive therapy modules and batch-processing contouring tools.
Pricing Analysis
The customization-premium spread separates FDA-validated neural network platforms from standard atlas-based alternatives. Subscription-based SaaS licensing dominates, with annual recurring revenue models capturing preference over perpetual licenses. Price differentiation rests on ISO 13485 certification tier and after-sales algorithm retraining intensity. Cost compression in mid-tier hospital segments is intensifying because cloud-hosted alternatives eliminate upfront infrastructure barriers. Outpatient clinics exhibit highest price sensitivity; academic medical centers with grant funding show lowest.
Supply Chain Analysis
Extended payment terms from cloud infrastructure providers and supply-chain finance facilities from GPU hardware vendors are reshaping vendor working capital requirements. Algorithm development concentrates in the United States, France, and Germany. Raw material dependencies include annotated medical imaging datasets, NVIDIA A100/H100 compute clusters, and IEC 62304-compliant software lifecycle management tools. Single-source vulnerability runs through concentrated GPU supply from Taiwan Semiconductor Manufacturing. Distribution runs through direct enterprise sales teams and radiotherapy equipment OEM bundling agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated contouring radiotherapy software functions as a service-attach opportunity where continuous algorithm retraining and regulatory compliance subscriptions expand faster than initial platform licensing, with recurring revenue multiples exceeding hardware-anchored alternatives.
For Market Incumbents: Insulate market position by deepening backward integration into proprietary imaging dataset libraries and securing exclusive hospital system partnerships that lock out API-first competitors. FDA software-as-a-medical-device validation timelines favor established quality management systems as a defensive moat. Prioritize regulatory affairs infrastructure investment over pure algorithmic performance gains. For New Entrants and Emerging Players: Establish a beachhead in Canadian and United Kingdom outpatient clinic segments where provincial health technology assessment frameworks create evaluation windows before formulary inclusion decisions. Community oncology practices previously excluded from enterprise tools represent the most penetrable white-space. Pursue lightweight cloud-native deployment architectures with minimal IT integration friction as the primary go-to-market angle. For Investors and Strategic Acquirers: EU AI Act high-risk system classification reshapes the acquisition landscape by elevating compliance infrastructure valuations above pure algorithmic capability. Long-term viability over a multi-year horizon favors vendors with demonstrated post-market surveillance systems and algorithmic change control documentation. Target acquisition archetypes include ISO 13485-certified software specialists with established European reference sites. Monitor Medicare AI-assisted planning reimbursement code finalization as the critical inflection signal for hospital capital allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Algorithmic transparency documentation unlocks United States academic medical center procurement committees. |
| CE Marking Pathway under EU MDR Class IIa/IIb | Conformity assessment obligations filter undercapitalized entrants from European hospital tenders. |
| Hospital System Partnership | Integrated delivery network contracts consolidate multi-site linear accelerator deployments into single-vendor relationships. |
| Software Companion Development | API-first architectures enable interoperability across legacy PACS and RIS systems in established cancer centers. |
| Reimbursement Strategy | Payment parity positioning determines whether automated contouring achieves standard-of-care status or remains premium add-on. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with radiation oncology department heads, biomedical informatics officers, hospital procurement committee members, and GPO contracts managers; and secondary validation against FDA 510(k) clearance databases, EU MDR notified body certificates, hospital capital expenditure disclosures, and CMS Medicare reimbursement code development records. Bottom-up segmentation modeling triangulated against top-down market sizing from equipment installation bases and software licensing trends.
Forecast inputs encompass deployment model, hospital tier, integration complexity, and regional regulatory pathway clustering across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, algorithmic technology tier, and clinical application specificity. CAGRs derived from logistic diffusion curves fitted to adoption rate data, with neural network training cost trajectories and cloud infrastructure price elasticity as industry-specific forecast inputs.
Sensitivities concentrate around FDA algorithm validation timeline extensions, EU AI Act enforcement intensity variations, and Medicare reimbursement code finalization outcomes. Forecasts reflect documented assumptions regarding clinical acceptance velocity and hospital IT modernization cycles. Macroeconomic pressure on hospital capital budgets, regulatory deviation from current pathway timelines, or breakthrough displacement by generative segmentation architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
US and Europe Digital Pathology Market
Medical Imaging
Germany Digital Pathology Market
Medical Imaging
Medical Hyperspectral Imaging Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Netherlands Diagnostic Imaging Equipment Market
Medical Imaging
Germany Magnetic Resonance Imaging Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
AI-Assisted Radiology Market