
 Germany Digital X-Ray Market | 2026-2036
Germany Digital X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Digital X-Ray Market Foresight
Buyer concentration among German hospital networks is shifting toward centralized procurement consortia, particularly the university hospital alliances in Berlin and Munich. Siemens Healthineers anchors its domestic position through deep vertical integration in detector manufacturing. Philips competes via specialized cardiac and interventional imaging portfolios tailored to German cath lab standards. Fujifilm leverages its portable digital x-ray line to serve the expanding diagnostic center segment in secondary cities.
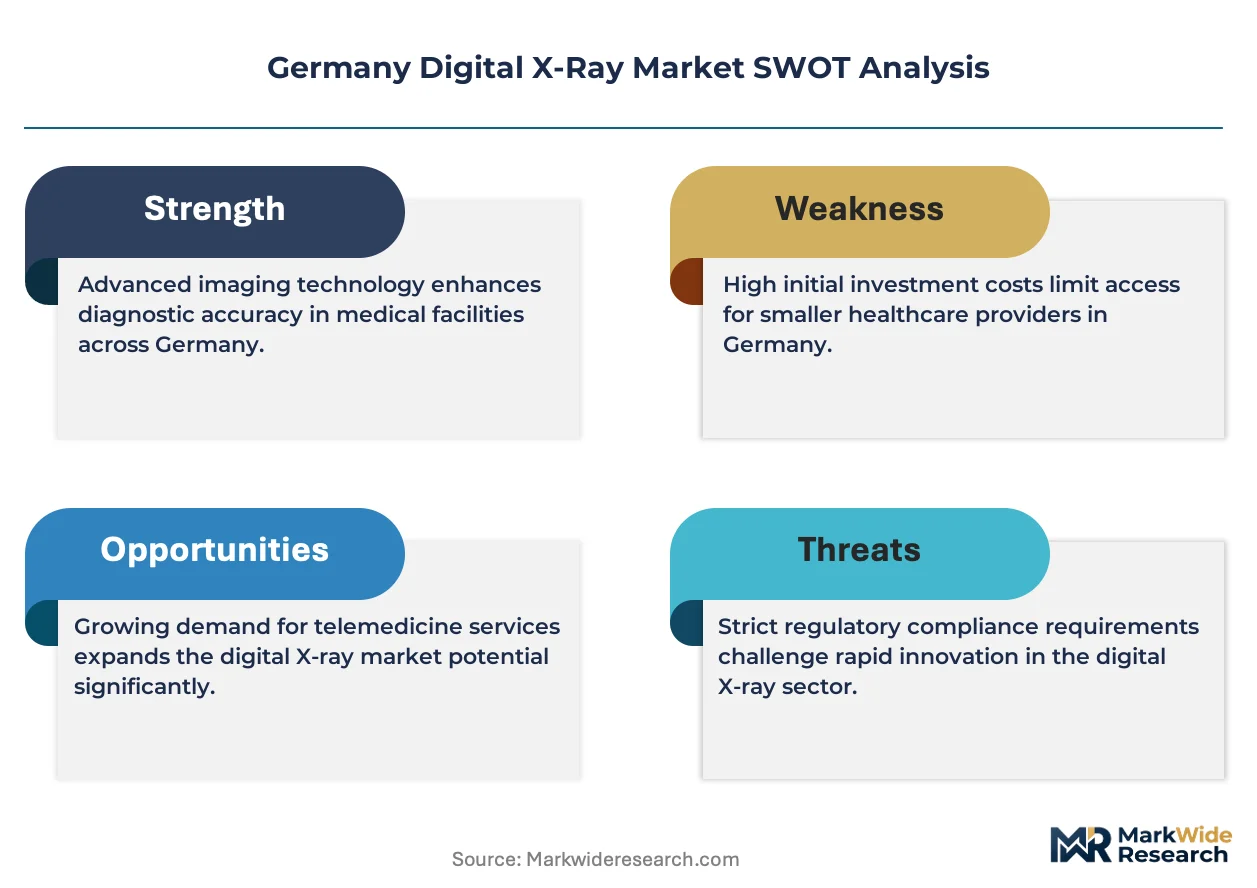
Germany digital x-ray equipment encompasses radiographic systems that convert x-ray photons into digital images via flat-panel detectors or computed radiography plates, typically operating at 40–150 kVp tube voltage for diagnostic clarity. These systems eliminate chemical processing, enabling immediate image distribution through hospital PACS infrastructure for trauma, pulmonary, and skeletal assessment. Digital radiography systems dominate installed base value due to higher throughput and lower per-exam operational cost, while portable digital x-ray units represent the fastest-expanding product category as point-of-care imaging extends into emergency departments and surgical suites. Flat panel detector technology leads technology segment margins, displacing phosphor plate systems in premium hospital installations.
Germany's Federal Institute for Drugs and Medical Devices enforces MDR compliance timelines that accelerate replacement of pre-2017 legacy equipment, while DIN standards for image quality and radiation dose shape product certification requirements. The country's statutory health insurance framework, governed by the Federal Joint Committee, influences reimbursement rates for outpatient radiography and thereby conditions capital investment cycles for imaging clinics. Stakeholders must monitor how the EU AI Act classification rules affect software-integrated x-ray systems with embedded diagnostic algorithms.
Market Dynamics
MDR compliance deadlines are compressing replacement timelines for legacy analog systems while Bavarian and North Rhine-Westphalian hospital networks consolidate procurement authority into centralized purchasing consortia.
Growth Catalysts
- MDR Implementation:Germany's Medical Device Regulation mandates accelerate retirement of pre-2017 equipment, forcing capital deployment toward certified digital systems.
- University Hospital Upgrades:Berlin and Munich academic medical centers are standardizing on flat-panel detector architectures to support high-throughput trauma and interventional workflows.
- Point-of-Care Expansion:Emergency departments and surgical suites across secondary cities are adopting portable digital x-ray units for intraoperative and bedside imaging.
Market Restraints
- Detector Supply Concentration:Flat-panel sensor production concentrates among Asian component suppliers, exposing German OEMs to single-source risk for amorphous silicon substrates.
- Capital Intensity:Full-room digital radiography installations require substantial infrastructure investment in PACS integration and shielding retrofit.
- Computed Radiography Persistence:Phosphor plate systems retain installed base share in rural diagnostic centers where utilization rates cannot justify DR capital outlay.
Strategic Opportunities
- AI-Integrated Diagnostics:Embedded algorithms for fracture detection and pulmonary nodule identification create software differentiation as EU AI Act classification rules clarify.
- Diagnostic Center Networks:Secondary cities like Dresden and Leipzig present whitespace for outpatient imaging chains seeking DR efficiency advantages over hospital-based competitors.
- Service Unbundling:Independent service organizations can capture maintenance revenue from multi-vendor hospital fleets as manufacturer service contracts expire.
Industry Challenges
- MDR Certification Timelines:Technical documentation requirements and notified body backlogs extend product registration cycles, delaying new system introductions.
- Legacy PACS Integration:Heterogeneous hospital IT environments complicate seamless image routing between new digital x-ray systems and existing archive infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Digital X-Ray Market |
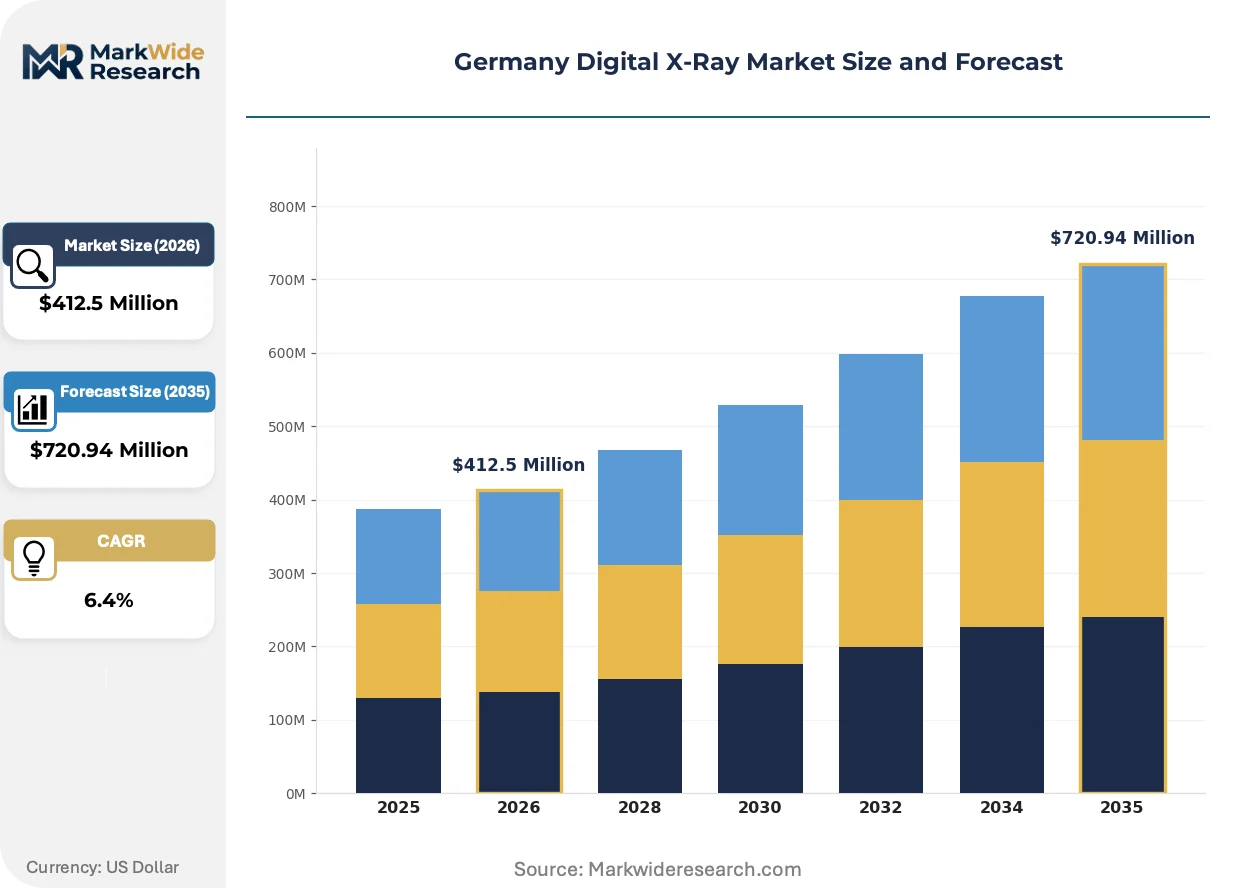
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Digital X-Ray, Fixed Digital X-Ray, Mobile Digital X-Ray, Computed Radiography Systems, Digital Radiography Systems Technology: Direct Radiography, Computed Radiography, Flat Panel Detectors, Phosphor Plate Technology, CCD Sensors Application: Orthopedics, Dental Imaging, Chest Radiography, Mammography, Emergency Imaging End User: Hospitals, Diagnostic Centers, Imaging Clinics, Surgical Centers, Academic & Research Institutes |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Koninklijke Philips N.V., Fujifilm Holdings Corporation, Canon Medical Systems Corporation, Carestream Health, Agfa-Gevaert Group, Shimadzu Corporation, Mindray Medical International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Digital X-Ray Market Shifts & Advancements
Software-hardware convergence is redefining competitive differentiation as embedded AI and cloud connectivity transform digital x-ray from standalone imaging hardware into integrated diagnostic nodes.
Dual-energy subtraction imaging is unifying anatomical visualization with tissue characterization in a single exposure. University hospital radiology departments in Heidelberg and Hamburg are deploying these systems for chest and abdominal protocols. The technology is unifying previously separate CT follow-up procedures into initial x-ray workflows, compressing diagnostic timelines and equipment utilization patterns.
EU AI Act risk classification rules are reshaping software development roadmaps for German OEMs. Systems with embedded diagnostic algorithms now face conformity assessment procedures that extend validation requirements. Cardiac and interventional imaging portfolios face the steepest compliance burden as class IIa and IIb designations trigger third-party oversight.
Hospital procurement consortia are consolidating vendor relationships across multi-site networks. The University Hospital Alliance in Berlin and similar structures in Munich are replacing decentralized department-level purchasing with centralized equipment standardization. Bavarian hospital networks demonstrate the most advanced consolidation, negotiating enterprise-wide service agreements that bundle digital x-ray with MRI and CT fleets.
Germany Digital X-Ray Market Segmentation
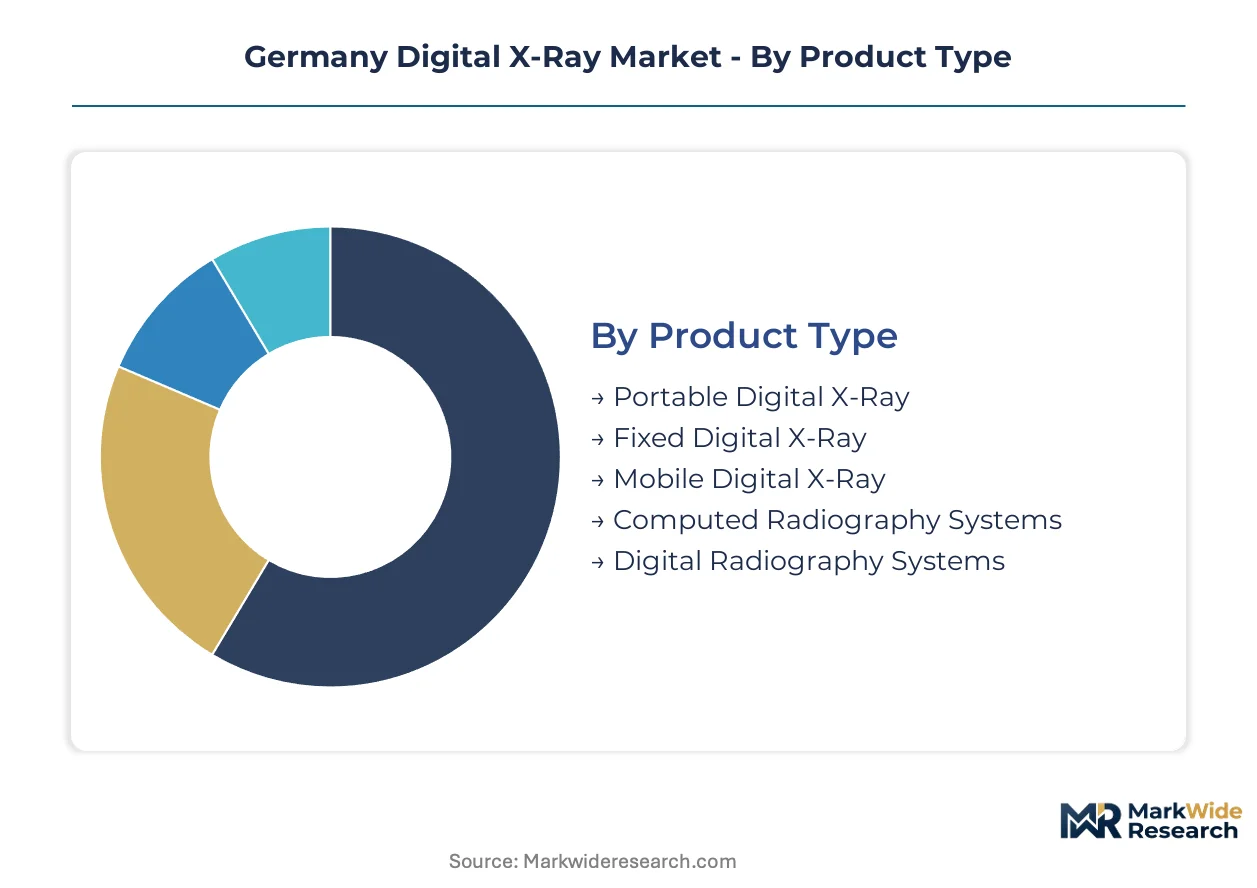
Segmentation in the Germany Digital X-Ray Market reveals how MDR certification burdens and procurement consolidation reshape competitive dynamics across equipment categories. Each dimension carries distinct regulatory weight and capital intensity profiles that determine vendor positioning.
Product Type:
MDR compliance timelines vary sharply across product categories, with portable and mobile systems facing accelerated notified body review due to their software-integrated diagnostic capabilities.
- Portable Digital X-Ray:Battery-powered units with wireless flat-panel detectors enable bedside and intraoperative imaging. Demand concentrates in Bavarian emergency departments upgrading trauma workflows. MDR Class IIa designation triggers extended validation for embedded image processing algorithms.
- Fixed Digital X-Ray:Ceiling-suspended or floor-mounted systems with automated positioning dominate high-throughput radiology departments. University hospital networks in Berlin and Munich standardize on these architectures for skeletal and chest protocols. Full-room installations require substantial PACS integration investment.
- Mobile Digital X-Ray:Motorized units with extended battery range serve ICU and surgical suite environments. North Rhine-Westphalian hospital consortia favor these for multi-department fleet standardization.
- Computed Radiography Systems:Phosphor plate-based digitization persists in rural diagnostic centers where utilization rates cannot justify DR capital outlay. Lower acquisition cost offsets slower workflow.
- Digital Radiography Systems:Direct-capture flat-panel architectures eliminate chemical processing. These systems anchor premium hospital installations with immediate image distribution capability.
Fixed Digital X-Ray sits at the top of the volume ranking, with Portable Digital X-Ray climbing the fastest.
Technology:
Cost tiers stratify sharply across detector architectures, with flat-panel systems commanding premium positioning against phosphor plate alternatives.
- Direct Radiography:Amorphous selenium or silicon detectors convert x-ray photons directly to electrical signal. Bavarian university hospitals deploy these for highest-resolution skeletal imaging. Supply concentration among Asian substrate suppliers creates single-source vulnerability.
- Computed Radiography:Photostimulable phosphor plates require laser scanning digitization. Secondary city diagnostic centers retain these for cost-constrained replacement cycles.
- Flat Panel Detectors:Thin-film transistor arrays on glass substrates enable large-area digital capture. Heidelberg and Hamburg academic centers lead adoption for dual-energy subtraction protocols.
- Phosphor Plate Technology:Barium fluorohalide crystals store latent images for subsequent laser readout. Rural imaging clinics maintain installed base where DR throughput advantages remain unexploited.
- CCD Sensors:Charge-coupled device cameras capture scintillator output in specialized dental and small-field applications. Niche positioning limits volume expansion.
Flat Panel Detectors command the highest margin tier, with Direct Radiography gaining share fastest among new installations.
Application:
Customer type determines workflow integration requirements, with orthopedics and emergency imaging driving distinct equipment specifications.
- Orthopedics:Weight-bearing and trauma protocols demand high-resolution skeletal visualization with automated stitching. Munich university hospital networks prioritize these capabilities for sports medicine centers.
- Dental Imaging:Intraoral and panoramic systems with specialized sensors address maxillofacial assessment. Lower kVp requirements differentiate certification pathways.
- Chest Radiography:High-throughput pulmonary screening requires rapid image acquisition and PACS distribution. Berlin hospital consortia standardize on dual-energy subtraction for nodule characterization.
- Mammography:Low-dose, high-contrast imaging with specialized compression and biopsy guidance. Separate MDR classification applies to screening versus diagnostic configurations.
- Emergency Imaging:Trauma and bedside protocols prioritize speed and portability. Bavarian emergency departments drive portable unit adoption for resuscitation bay integration.
Chest Radiography anchors installed base volume, with Emergency Imaging expanding most quickly as point-of-care protocols proliferate.
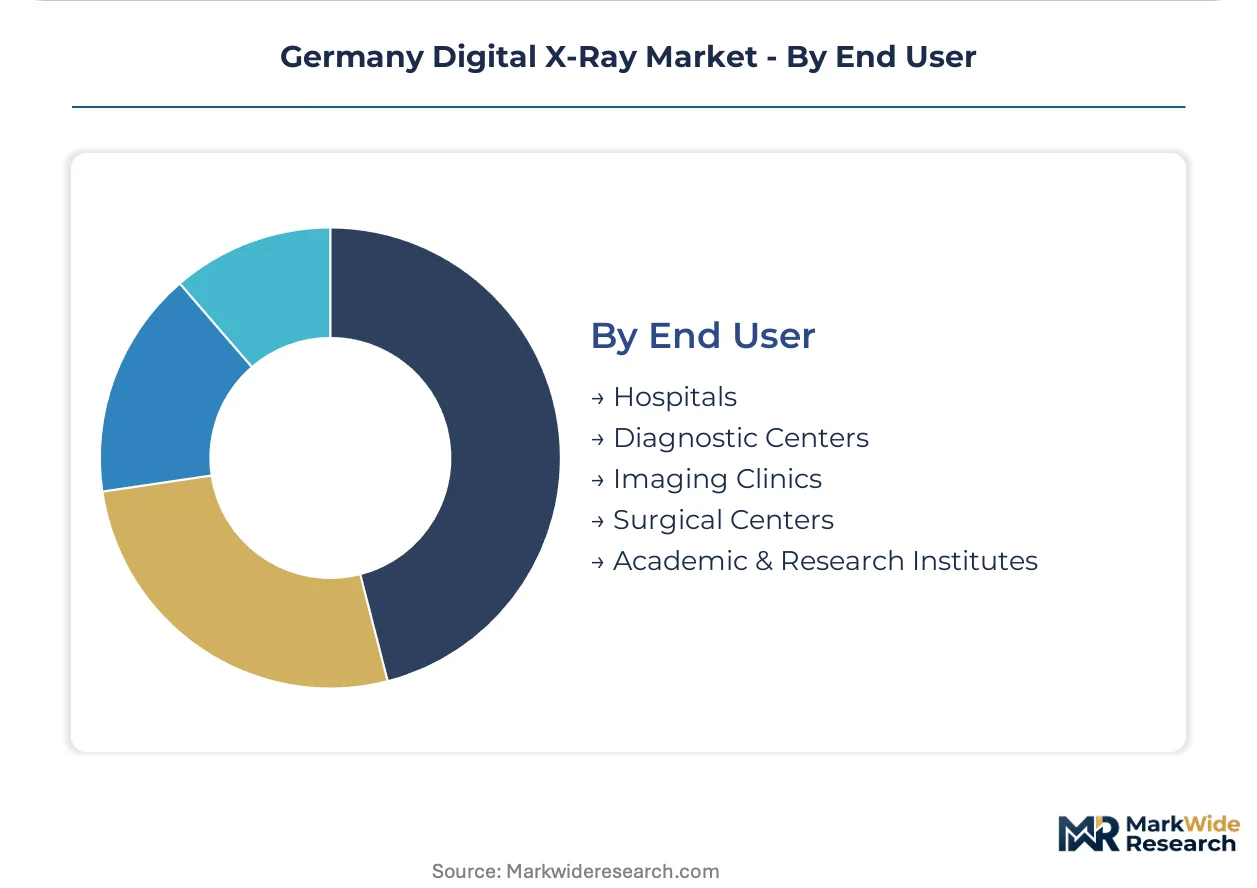
End User:
Procurement authority concentration varies across institutional types, with hospital networks consolidating purchasing power against fragmented diagnostic center ownership.
- Hospitals:Multi-department imaging infrastructure with enterprise PACS integration. North Rhine-Westphalian and Bavarian consortia negotiate fleet-wide service agreements bundling digital x-ray with CT and MRI.
- Diagnostic Centers:Outpatient-focused operations with high utilization targets. Dresden and Leipzig present whitespace for chain expansion seeking DR efficiency advantages.
- Imaging Clinics:Specialist-owned facilities with procedure-specific equipment configurations. Computed radiography persistence is highest in this segment.
- Surgical Centers:Ambulatory facilities with intraoperative imaging requirements. Mobile unit adoption concentrates here for orthopedic and spine procedures.
- Academic & Research Institutes:University hospitals in Berlin, Munich, Heidelberg, and Hamburg drive technology validation and protocol development. These institutions anchor demand for advanced detector architectures and AI-integrated diagnostics.
Hospitals dominate procurement volume, with Diagnostic Centers climbing fastest as outpatient imaging chains consolidate secondary city markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands a denser installed base of digital radiography systems than France, yet both markets face parallel MDR compliance deadlines that compress replacement cycles for legacy analog equipment.
Bavaria
Munich and Nuremberg anchor Germany's most advanced hospital procurement consortium, where university medical centers standardize on flat-panel detector architectures for high-throughput trauma workflows. The Federal Institute for Drugs and Medical Devices enforces MDR certification timelines that accelerate retirement of pre-2017 equipment. Erlangen's medical technology cluster concentrates detector manufacturing capabilities through Siemens Healthineers' captive production facilities.
North Rhine-Westphalia
Cologne and Düsseldorf hospital networks consolidate purchasing authority into centralized consortia that negotiate enterprise-wide service agreements bundling digital x-ray with MRI and CT fleets. DIN standards for image quality and radiation dose shape product certification requirements across outpatient imaging clinics. The Ruhr region's diagnostic center chains drive portable digital x-ray adoption for point-of-care expansion into emergency departments.
Baden-Württemberg
Heidelberg and Stuttgart academic medical centers validate dual-energy subtraction protocols that unify anatomical visualization with tissue characterization. The Federal Joint Committee's reimbursement framework conditions capital investment cycles for imaging clinics in Mannheim and Karlsruhe. Freiburg's university hospital anchors demand for AI-integrated diagnostics with embedded fracture detection algorithms.
Berlin-Brandenburg
The University Hospital Alliance in Berlin replaces decentralized department-level purchasing with centralized equipment standardization across Charité and affiliated sites. EU AI Act classification rules reshape software development roadmaps for embedded diagnostic algorithms in chest radiography systems. Potsdam's expanding diagnostic center network presents whitespace for outpatient imaging chains seeking DR efficiency advantages.
Hamburg
University Medical Center Hamburg-Eppendorf leads adoption of advanced detector architectures for pulmonary nodule identification protocols. The statutory health insurance framework governs reimbursement rates for outpatient radiography across Schleswig-Holstein border clinics. Lübeck's medical technology corridor concentrates service unbundling opportunities as manufacturer maintenance contracts expire across multi-vendor hospital fleets.
Germany Digital X-Ray Market Competitive Landscape
German producers anchor the premium-tier detector manufacturing segment; Japanese and Dutch specialists hold positions in portable and interventional imaging portfolios. The vendor base stratifies across three tiers: integrated conglomerates with captive detector production, mid-scale imaging specialists with software-differentiated offerings, and regional service organizations capturing maintenance revenue from expiring OEM contracts. Dominant competitive moves include backward integration into amorphous silicon substrate supply and strategic partnerships for AI algorithm licensing.
Within the integrated conglomerate tier, Siemens Healthineers AG exemplifies vertical control through in-house detector manufacturing. Koninklijke Philips N.V. occupies a position representing software-hardware convergence in cardiac and interventional imaging. Fujifilm Holdings Corporation anchors the portable digital x-ray segment serving secondary city diagnostic centers. These three entities represent distinct strategic archetypes: captive supply chain control, specialized clinical workflow optimization, and point-of-care mobility expansion.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Fujifilm Holdings Corporation |
| Canon Medical Systems Corporation |
| Carestream Health |
| Agfa-Gevaert Group |
| Shimadzu Corporation |
| Mindray Medical International |
| Others |
Supply & Pricing Matrix
Captive amorphous silicon substrate production anchors Siemens Healthineers' cost position and pricing power across German university hospital networks. This backward integration into detector manufacturing insulates premium-tier flat-panel systems from Asian component volatility while forcing competitors to absorb margin compression or cede share.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for standard-tier flat-panel detectors, compressing margins for non-integrated OEMs. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified university hospital systems from cost-constrained rural diagnostic centers. Pricing pressure stems from computed radiography persistence in secondary cities where utilization rates cannot justify DR capital outlay. Imaging clinics exhibit highest price sensitivity; academic medical centers prioritize throughput and AI integration over acquisition cost.
Supply Chain Analysis
MDR certification timelines gate component qualification, extending validation cycles for amorphous silicon substrates sourced from Japan, South Korea, and Taiwan. German OEMs draw from concentrated Asian suppliers for thin-film transistor arrays, barium fluorohalide phosphor crystals, and selenium deposition equipment. Single-source vulnerability concentrates in amorphous silicon glass substrate production. Distribution runs through hospital procurement consortia in Bavaria and North Rhine-Westphalia that negotiate enterprise-wide fleet agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in German digital x-ray hinges on MDR-driven replacement premiums and service revenue capture as manufacturer contracts expire across multi-vendor hospital fleets.
For Market Incumbents: Lock in detector supply security through long-term substrate agreements with Japanese and Taiwanese suppliers before notified body backlogs worsen. Accelerate AI-integrated diagnostic software roadmaps to capture EU AI Act Class IIa compliance premiums. Defend against portable specialist encroachment by bundling fixed-room DR with mobile fleet standardization across Bavarian consortia. For New Entrants and Emerging Players: Launch via independent service organization models targeting expired OEM maintenance contracts in Hamburg and Lübeck medical corridors. White-space concentrates in Dresden and Leipzig diagnostic center networks seeking DR efficiency advantages over hospital-based competitors. Secondary city outpatient imaging chains present the most penetrable end-user segment for cost-optimized portable units. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR certification burdens outstrip mid-scale imaging specialists' technical documentation capabilities. Five-to-ten year viability favors vendors with captive detector production or software-differentiated cardiac portfolios. Target acquisition archetype: regional service organizations with multi-vendor hospital relationships. Signal to watch: notified body backlog resolution timelines affecting new system introduction rates.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Fast-Track | Accelerates market access ahead of competitors facing notified body delays. |
| AI Algorithm Licensing Partnership | Embeds diagnostic differentiation into flat-panel systems for Berlin university networks. |
| Detector Supply Agreement | Secures amorphous silicon substrate allocation from South Korean suppliers. |
| Service Contract Unbundling | Captures maintenance revenue from expiring OEM agreements across North Rhine-Westphalian fleets. |
| Diagnostic Center Chain Partnership | Positions portable DR units for Dresden and Leipzig outpatient expansion. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down detector production tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists at German notified bodies combined with secondary validation from BfArM device registrations, DIN standards documentation, Federal Joint Committee reimbursement schedules, and university hospital capital expenditure disclosures. Cross-referencing bottom-up equipment placement data against top-down OEM revenue segmentation ensures triangulation integrity.
Input-output matrices map flat-panel detector shipments to end-user installations across product type, technology architecture, clinical application, and institutional category over the projection horizon. CAGRs derive from logistic adoption curves fitted to MDR compliance deadline schedules and replacement cycle acceleration patterns. Forecast inputs incorporate PACS integration cost trajectories, AI Act classification pathway timelines, and procurement consortium formation rates by federal state.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body capacity constraints or phosphor plate technology persistence in rural markets. Model assumptions reflect documented MDR implementation schedules, statutory health insurance reimbursement stability, and Asian substrate supply continuity. A model refresh is warranted upon material change in EU AI Act enforcement timelines or hospital procurement consortium consolidation rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market
Medical Imaging
UK Imaging Services Market
Medical Imaging
Global Medical Cameras Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
Mexico Diagnostic Imaging Equipment Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Digital Telepathology Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Americas Interventional Radiology Market
Medical Imaging
Dental Imaging Market
Medical Imaging
India Magnetic Resonance Imaging Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market